
 Global Chloroform Market | 2026-2036
Global Chloroform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chloroform Market Foresight
The EU Green Deal's chemical sustainability targets is realigning chloroform procurement across European pharmaceutical supply chains. Olin Corporation leverages its integrated chlor-alkali platform to sustain cost-advantaged feedstock access in North America. Solvay SA anchors its European position through specialized pharmaceutical-grade purification capabilities. Dow Inc. competes on bulk industrial-grade volumes serving chemical intermediate buyers.
Chloroform (trichloromethane, CHCl₃) is a dense, nonflammable liquid with a boiling point of 61.2°C, historically produced via the haloform reaction of acetone with sodium hypochlorite and now predominantly manufactured through methane chlorination or chlorination of methyl chloride. Its primary industrial purpose centers on solvent extraction of alkaloids, lipids, and pharmaceutical intermediates where selective organic solubility proves critical. Pharmaceutical-grade chloroform dominates value pools due to stringent purity requirements and regulatory documentation burdens, while industrial-grade volumes anchor overall tonnage in chemical intermediate applications. Laboratory reagent demand sustains premium pricing through small-batch certification and distributor markups.
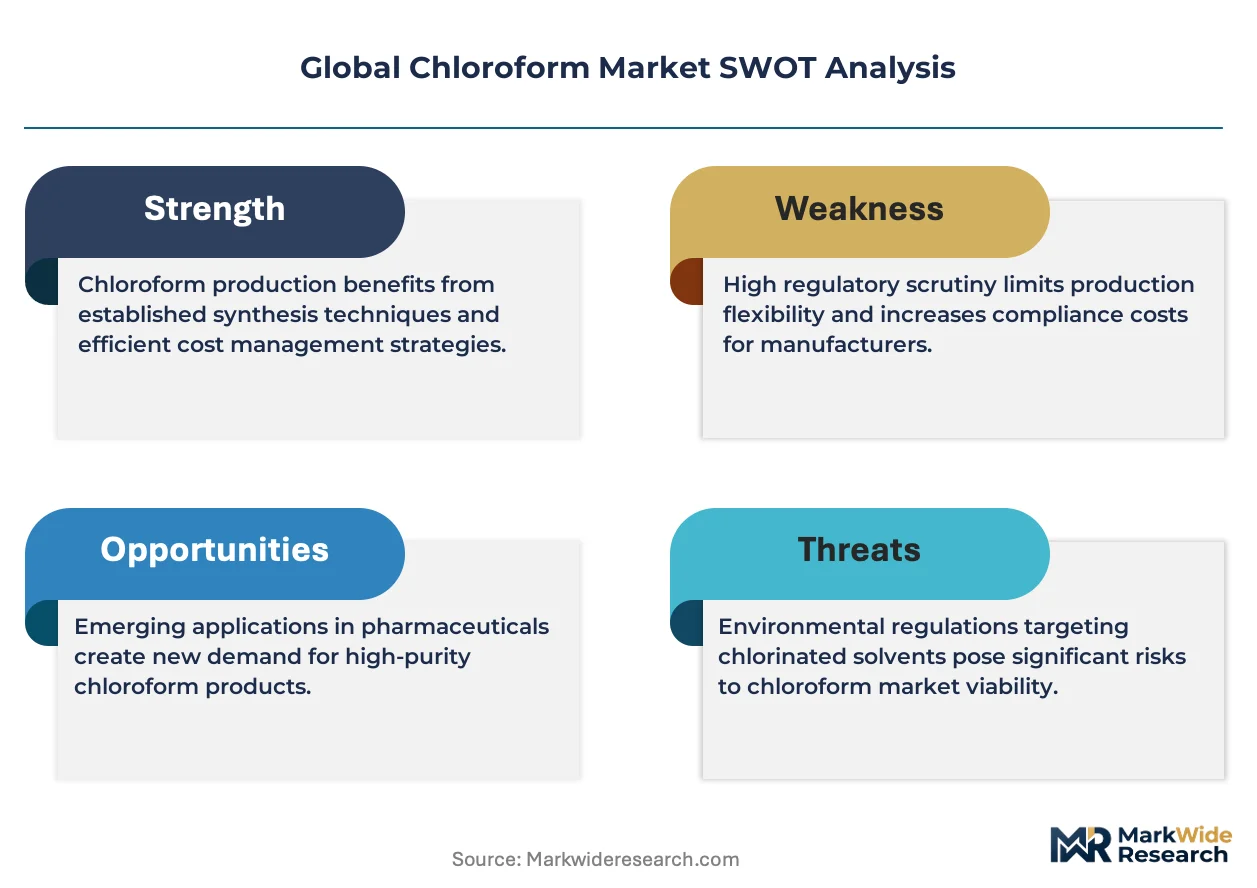
The EPA regulates chloroform under the Clean Air Act as a hazardous air pollutant, while REACH imposes authorization requirements on chlorinated solvent uses within the European Economic Area. China's MEE enforces GB standards limiting volatile organic compound emissions from chloroform production facilities, constraining capacity expansion in the Yangtze River Delta. India's Central Pollution Control Board monitors chloroform discharge under the Water Act, affecting chemical processing units in Gujarat and Maharashtra. Stakeholders must monitor evolving solvent substitution mandates and bio-based extraction alternatives that could displace conventional chloroform demand in pharmaceutical manufacturing.
Market Dynamics
Pharmaceutical-grade solvent demand is concentrating procurement power among alkaloid extractors in India and China, while REACH authorization requirements and China's GB emission standards simultaneously compress industrial-grade capacity expansion across the Yangtze River Delta and Gujarat.
Growth Catalysts
- Active pharmaceutical ingredient synthesis:Indian and Chinese pharmaceutical manufacturers are expanding solvent extraction capacity for alkaloid and lipid purification, pulling chloroform volumes into East Asian chemical processing clusters.
- EU Green Deal chemical sustainability targets:European pharmaceutical supply chains are realigning procurement toward documented low-emission solvent sources, creating premium-grade demand segmentation.
- Methane chlorination process efficiency:Integrated chlor-alkali platforms are reducing feedstock cost volatility for producers with captive chlorine supply, sustaining margin structures in North American production bases.
Market Restraints
- Chlorine feedstock cost volatility:Natural gas and electricity price swings directly impact methane chlorination economics, squeezing margins for non-integrated producers.
- REACH authorization friction:ECHA's sunset date requirements for chlorinated solvents in non-pharmaceutical applications are structurally shrinking addressable industrial-grade demand within the European Economic Area.
- Bio-based extraction substitution:Supercritical CO₂ and ionic liquid alternatives are capturing share in botanical extraction applications where regulatory pressure meets sustainability procurement mandates.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing corridor:Greenfield API facilities in the Red River Delta lack established solvent supply relationships, creating first-mover positioning for certified pharmaceutical-grade suppliers.
- Specialized reagent distribution channels:Laboratory certification and small-batch documentation capabilities are enabling premium pricing capture through distributor partnerships serving analytical chemistry end-users.
- China dual carbon policy alignment:MEE emissions trading schemes and carbon intensity benchmarks are rewarding chloroform producers with closed-loop recovery systems and thermal oxidizer integration.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA documentation requirements for residual solvent specifications extend qualification cycles by 18-24 months for new supply sources.
- Skilled process safety engineering:Chlorinated solvent handling expertise is concentrating at legacy production sites, constraining workforce availability for capacity expansion projects.
- Legacy equipment reconfiguration:Existing methyl chloride chlorination assets require significant capex for GB standard-compliant emission controls and vapor recovery system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chloroform Market |
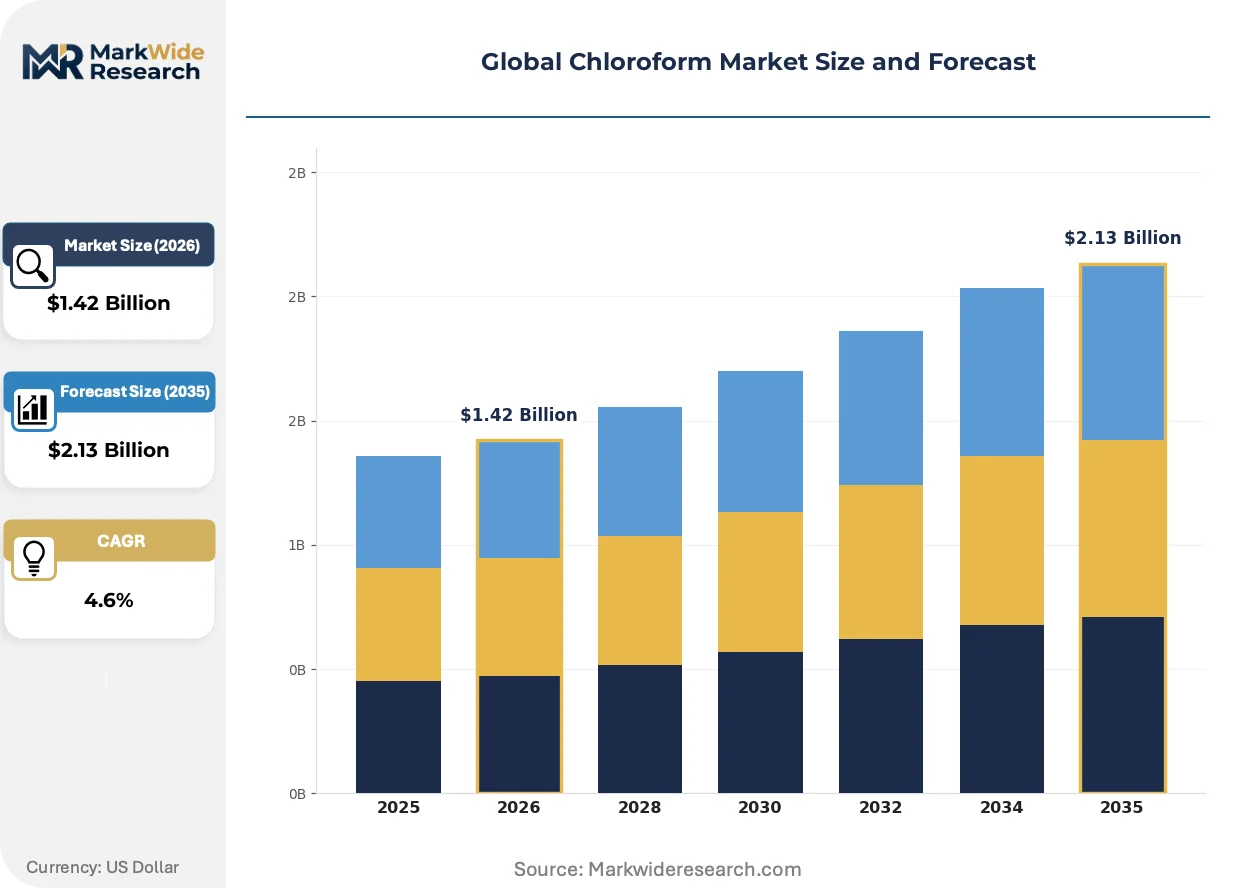
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Industrial Grade, Pharmaceutical Grade, Analytical Grade Application: Solvent Extraction, Anesthetics Manufacture, Laboratory Reagent, Chemical Intermediate End User: Pharmaceutical Manufacturers, Chemical Processing Units, Research Laboratories, Cosmetic Producers Packaging Type: Drums, ISO Tanks, Bottles, Bulk Containers |
| Companies Covered | Olin Corporation, Shin-Etsu Chemical Co., Ltd., Solvay SA, Dow Inc., Tokuyama Corporation, Arihant Chemicals, Sankyo Chemical Co., Ltd., Juhua Co., Ltd., Luxi Chemical Group Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chloroform Market Shifts & Advancements
Integrated chlor-alkali production platforms are reshaping competitive economics by collapsing feedstock cost structures, while regulatory documentation requirements are fragmenting demand into certified pharmaceutical-grade and commoditized industrial-grade tiers.
Membrane cell chlor-alkali technology is consolidating cost advantages for chloroform producers with backward integration into chlorine and caustic soda production. Indian and Chinese pharmaceutical API manufacturers are prioritizing supply contracts with integrated producers to secure volume commitments and price stability. This technology is consolidating procurement leverage around Shanghai and Gujarat production clusters where captive chlorine supply eliminates merchant market exposure.
REACH authorization sunset clauses are compressing industrial-grade chloroform demand timelines across European chemical intermediate applications. ECHA's 2025-2027 review schedule for chlorinated solvents is forcing downstream users to submit substitution plans or secure time-limited derogations. Pharmaceutical-grade applications retain authorization priority, redirecting European producer volumes toward documented reagent and extraction solvent certifications.
Long-term offtake contracting is displacing spot market transactions among alkaloid extractors and pharmaceutical intermediates buyers. Indian API manufacturers are negotiating 3-5 year supply agreements with fixed-volume, indexed-price structures to secure regulatory documentation continuity. This behavioral shift is most visible in Gujarat's specialty chemical corridor, where contract coverage now exceeds 60% of pharmaceutical-grade chloroform consumption.
Global Chloroform Market Segmentation
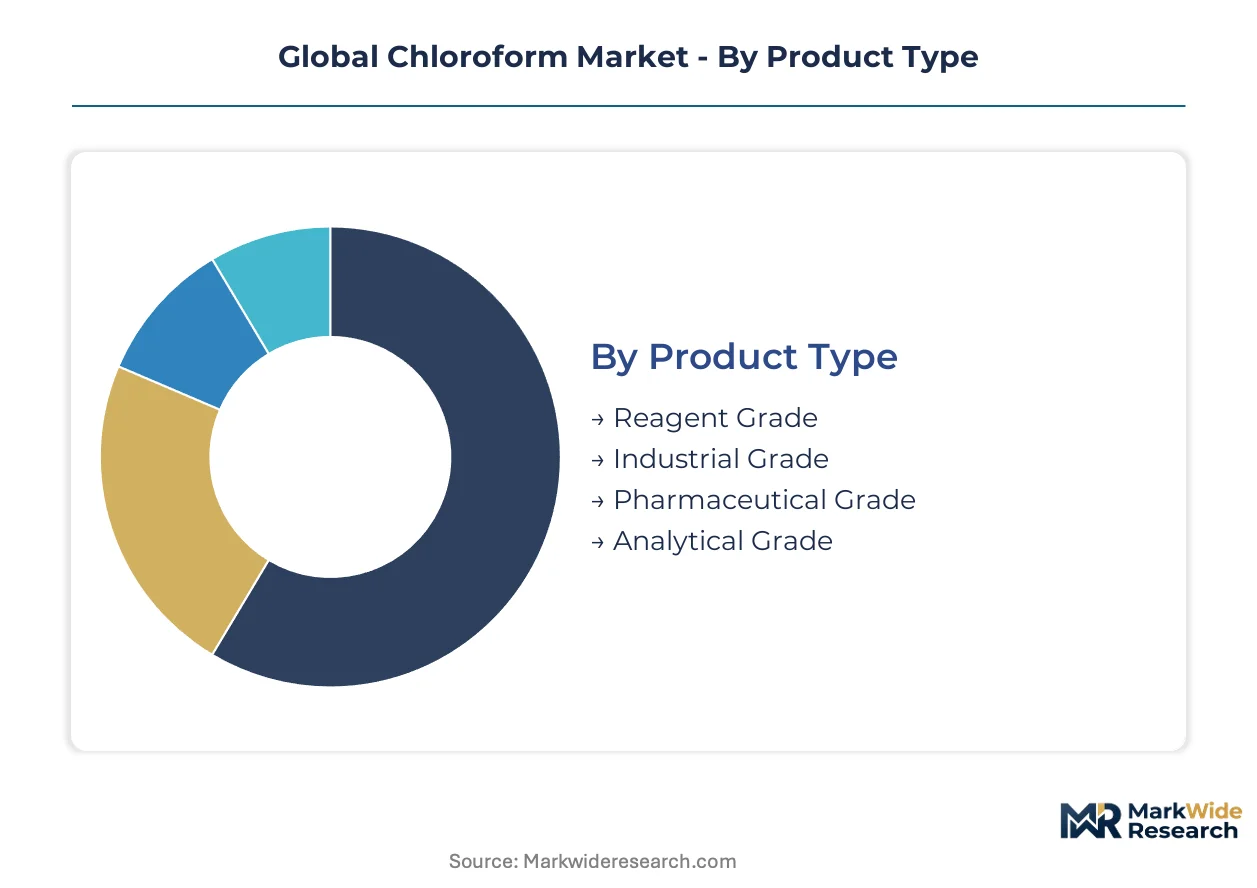
Chloroform demand fragments sharply across purity tiers and use cases. Pharmaceutical-grade specifications command documentation burdens that industrial buyers bypass entirely. Packaging and logistics configurations further stratify procurement economics between bulk chemical processors and precision laboratory end-users.
Product Type:
Standalone purification systems dominate high-value applications, while embedded feedstock supply serves commodity chemical synthesis.
- Pharmaceutical Grade:Stringent residual solvent specifications under FDA and EMA guidelines require batch-level certification and 18-24 month qualification cycles. Indian API manufacturers in Gujarat and Maharashtra concentrate procurement here, prioritizing supply contracts with integrated chlor-alkali producers to secure documentation continuity.
- Industrial Grade:Standard purity levels serve chemical intermediate manufacturing where cost minimization outweighs certification requirements. REACH authorization sunset clauses are compressing European demand timelines, redirecting volumes toward Asian chemical processing clusters.
- Reagent Grade:Laboratory-scale purification with documented traceability for analytical chemistry applications.
- Analytical Grade:Ultra-high purity specifications for chromatography and spectroscopy methods requiring minimal background interference.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tiers separate extraction solvents from specialty chemical inputs, with laboratory precision commanding premium multiples over bulk processing.
- Solvent Extraction:Selective organic solubility enables alkaloid and lipid purification for active pharmaceutical ingredient synthesis. Chinese and Indian pharmaceutical manufacturers are expanding capacity in the Yangtze River Delta and Gujarat specialty chemical corridors, pulling chloroform volumes into concentrated procurement relationships.
- Chemical Intermediate:Feedstock for fluorocarbon and refrigerant precursor manufacturing with high-volume, price-sensitive demand characteristics.
- Anesthetics Manufacture:Declining therapeutic use limits this segment to specialized veterinary and research applications.
- Laboratory Reagent:Small-batch certification and distributor markups sustain premium pricing for analytical chemistry end-users.
Procurement scale favors Chemical Intermediate; documented purity requirements are climbing fastest in Solvent Extraction.
End User:
Customer type determines whether chloroform enters as a direct material or embedded within formulated products.
- Pharmaceutical Manufacturers:API synthesis and purification operations in India and China are negotiating 3-5 year offtake agreements with indexed-price structures to secure volume commitments.
- Chemical Processing Units:Intermediate manufacturing for downstream fluorochemical and polymer applications with merchant market price exposure.
- Research Laboratories:Academic and industrial R&D facilities requiring certified reagent-grade supply with full documentation chains.
- Cosmetic Producers:Limited solvent extraction applications for botanical ingredient processing, facing substitution pressure from bio-based alternatives.
Contract coverage is deepest among Pharmaceutical Manufacturers; spot market dependence persists for Chemical Processing Units.
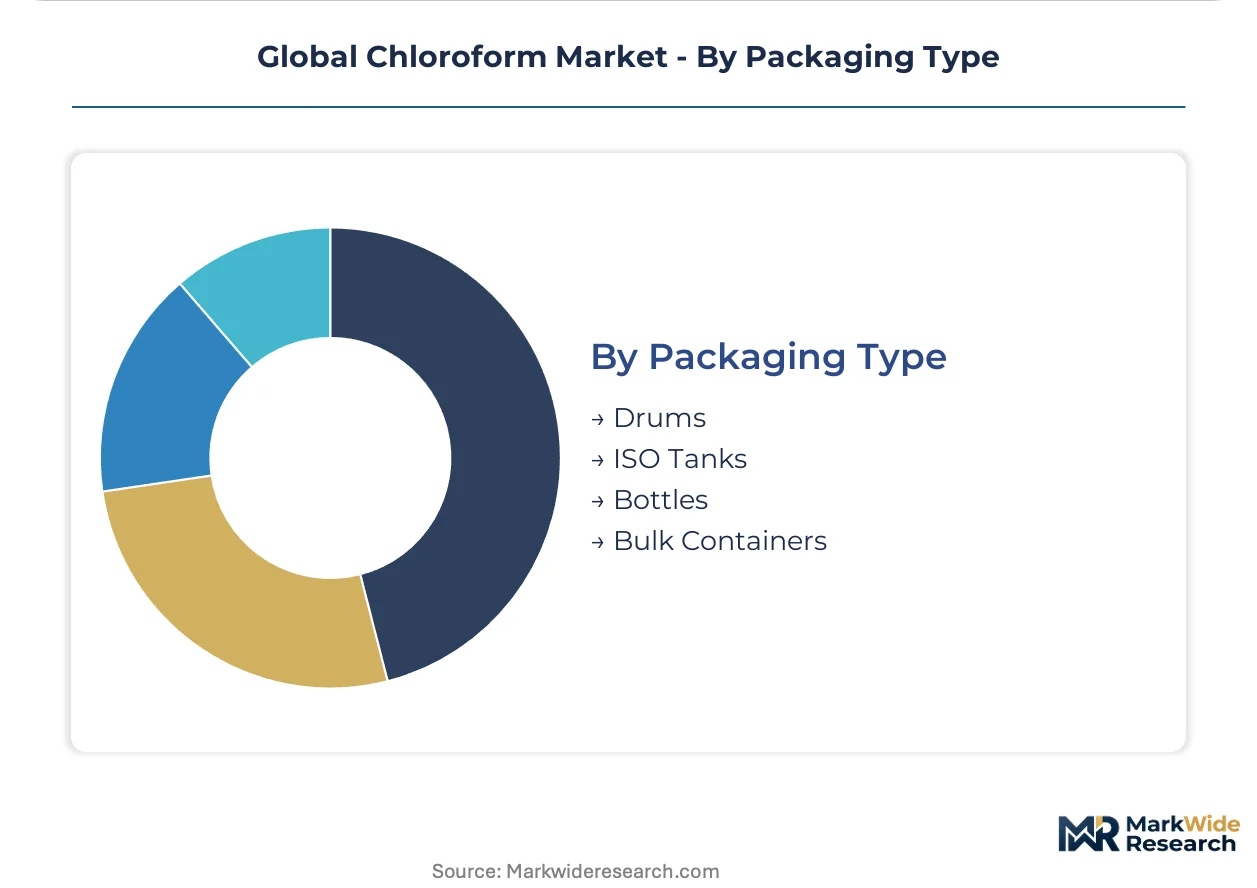
Packaging Type:
Supply concentration shapes logistics configurations, with integrated producers favoring bulk formats and distributors handling precision packaging.
- ISO Tanks:Intermodal bulk transport serving high-volume pharmaceutical and chemical processors with dedicated supply contracts.
- Drums:Standard intermediate packaging for chemical processing units with moderate throughput requirements.
- Bulk Containers:Regional distribution hubs serving clustered manufacturing facilities in Shanghai and Gujarat chemical corridors.
- Bottles:Laboratory-scale packaging with certification documentation for research and analytical end-users.
Shipment volumes cluster in ISO Tanks; specialized certification requirements are expanding fastest in Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors chloroform procurement intensity through its integrated Yangtze River Delta chemical processing corridor, where pharmaceutical-grade solvent demand concentrates among API manufacturers. Regulatory divergence across major producing jurisdictions is fragmenting capacity expansion timelines and redirecting investment toward emission-compliant production bases.
China
API synthesis expansion in Jiangsu and Zhejiang provinces is pulling chloroform volumes into concentrated procurement relationships. MEE enforces GB standards limiting VOC emissions from chloroform production facilities, constraining capacity additions in the Yangtze River Delta. Juhua Co., Ltd. and Luxi Chemical Group Co anchor supply from Zhejiang and Shandong production bases with integrated chlor-alkali platforms.
India
Alkaloid extractors in Gujarat and Maharashtra are negotiating long-term offtake agreements with indexed-price structures to secure volume commitments. The Central Pollution Control Board monitors chloroform discharge under the Water Act, affecting chemical processing units in the Ankleshwar-Vapi corridor. Ahmedabad and Vadodara specialty chemical clusters concentrate pharmaceutical-grade demand among CDSCO-regulated API manufacturers.
United States
Chemical intermediate manufacturing for fluorocarbon precursors sustains industrial-grade consumption in the Gulf Coast petrochemical corridor. EPA regulates chloroform under the Clean Air Act as a hazardous air pollutant, imposing emission control requirements on Texas and Louisiana production facilities. Olin Corporation leverages its integrated chlor-alkali platform across the Ohio River Valley to sustain cost-advantaged feedstock access.
Germany
REACH authorization sunset clauses are compressing industrial-grade demand timelines across Rhineland chemical intermediate applications. ECHA's review schedule for chlorinated solvents forces downstream users to submit substitution plans or secure time-limited derogations. BASF and Bayer legacy production sites in Ludwigshafen and Leverkusen face reconfiguration pressure for EMA-compliant pharmaceutical-grade certification.
Japan
Laboratory reagent demand sustains premium pricing through small-batch certification serving analytical chemistry end-users. METI chemical management policies impose handling requirements on chlorinated solvent distribution channels. Tokyo-Yokohama and Osaka-Kobe metropolitan clusters concentrate research institution procurement of reagent-grade supply with full documentation chains.
Global Chloroform Market Competitive Landscape
The competitive structure tilts toward integrated chlor-alkali producers with captive chlorine supply, compressing margins for merchant market-dependent operators. Three archetypes dominate: multinational chemical conglomerates with backward integration into feedstock production, regional specialty chemical producers with pharmaceutical-grade purification capabilities, and state-affiliated chemical groups with scale-driven cost positions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as producers seek emission-compliant production bases and long-term API manufacturer contracts.
Within the integrated multinational tier, Olin Corporation and Dow Inc. represent North American positions anchored by captive chlorine access. Solvay SA exemplifies the European pharmaceutical-grade specialization archetype through its purification and documentation capabilities. Shin-Etsu Chemical Co., Ltd. and Tokuyama Corporation occupy positions within the Asia-Pacific integrated producer segment, while Juhua Co., Ltd. and Luxi Chemical Group Co represent Chinese state-affiliated chemical groups with scale-driven positions in the Yangtze River Delta and Shandong Peninsula production clusters.
| Leading Market Players |
|---|
| Olin Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Solvay SA |
| Dow Inc. |
| Tokuyama Corporation |
| Arihant Chemicals |
| Sankyo Chemical Co., Ltd. |
| Juhua Co., Ltd. |
| Luxi Chemical Group Co |
| Others |
Supply & Pricing Matrix
Membrane cell chlor-alkali technology is collapsing feedstock cost structures while simultaneously concentrating procurement leverage around integrated producers in Shanghai and Gujarat. This production-method transition eliminates merchant chlorine exposure for backward-integrated operators, enabling indexed-price contracting that locks out non-integrated competitors from pharmaceutical-grade value pools.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade chloroform contracts, with Indian API manufacturers negotiating 3-5 year offtake agreements tied to alkaloid extraction throughput guarantees. Certification grade and volume scale drive price differentiation, with FDA-documented batches commanding substantial premiums over industrial-grade spot volumes. Pricing pressure stems from supercritical CO₂ substitution in botanical extraction, compressing margins in non-pharmaceutical tiers. Chemical processing units exhibit highest price sensitivity due to merchant market chlorine exposure, while laboratory reagent buyers show lowest sensitivity given small-batch certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese chlorine production, where Yangtze River Delta capacity expansion faces MEE emissions constraints. Supply concentrates in China, India, and the United States, with raw material dependencies spanning natural gas feedstock, electrolytic chlorine, and methyl chloride intermediates. Tariff exposure on chlor-alkali equipment imports threatens reconfiguration timelines for legacy assets. Distribution runs through ISO tank intermodal networks serving clustered pharmaceutical corridors, with drum and bottle formats handled by regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chloroform demand is transitioning from legacy methane chlorination toward closed-loop recovery systems as China's dual carbon policy rewards emission-compliant producers. Supercritical CO₂ and ionic liquid extraction technologies are displacing conventional solvent demand in sustainability-mandated procurement.
For Market Incumbents: Lock in long-term offtake agreements with Gujarat and Maharashtra API manufacturers before certification timelines extend qualification cycles for new entrants. Prioritize thermal oxidizer integration and vapor recovery retrofits to secure MEE compliance in Yangtze River Delta production bases. Defend against bio-based substitution by embedding solvent recovery services into pharmaceutical supply contracts. For New Entrants and Emerging Players: E-commerce distribution channels for reagent-grade chloroform offer lowest barrier-to-entry positioning, bypassing ISO tank infrastructure requirements that favor incumbents. Target Vietnam's Red River Delta pharmaceutical corridor where greenfield API facilities lack established solvent relationships. Penetrate through laboratory certification partnerships with distributor networks serving analytical chemistry end-users. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated chlor-alkali producers with captive chlorine supply and pharmaceutical-grade documentation capabilities. Five-to-ten year viability favors operators with closed-loop recovery systems and carbon intensity benchmarks aligned with China's emissions trading schemes. Watch ECHA authorization sunset clause enforcement as inflection indicator for European industrial-grade demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Olin Corporation's captive chlorine access eliminates merchant market price volatility in North America. |
| Pharmaceutical-Grade Certification Investment | Solvay SA's EMA-compliant purification capabilities command premium pricing in European API supply chains. |
| Long-term Supply Agreement | Indian alkaloid extractors in Gujarat now secure 60% contract coverage through indexed-price structures. |
| Emission Control Retrofit | MEE GB standards force Yangtze River Delta producers to reconfigure methyl chloride chlorination assets. |
| Laboratory Distribution Partnership | Tokuyama Corporation's small-batch certification channels capture premium multiples in Japan's research clusters. |
Research Methodology
Trade databases, SEC filings, and ECHA authorization registries formed the secondary backbone, cross-referenced with primary interviews involving chlor-alkali plant managers, pharmaceutical procurement leads at Indian API manufacturers, distribution channel partners in East Asian chemical corridors, and technical R&D directors at integrated producers. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across pharmaceutical-grade, industrial-grade, and reagent-grade tiers.
Bottom-up segment analysis modeled grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs derived from capacity-expansion timelines, regulatory authorization schedules, and substitution elasticity estimates for bio-based alternatives. Forecast inputs incorporated MEE emissions trading scheme participation rates and REACH sunset clause enforcement patterns.
Inputs from Chinese customs records and Indian CDSCO facility registrations were available through the study window; gaps in real-time spot pricing transparency introduce uncertainty bands around industrial-grade volume estimates. Forecasts reflect documented assumptions on chlor-alkali integration economics and pharmaceutical certification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Chloromethane Market
Solvents
Nitromethane Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Piperylene Market
Solvents
Nitroglycerin Market
Solvents
Toluene Market
Solvents
N-Hexane Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Trifluoroethanol Market
Solvents
Global Droppers Market
Solvents
Chloroacetonitrile Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Ethoxydiglycol Market