
 2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market | 2026-2036
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market Insights
Germany's Rhine-Main chemical corridor is tilting toward higher-purity amino alcohol capacity as pharmaceutical contract manufacturers expand local sourcing. BASF SE leverages its Ludwigshafen integrated site to sustain captive ethylene amine feedstock advantages. Evonik Industries AG specializes in high-specification alkylamines for life science applications, while Huntsman Corporation anchors North American supply through its Conroe, Texas amines complex.
2-(4-Aminopentyl(Ethyl)Amino)Ethanol functions as a specialty amino alcohol with a molecular structure combining a primary amine, secondary amine, and terminal hydroxyl group, synthesized through reductive amination of precursor aldehydes with ethanolamine derivatives, serving primarily as an intermediate for active pharmaceutical ingredient synthesis and surfactant formulation. Liquid formulations dominate current volume given their compatibility with continuous flow chemistry protocols, while powder grades command margin premiums in analytical standard applications. Pharmaceutical end users concentrate procurement through direct sales channels, whereas research institutions fragment purchases across online retail platforms.
REACH registration requirements in Europe and EPA Toxic Substances Control Act evaluations in the United States enforce escalating purity documentation for amino alcohol imports, effectively filtering smaller traders from regulated supply chains. FDA current Good Manufacturing Practice standards for pharmaceutical intermediates further constrain acceptable impurity profiles. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
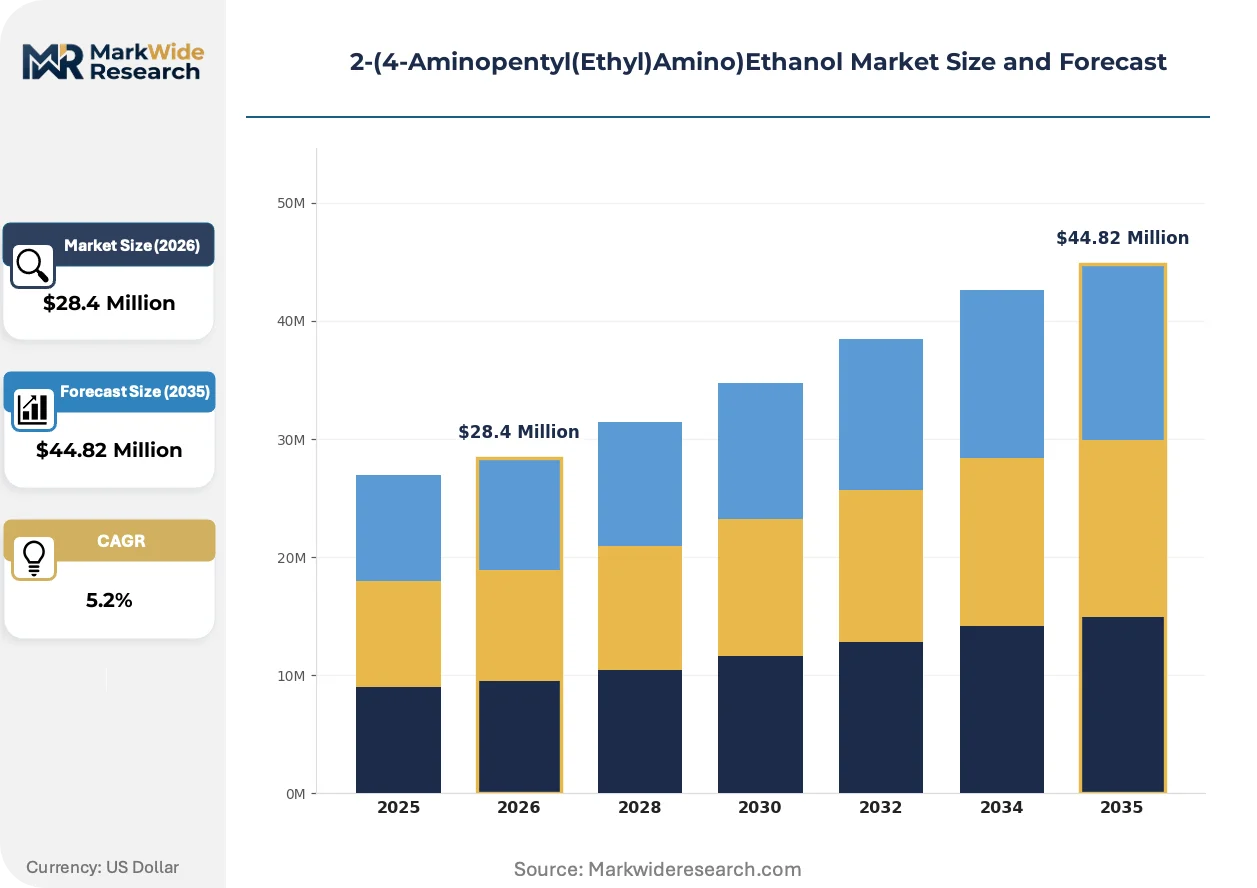
Market Dynamics
Pharmaceutical contract manufacturers are consolidating amino alcohol procurement around vertically integrated European suppliers to satisfy REACH documentation requirements while securing captive feedstock for continuous flow synthesis protocols.
Growth Catalysts
- Continuous flow chemistry:Pharmaceutical manufacturers in Germany's Rhine-Main cluster are retrofitting batch plants with flow reactors that demand liquid-phase amino alcohol inputs with precise viscosity profiles.
- REACH registration thresholds:ECHA's escalating tonnage-band data requirements for specialty amines are filtering non-compliant traders and concentrating volume among registered importers with full dossier submissions.
- Surfactant formulation demand:Personal care compounders in the United States are expanding alkylamino alcohol portfolios for mild surfactant systems targeting sulfate-free cleansing applications.
Market Restraints
- Ethylene amine feedstock volatility:Captive ethylene oxide supply at Ludwigshafen and Conroe insulates integrated producers while merchant buyers face ethylene chain price swings.
- Purity documentation burden:FDA current Good Manufacturing Practice impurity profiling for pharmaceutical intermediates extends qualification timelines to 18-24 months for new supplier onboarding.
- Alkanolamine substitution pressure:Commodity diethanolamine and triethanolamine variants compete in surfactant applications where functional equivalence permits formulation switching.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's accelerated API approval pathways and PLI scheme incentives are attracting custom synthesis investments that require high-specification amino alcohol intermediates.
- Powder-grade analytical standards:Reference material laboratories in Switzerland and Germany command margin premiums for certified reference standards with sub-ppm impurity certificates.
- Green chemistry mandates:EU Green Deal sustainable chemistry criteria favor bio-based feedstock routes for amine synthesis, creating qualification advantages for renewable-derived products.
Industry Challenges
- Specialized chemist scarcity:Reductive amination process expertise and continuous flow optimization skills concentrate at Ludwigshafen and Conroe, constraining capacity expansion at second-tier sites.
- Multi-jurisdiction compliance synchronization:Divergent EPA TSCA evaluation timelines versus ECHA harmonized classification procedures create inventory positioning complexity for cross-Atlantic traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market |
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $44.82 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Solution Application: Pharmaceuticals, Chemicals, Research, Cosmetics End User: Hospitals, Laboratories, Research Institutions, Manufacturing Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Huntsman Corporation, Akzo Nobel N.V., Eastman Chemical Company, Solvay S.A., Nouryon, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market Trends and Innovations
Digital process control systems and predictive analytics are compressing batch-to-batch variability in amino alcohol synthesis while regulatory data automation is reshaping supplier qualification workflows across pharmaceutical value chains.
Flow chemistry automation is virtualizing traditional batch synthesis protocols for 2-(4-Aminopentyl(Ethyl)Amino)Ethanol production. Contract manufacturers at Germany's Rhine-Main sites are deploying sensor-integrated microreactors that enable real-time purity monitoring and reduce solvent waste streams. This virtualization is compressing capital requirements for capacity expansion while tightening impurity control beyond batch reactor capabilities.
EMA's revised guideline on elemental impurities in pharmaceutical products is forcing amino alcohol suppliers to implement ICP-MS screening protocols for catalyst residues. The industrial consequence is a tiered supplier base where integrated producers with in-house metals testing laboratories capture formulation laboratory contracts. European API manufacturers are responding by consolidating procurement around REACH-registered suppliers with documented elemental impurity control strategies.
Buyer concentration among top-ten pharmaceutical contract manufacturers is compressing negotiation leverage for mid-tier amino alcohol traders. Direct sales channels now dominate volume procurement for commercial API synthesis, while research institutions fragment purchases across specialized chemical distributors. This channel bifurcation is most visible in Germany, where custom synthesis houses negotiate multi-year supply agreements while academic laboratories rely on catalog distributors with limited technical support.
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market Segmentation
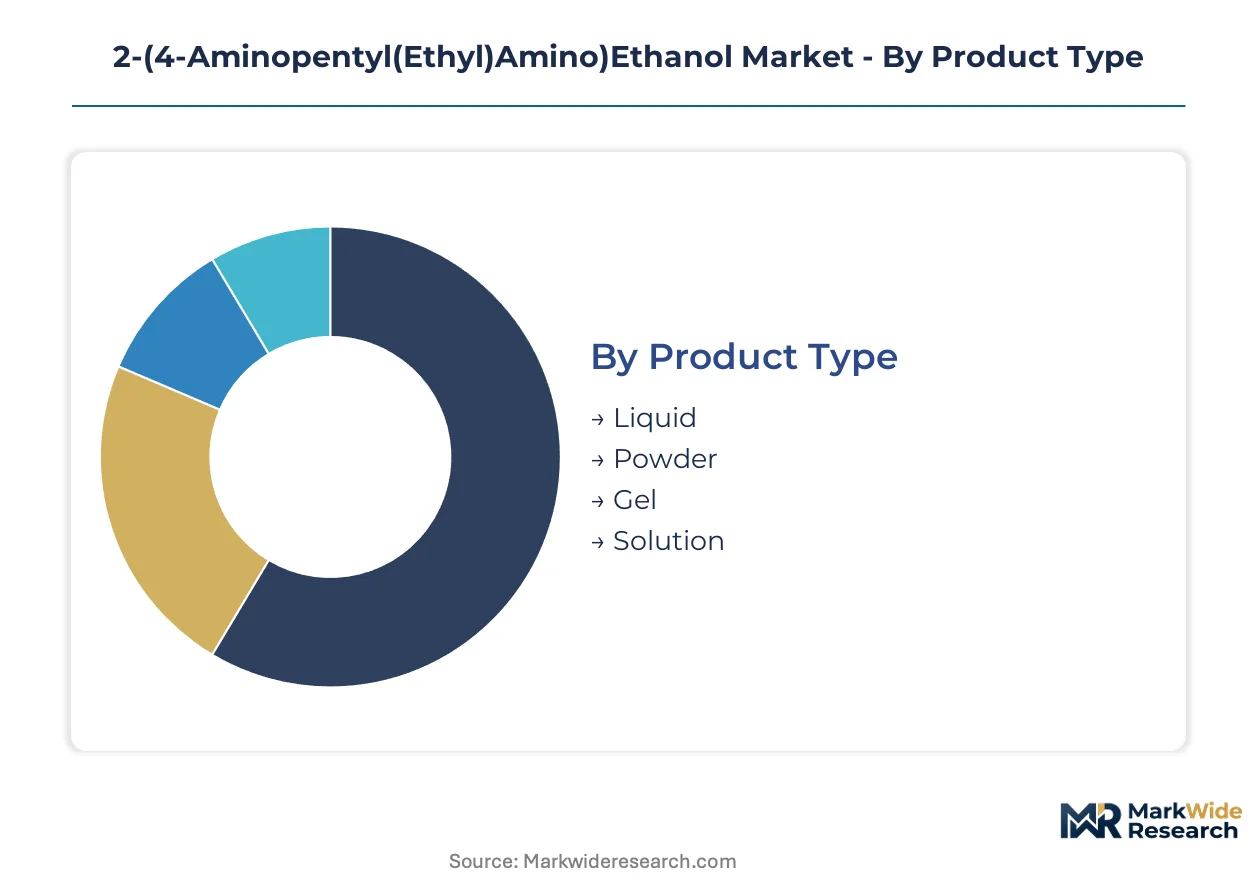
Specialty amino alcohol procurement divides sharply between bulk pharmaceutical intermediates and precision analytical grades, with formulation requirements dictating product form, purity thresholds, and channel selection. Segmentation clarity enables suppliers to align capacity investments with the divergent qualification burdens of commercial API synthesis versus research-scale offtake.
Product Type:
Mature liquid formulations dominate commercial throughput while powder and gel variants occupy emerging niches with steeper technical barriers.
- Liquid:Low-viscosity formulations engineered for continuous flow reactor compatibility, with Rhine-Main pharmaceutical contract manufacturers specifying narrow density ranges for microreactor feedstock. German custom synthesis houses anchor volume demand as they retrofit batch facilities with sensor-integrated flow systems.
- Powder:Spray-dried or crystalline grades with sub-ppm residual solvent specifications, certified for analytical reference standards. Swiss and German reference material laboratories command premium positioning for ICP-MS-screened batches with documented elemental impurity profiles.
- Gel:Thickened aqueous preparations for topical pharmaceutical prototyping and cosmetic formulation R&D.
- Solution:Pre-diluted aqueous or alcoholic preparations for research institutions requiring immediate-use convenience without in-house dissolution protocols.
Liquid handles the majority of throughput; powder is the fastest mover on share.
Application:
Cost tier stratification separates high-qualification pharmaceutical intermediates from commodity-exposed surfactant applications.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and intermediate production for regulated drug substances, requiring REACH-registered supply chains with full dossier submissions. FDA current Good Manufacturing Practice compliance extends supplier qualification timelines to 18-24 months.
- Chemicals:Specialty surfactant and alkylamino alcohol formulation for industrial and personal care compounders, where mild cleansing systems compete against commodity diethanolamine substitutes.
- Research:Academic and institutional procurement for method development and analytical validation, fragmenting across catalog distributors with limited technical support.
- Cosmetics:Sulfate-free cleansing formulations and mild surfactant systems targeting dermatological positioning in United States personal care markets.
Pharmaceuticals commands the dominant value share; cosmetics is expanding most quickly as sulfate-free positioning accelerates.
End User:
Customer type concentration bifurcates between consolidated contract manufacturers and fragmented research purchasers.
- Hospitals:Limited direct procurement for in-house compounding and specialized therapeutic preparation, with most amino alcohol inputs arriving via finished drug product supply chains.
- Laboratories:Quality control and analytical testing facilities requiring certified reference materials with documented traceability.
- Research Institutions:Academic chemistry departments and government research facilities purchasing through online retail platforms with minimal volume commitment.
- Manufacturing:Commercial-scale API producers and pharmaceutical contract manufacturers negotiating multi-year direct supply agreements with REACH-registered importers.
Manufacturing absorbs the bulk of commercial volume; research institutions represent the most dispersed demand pattern.
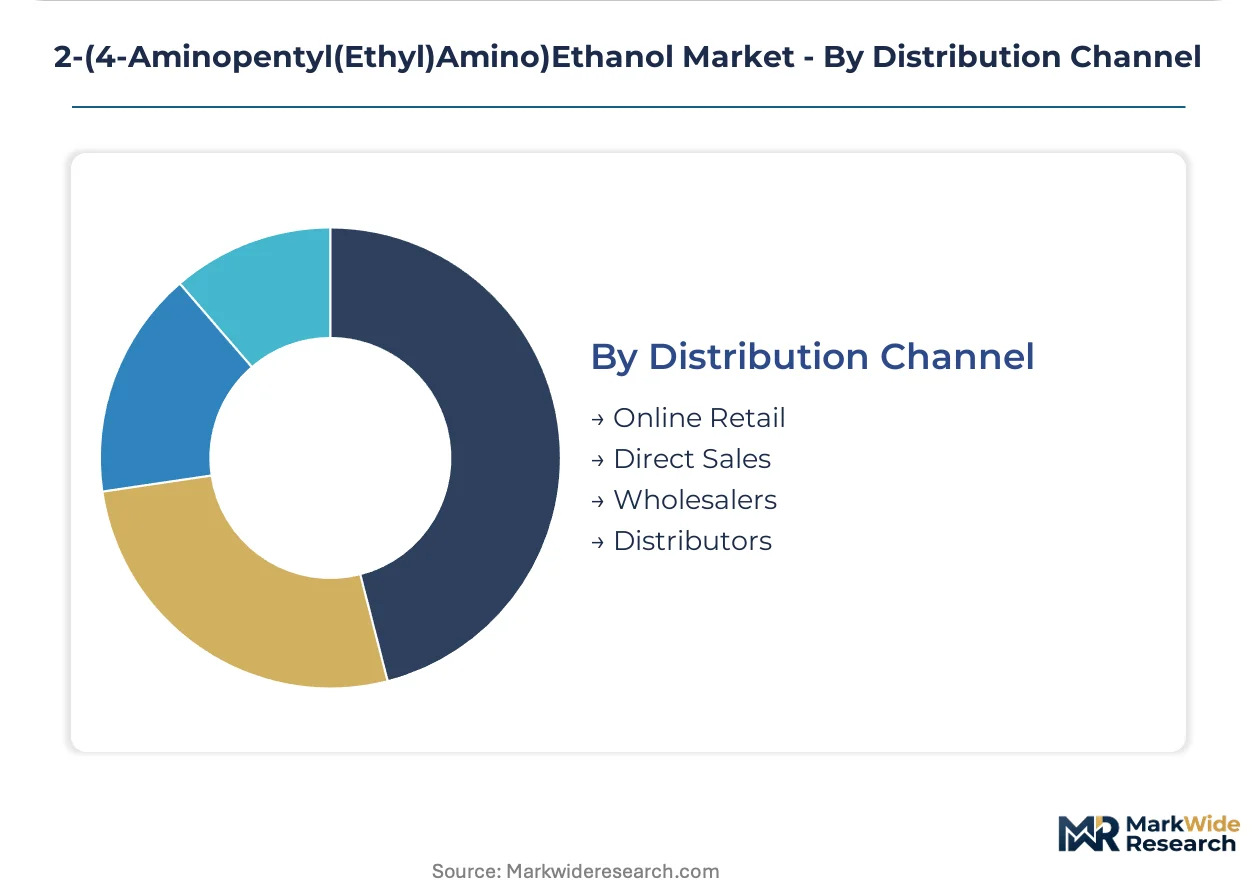
Distribution Channel:
Supply concentration favors direct relationships for qualified pharmaceutical supply, while merchant channels serve price-sensitive research segments.
- Online Retail:Catalog-based procurement for research-scale quantities, with limited technical documentation and minimal supplier qualification support.
- Direct Sales:Long-term supply agreements between amino alcohol producers and top-ten pharmaceutical contract manufacturers, consolidating negotiation leverage and compressing margins for mid-tier traders.
- Wholesalers:Regional chemical distributors serving mid-size formulation houses with standardized product grades and limited customization.
- Distributors:Specialized life science distributors bridging REACH-registered European suppliers with North American pharmaceutical manufacturers navigating EPA Toxic Substances Control Act evaluation requirements.
Direct sales captures the pharmaceutical value pool; distributors are gaining share fastest as cross-Atlantic regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration regime filters non-compliant traders from European amino alcohol supply chains, concentrating volume among dossier-holding importers. Pharmaceutical contract manufacturers in Germany's Rhine-Main corridor anchor regional demand as continuous flow chemistry retrofits accelerate. India's CDSCO approval pathways and PLI scheme incentives are attracting custom synthesis investments requiring high-specification intermediates.
Germany
Pharmaceutical contract manufacturers at Ludwigshafen and Frankfurt am Main drive liquid-grade amino alcohol consumption for microreactor feedstock. ECHA's escalating tonnage-band data requirements under REACH filter smaller traders from regulated supply chains. BASF SE's integrated Ludwigshafen complex sustains captive ethylene amine feedstock advantages for regional amino alcohol production.
United States
Personal care compounders in New Jersey and California expand alkylamino alcohol portfolios for sulfate-free cleansing formulations. EPA Toxic Substances Control Act evaluations enforce purity documentation burdens that concentrate procurement among pre-qualified suppliers. Huntsman Corporation's Conroe, Texas amines complex anchors North American supply through backward integration into ethylene oxide feedstock.
India
CDSCO's accelerated API approval pathways attract pharmaceutical custom synthesis investments requiring high-specification amino alcohol intermediates. The PLI scheme for active pharmaceutical ingredients incentivizes domestic manufacturing capacity for regulated intermediates. Maharashtra's Mumbai-Pune pharmaceutical cluster concentrates demand as multinational contract manufacturers establish local sourcing relationships.
Switzerland
Reference material laboratories in Basel and Zurich command margin premiums for certified analytical standards with sub-ppm impurity certificates. Swissmedic's pharmaceutical quality standards align with EMA elemental impurity guidelines requiring ICP-MS screening protocols. The Basel life science corridor concentrates precision-grade amino alcohol demand from multinational pharmaceutical quality control operations.
China
NMPA's pharmaceutical intermediate registration requirements are tightening documentation standards for amino alcohol imports used in API synthesis. The Yangtze River Delta chemical cluster around Shanghai concentrates surfactant formulation demand for personal care applications. Domestic amine producers are expanding specialty alkylamino alcohol capacity to serve both export pharmaceutical markets and local sulfate-free surfactant compounders.
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market Competitive Landscape
Vertically integrated chemical conglomerates and specialized alkylamine producers split the market between captive feedstock advantages and application-specific formulation expertise. The vendor base concentrates around three strategic archetypes: integrated petrochemical majors with ethylene oxide backward integration, specialty amine houses focusing on pharmaceutical-grade purity, and regional distributors bridging regulatory compliance gaps. Competitive moves center on REACH dossier completion for European market access and continuous flow chemistry partnerships with pharmaceutical contract manufacturers.
Among European-integrated majors, BASF SE exemplifies the petrochemical archetype through its Ludwigshafen complex, while Evonik Industries AG represents specialty amine expertise for life science applications. Huntsman Corporation anchors North American positioning through its Texas-based amines operations. These three entities collectively illustrate the competitive divide between scale-driven feedstock integration and specification-driven pharmaceutical qualification.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Huntsman Corporation |
| Akzo Nobel N.V. |
| Eastman Chemical Company |
| Solvay S.A. |
| Nouryon |
| Clariant AG |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Germany's Rhine-Main pharmaceutical corridor is concentrating pricing power among REACH-registered suppliers with captive ethylene amine feedstock, forcing merchant buyers to absorb ethylene chain volatility while integrated producers defend margin structures through backward control.
Pricing Analysis
German liquid-grade formulations trade at substantial premiums to United States surfactant-tier deliveries, reflecting REACH dossier completion costs and microreactor feedstock certification requirements. Three-tier pricing structure across pharmaceutical-grade, analytical-standard, and industrial-surfactant levels separates buyers by qualification burden and volume commitment. Cost compression in commodity-exposed surfactant tiers is intensifying as diethanolamine substitution pressure erodes formulation premiums. Research institutions exhibit highest price sensitivity due to fragmented catalog purchasing, while pharmaceutical contract manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Extended payment terms from German custom synthesis houses to Ludwigshafen suppliers illustrate supply-chain finance facilities tightening working capital constraints for non-integrated traders. Production gravity centers on Germany, the United States, and India, with captive ethylene oxide supply at Ludwigshafen and Conroe insulating integrated majors from merchant feedstock exposure. The chain rests on ethylene amine precursors, ethanolamine derivatives, and catalyst metals for reductive amination. Single-source vulnerability concentrates at Rhine-Main for pharmaceutical-grade qualification. Distribution runs through direct sales channels for commercial API manufacturers and specialized life science distributors for cross-Atlantic regulatory bridging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH dossier completion and FDA current Good Manufacturing Practice qualification creates formidable defensive moats, as eighteen-to-twenty-four-month supplier onboarding timelines lock pharmaceutical contract manufacturers into established relationships.
For Market Incumbents: Entrench position by completing higher tonnage-band REACH registrations before ECHA's next data deadline, and expand captive ethylene amine capacity at Ludwigshafen or Conroe to neutralize feedstock volatility threats from merchant ethylene oxide markets. Certification investment in ICP-MS metals screening protocols captures EMA elemental impurity guideline compliance premiums from Swiss reference material laboratories. For New Entrants and Emerging Players: India's Maharashtra pharmaceutical cluster represents the most penetrable entry point, where CDSCO accelerated API approvals and PLI scheme incentives attract multinational contract manufacturing investments requiring high-specification amino alcohol intermediates. Powder-grade analytical standards for Swiss and German reference laboratories offer secondary white-space with margin premiums detached from commodity surfactant competition. A go-to-market angle through specialized life science distributors bridges REACH-registered European supply with North American EPA TSCA evaluation requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among REACH-registered suppliers with multi-year direct sales agreements to top-ten pharmaceutical contract manufacturers, as qualification timelines create sticky offtake relationships resistant to price-based switching. Long-term viability favors integrated petrochemical majors with ethylene oxide backward integration or specialty amine houses with pharmaceutical-grade purity expertise. The signal to watch is EMA enforcement action on elemental impurity violations, which would accelerate consolidation around suppliers with in-house ICP-MS screening capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Tonnage-Band Registration Completion | ECHA dossier submission secures legal market access for specialty amine volumes above one-hundred-ton thresholds. |
| Continuous Flow Chemistry Partnership | Microreactor feedstock agreements with Rhine-Main contract manufacturers lock in pharmaceutical-grade demand. |
| ICP-MS Metals Screening Installation | In-house elemental impurity testing captures EMA guideline compliance premiums from Swiss reference laboratories. |
| India Manufacturing Footprint Establishment | CDSCO PLI scheme alignment positions suppliers for API intermediate demand from Maharashtra pharmaceutical cluster. |
| Backward Ethylene Oxide Integration | Captive feedstock supply at Ludwigshafen or Conroe insulates margin structures from merchant ethylene chain volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, FDA drug master file submissions, and customs trade flows for amino alcohol classifications. Conversations with pharmaceutical contract manufacturing procurement directors, specialty amine plant managers at integrated chemical complexes, and regulatory affairs specialists handling REACH dossier submissions informed supply-side dynamics. Secondary validation drew from SEC 10-K disclosures of listed chemical producers, Cefic sector reports, and EPA TSCA chemical data reporting. Bottom-up volume estimates from end-use application modeling were triangulated against top-down trade flow analysis.
Forecast inputs span pharmaceutical intermediate demand by API synthesis route, surfactant formulation requirements by sulfate-free cleansing adoption, and analytical standard certification by reference laboratory procurement patterns. Segmentation dimensions include product form, application tier, end-user concentration, and distribution channel structure. CAGRs were derived from regression analysis against pharmaceutical manufacturing output indices and personal care formulation trends. Industry-specific inputs incorporate EMA elemental impurity guideline enforcement trajectories and continuous flow chemistry retrofit rates at Rhine-Main sites.
Practitioners should monitor ECHA registration deadline compliance rates and EPA TSCA evaluation timeline divergence for early signals of supply concentration or regulatory friction. Forecasts embed assumptions around REACH dossier maintenance costs and pharmaceutical contract manufacturer sourcing consolidation. Macroeconomic deviation in ethylene chain pricing, regulatory acceleration in elemental impurity enforcement, or technological displacement by flow chemistry automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Epoxy Thinner Market
Solvents
Tetraethyl Benzene Market
Solvents
Butane Market
Solvents
Coating Solvents Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Hydrosol Market
Solvents
Benzyl Alcohol Market
Solvents
India High Purity Solvents Market
Solvents
1,2-Ethanedithiol Market
Solvents
2-Phenylethanol Market
Solvents
Crotonaldehyde Market
Solvents
Dihydromyrcene Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Global Ethyl Lactate Market
Solvents
Phenol Derivatives Market
Solvents
Global 2-Ethoxyethanol Market