

1,2-Ethanedithiol Market Size, Share, and Industry Trends Forecast 2026-2036
1,2-Ethanedithiol Market Insights
The 1,2-Ethanedithiol market is pivoting on a widening split between pharmaceutical-grade purity standards and commodity technical-grade volumes. Matrix Fine Chemicals leverages its European manufacturing base to serve regulated pharmaceutical synthesis customers with documented batch consistency. Sanmenxia Aoke Chemical Industry anchors the technical-grade segment through integrated production of thiol precursors in Henan Province. Shanghai Zhuorui Chemical differentiates by specializing in reagent-grade packaging for laboratory research channels across East Asia.
1,2-Ethanedithiol is an organic compound with the formula HSCH₂CH₂SH, a colorless liquid with a strong odor, featuring two thiol functional groups that enable metal chelation and nucleophilic substitution reactions. Manufacturers produce it through ethylene dichloride reaction with sodium hydrosulfide or via ethylene oxide conversion, yielding purities from technical grade to reagent grade depending on distillation steps. Pharmaceutical synthesis applications command premium pricing due to stringent impurity thresholds, while agrochemical production absorbs the largest volume share as technical-grade material for pesticide intermediate manufacturing. Chemical intermediates represent the fastest-expanding application segment as downstream specialty sulfur compounds find wider industrial use.
EPA oversight under the Toxic Substances Control Act governs commercial handling and emission thresholds for thiol compounds in the United States, while REACH registration requirements in Europe mandate comprehensive safety dossiers for importers and manufacturers. China's MEE enforces wastewater discharge standards that affect thiol production facility permitting in Shandong and Jiangsu provinces. Stakeholders must monitor evolving pharmaceutical-grade certification requirements and regional environmental enforcement intensity when allocating capacity investments across purity tiers.
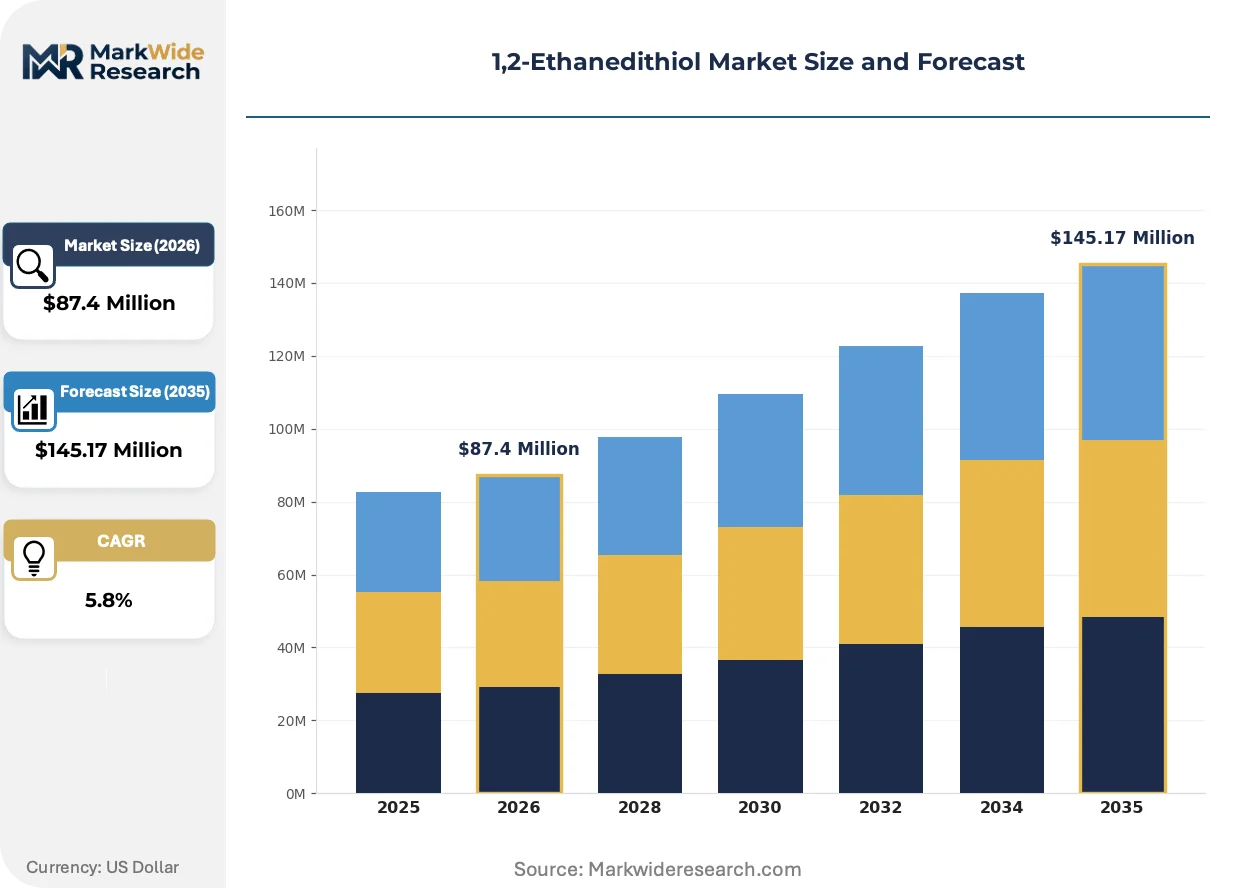
Market Dynamics
The 1,2-Ethanedithiol market is bifurcating sharply between pharmaceutical-grade purity mandates and commodity technical-grade volumes, with regulatory divergence across jurisdictions forcing manufacturers to maintain parallel production lines and certification systems.
Growth Catalysts
- REACH registration dossiers:European pharmaceutical manufacturers now require documented impurity profiles for nucleophilic substitution reactions, pulling high-purity grades into synthetic routes for complex APIs.
- Agrochemical intermediate demand:China's domestic pesticide sector absorbs technical-grade output for thiol-based fungicide precursors, with Henan and Shandong provinces scaling captive production.
- Metal chelation chemistry:Mining and electroplating applications in South America and Australia are expanding consumption for ore processing and wastewater treatment protocols.
Market Restraints
- Feedstock volatility:Ethylene dichloride pricing tracks chlor-alkali capacity swings, compressing margins for producers without backward integration into caustic soda or chlorine production.
- Substitution pressure:1,3-Propanedithiol and thioglycolic acid derivatives are displacing 1,2-Ethanedithiol in certain metal chelation applications where odor tolerance is lower.
- Environmental discharge limits:China's MEE wastewater standards for thiol-containing effluent have raised compliance costs for Shandong and Jiangsu production facilities.
Strategic Opportunities
- Reagent-grade laboratory channels:Academic and contract research organizations across East Asia are consolidating purchasing through specialized chemical distributors, creating premium pricing tiers.
- Green synthesis routes:Bio-based ethylene oxide feedstocks and enzymatic thiolation processes are opening pathways to carbon-intensity certifications valued by European pharmaceutical buyers.
- Specialty sulfur compound derivatives:Downstream manufacturers of thioethers, thioesters, and heterocyclic intermediates are seeking captive 1,2-Ethanedithiol supply for vertical integration.
Industry Challenges
- Analytical chemistry talent scarcity:Pharmaceutical-grade batch certification requires gas chromatography-mass spectrometry expertise that competes with broader fine chemical sectors for skilled technicians.
- Dual-track facility design:Producers serving both technical and pharmaceutical grades must segregate equipment, ventilation, and documentation systems, raising capital intensity per ton of nameplate capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,2-Ethanedithiol Market Trends and Innovations
Continuous processing technology and automated distillation systems are compressing batch-to-batch variability, while regulatory data integrity requirements are reshaping how manufacturers document and transfer quality specifications across supply chains.
Membrane separation technology is electrifying purification economics for reagent-grade production. German and Swiss specialty chemical firms are retrofitting continuous membrane systems alongside traditional fractional distillation, cutting energy consumption per kilogram of high-purity output. This hybrid approach is enabling smaller batch sizes with documented traceability for pharmaceutical synthesis customers.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity thresholds for sulfur-containing process chemicals. ECHA guidance on Substances of Very High Concern is forcing importers to submit extended safety data for thiol derivatives used in consumer-facing applications. Pharmaceutical-grade producers are responding by investing in dedicated analytical laboratories capable of detecting parts-per-billion contaminants.
Contract research organizations are consolidating chemical sourcing through preferred supplier programs with audited quality systems. East Asian academic institutions and biotech startups are shifting from spot purchases to annual framework agreements with documented chain-of-custody records. Japan's PMDA-aligned research facilities are driving this behavioral shift through mandatory supplier qualification for GMP-adjacent studies.
1,2-Ethanedithiol Market Segmentation
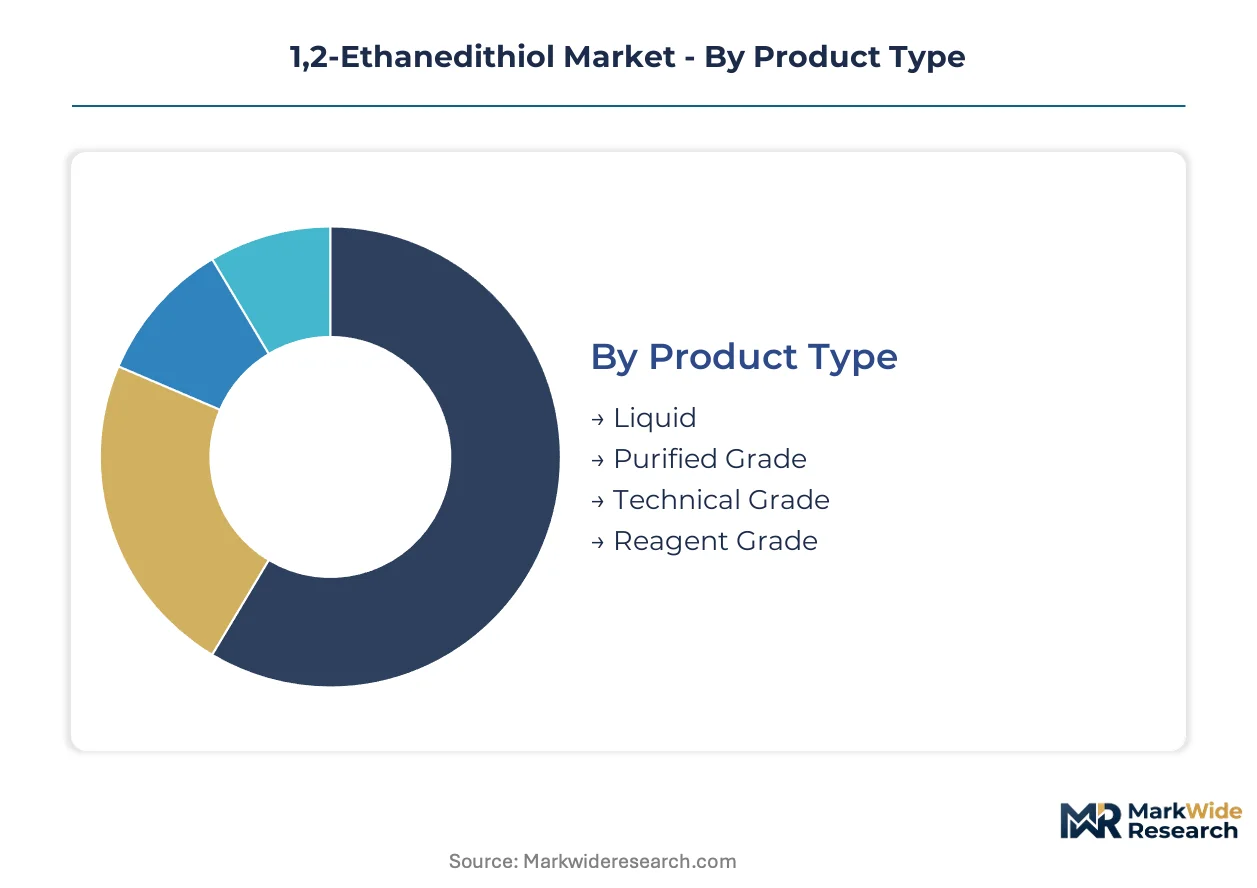
Segmentation in the 1,2-Ethanedithiol market reveals a stark divide between high-purity pharmaceutical grades and commodity technical volumes. Each tier operates under distinct regulatory regimes, customer qualification requirements, and margin structures that shape competitive positioning.
Product Type:
Purity specifications separate premium pharmaceutical grades from bulk technical material, with reagent-grade commanding laboratory premiums and liquid formulations serving process chemistry needs.
- Liquid:Standard physical state for industrial handling, delivered in bulk to agrochemical manufacturers and metal chelation facilities. Henan Province chemical parks absorb the largest volumes for thiol-based fungicide precursor synthesis.
- Purified Grade:Multi-stage fractional distillation yields impurity profiles below 500 ppm for nucleophilic substitution reactions in API manufacturing. European REACH registration dossiers now mandate documented batch-to-batch consistency from suppliers serving EMA-regulated pharmaceutical customers.
- Technical Grade:Single-pass distillation material for pesticide intermediate production and polymer stabilization. China's domestic pesticide sector in Shandong Province scales captive consumption for thiol-derived fungicide active ingredients.
- Reagent Grade:Laboratory-scale packaging with ppm-level impurity documentation for academic and CRO synthesis routes. East Asian contract research organizations are consolidating procurement through audited distributor frameworks.
Today's leader: Technical Grade. Tomorrow's challenger: Purified Grade.
Application:
End-use concentration tracks regional industrial specialization, with pharmaceutical synthesis pulling high-purity material and agrochemical production absorbing volume.
- Pharmaceutical Synthesis:Nucleophilic substitution reactions in complex API construction demand documented impurity thresholds. EMA and FDA oversight forces manufacturers to maintain dedicated analytical laboratories and chain-of-custody documentation systems.
- Agrochemical Production:Thiol-based fungicide and insecticide precursors consume technical-grade volumes at scale. China's domestic pesticide formulation sector in Jiangsu and Shandong provinces drives regional production capacity expansion.
- Polymer Stabilizers:Sulfur-containing additives for rubber and plastic antioxidant systems. Automotive supply chains in Germany and Japan specify technical-grade material for tire manufacturing.
- Chemical Intermediates:Downstream thioether and thioester synthesis for specialty sulfur compounds. Expanding most quickly as industrial users seek captive thiol supply for vertical integration.
Agrochemical Production commands current volume leadership. Chemical Intermediates show the steepest expansion trajectory.
End User:
Customer type determines packaging scale, certification burden, and procurement channel structure across the value chain.
- Chemical Manufacturers:Bulk drum and tote consumption for process chemistry integration. Integrated producers in China's chemical parks backward into thiol precursor production to secure supply.
- Laboratory Research:Small-volume bottle procurement with reagent-grade certification requirements. Japan's PMDA-aligned research facilities drive supplier qualification mandates for GMP-adjacent studies.
- Specialty Chemicals:Custom synthesis houses and fine chemical producers requiring flexible purity tiers. Swiss and German specialty firms specify membrane-purified grades for pharmaceutical-adjacent applications.
- Pesticide Formulators:Technical-grade drum shipments for active ingredient synthesis. Brazilian ANVISA and Australian APVMA registration requirements shape import specifications for thiol-derived agrochemical inputs.
Chemical Manufacturers dominate procurement scale. Laboratory Research delivers the highest margin per kilogram.
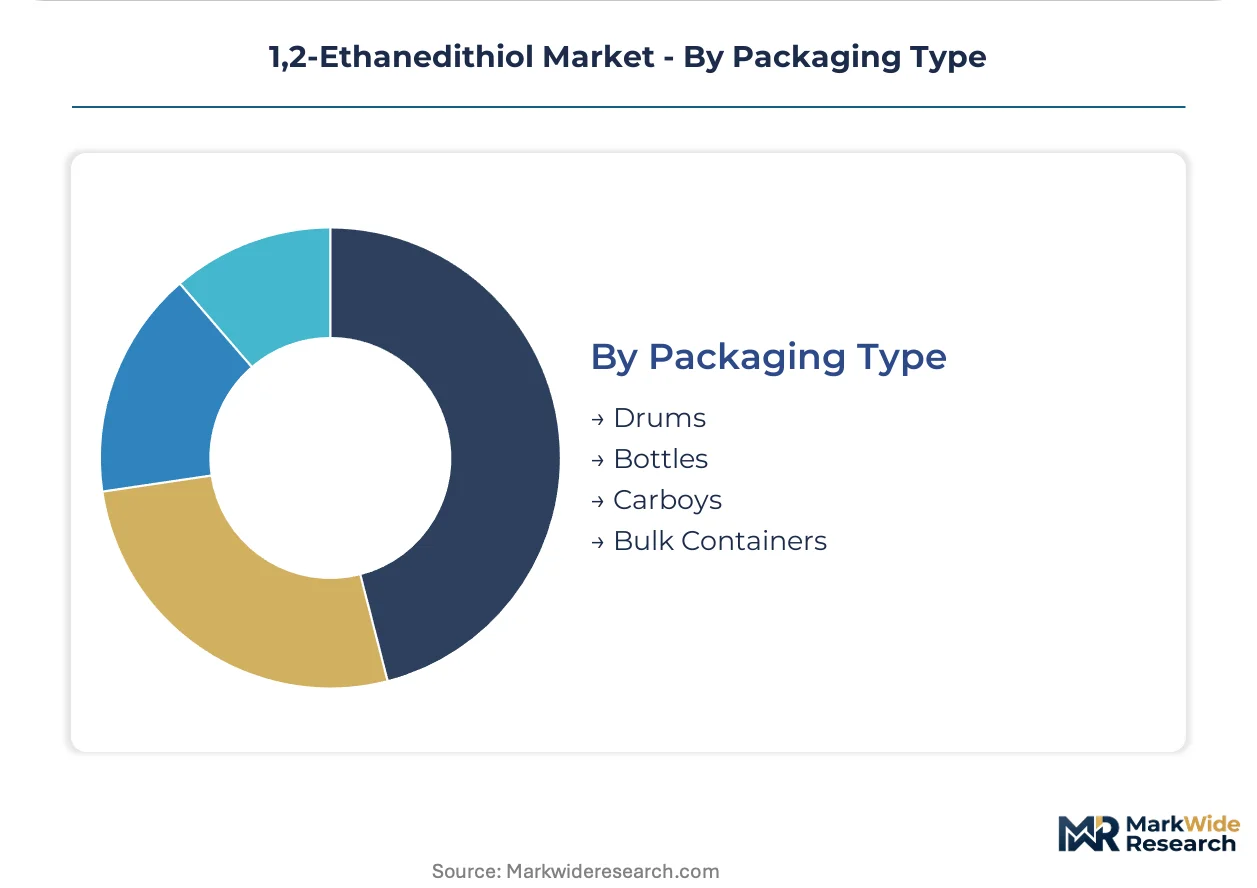
Packaging Type:
Container format aligns with customer scale, regulatory documentation needs, and hazardous material handling protocols.
- Drums:Standard 200-liter steel packaging for industrial chemical manufacturers. EPA and OSHA hazardous material regulations govern US domestic transport and storage.
- Bottles:Glass and fluoropolymer containers for reagent-grade laboratory distribution. PMDA-aligned Japanese research facilities require tamper-evident seals and lot-specific certificates of analysis.
- Carboys:Intermediate-volume plastic containers for pilot-scale synthesis operations. Specialty chemical producers in Switzerland and Germany specify UN-certified carboys for cross-border EU distribution.
- Bulk Containers:ISO tanks and flexitanks for agrochemical intermediate producers with integrated storage. China's MEE wastewater and emissions standards affect bulk handling facility permitting in coastal chemical parks.
Drums anchor industrial throughput. Bottles capture the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest technical-grade volumes for agrochemical intermediates, while Germany's pharmaceutical manufacturers command premium pricing for REACH-compliant purified grades. This divergence shapes capacity allocation and certification investments across production networks.
China
Henan and Shandong provinces scale domestic output for thiol-based fungicide precursors. MEE wastewater discharge standards tighten compliance costs for coastal chemical parks. Sanmenxia Aoke Chemical Industry anchors captive production in Henan Province with integrated thiol precursor manufacturing.
Germany
Specialty chemical manufacturers in Baden-Württemberg and North Rhine-Westphalia demand documented batch consistency for nucleophilic substitution reactions. ECHA REACH registration mandates comprehensive safety dossiers for thiol importers. Membrane separation technology retrofits in Swiss and German facilities cut energy consumption for reagent-grade output.
United States
EPA Toxic Substances Control Act oversight governs commercial handling thresholds for thiol compounds in pharmaceutical synthesis. FDA-aligned research facilities in Greater Boston and the Research Triangle specify chain-of-custody documentation for GMP-adjacent studies. Metal chelation applications in Arizona and Nevada mining operations expand technical-grade consumption.
Japan
PMDA-aligned research facilities in Kanto and Kansai regions drive supplier qualification mandates for laboratory reagent procurement. METI standards shape hazardous material handling protocols for thiol distribution. Academic institutions in Tokyo and Osaka consolidate purchasing through audited framework agreements.
Brazil
ANVISA registration requirements shape import specifications for thiol-derived agrochemical inputs in São Paulo and Minas Gerais. Pesticide formulators in the agricultural belt absorb technical-grade drum shipments for active ingredient synthesis. Domestic blending operations seek backward integration into sulfur compound supply chains.
1,2-Ethanedithiol Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification systems, while technical-grade producers compete on scale and feedstock integration. The vendor base spans European specialty chemical houses, Chinese integrated producers, and regional laboratory distributors. Three archetypes dominate: REACH-registered European suppliers, captive-integrated Chinese manufacturers, and reagent-grade laboratory specialists. Capacity expansion in Shandong Province and strategic partnerships for green synthesis routes represent the dominant competitive moves.
Among China-based integrated producers, Sanmenxia Aoke Chemical Industry and Shanghai Zhuorui Chemical exemplify the technical-grade and reagent-grade archetypes respectively. Matrix Fine Chemicals occupies a position representing European REACH-compliant supply. These three names anchor the competitive structure without exhaustively mapping the fragmented lower tier.
| Leading Market Players |
|---|
| Matrix Fine Chemicals |
| Sanmenxia Aoke Chemical Industry |
| Shanghai Zhuorui Chemical |
| Shanghai Ruifu Chemical |
| Jinan Xinggao Chemical Technology |
| ADVENT CHEMBIO PRIVATE LIMITED |
| Syglak Laboratories |
| Otto Chemie |
| Central Drug House |
| Others |
Pricing and Supply Chain Analysis
REACH-registered pharmaceutical buyers in Germany and Switzerland now mandate documented carbon-intensity certifications alongside traditional purity specifications, forcing suppliers to reconfigure production assets and absorb certification costs that widen spreads between technical and reagent grades.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for technical-grade material, compressing margins for non-integrated producers while purified grades maintain premium spreads through EMA-mandated batch documentation. Three-tier pricing structure across reagent, purified, and technical levels reflects certification burden and analytical chemistry investment. Cost compression in the technical tier intensifies as Henan Province integrated producers leverage captive caustic soda supply. Pesticide formulators in Brazil and China exhibit highest price sensitivity, while PMDA-aligned Japanese research facilities accept reagent-grade premiums for tamper-evident packaging and chain-of-custody records.
Supply Chain Analysis
Reverse logistics for reagent-grade returns and expired laboratory stock operates through specialized chemical distributors in East Asia, with Swiss and German facilities refurbishing membrane separation equipment for secondary markets. Manufacturing concentrates in China, Germany, and Switzerland, with Shandong and Henan provinces anchoring technical-grade output and Baden-Württemberg housing REACH-registered pharmaceutical supply. Feedstock draws from ethylene dichloride and sodium hydrosulfide streams tethered to chlor-alkali capacity swings. Single-source vulnerability runs through Chinese thiol precursor integration. Distribution runs through audited distributor frameworks for laboratory channels and bulk drum networks for agrochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on membrane separation technology retrofits cutting energy consumption per kilogram of high-purity output, alongside pharmaceutical-grade certification investments that widen pricing spreads.
For Market Incumbents: Cement analytical laboratory capabilities capable of parts-per-billion contaminant detection to defend EMA and FDA-aligned customer relationships against emerging membrane-purified entrants from Swiss specialty houses. Deepen backward integration into ethylene dichloride or caustic soda production to offset feedstock volatility compressing technical-grade margins. Prioritize dual-track facility segregation investments that satisfy both pharmaceutical-grade documentation and technical-grade volume throughput without cross-contamination risk. For New Entrants and Emerging Players: The price-point gap between reagent-grade laboratory premiums and commodity technical-grade volumes offers entry space for mid-purity grades targeting contract research organizations consolidating procurement through audited frameworks. White-space sits in green synthesis routes using bio-based ethylene oxide feedstocks to serve European pharmaceutical buyers seeking carbon-intensity certifications. Penetrate East Asian academic institutions shifting from spot purchases to annual agreements by offering PMDA-aligned documentation and lot-specific certificates of analysis. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane separation technology specialists capable of retrofitting continuous purification systems for energy-efficient reagent-grade production. Long-term viability favors producers with dual certification systems spanning REACH registration and China's MEE wastewater compliance, enabling supply security across regulatory jurisdictions. Acquisition targets should demonstrate integrated thiol precursor production or captive ethylene dichloride supply. Monitor ECHA guidance on Substances of Very High Concern for thiol derivatives as an inflection signal for impurity threshold tightening and analytical chemistry investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caustic Soda Production | Henan Province producers offset ethylene dichloride feedstock volatility through captive chlor-alkali capacity. |
| Membrane Separation Technology Retrofit | Swiss and German facilities cut energy consumption per kilogram while enabling smaller batch traceability for EMA customers. |
| REACH Registration Dossier Investment | European pharmaceutical manufacturers now require documented impurity profiles for nucleophilic substitution reactions in complex API construction. |
| Green Synthesis Route Development | Bio-based ethylene oxide feedstocks and enzymatic thiolation processes open pathways to carbon-intensity certifications valued by European buyers. |
| Long-term Supply Agreement with CRO Networks | East Asian contract research organizations consolidate chemical sourcing through preferred supplier programs with audited quality systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Shandong and Henan production facilities, procurement leads at downstream agrochemical formulators, distribution channel partners handling laboratory reagent logistics, and technical R&D directors at Swiss and German specialty chemical houses. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration databases. Bottom-up capacity assessments and top-down demand modeling triangulated across these sources.
Historical reference periods anchored the projection horizon to observed capacity utilization rates, feedstock cost trajectories, and regulatory enforcement intensity across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, packaging format, and regional production hub. CAGRs derived from fitted growth curves reflecting pharmaceutical synthesis demand expansion, agrochemical intermediate consumption patterns, and metal chelation chemistry adoption. Industry-specific inputs incorporated chlor-alkali capacity cycles and ECHA guidance evolution on sulfur-containing process chemicals.
Caveats apply where MEE wastewater standard enforcement intensity, ethylene dichloride feedstock volatility, or ECHA Substances of Very High Concern reclassifications could materially shift the outlook. Forecasts reflect assumptions regarding membrane separation technology adoption rates and pharmaceutical-grade certification investment pacing. Practitioners should monitor ECHA guidance publications and Shandong Province environmental inspection schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.