
 Ethyl Pyruvate Market | 2026-2036
Ethyl Pyruvate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Pyruvate Market Insights
Multi-source procurement among pharmaceutical fine chemical buyers is recalibrating supplier relationships across the ethyl pyruvate value chain. Merck KGaA leverages its integrated life sciences platform to control quality documentation from raw pyruvate through final esterification. Tokyo Chemical Industry anchors Asia-Pacific laboratory supply channels with catalog-scale distribution. BASF competes on captive acetaldehyde feedstock access, sustaining cost positions in European pharmaceutical contract manufacturing.
Ethyl pyruvate is the ethyl ester of pyruvic acid, a colorless liquid with molecular formula C5H8O3 typically synthesized via acid-catalyzed esterification of pyruvic acid with ethanol under controlled temperature and pressure conditions, serving primarily as a reactive intermediate, cell culture additive, and flavoring agent. Liquid-grade material dominates pharmaceutical procurement due to handling compatibility with automated formulation systems, while powder and granule formats occupy nutraceutical tableting workflows where flow properties and shelf stability command premium positioning. The Cosmetics application segment shows structural momentum as formulators incorporate ethyl pyruvate for antioxidant claims in skin care, though Pharmaceuticals retains the deepest margin pool through GMP-certification requirements and audit-intensive vendor qualification.
FDA excipient guidelines, REACH substance registration in Europe, and ISO 10993 biocompatibility standards collectively elevate documentation burdens for clinical-grade ethyl pyruvate suppliers, filtering non-compliant producers from pharmaceutical qualification lists. These frameworks intensify capital requirements for analytical infrastructure, advantaging incumbent manufacturers with established regulatory affairs teams over new market entrants. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional green chemistry mandates that could redirect process chemistry investments toward enzymatic or solvent-reduced esterification routes.
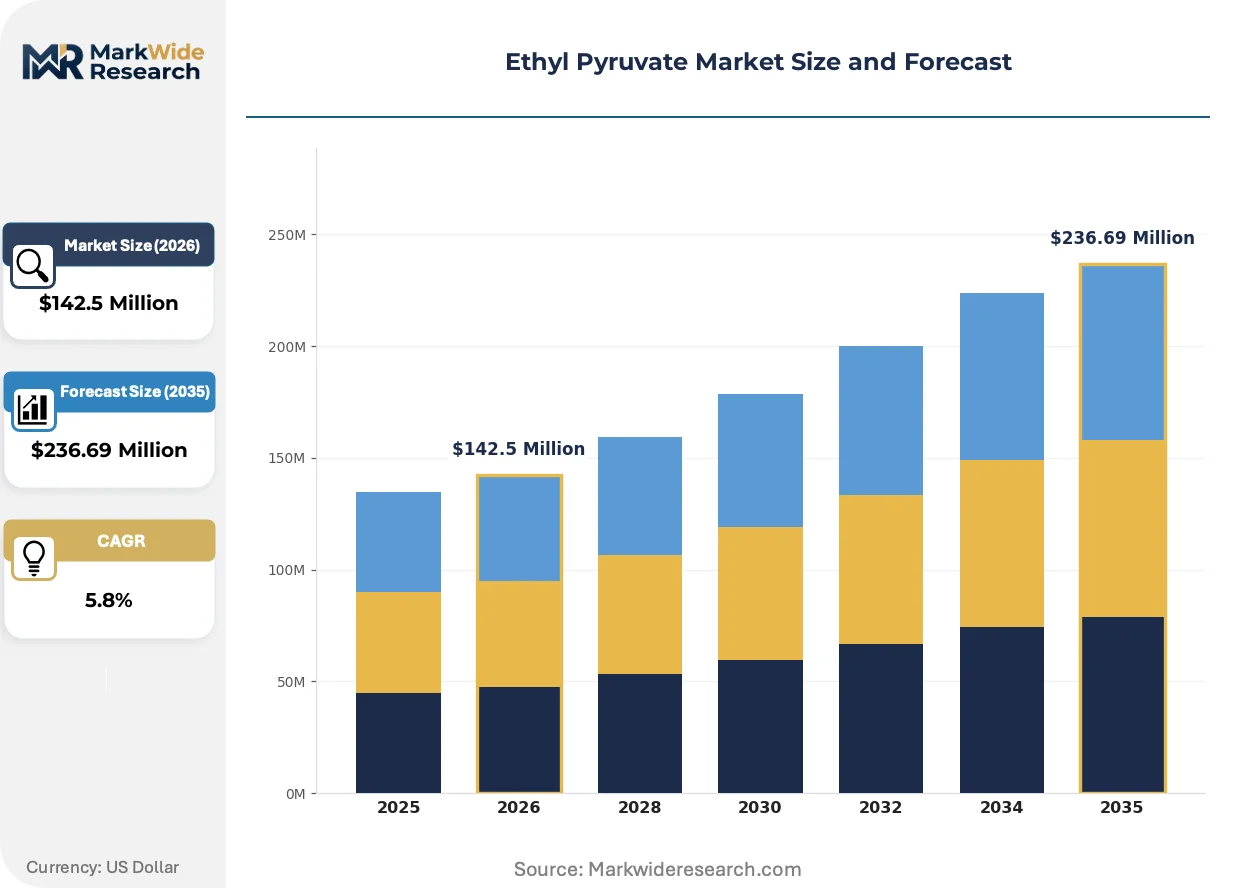
Market Dynamics
Pharmaceutical fine chemical buyers are consolidating supplier lists around vendors with integrated GMP documentation capabilities, compressing procurement channels for clinical-grade ethyl pyruvate as audit intensity rises.
Growth Catalysts
- REACH substance registration:European regulatory compliance requirements filter non-compliant producers from pharmaceutical qualification lists, concentrating demand among certified manufacturers.
- Cell culture additive demand:Biopharmaceutical manufacturers expand ethyl pyruvate procurement for serum-free media formulations supporting monoclonal antibody production.
- China and India:Domestic fine chemical producers scale pyruvate derivative output to serve regional pharmaceutical supply chains, reducing import dependency.
Market Restraints
- Pyruvic acid feedstock volatility:Fermentation-derived pyruvic acid supply fluctuates with agricultural commodity pricing, compressing esterification margins.
- European supply concentration:REACH-compliant manufacturing clusters concentrate in Germany and Switzerland, creating geographic vulnerability for qualified material.
- Acetone diacetone alcohol substitution:Alternative reactive intermediates displace ethyl pyruvate in select flavoring applications where purity requirements are less stringent.
Strategic Opportunities
- Cosmetics antioxidant claims:Formulators incorporate ethyl pyruvate into skin care products targeting oxidative stress protection, opening non-pharmaceutical volume channels.
- Enzymatic esterification:Lipase-catalyzed production routes reduce solvent intensity and align with EU Green Deal process chemistry mandates.
- Laboratory-scale distribution:Catalog chemical suppliers capture emerging biotechnology research demand through gram-scale packaging and rapid fulfillment.
Industry Challenges
- ISO 10993 biocompatibility certification:Medical device-grade material requires extended cytotoxicity and sensitization testing timelines, delaying vendor qualification.
- Analytical infrastructure capex:GMP-compliant manufacturers must deploy LC-MS and NMR systems for impurity profiling, raising capital barriers for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Pyruvate Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Solution Application: Pharmaceuticals, Food & Beverage, Cosmetics, Nutraceuticals End User: Manufacturers, Research Institutions, Hospitals, Clinics Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Merck KGaA, Sigma-Aldrich, Tokyo Chemical Industry, Alfa Aesar, Arkema, Cayman Chemical Company, Acros Organics, BASF, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Pyruvate Market Trends and Innovations
Process intensification and regulatory documentation automation are restructuring how ethyl pyruvate manufacturers compete on speed-to-qualification rather than unit cost alone.
Continuous flow esterification technology is modularizing pyruvic acid conversion, replacing batch reactors with microchannel systems that pharmaceutical contract manufacturers adopt for tighter residence time control and reduced solvent inventory. This architecture compresses validation documentation for multi-product facilities.
EMA's evolving excipient guidelines and FDA's Inactive Ingredient Database updates are tightening impurity specification thresholds, forcing suppliers to invest in dedicated pharmaceutical-grade production lines separate from flavor and industrial material. European manufacturers bear the heaviest analytical burden as pharmacopeial monograph revisions outpace other regions.
Multi-year supply agreements with locked pricing are displacing spot purchasing in pharmaceutical procurement, as Merck KGaA and Tokyo Chemical Industry anchor preferred supplier status through integrated quality systems. This consolidation concentrates volume among documented vendors and marginalizes traders in qualified channels, with the shift most visible in North American biopharmaceutical buying patterns.
Ethyl Pyruvate Market Segmentation
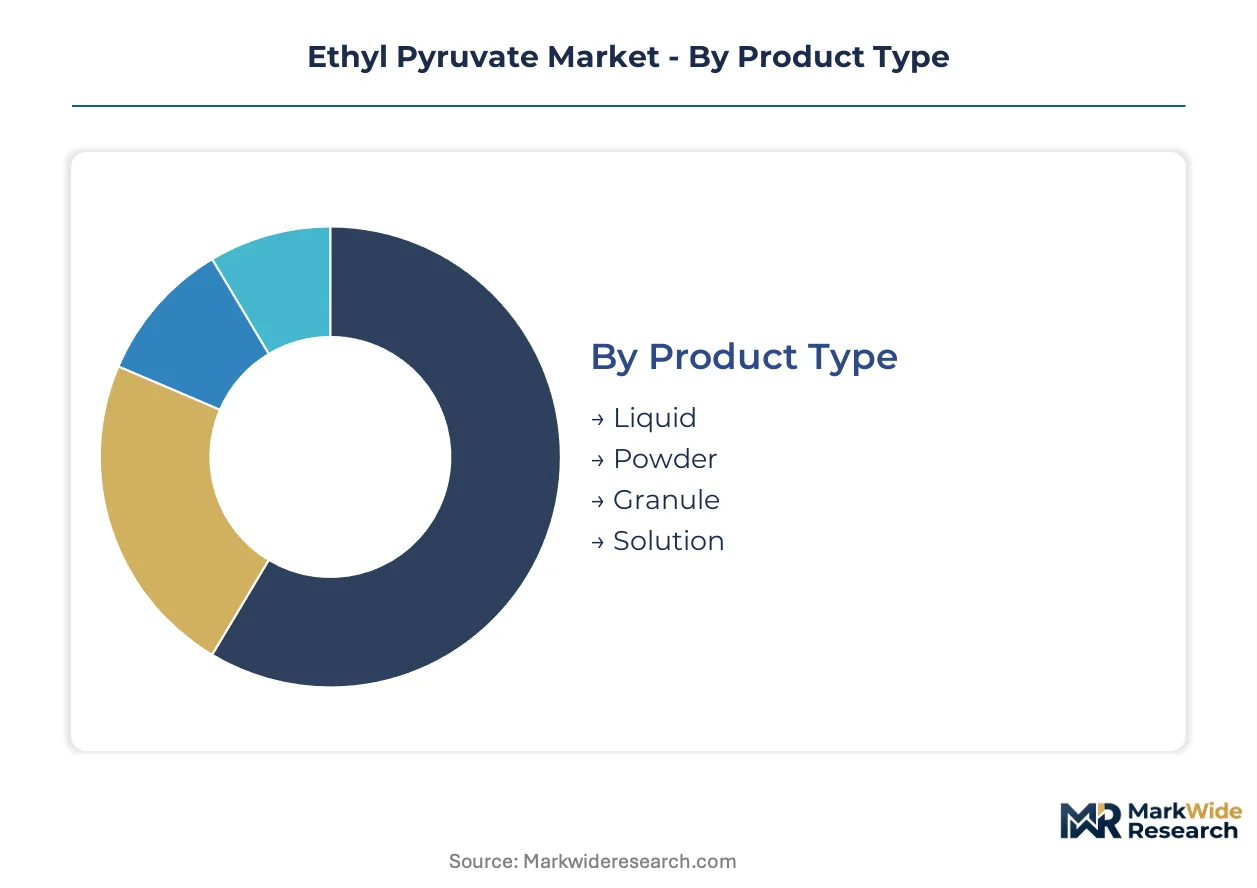
Ethyl pyruvate procurement patterns diverge sharply across physical formats and end-use specifications, with pharmaceutical-grade liquid commanding premium positioning against industrial-grade alternatives. Segmentation discipline separates margin-rich clinical applications from commodity flavoring volumes.
Product Type:
Liquid-grade supply concentrates among German and Swiss GMP-certified manufacturers with captive pyruvic acid feedstock and dedicated pharmaceutical filling lines.
- Liquid:Colorless ester solution meeting USP-NF and EP monograph specifications for parenteral formulation compatibility. Demand clusters in monoclonal antibody media production at Boston and Basel biomanufacturing hubs, where automated dispensing systems require pumpable viscosity profiles.
- Powder:Spray-dried crystalline material with controlled particle size distribution for direct compression tableting. Nutraceutical contract manufacturers in Gujarat and Shandong provinces drive procurement for shelf-stable antioxidant formulations with extended stability data requirements.
- Granule:Agglomerated powder with improved flow properties for high-speed encapsulation lines.
- Solution:Pre-diluted aqueous preparations for laboratory-scale cell culture workflows.
Today's leader: Liquid. Tomorrow's challenger: Powder.
Application:
Cost tier differentiation separates audit-intensive pharmaceutical qualification from cosmetics volume plays with lighter documentation burdens.
- Pharmaceuticals:Reactive intermediate for active pharmaceutical ingredient synthesis and certified cell culture additive for serum-free media. FDA Inactive Ingredient Database listings and EMA excipient master file submissions create multi-year vendor lock-in with integrated quality systems at Merck KGaA and Tokyo Chemical Industry.
- Cosmetics:Antioxidant active in oxidative stress protection claims for premium skin care. Formulators in Seoul and Milan incorporate ethyl pyruvate at sub-percentage levels for label differentiation in crowded cosmeceutical markets.
- Food & Beverage:Synthetic flavoring agent with FEMA GRAS status for fruity note enhancement in beverage applications.
- Nutraceuticals:Metabolic support ingredient in sports nutrition and mitochondrial health supplements.
Pharmaceuticals commands margin. Cosmetics climbs fastest.
End User:
Customer type determines packaging scale and documentation depth, from gram-scale research shipments to multi-ton pharmaceutical raw material orders.
- Manufacturers:Fine chemical and finished dosage form producers with validated supply chain qualification protocols.
- Research Institutions:University and biotechnology laboratory buyers prioritizing rapid fulfillment and certificate of analysis availability over volume pricing.
- Hospitals:Compounding pharmacy operations seeking USP-grade material for personalized medicine formulations.
- Clinics:Specialized regenerative medicine centers sourcing for autologous cell therapy processing.
Manufacturers dominate volume. Research institutions expand fastest.
Distribution Channel:
Volume flows through direct sales for qualified pharmaceutical accounts, while catalog distributors capture fragmented research demand.
- Direct Sales:Multi-year supply agreements with locked pricing and dedicated quality liaison support for top-tier pharmaceutical manufacturers.
- Distributors:Regional chemical distributors with local warehousing for mid-scale nutraceutical and cosmetics compounders.
- Online:E-commerce platforms serving research institutions with credit-card purchasing and next-day delivery options.
- Offline:Traditional trade counter and field sales relationships for established industrial accounts.
Direct sales anchors value. Online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel and Boston biomanufacturing clusters anchor pharmaceutical-grade ethyl pyruvate procurement through their monoclonal antibody production networks. Regulatory divergence across major economies is fragmenting supplier qualification pathways and concentrating volume among documented vendors.
United States
FDA Inactive Ingredient Database listings and evolving excipient guidelines drive pharmaceutical manufacturer consolidation around pre-qualified suppliers. The agency's tightened impurity specifications compress procurement channels for clinical-grade material. Greater Boston's contract manufacturing organizations anchor North American demand through multi-year supply agreements with locked pricing.
Germany
REACH substance registration and EMA excipient master file requirements filter non-compliant producers from pharmaceutical qualification lists. The country's national chemical regulator enforces analytical documentation standards that advantage incumbent manufacturers with established regulatory affairs teams. Ludwigshafen and Leverkusen industrial clusters sustain captive acetaldehyde feedstock access for integrated esterification operations.
Switzerland
Swissmedic certification for medical device-grade material extends cytotoxicity testing timelines and delays vendor qualification. The Basel biopharmaceutical corridor concentrates demand for GMP-certified liquid-grade supply compatible with automated formulation systems. Regional manufacturers deploy dedicated pharmaceutical filling lines separate from flavor and industrial material.
China
Domestic fine chemical producers scale pyruvate derivative output to serve regional pharmaceutical supply chains and reduce import dependency. NMPA alignment with ICH Q3D guidelines elevates elemental impurity controls for excipient-grade material. Shandong province's nutraceutical contract manufacturers drive powder-format procurement for shelf-stable antioxidant formulations.
India
CDSCO's phased implementation of ICH Q7 GMP guidelines for active pharmaceutical ingredients tightens documentation requirements for imported raw materials. Gujarat's fine chemical sector expands esterification capacity to capture regional pharmaceutical outsourcing. Domestic producers leverage fermentation-derived pyruvic acid supply chains subject to agricultural commodity pricing volatility.
Ethyl Pyruvate Market Competitive Landscape
Global majors compete with regional champions across documentation capabilities and feedstock integration. The vendor base stratifies between integrated life sciences platforms controlling quality systems from raw pyruvate through final esterification, and catalog-scale distributors capturing fragmented research demand. Three archetypes dominate: GMP-certified pharmaceutical specialists, laboratory chemical suppliers with rapid fulfillment infrastructure, and industrial-scale esterification houses with captive feedstock positions. Capacity expansion and strategic partnerships represent the dominant competitive moves as audit intensity rises.
Among integrated life sciences platforms, Merck KGaA and Tokyo Chemical Industry exemplify the documentation-intensive tier anchoring preferred supplier status through multi-year agreements. BASF occupies a position among industrial-scale producers leveraging captive acetaldehyde access for European contract manufacturing competitiveness. Cayman Chemical Company represents the specialist archetype serving research institutions with gram-scale packaging and certificate of analysis availability.
| Leading Market Players |
|---|
| Merck KGaA |
| Sigma-Aldrich |
| Tokyo Chemical Industry |
| Alfa Aesar |
| Arkema |
| Cayman Chemical Company |
| Acros Organics |
| BASF |
| Toray Industries |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical manufacturer consolidation around GMP-certified suppliers concentrates procurement power among documented vendors, forcing supply-side investment in analytical infrastructure and dedicated pharmaceutical-grade production lines that elevate pricing floors for clinical-grade material.
Pricing Analysis
Fermentation-derived pyruvic acid feedstock costs pass through directly to ethyl pyruvate esterification margins, creating commodity-linked volatility in base chemical pricing. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and industrial-grade levels separates audit-intensive qualification premiums from flavor-application spot markets. Cost compression in industrial-grade tiers reflects acetone diacetone alcohol substitution pressure. Research institutions show highest price sensitivity due to budget constraints and catalog-scale purchasing, while biopharmaceutical manufacturers prioritize documentation reliability over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle multi-ton contract volumes with locked pricing and dedicated quality liaison support, while catalog distributors capture fragmented gram-scale research demand. Production concentrates in Germany, Switzerland, and China, with German and Swiss facilities anchoring REACH-compliant pharmaceutical supply. Pyruvic acid fermentation feedstock, ethanol solvent, and acetaldehyde co-feedstock constitute critical input dependencies. Single-source vulnerability runs through fermentation-derived pyruvic acid supply exposed to agricultural commodity pricing swings. Distribution runs through integrated life sciences platforms with captive quality documentation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethyl pyruvate operates as a regulatory compounder where EMA excipient master file requirements and FDA Inactive Ingredient Database listings create multi-year vendor lock-in and concentrate demand among pre-qualified suppliers.
For Market Incumbents: Deepen pharmaceutical-grade production line separation from industrial material to defend margin position against acetone diacetone alcohol substitution in flavor applications. Invest in continuous flow esterification technology to compress validation documentation timelines for multi-product facilities. Prioritize enzymatic process chemistry R&D to align with EU Green Deal mandates and preempt regulatory preference shifts. For New Entrants and Emerging Players: REACH substance registration in Europe opens a window for mid-scale Indian and Chinese producers to capture regional pharmaceutical outsourcing demand as CDSCO and NMPA align with ICH guidelines. Target cosmetics antioxidant applications in Seoul and Milan where documentation burdens remain lighter than pharmaceutical qualification. Lead with laboratory-scale distribution partnerships offering rapid fulfillment and certificate of analysis availability. For Investors and Strategic Acquirers: Asymmetric upside sits with GMP-certified pharmaceutical specialists with established regulatory affairs teams and integrated quality systems from raw pyruvate through final esterification. Five-to-ten year viability hinges on pharmacopeial monograph revision tracking and green chemistry mandate compliance. Monitor EMA and FDA excipient guideline updates as inflection indicators for process chemistry investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyruvic Acid | Captive fermentation capacity insulates BASF and Merck KGaA from agricultural commodity pricing volatility. |
| Enzymatic Esterification Scale-Up | Lipase-catalyzed routes reduce solvent intensity and align Toray Industries with EU Green Deal mandates. |
| Pharmaceutical-Grade Line Separation | Dedicated filling lines at Swiss facilities satisfy Swissmedic certification for medical device-grade material. |
| Multi-Year Supply Agreements | Locked pricing contracts with Boston CMOs anchor Tokyo Chemical Industry's preferred supplier status. |
| Laboratory-Scale Distribution Expansion | Gram-scale packaging and rapid fulfillment capture Cayman Chemical Company's biotechnology research demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement managers, fine chemical plant managers, regulatory affairs directors, and cosmetics formulators with secondary validation from FDA Inactive Ingredient Database listings, EMA excipient master file submissions, REACH substance registrations, and customs trade data. Bottom-up demand modeling across end-use segments triangulated against top-down supply-side capacity assessments.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical reactive intermediates, cell culture additives, cosmetics antioxidants, and flavoring applications. Modeled dimensions included physical format, grade certification tier, end-use industry, and regional regulatory cluster. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated pyruvic acid feedstock pricing indices and biopharmaceutical manufacturing capacity expansion announcements.
Revisions become necessary when pharmacopeial monograph revisions, green chemistry mandate implementations, or fermentation feedstock supply disruptions materialize beyond modeled scenarios. Forecasts reflect documented assumptions about regulatory alignment timelines and substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Ink Solvents Market
Solvents
Sugar Dissolvers Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Reactive Diluents Market
Solvents
Benzene and Its Derivatives Market
Solvents
Methyl Formate Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Global Tert-Butanol Market
Solvents
Global Xylenols Market
Solvents
Isopropylamine Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Butane Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Piperylene Market