
 Industrial Solvents Market | 2026-2036
Industrial Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Solvents Market Analysis
Germany's chemical corridor expansion is reshaping regional supply dynamics for oxygenated and aromatic solvent grades. BASF SE leverages integrated Ludwigshafen manufacturing complexes to sustain cost advantages across ester and ketone product lines. Eastman Chemical Company anchors North American supply through Kingsport, Tennessee specialty solvent operations. INEOS competes aggressively in European aromatic hydrocarbons through its Cologne-Rotterdam pipeline network.
Industrial solvents are liquid organic compounds with defined volatility parameters, typically exhibiting boiling points between 60°C and 200°C, engineered to dissolve, suspend, or extract other substances without chemically altering them. These formulations serve as process enablers across manufacturing stages including surface preparation, coating application, and precision cleaning. Alcohol solvents dominate volume consumption in pharmaceutical and personal care applications where residual toxicity thresholds are stringent. Ketone categories represent the fastest-expanding margin pool, driven by aerospace adhesive formulations and high-performance coating systems. Aromatic hydrocarbon segments face structural compression in Western Europe as REACH authorization requirements tighten benzene and toluene exposure limits.
EPA hazardous air pollutant standards under NESHAP and OSHA permissible exposure limits directly constrain chlorinated solvent use in metal degreasing operations. EMA pharmaceutical manufacturing guidelines and FDA current good manufacturing practice standards dictate residual solvent thresholds in drug substance purification, creating specification premiums for high-purity grades. Stakeholders must monitor regulatory divergence between EPA risk evaluations and ECHA sunset date timelines, as misaligned phase-out schedules will fragment supply chain planning across Atlantic markets.
Market Dynamics
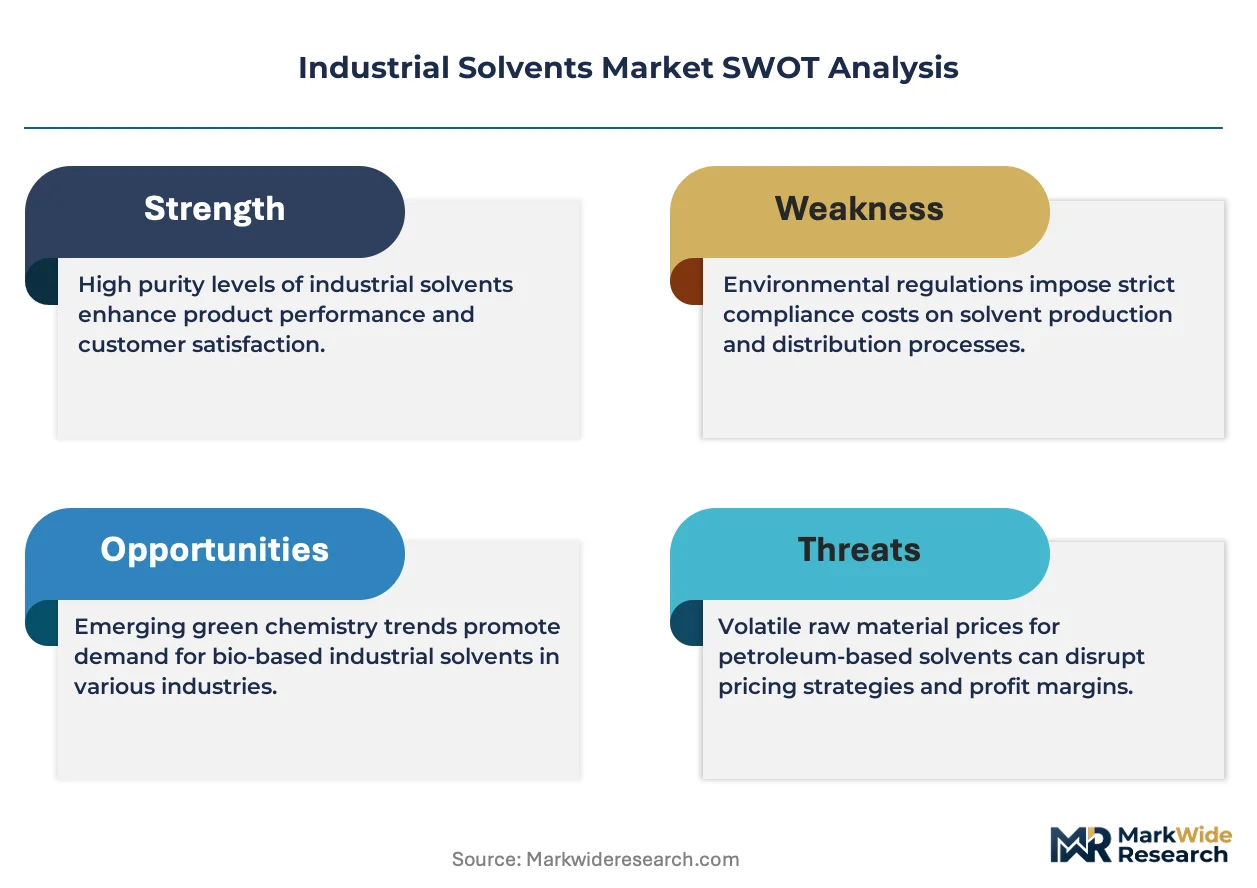
REACH authorization timelines and EPA risk evaluations are creating asynchronous phase-out schedules that fragment supply chain planning across Atlantic markets, forcing solvent users to maintain dual-qualified material streams.
Growth Catalysts
- Pharmaceutical extraction demand:Active ingredient purification processes in drug manufacturing are expanding consumption of high-purity alcohol and ester solvents. FDA cGMP standards for residual solvent thresholds create specification premiums that reward qualified suppliers.
- EU Green Deal bio-based mandates:Renewable solvent formulations gain competitive positioning through preferential procurement criteria in public tenders and corporate sustainability frameworks.
- Aerospace adhesive specifications:Ketone solvents meet performance requirements for high-temperature bonding applications in composite airframe assembly, with demand concentrating around Toulouse and Hamburg manufacturing clusters.
Market Restraints
- Feedstock volatility:Propylene and benzene derivative costs fluctuate with crude oil refining margins, compressing formulation economics for aromatic hydrocarbon producers.
- Chlorinated solvent phase-downs:NESHAP hazardous air pollutant standards constrain trichloroethylene and perchloroethylene use in metal degreasing, eliminating established process chemistries without drop-in replacements.
- Specialty grade supply concentration:Pharmaceutical-grade solvent purification capacity clusters in Germany's Ludwigshafen and Belgium's Antwerp corridor, creating geographic single-source risk for qualified material.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-aligned facilities in Hyderabad and Ahmedabad are scaling active pharmaceutical ingredient production, creating demand for USP-grade solvent supply with localized technical service.
- Electronics cleaning precision requirements:Semiconductor fabrication nodes below 7nm require ultra-high-purity oxygenated solvents for photoresist stripping and wafer cleaning processes.
- Carbon border adjustment mechanism:EU CBAM implementation creates competitive advantage for bio-based solvent producers with verified lifecycle emissions data against imported fossil-derived alternatives.
Industry Challenges
- Cross-qualified chemist scarcity:Formulation scientists capable of navigating both REACH registration dossiers and FDA drug master file requirements command premium compensation, constraining R&D scaling.
- Legacy equipment incompatibility:Bio-based solvent alternatives often exhibit different polarity parameters and evaporation profiles, requiring capital-intensive process revalidation for coating and cleaning lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Solvents Market |
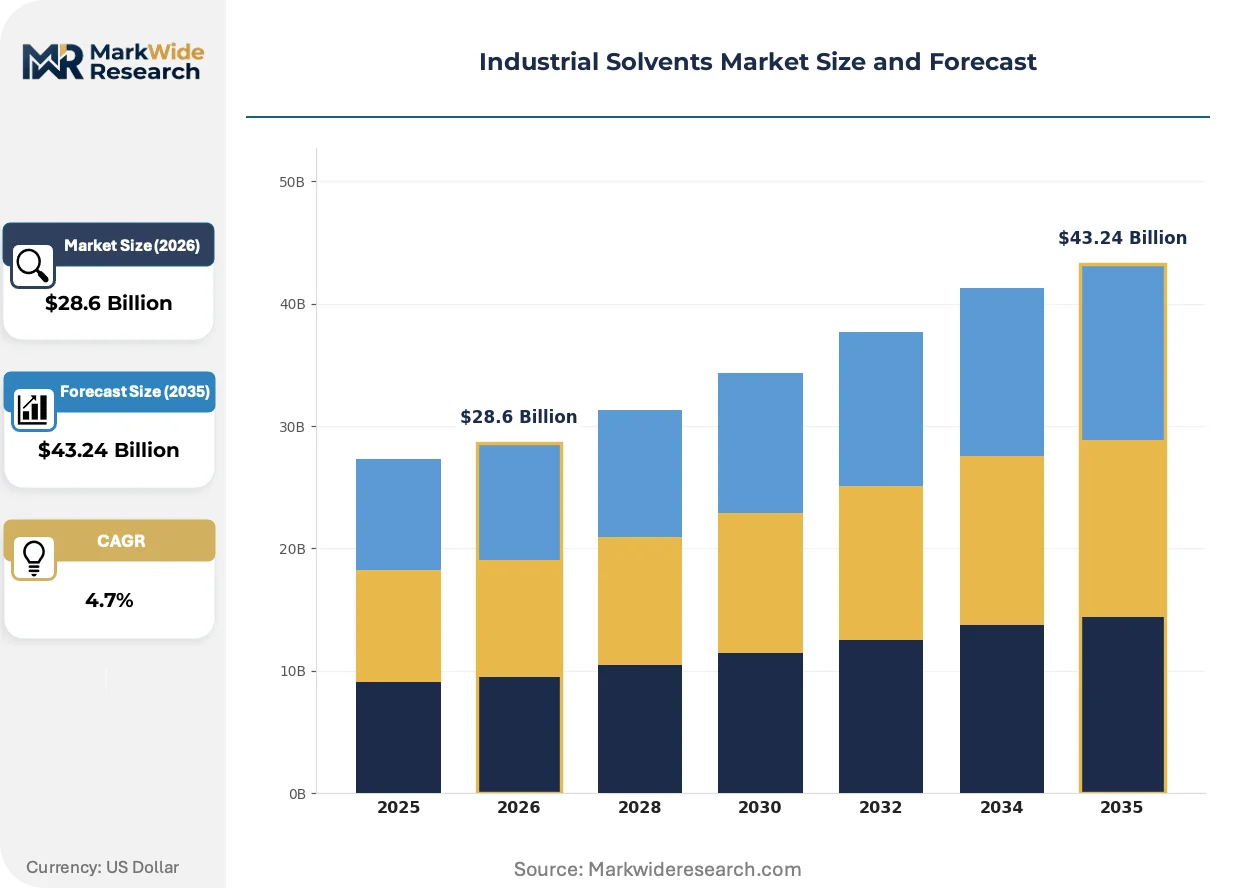
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Ketones, Esters, Aromatic Hydrocarbons Application: Paints, Coatings, Adhesives, Cleaners End User: Manufacturing, Automotive, Construction, Aerospace Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | LyondellBasell Industries, Honeywell International Inc., BASF SE, Eastman Chemical Company, INEOS, Shell plc, Arkema, Celanese Corporation, ExxonMobil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Solvents Market Emerging Trajectories
Deep eutectic solvents and switchable hydrophilicity systems are collapsing traditional boundaries between extraction efficiency and environmental compliance, enabling water-free process chemistries that bypass wastewater treatment infrastructure.
Supercritical carbon dioxide extraction technology is collapsing conventional solvent-based separation economics in natural product processing. Botanical extract manufacturers in Switzerland and Italy are adopting scCO2 systems to eliminate hexane residual concerns. The technology is collapsing demand for conventional hydrocarbon extraction solvents in high-value fragrance and nutraceutical applications.
EPA's revised risk determination for 1-bromopropane under TSCA Section 6 is accelerating substitution timelines for vapor degreasing applications. Metal finishing operations face compressed compliance windows as the agency finalizes workplace exposure restrictions. Aqueous and modified alcohol cleaning systems are capturing specification share in aerospace component manufacturing facilities across Michigan and Ohio.
Specification consolidation among pharmaceutical contract manufacturers is compressing approved supplier lists for excipient-grade solvents. Large CDMOs in Ireland and Singapore now mandate single-source qualification for multi-site supply security. This concentration is forcing regional distributors to invest in dedicated pharmaceutical warehousing and temperature-controlled logistics capabilities to retain material access.
Industrial Solvents Market Segmentation
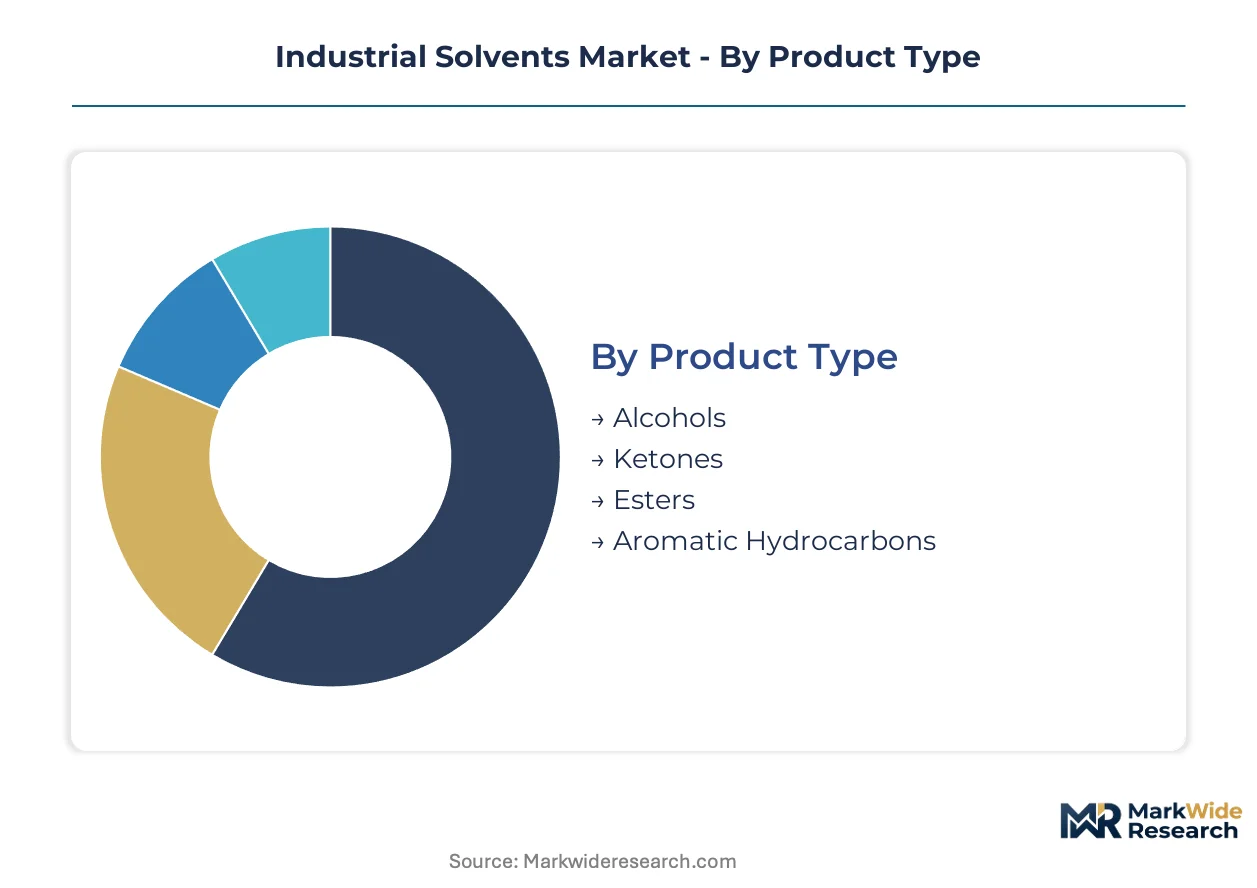
Solvent purchasing cycles vary dramatically across product categories, with commodity alcohols turning over monthly while specialty esters for pharmaceutical applications carry qualification periods exceeding eighteen months. Understanding these velocity differentials enables suppliers to calibrate inventory positions and working capital deployment against margin capture opportunities.
Product Type:
Alcohol solvents rotate inventory fastest due to standardized specifications and broad substitution elasticity, while ketone grades for aerospace adhesives exhibit extended procurement cycles tied to customer qualification protocols.
- Alcohols:These oxygenated solvents exhibit boiling points typically ranging from 60°C to 150°C with hydroxyl functional groups enabling hydrogen bonding for polar substrate dissolution. Pharmaceutical manufacturers in Germany's Ludwigshafen corridor consume ethanol and isopropanol grades under FDA cGMP residual solvent thresholds, with qualification requirements extending procurement lead times despite volume scale.
- Ketones:Characterized by carbonyl functionality and intermediate polarity parameters between alcohols and hydrocarbons, these solvents enable high-solids coating formulations with controlled evaporation profiles. Toulouse and Hamburg aerospace clusters specify methyl ethyl ketone and methyl isobutyl ketone for composite airframe bonding applications, with Airbus tier-one suppliers maintaining dual-source qualification to mitigate supply disruption risk.
- Esters:Formed from carboxylic acid-alcohol condensation, these solvents deliver superior resin solvency for high-performance coatings with reduced photochemical reactivity versus ketones.
- Aromatic Hydrocarbons:Benzene-ring structures provide non-polar solvency for hydrocarbon resins, though REACH authorization timelines are compressing toluene and xylene applications in Western Europe.
Alcohols anchor the volume base while ketones gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity coating formulations from precision cleaning specifications, with price premiums expanding across aerospace and electronics-grade requirements.
- Paints:Architectural and industrial coating systems utilize oxygenated and hydrocarbon solvents to control viscosity, flow, and film formation kinetics. Construction activity in Germany's chemical corridor sustains bulk ester and alcohol consumption, though waterborne technology displacement is compressing solvent-borne volume growth in residential applications.
- Coatings:Protective and decorative film-forming systems for metal, wood, and plastic substrates require precise solvent blends to achieve target solids content and application viscosity. Automotive OEM coating lines in Stuttgart and Wolfsburg mandate low-VOC reformulations under EU solvent emission directives, forcing reformulation investment across supplier bases.
- Adhesives:Bonding systems for structural and assembly applications rely on ketone and ester solvents to dissolve thermoplastic and elastomeric components.
- Cleaners:Degreasing and precision cleaning formulations face regulatory pressure from EPA NESHAP standards and REACH authorization requirements for chlorinated and aromatic chemistries.
Paints and coatings concentrate revenue contribution while cleaners expand most quickly under semiconductor and medical device precision requirements.
End User:
Customer scale and specification intensity stratify solvent procurement, with pharmaceutical-grade requirements commanding tenfold premiums over industrial commodity grades.
- Manufacturing:General industrial processing spans metal fabrication, plastics forming, and chemical synthesis with broad solvent applicability and price-sensitive procurement. Electronics contract manufacturers in Bavaria and Baden-Württemberg are scaling ultra-high-purity oxygenated solvent consumption for semiconductor substrate cleaning, with node shrinkage below 7nm tightening residual metallic impurity specifications.
- Automotive:OEM and tier supplier coating, adhesive, and cleaning operations drive ketone and ester demand with stringent VOC emission compliance requirements. Paint shop operations at BMW Munich and Mercedes Sindelfingen facilities operate under TA Luft technical instructions, with solvent recovery systems capturing 95-plus percent of emissions for thermal oxidation.
- Construction:Architectural coatings and adhesives represent high-volume, specification-tolerant consumption with pronounced cyclicality tied to residential and commercial building permits.
- Aerospace:Composite bonding and precision cleaning applications demand qualified solvent grades with full material traceability and batch certification.
Manufacturing anchors the volume base while aerospace gains share at the steepest rate.
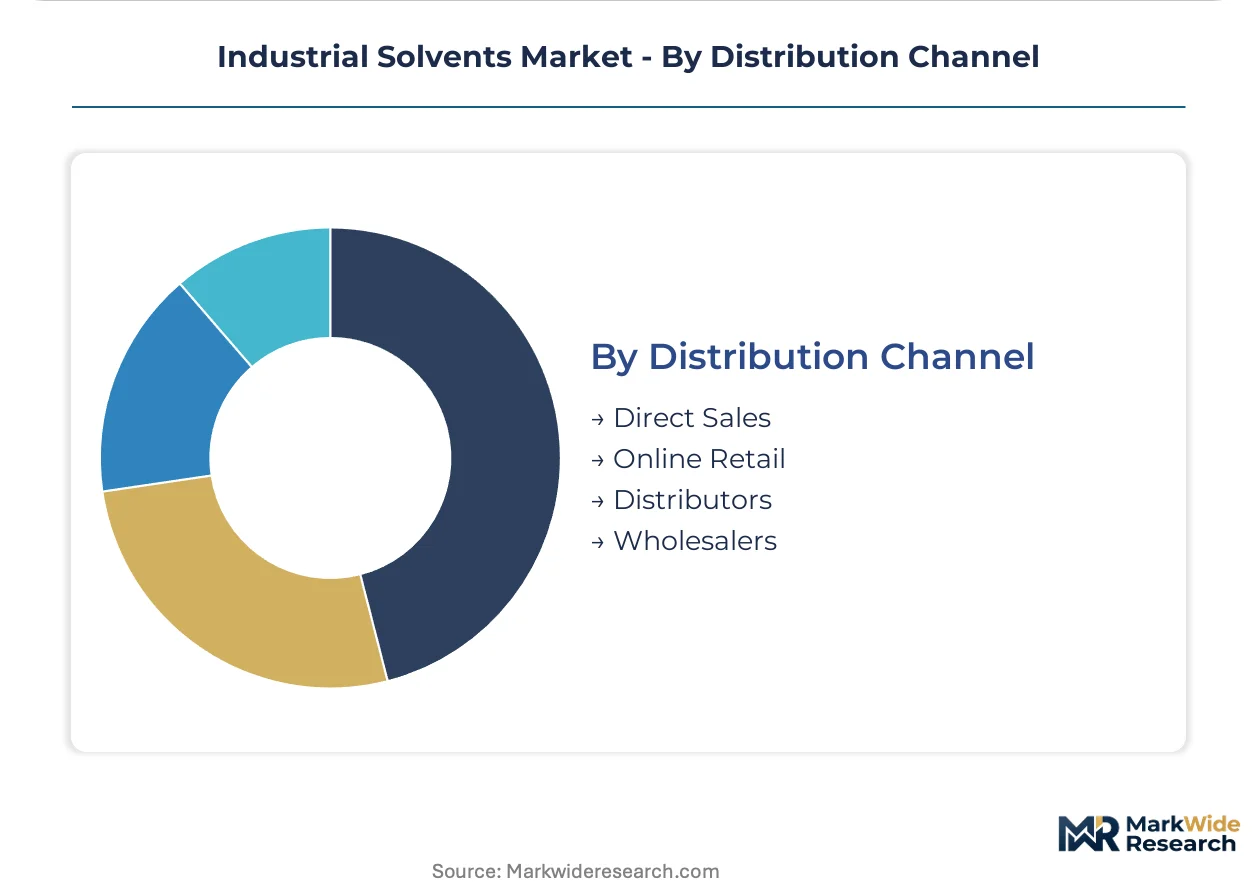
Distribution Channel:
Supply chain configuration separates direct mill-to-plant relationships for high-volume commodity solvents from distributor-mediated access for specialty grades requiring technical service support.
- Direct Sales:Producer-to-customer relationships dominate bulk alcohol and aromatic hydrocarbon movements for large coating and chemical manufacturing accounts. BASF Ludwigshafen complexes deliver tank-car quantities to adjacent chemical processors, with pipeline connections eliminating packaging and handling costs for captive consumption within the Verbund site.
- Distributors:Regional chemical distributors provide blending, repackaging, and technical service for mid-volume customers lacking direct producer relationships. Pharmaceutical solvent distributors in Belgium's Antwerp port zone maintain temperature-controlled warehousing and GDP-compliant logistics for excipient-grade material serving CDMO facilities in Ireland and the Netherlands.
- Online Retail:E-commerce platforms capture small-laboratory and maintenance-repair-operating demand with rapid fulfillment and certificate-of-analysis documentation.
- Wholesalers:Bulk intermediaries aggregate demand across smaller accounts for standardized solvent grades with limited specification differentiation.
Direct sales anchor the volume base while distributor channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization timelines in Germany anchor European regulatory gravity for solvent formulations. FDA cGMP standards in the United States and CDSCO alignment requirements in India fragment compliance architectures across Atlantic and Asian manufacturing corridors.
Germany
Pharmaceutical-grade solvent purification concentrates in the Ludwigshafen-Antwerp corridor where BASF SE operates integrated manufacturing complexes. EU Green Deal bio-based procurement criteria accelerate renewable formulation adoption in public tenders. The Rhine-Neckar metropolitan region sustains specialty ester production for electronics and aerospace end-users.
United States
EPA NESHAP hazardous air pollutant standards constrain chlorinated solvent use in Michigan and Ohio metal degreasing operations. OSHA permissible exposure limits for 1-bromopropane accelerate aqueous cleaning system substitution in aerospace component manufacturing. Kingsport, Tennessee anchors North American specialty solvent supply through integrated chemical processing infrastructure.
India
CDSCO-aligned pharmaceutical manufacturing facilities in Hyderabad and Ahmedabad scale active ingredient production requiring USP-grade solvent supply. The country's national pharmaceutical regulator tightens residual solvent thresholds for export-oriented drug substance purification. Gujarat's chemical manufacturing belt attracts technical service investments from regional distributors seeking localized excipient-grade logistics.
China
Semiconductor fabrication expansion below 7nm nodes in the Yangtze River Delta drives ultra-high-purity oxygenated solvent consumption for photoresist stripping. MIIT industrial standards for electronics-grade chemicals tighten metallic impurity specifications beyond ISO baseline requirements. Shanghai's Pudong district concentrates solvent recovery system deployment for coating and cleaning process emissions compliance.
France
Toulouse aerospace manufacturing clusters specify ketone solvents for composite airframe bonding applications under Airbus tier-one supplier protocols. ANSM pharmaceutical manufacturing guidelines align with EMA residual solvent thresholds for drug substance purification. The Occitanie region sustains demand for high-performance adhesive formulations serving satellite and defense contractor operations.
Industrial Solvents Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing backward control over feedstock supply; scale advantage sits with regional distributors maintaining temperature-controlled logistics networks for pharmaceutical-grade material. The vendor base stratifies across three tiers: multinational chemical conglomerates with Verbund manufacturing sites, mid-cap specialty producers focused on ester and ketone formulations, and regional blenders serving coating and cleaning end-users with rapid fulfillment. Dominant competitive moves include capacity expansion in Germany's chemical corridor and strategic partnerships between solvent producers and pharmaceutical CDMOs for multi-site qualification.
Among European-integrated majors, BASF SE and INEOS occupy positions exemplifying feedstock-advantaged manufacturing architectures. Eastman Chemical Company anchors North American specialty supply through Tennessee-based operations. These three entities represent divergent strategic archetypes: the German conglomerate leverages pipeline-connected Verbund sites, the British-Dutch partnership controls aromatic hydrocarbon distribution through Rotterdam-Antwerp infrastructure, and the US producer concentrates on high-margin ketone and ester formulations for aerospace and pharmaceutical applications.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Honeywell International Inc. |
| BASF SE |
| Eastman Chemical Company |
| INEOS |
| Shell plc |
| Arkema |
| Celanese Corporation |
| ExxonMobil |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Germany's Ludwigshafen-Antwerp corridor for pharmaceutical-grade solvent purification determines both extreme pricing tier spreads and supply chain configuration across Atlantic markets. REACH authorization timelines and FDA cGMP residual solvent thresholds fragment procurement economics, forcing buyers to absorb qualification premiums or risk supply disruption.
Pricing Analysis
Geographic price spreads between Germany's chemical corridor and Indian pharmaceutical manufacturing zones exceed threefold for USP-grade ester solvents. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cGMP certified pharmaceutical grades from industrial coating specifications and commodity solvent blends. Cost compression in aromatic hydrocarbon segments is intensifying because REACH sunset dates accelerate substitution timelines. Volume-scale manufacturing buyers exhibit highest price sensitivity, while aerospace adhesive formulators accept specification premiums for qualified ketone grades.
Supply Chain Analysis
Extended payment terms from German integrated producers to downstream pharmaceutical CDMOs stabilize working capital across qualification-intensive procurement cycles. Manufacturing gravity centers on Germany, Belgium, and the United States for high-purity oxygenated and ester solvent production. Feedstock supply draws from propylene derivative streams and bio-based fermentation pathways. Single-source vulnerability concentrates in Ludwigshafen-Antwerp pharmaceutical purification capacity. Distribution runs through direct mill-to-plant relationships for bulk commodities and temperature-controlled distributor networks for excipient-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical carbon dioxide extraction technology is collapsing conventional solvent-based separation economics in natural product processing, creating structural displacement risk for hydrocarbon extraction solvents across fragrance and nutraceutical applications.
For Market Incumbents: Pre-empt supercritical CO2 substitution in high-value botanical extraction by securing backward integration into bio-based feedstock supply and expanding pharmaceutical-grade purification capacity in India. Defend ketone solvent margins through aerospace adhesive qualification lock-in at Toulouse and Hamburg manufacturing clusters. For New Entrants and Emerging Players: India's pharmaceutical manufacturing corridor offers the most penetrable white-space for USP-grade solvent supply with localized technical service. Target CDSCO-aligned API producers in Hyderabad and Ahmedabad with dedicated excipient-grade logistics capabilities. Differentiate through carbon footprint verification for EU CBAM-compliant bio-based formulations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with captive feedstock supply and multi-regional qualification infrastructure. Long-term viability rests on regulatory navigation capabilities spanning REACH registration dossiers and FDA drug master file requirements. Watch for divergence between EPA risk evaluation timelines and ECHA sunset dates as inflection signal for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | BASF SE's Ludwigshafen Verbund complex additions strengthen pharmaceutical-grade ester supply security for European CDMOs. |
| Backward Integration | Captive bio-based feedstock production insulates margins from propylene and benzene derivative cost volatility. |
| Green Manufacturing Transition | EU Green Deal procurement criteria reward renewable solvent formulations with preferential public tender access. |
| Long-term Supply Agreement | Multi-site qualification partnerships between solvent producers and pharmaceutical CDMOs reduce geographic single-source risk. |
| Joint Venture | Regional distribution alliances in India's Gujarat chemical belt enable localized USP-grade logistics for export-oriented API production. |
Methodological Framework
Operator-level perspectives from plant managers at integrated chemical complexes, procurement leads at pharmaceutical CDMOs, distribution channel partners, and technical R&D directors anchored the qualitative base. Secondary validation drew from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up volume modeling and top-down market sizing triangulation ensured cross-verification across estimation approaches.
Scenario-bracketing around regulatory phase-out timelines and feedstock cost trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include solvent grade tier, end-use industry application, packaging format, and regional production hub. CAGRs were derived from trend extrapolation against historical substitution patterns and capacity expansion announcements. Forecast inputs incorporated REACH authorization sunset schedules and semiconductor node shrinkage specifications for ultra-high-purity requirements.
Practitioners should monitor EPA risk evaluation finalizations and ECHA sunset date announcements for early signals of supply chain restructuring. Forecasts reflect assumptions around regulatory alignment timelines and bio-based formulation cost parity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Ethane Market
Solvents
Nitromethane Market
Solvents
Saudi Arabia Methanol Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Aprotic Solvents Market
Solvents
Butyl Glycol Market
Solvents
Tetraethyl Benzene Market
Solvents
India High Purity Solvents Market
Solvents
Triacetin Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Diethyl Ether Market
Solvents
Toluene Derivatives Market
Solvents
Global Green and Bio-Based Solvents Market