
 Global Glycol Market | 2026-2036
Global Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycol Market Foresight
Aftermarket service revenue for glycol storage and reclamation systems is tilting toward integrated producers with captive logistics. Dow anchors North American supply through its Gulf Coast ethylene oxide derivative complexes. SABIC dominates Middle Eastern export volumes with access to low-cost feedstock. Indorama Ventures Public Company Limited extends its polyester value chain backward into glycol production across Asian markets.
Glycols are polyhydric alcohols with two hydroxyl groups, typically produced via hydration of ethylene oxide or propylene oxide, with ethylene glycol achieving purity grades above 99.8% for polyester applications. These compounds function primarily as chemical intermediates, heat transfer fluids, and humectants across industrial and consumer formulations. Ethylene glycol leads product type volumes due to its lock-in with polyester fiber and resin demand, while propylene glycol gains structural share from food-grade and pharmaceutical solvent applications. The antifreeze and coolant application segment sustains baseline offtake through automotive aftermarket replenishment cycles.
The US EPA regulates glycol emissions under Clean Air Act provisions for ethylene oxide byproducts, while EU REACH mandates registration and hazard communication for glycol ethers and derivatives. China's MEE enforces wastewater discharge limits on glycol manufacturing facilities in the Yangtze River basin. Stakeholders must monitor feedstock cost spreads between naphtha and ethane cracking economics to time capacity decisions.
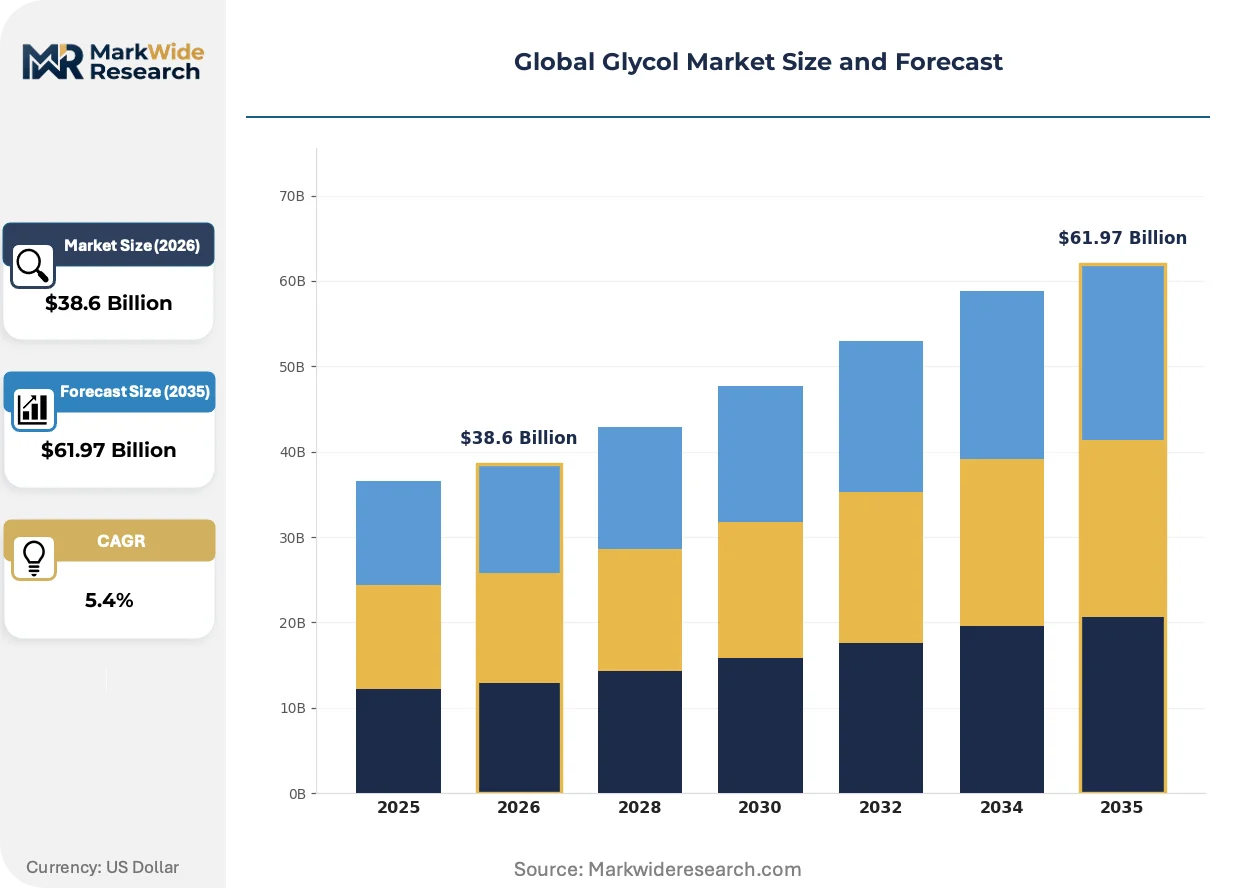
Market Dynamics
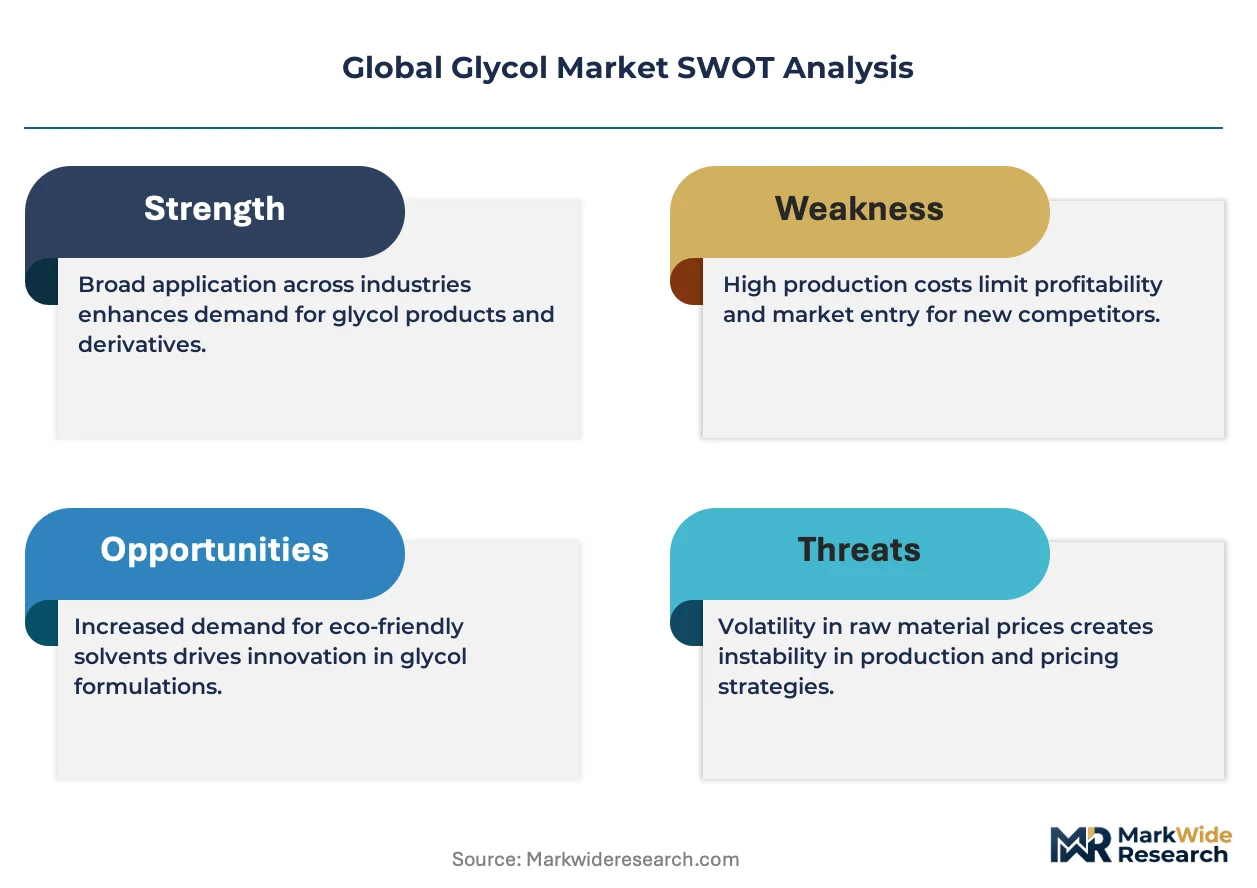
Polyester fiber demand from Asia's textile clusters is compressing glycol margins while pulling capacity decisions toward integrated petrochemical corridors with captive ethylene oxide supply.
Growth Catalysts
- REACH Phase-in Substances:ECHA's updated registration requirements for glycol ethers are forcing purity upgrades that favor producers with advanced distillation capabilities.
- China Textile Belt:Polyester resin consumption in Zhejiang and Jiangsu provinces sustains ethylene glycol offtake through vertically integrated fiber-to-fabric operations.
- Biobased Propylene Glycol:Glycerol-to-propylene glycol conversion technology is expanding food-grade and pharmaceutical solvent applications beyond petroleum-derived supply.
Market Restraints
- Ethane-Naphtha Spread Volatility:Feedstock cost arbitrage between US Gulf Coast ethane and Asian naphtha cracking economics destabilizes regional cost competitiveness.
- Middle East Export Concentration:SABIC and regional state-controlled producers command over half of seaborne glycol volumes, creating supply security exposure for Asian buyers.
- Ethylene Oxide Carcinogen Classification:IARC's Group 1 designation elevates capital requirements for emissions containment and worker exposure protocols.
Strategic Opportunities
- India PLI Scheme for Textiles:Production-linked incentives for man-made fiber manufacturing are attracting glycol storage and blending investments near Surat and Tiruppur.
- Carbon Capture Integration:Glycol dehydration units for natural gas processing are pairing with amine-based CO2 capture systems in US Permian and Norwegian North Sea installations.
- EU Green Deal Methanol Mandates:Renewable methanol specifications for marine fuels are opening glycol ether demand from biodiesel and e-fuel synthesis pathways.
Industry Challenges
- Process Safety Engineering Shortage:Ethylene oxide handling expertise is concentrated among a shrinking cohort of specialists with Hazop certification and incident investigation experience.
- MEE Wastewater Compliance:China's Ministry of Ecology and Environment enforces COD and BOD discharge limits that require membrane bioreactor upgrades at legacy glycol plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycol Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Butylene Glycol, Diethylene Glycol, Triethylene Glycol Application: Antifreeze & Coolants, Plasticizers, Functional Fluids, Solvents, Pharmaceuticals Form: Liquid, Aqueous Solution, Powder, Resin End User Industry: Textile Manufacturing, Adhesive Production, Agriculture Chemicals, Paints & Coatings |
| Companies Covered | Shell PLC, MEGlobal, Indorama Ventures Public Company Limited, Reliance Industries Limited, PETRONAS Chemicals Group Berhad, Dow, LyondellBasell Industries, BASF SE, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycol Market Shifts & Advancements
Process intensification and regulatory chemistry are reshaping how glycol derivatives achieve specification grades for pharmaceutical and food-contact applications.
Membrane-assisted reactive distillation is hybridizing conventional ethylene oxide hydration with pervaporation separation, enabling producers to reach polymer-grade purity above 99.9% without energy-intensive vacuum systems. Specialty chemical divisions in Germany and Japan are piloting these units for pharmaceutical-grade monoethylene glycol. The technology is compressing capital intensity for mid-scale entrants while eroding the yield advantage of legacy mega-plants.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in automotive and stationary cooling, reducing traditional glycol-based heat transfer fluid volumes in mobile air conditioning. ECHA's restriction proposals for perfluorinated substances are redirecting formulation R&D toward glycol-silicate hybrid coolants with lower global warming potential. Automotive OEMs in Stuttgart and Wolfsburg are qualifying these alternatives for electric vehicle thermal management.
Specification-driven procurement is consolidating glycol purchasing among polyester producers with in-house laboratory certification capabilities, displacing spot-market traders who lack real-time purity verification. Indorama Ventures and Reliance Industries are integrating reclamation services into long-term supply agreements for bottle-grade resin operations. This pattern is most visible in Thailand and Indonesia, where integrated PET producers are capturing reclaimed glycol from post-consumer recycling streams.
Global Glycol Market Segmentation
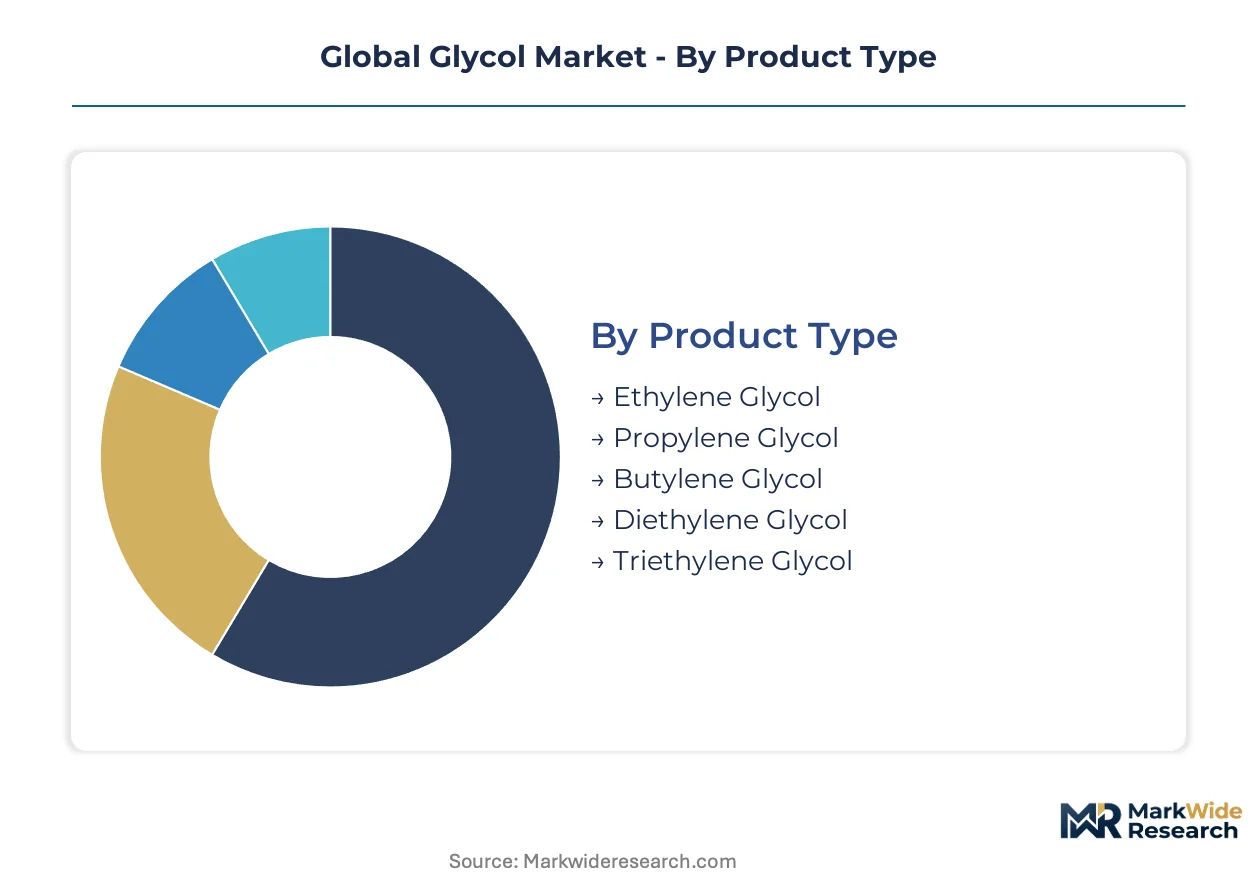
Glycol market segmentation reveals how specification grades, formulation chemistry, and end-use certification requirements partition value capture across producers. Each dimension—product type, application, physical form, and customer industry—creates distinct margin tiers and captive supply relationships.
Product Type:
Mature commodity glycols dominate volume throughput while specialty grades command specification premiums in regulated applications.
- Ethylene Glycol:The dihydric alcohol achieves polymer-grade purity above 99.8% through ethylene oxide hydration and vacuum distillation. Polyester resin production in China's Zhejiang and Jiangsu textile belts absorbs the majority of offtake, with MEGlobal and SABIC operating integrated crackers-to-derivatives complexes that lock in cost advantages.
- Propylene Glycol:This hygroscopic liquid serves dual markets—USP-grade for pharmaceuticals and food additives, industrial-grade for unsaturated polyester resins. Biobased production from glycerol feedstock is expanding pharmaceutical solvent applications beyond petroleum-derived supply, particularly under EU REACH purity mandates.
- Butylene Glycol:The four-carbon diol functions as a humectant and solvent in cosmetic formulations.
- Diethylene Glycol:This byproduct of ethylene glycol manufacture finds use in unsaturated polyester resins and plasticizers.
- Triethylene Glycol:The higher glycol ether serves natural gas dehydration and aromatic extraction processes.
Ethylene glycol handles the majority of throughput; propylene glycol is expanding most quickly on share as food-grade and pharmaceutical certifications displace industrial solvents.
Application:
Application segmentation tracks how thermal performance requirements and regulatory exposure partition procurement patterns across customer sets.
- Antifreeze & Coolants:Formulations blend glycol bases with corrosion inhibitors for engine and industrial heat transfer systems. Automotive OEM qualification cycles in Stuttgart and Wolfsburg are driving adoption of glycol-silicate hybrid coolants with lower global warming potential under EU F-Gas Regulation phase-down schedules.
- Plasticizers:Glycol esters soften PVC and synthetic rubber compounds. REACH registration requirements for glycol ethers are forcing purity upgrades that favor producers with advanced distillation capabilities, consolidating supply among integrated petrochemical operators.
- Functional Fluids:Heat transfer and hydraulic applications demand thermal stability across wide temperature ranges.
- Solvents:Printing inks and coatings formulations utilize glycol ether co-solvents for viscosity control.
- Pharmaceuticals:USP-grade glycols serve as excipients and drug delivery vehicles. Specification-driven procurement is consolidating purchasing among manufacturers with in-house laboratory certification capabilities, displacing spot-market traders lacking real-time purity verification.
Antifreeze and coolants anchor baseline demand through automotive aftermarket replenishment; pharmaceuticals represents the steepest expansion trajectory as regulatory chemistry tightens specification thresholds.
Form:
Physical form determines logistics economics, handling safety protocols, and customer formulation flexibility.
- Liquid:Bulk liquid glycols move via dedicated tanker fleets and terminal storage, with integrated producers capturing aftermarket service revenue for reclamation systems.
- Aqueous Solution:Pre-diluted formulations reduce customer handling of concentrated ethylene oxide derivatives, addressing IARC carcinogen classification concerns.
- Powder:Spray-dried glycols serve specialty adhesive and powder coating applications.
- Resin:Solid glycol-modified polyester resins enable powder coating and composite manufacturing.
Liquid form commands the dominant share of tonnage moved; aqueous solutions are climbing the fastest as downstream formulators outsource dilution and hazard management.
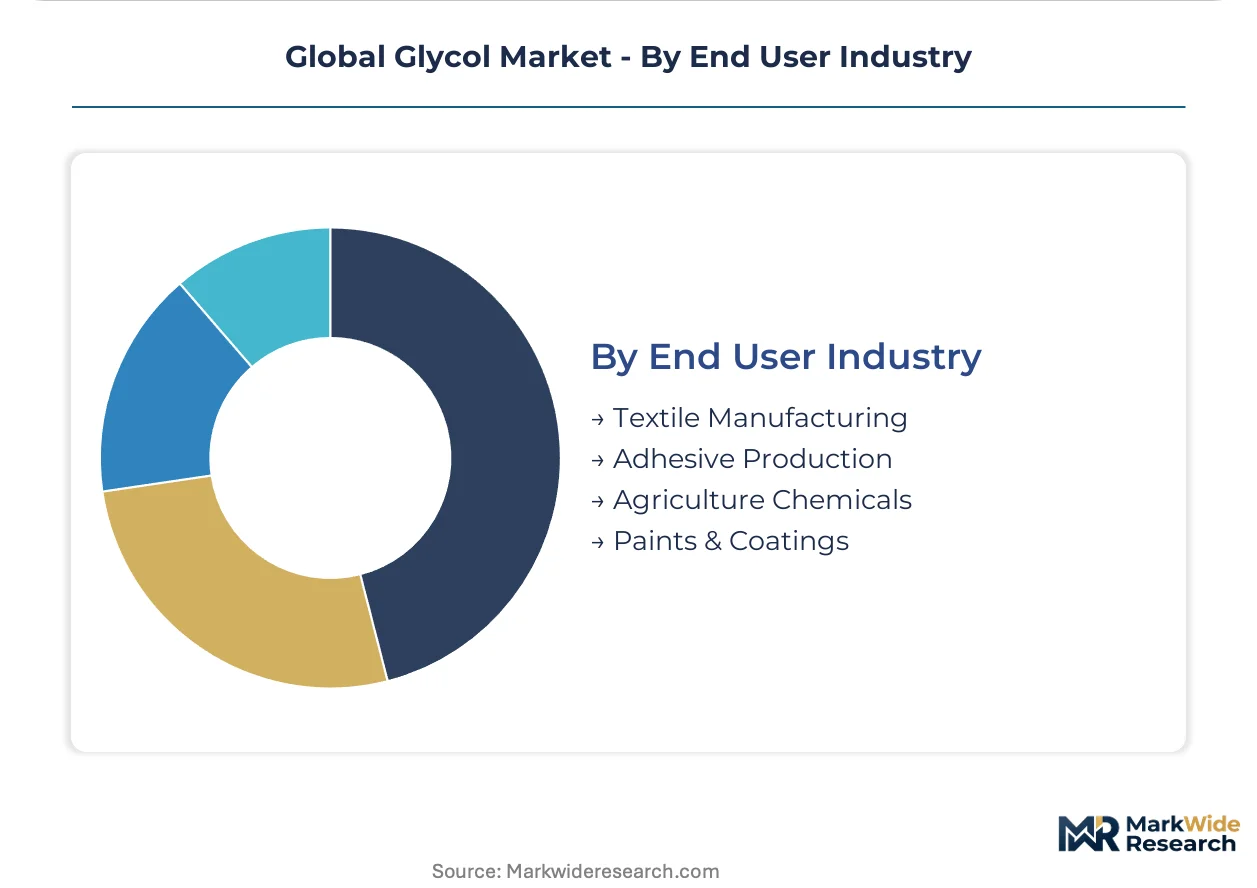
End User Industry:
Customer industry segmentation maps how specification intensity and vertical integration depth shape contract structures.
- Textile Manufacturing:Polyester fiber and resin demand from Asia's textile clusters compresses glycol margins while pulling capacity toward integrated petrochemical corridors. India's PLI scheme for man-made fiber manufacturing is attracting glycol storage investments near Surat and Tiruppur.
- Adhesive Production:Polyurethane and epoxy formulations utilize glycols as chain extenders and reactive diluents.
- Agriculture Chemicals:Pesticide formulations employ glycol ethers as co-solvents and stabilizers.
- Paints & Coatings:Waterborne coating systems rely on glycol ether co-solvents for freeze-thaw stability and film formation. ECHA restriction proposals for perfluorinated substances are redirecting R&D toward glycol-based alternatives with lower environmental persistence.
Textile manufacturing absorbs the largest volume share; paints and coatings is gaining share fastest as architectural and industrial coating regulations tighten volatile organic compound limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and China together command over half of seaborne glycol export volumes, with state-controlled and integrated petrochemical complexes locking in feedstock cost advantages that reshape trade flows toward Asian polyester manufacturing clusters.
United States
Gulf Coast ethane cracking economics sustain cost-competitive ethylene oxide derivative output. EPA Clean Air Act enforcement tightens emissions thresholds for ethylene oxide byproducts near Houston and Corpus Christi. Dow anchors supply through integrated complexes along the Texas-Louisiana corridor.
China
Zhejiang and Jiangsu textile belts absorb the majority of ethylene glycol offtake for polyester resin production. MEE wastewater discharge limits force membrane bioreactor upgrades at legacy glycol plants in the Yangtze River basin. MEGlobal operates integrated crackers-to-derivatives complexes with captive logistics.
Saudi Arabia
Low-cost ethane feedstock access underpins export dominance across Asian markets. State-controlled producers command over half of seaborne glycol volumes. SABIC leverages integrated petrochemical corridors on the Arabian Gulf for derivative output.
Germany
Automotive OEM qualification cycles in Stuttgart and Wolfsburg drive glycol-silicate hybrid coolant adoption. EU REACH mandates registration and hazard communication for glycol ethers. Specialty chemical divisions pilot membrane-assisted reactive distillation for pharmaceutical-grade purity.
India
PLI scheme incentives for man-made fiber manufacturing attract glycol storage investments. BIS certification requirements tighten specification thresholds for imported glycol derivatives. Surat and Tiruppur clusters emerge as blending and distribution hubs for polyester value chains.
Global Glycol Market Competitive Landscape
Integrated petrochemical majors and regional export specialists split the market between captive supply chains and merchant trading positions. Consolidation concentrates around ethylene oxide derivative complexes with backward integration into ethylene production. Three archetypes dominate: Gulf Coast ethane-based operators, Middle Eastern state-controlled exporters, and Asian polyester-integrated producers. Capacity expansion and specification-grade purification technology licensing represent the dominant competitive vectors.
Within the integrated major tier, Shell PLC and Dow exemplify ethane-based cost structures anchored in North American feedstock advantages. SABIC occupies a position as the archetypal Middle Eastern export specialist with state-backed feedstock access. Indorama Ventures Public Company Limited represents Asian backward integration into glycol production from polyester resin operations.
| Leading Market Players |
|---|
| Shell PLC |
| MEGlobal |
| Indorama Ventures Public Company Limited |
| Reliance Industries Limited |
| PETRONAS Chemicals Group Berhad |
| Dow |
| LyondellBasell Industries |
| BASF SE |
| SABIC |
| Others |
Supply & Pricing Matrix
Zhejiang and Jiangsu textile belts concentrate polyester resin production capacity that compresses ethylene glycol margins through captive offtake agreements. This geographic clustering hands pricing power to integrated petrochemical operators with backward integration into ethylene oxide supply, while spot-market traders face yield erosion from real-time purity verification requirements.
Pricing Analysis
Aftermarket service revenue for glycol storage and reclamation systems anchors lifetime value through multi-year maintenance contracts and purity upgrade subscriptions. Three-tier pricing structure across polymer-grade, industrial-grade, and reclaimed glycol levels separates specification premiums from commodity baselines. Cost compression in industrial-grade tiers is intensifying because biobased propylene glycol from glycerol feedstock is displacing petroleum-derived supply. Polyester producers with in-house laboratory certification capabilities exhibit lowest price sensitivity; spot-market traders lacking real-time verification face highest margin pressure.
Supply Chain Analysis
Ethane and naphtha feedstock economics hinge on cracking configurations across Saudi Arabia, the United States, and China. Ethylene oxide, propylene oxide, and glycerol constitute the primary input dependencies. Single-source vulnerability concentrates in Middle Eastern state-controlled export volumes where SABIC commands seaborne glycol flows. Distribution runs through dedicated tanker fleets and terminal storage networks anchored at integrated crackers-to-derivatives complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glycol markets are approaching a platform-economics inflection as specification-driven procurement consolidates purchasing among integrated polyester producers with captive reclamation capabilities, displacing fragmented spot-market intermediaries.
For Market Incumbents: Pre-empt margin erosion from biobased propylene glycol by securing glycerol supply agreements and licensing membrane-assisted reactive distillation for pharmaceutical-grade purity tiers. Anchor capacity decisions in integrated petrochemical corridors with captive ethylene oxide supply to defend against feedstock cost arbitrage volatility.
For New Entrants and Emerging Players: India's Surat and Tiruppur clusters present underpenetrated glycol storage and blending infrastructure gaps as PLI scheme incentives attract man-made fiber manufacturing. Target food-grade and pharmaceutical solvent applications where REACH purity mandates favor advanced distillation capabilities over legacy commodity producers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded glycol ether divisions lacking pharmaceutical-grade certification pathways. Long-term viability centers on carbon capture integration potential and renewable methanol offtake agreements for marine fuel synthesis. Monitor EU F-Gas Regulation phase-down schedules as inflection indicators for glycol-silicate hybrid coolant adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply locks in cost advantages against naphtha-ethane spread volatility. |
| Membrane-Assisted Reactive Distillation Licensing | Pharmaceutical-grade purity above 99.9% opens REACH-compliant solvent markets in Germany and Japan. |
| Carbon Capture Integration | Amine-based CO2 capture pairing with glycol dehydration units accesses US Permian and Norwegian North Sea installations. |
| Biobased Propylene Glycol Scale-Up | Glycerol-to-propylene glycol conversion technology expands food-grade applications beyond petroleum supply. |
| Long-Term Supply Agreement with Polyester Producers | Indorama Ventures and Reliance Industries are consolidating procurement through integrated reclamation services. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant managers at ethylene oxide derivative complexes, procurement leads at polyester resin manufacturers, distribution channel partners in Asian textile clusters, and technical R&D directors developing membrane separation technologies. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA Clean Air Act enforcement disclosures. Bottom-up capacity modeling and top-down demand aggregation were triangulated against observed offtake patterns.
Calibration against historical capacity utilization and feedstock cost spreads anchored projections across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry application, physical form logistics economics, and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions for biobased alternatives. Ethylene oxide carcinogen classification impacts and MEE wastewater compliance costs were incorporated as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Middle Eastern state-controlled exporters or sudden ethane-naphtha spread reversals would shift outcomes beyond modeled ranges. Cross-checking against IEA petrochemical feedstock benchmarks and ECHA registration timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Diethylene Glycol (DEG) Market
Solvents
Methyl Undecylenate Market
Solvents
2-Butanone Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Monochlorobenzene Market
Solvents
Sugar Dissolvers Market
Solvents
Global Ethyl Lactate Market
Solvents
Mineral Turpentine Market
Solvents
Crotonaldehyde Market
Solvents
6-Xylenol Market
Solvents
Solvent Cement Market
Solvents
Asia-Pacific Ethane Market
Solvents
Phenol Derivatives Market
Solvents
Chlorobenzene Market
Solvents
Isoparaffin Solvents Market
Solvents
Chloromethane Market