
 Asia-Pacific Ethane Market | 2026-2036
Asia-Pacific Ethane Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ethane Market Insights
Feedstock flexibility premiums is reconfiguring margin distribution between naphtha crackers and ethane-based facilities across Asia-Pacific. Sinopec leverages its integrated refining-petrochemical complexes to capture economies of scale in eastern China. Reliance Industries Limited anchors its Jamnagar complex with dedicated ethane import infrastructure from US Gulf terminals. PTT Global Chemical Public Company Limited competes through its Map Ta Phut olefins hub with direct pipeline connectivity to regional ethane storage.
Ethane constitutes a saturated hydrocarbon with molecular formula C₂H₆, typically extracted from natural gas processing streams at purity levels exceeding 90 percent for petrochemical cracking operations. Its primary commercial purpose centers on steam cracking to yield ethylene, the foundational monomer for polyethylene resins and ethylene glycol production. Pipeline delivery dominates volume movements across the Asia-Pacific Ethane Market, reflecting the infrastructure density linking import terminals to coastal crackers in China and South Korea. Chemical feedstock classification captures the majority of value realization, while marine fuel applications remain nascent amid regulatory uncertainty over bunker emission standards.
China's MEE enforces escalating carbon intensity benchmarks for steam crackers, effectively mandating feedstock shifts toward lower-emission ethane pathways. South Korea's MFDS and KOSHA frameworks govern workplace exposure limits and process safety protocols at Daesan and Yeosu industrial complexes. India's CEA and Petroleum and Natural Gas Regulatory Board oversee cross-country pipeline tariffs and import terminal approvals. Stakeholders must monitor feedstock cost spreads between ethane and naphtha to time capacity additions and retrofit commitments.
Market Dynamics
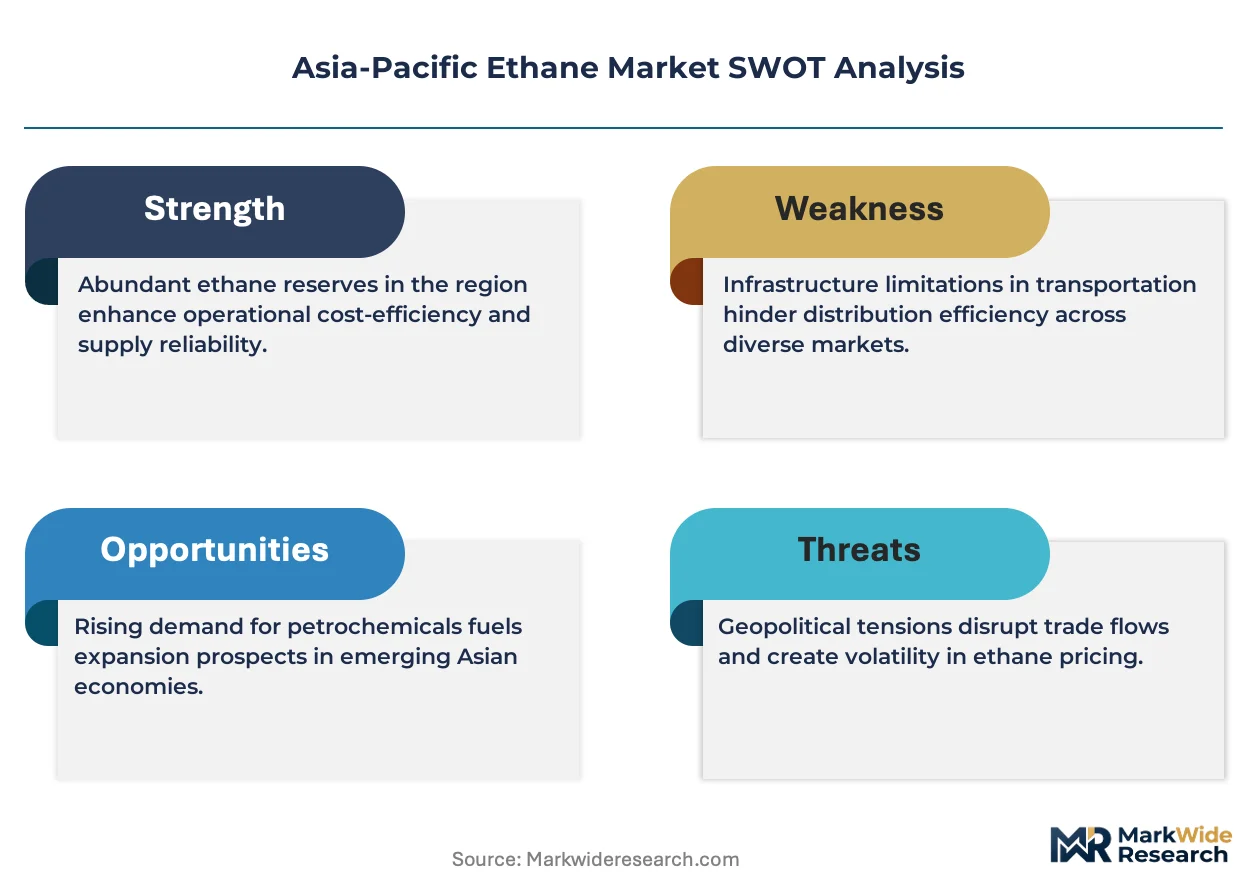
China's MEE emissions benchmarks are forcing feedstock substitution toward ethane cracking, compressing naphtha cracker margins and redistributing capital across Asia-Pacific petrochemical clusters. This regulatory pressure is concentrating investment in dedicated ethane import terminals and coastal steam cracking facilities.
Growth Catalysts
- Dual carbon goals:China's national decarbonization targets mandate carbon intensity reductions at Shandong and Jiangsu petrochemical complexes, redirecting capital toward lighter feedstock configurations with lower emission profiles.
- Polyethylene demand:Packaging and construction end-uses across eastern China are absorbing expanded ethylene output, sustaining throughput at ethane-optimized crackers with superior yield economics.
- Import infrastructure:Dedicated very large ethane carriers and cryogenic storage terminals at Ningbo and Dalian are reducing delivered cost spreads against naphtha alternatives.
Market Restraints
- Feedstock price volatility:Mont Belvieu ethane pricing tied to Henry Hub natural gas creates margin compression risk for crackers without long-term offtake hedging.
- Supply route concentration:US Gulf Coast terminal bottlenecks and Panama Canal transit constraints expose Asia-Pacific buyers to seasonal shipping disruptions.
- Cracker conversion costs:Retrofitting naphtha-optimized furnaces for ethane flexibility requires substantial furnace coil replacement and quench system modifications.
Strategic Opportunities
- Vietnam's emerging demand:Greenfield petrochemical investments at Long Son and Nghi Son are evaluating ethane feedstock configurations for integrated polyethylene complexes.
- Marine fuel applications:IMO 2025 sulfur regulations are creating pilot demand for ethane as LNG-comparable bunker fuel at Singapore and Busan bunkering hubs.
- Pipeline interconnectivity:Cross-border ethane distribution networks linking Thai storage caverns to Vietnamese crackers could unlock inland demand beyond coastal terminals.
Industry Challenges
- Cryogenic handling expertise:Scarce technician pools for minus-90-degree Celsius storage and regasification operations are extending commissioning timelines at new terminals.
- Feedstock certification complexity:MEE carbon accounting requirements demand granular supply chain documentation from US extraction through Chinese cracking, straining traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ethane Market |
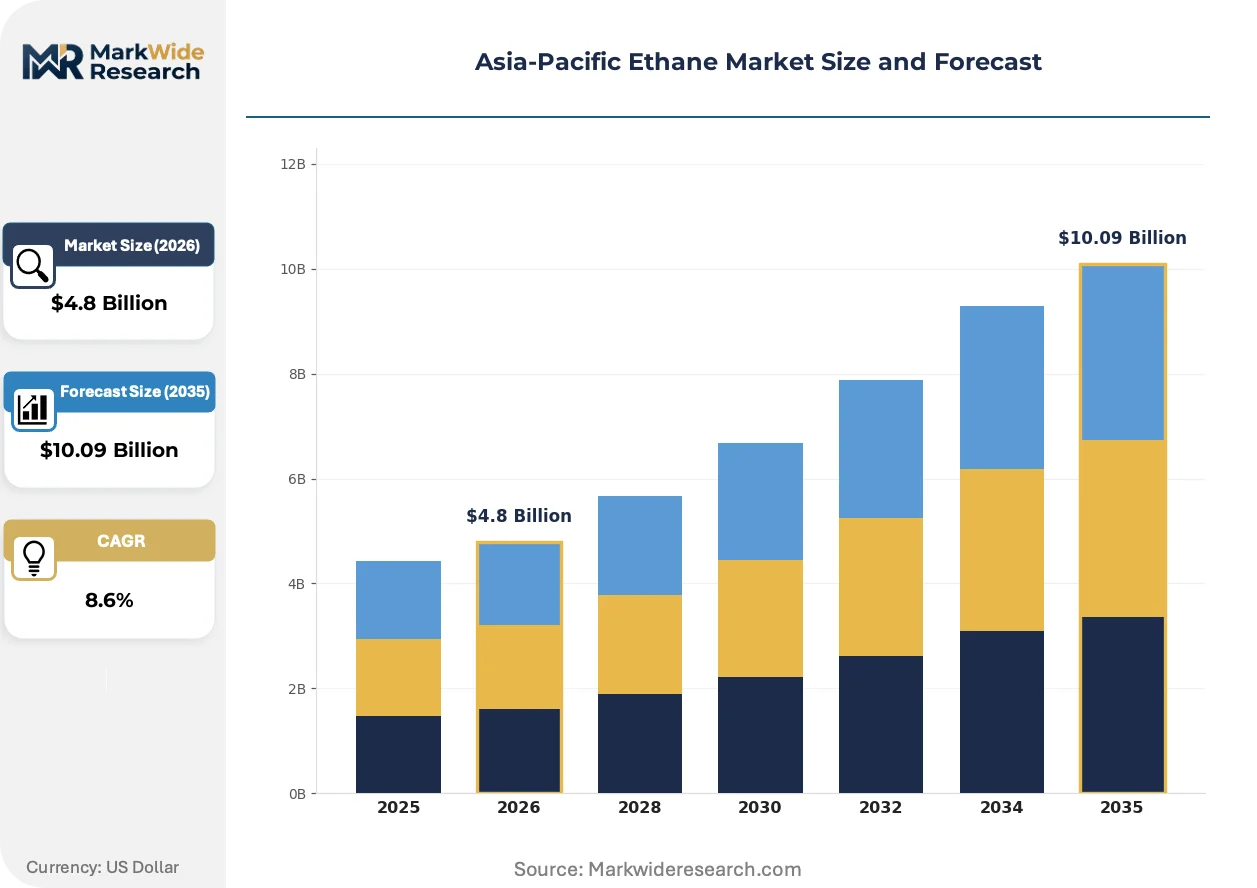
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethane, Ethylene, Polymer Grade Ethylene, Chemical Feedstock End User: Petrochemical Industry, Power Generation, Residential Heating, Marine Fuel Application: Gas Processing, Energy Production, Chemical Manufacturing, Fuel Supply Delivery Mode: Pipelines, Shipping, Truck Transport, Tanker Delivery |
| Companies Covered | Formosa Petrochemical Corporation, Wanhua Chemical Group, Reliance Industries Limited, Sinopec, China National Offshore Oil, China National Petroleum Corporation, Yulong Petrochemical, Indorama Ventures, PTT Global Chemical Public Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ethane Market Trends and Innovations
Digital twin technology is virtualizing operational decision-making across Asia-Pacific ethane supply chains. These innovations compress planning cycles and enable predictive optimization of import scheduling and cracking operations.
Advanced process control systems using real-time furnace analytics are virtualizing yield optimization at steam cracking units. Sinopec and PTT Global Chemical are deploying these platforms at Shandong and Map Ta Phut complexes. The technology is virtualizing manual operator interventions into automated temperature and residence time adjustments, reducing off-spec ethylene batches.
South Korea's MFDS workplace exposure mandates are tightening process safety documentation requirements at Yeosu and Daesan industrial zones. Facilities must now install continuous ethane leak detection with automated shutdown protocols. Daesan crackers are responding by retrofitting infrared gas imaging and distributed acoustic sensing along cryogenic transfer lines.
Buyers are consolidating procurement through multi-year offtake agreements with embedded price collars. This behavior is displacing spot market participation among mid-sized polyethylene producers. The shift is most visible in Jiangsu province, where processors are locking in five-year ethane supply to secure bank financing for capacity expansions.
Asia-Pacific Ethane Market Segmentation
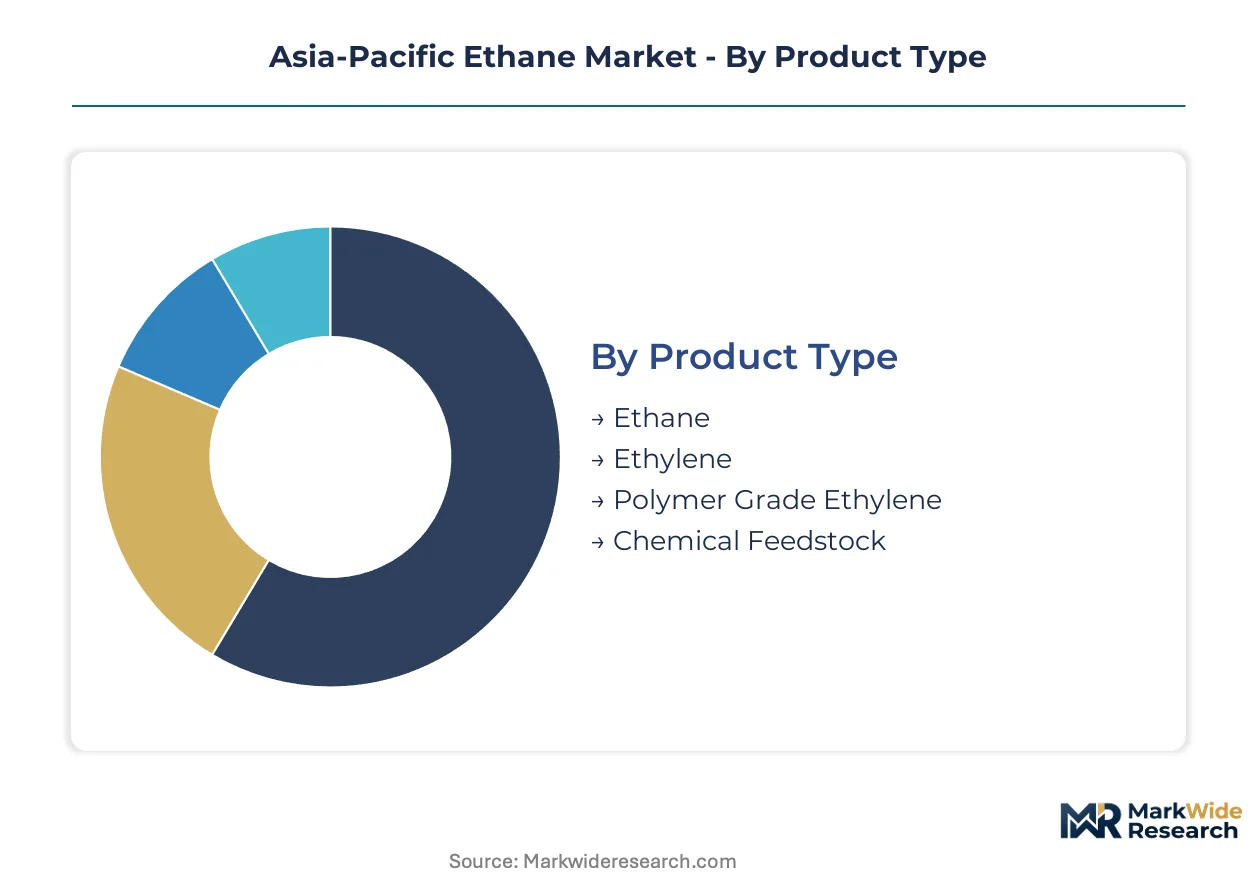
Ethane market segmentation reveals how feedstock purity, delivery infrastructure, and end-use specifications determine pricing tiers and contract structures across Asia-Pacific. Each dimension carries distinct margin profiles and capital intensity requirements that shape procurement strategies for crackers and distributors.
Product Type:
Inventory velocity varies sharply across purity grades, with pipeline-grade ethane turning over weekly while polymer-grade specifications sit in terminal storage awaiting cracker campaigns.
- Ethane:Raw natural gas liquids fraction with 60-80% purity serves regional blending operations and intermediate processing. Daesan and Yeosu industrial zones absorb volumes for on-site upgrading before cracking.
- Ethylene:Direct output from steam cracking operations, immediately consumed in downstream polyethylene units at Shandong complexes. This segment turns fastest due to integrated plant configurations.
- Polymer Grade Ethylene:Ultra-high purity specification exceeding 99.9% for specialized copolymer production. Jiangsu province processors pay premiums for certified batches meeting automotive and medical packaging standards.
- Chemical Feedstock:Broad classification capturing ethane destined for ethylene glycol, styrene, and vinyl chloride monomer synthesis. Ningbo terminals handle the largest regional volumes.
Standard ethane dominates installed base. Polymer-grade specifications are where expansion concentrates.
End User:
Customer concentration runs inverse to volume scale, with petrochemical majors commanding tonnage discounts while marine fuel buyers purchase spot cargoes at terminals.
- Petrochemical Industry:Integrated crackers at Jamnagar, Map Ta Phut, and Shandong consume 90%+ of regional ethane imports. Long-term offtake agreements with US Gulf suppliers lock in fifteen-year supply horizons.
- Power Generation:Emerging peaker plant fuel source in South Korea's KPX grid balancing market. MFDS safety protocols limit deployment to coastal facilities with dedicated cryogenic vaporization.
- Residential Heating:Minimal penetration limited to Japanese rural districts with legacy propane infrastructure retrofits. METI building codes restrict new ethane heating installations.
- Marine Fuel:Singapore and Busan bunkering hubs pilot ethane as IMO-compliant low-sulfur alternative. Pilot programs at PSA Singapore involve dedicated VLEC-to-bunker vessel transfers.
Petrochemical processors anchor volume commitments. Marine fuel trials are climbing the fastest.
Application:
Process complexity tiers separate commodity extraction from specialty chemical synthesis, with margin capture scaling directly with molecular transformation depth.
- Gas Processing:Upstream separation at Australian North West Shelf and Malaysia's Bintulu facilities yields feedstock for regional export. Cryogenic fractionation trains operate at minus-90 degrees Celsius.
- Energy Production:Direct combustion in industrial boilers and power turbines. South Korean district heating experiments at Seongnam use ethane as bridge fuel during coal phase-out.
- Chemical Manufacturing:Steam cracking to ethylene, propylene, and butadiene derivatives. Sinopec's Shandong complex achieves highest regional yields through advanced furnace analytics.
- Fuel Supply:Bulk distribution to remote industrial sites lacking pipeline connectivity. Truck-mounted cryogenic tanks serve western China cement kilns.
Gas processing commands the largest throughput base. Chemical manufacturing routes are where value addition concentrates.
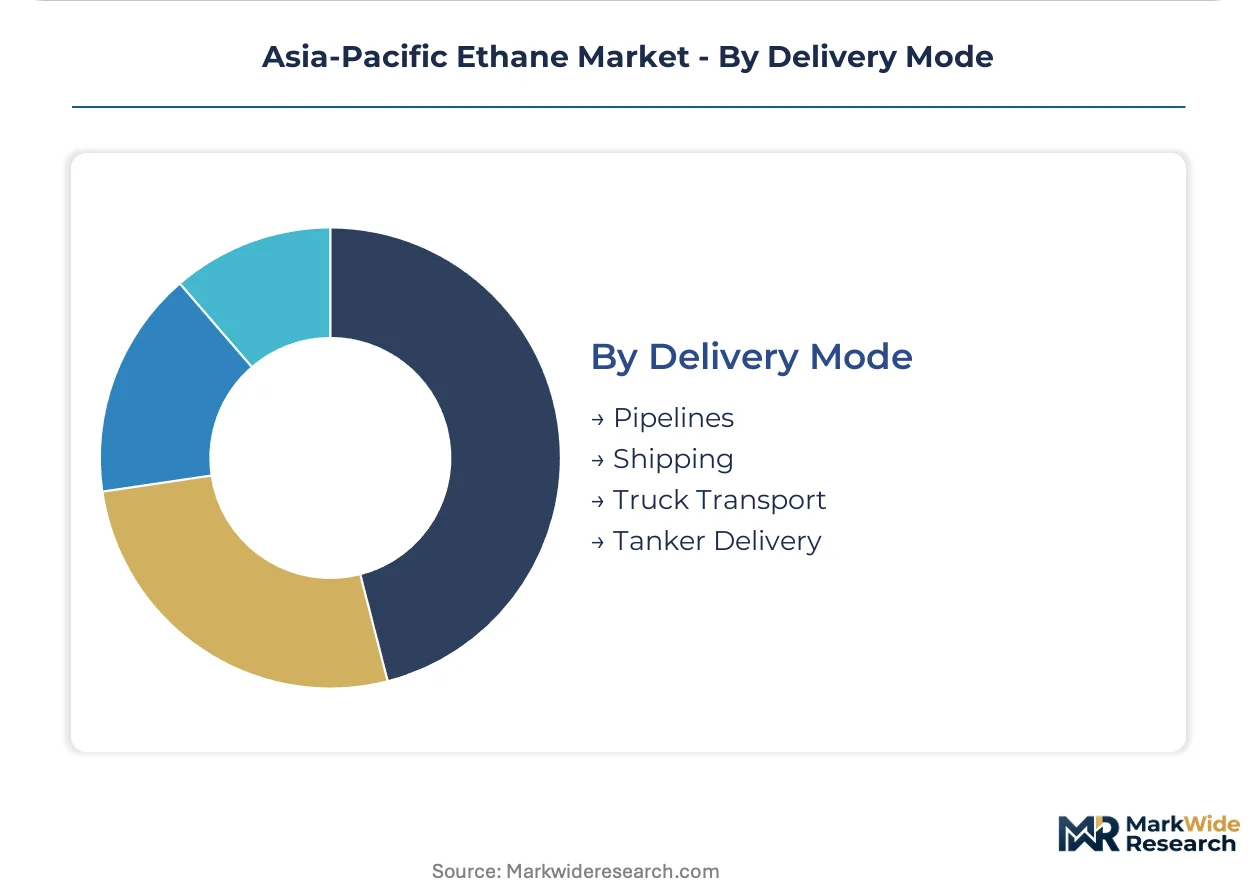
Delivery Mode:
Capital intensity and flexibility trade off across transport modes, with pipelines offering lowest unit costs and shipping providing destination optionality.
- Pipelines:Dedicated ethane lines connect PTT Global Chemical's Map Ta Phut terminal to Rayong crackers. Thai pipeline tariffs are regulated under national petroleum board frameworks.
- Shipping:Very Large Ethane Carriers move US Gulf volumes through Panama Canal to Ningbo and Dalian. Canal transit constraints create seasonal bottlenecks during drought restrictions.
- Truck Transport:Cryogenic tanker fleets serve inland crackers beyond pipeline reach. Indian cross-country movements face Petroleum and Natural Gas Regulatory Board tariff disputes.
- Tanker Delivery:Coastal barge transfers between Singapore storage and Malaysian end-users. Short-haul routes avoid deepwater vessel demurrage costs.
Pipelines dominate installed infrastructure. Shipping routes are where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ethane almost exclusively for polyethylene manufacturing, while South Korea and India deploy smaller volumes for power generation peaking and industrial fuel blending. This consumption-mix differential shapes infrastructure investment patterns across the region.
China
Shandong and Jiangsu province petrochemical clusters absorb the bulk of regional ethane imports for steam cracking operations. The MEE enforces escalating carbon intensity benchmarks that mandate feedstock shifts toward lower-emission ethane pathways. Ningbo and Dalian terminals handle the largest cryogenic storage volumes, with dedicated very large ethane carriers reducing delivered cost spreads against naphtha alternatives.
South Korea
Daesan and Yeosu industrial complexes anchor ethylene production for export-oriented polyethylene manufacturing. The MFDS workplace exposure mandates are tightening process safety documentation requirements, requiring continuous ethane leak detection with automated shutdown protocols. Yeosu crackers are retrofitting infrared gas imaging and distributed acoustic sensing along cryogenic transfer lines to comply.
India
Reliance Industries Limited's Jamnagar complex anchors national demand with dedicated ethane import infrastructure from US Gulf terminals. The CEA and Petroleum and Natural Gas Regulatory Board oversee cross-country pipeline tariffs and import terminal approvals. Gujarat's coastal refining corridor concentrates ethane-receiving capacity, with cross-country movements facing ongoing tariff disputes.
Thailand
PTT Global Chemical's Map Ta Phut olefins hub competes through direct pipeline connectivity to regional ethane storage caverns. Thai pipeline tariffs are regulated under national petroleum board frameworks that influence regional pricing benchmarks. Rayong crackers receive dedicated ethane lines from Map Ta Phut terminal, creating integrated supply security.
Vietnam
Greenfield petrochemical investments at Long Son and Nghi Son are evaluating ethane feedstock configurations for integrated polyethylene complexes. Emerging demand from packaging and construction end-uses is attracting feasibility studies for dedicated import terminals. Cross-border pipeline interconnectivity from Thai storage caverns could unlock inland demand beyond coastal terminals.
Asia-Pacific Ethane Market Competitive Landscape
Capability concentration sits with integrated refining-petrochemical majors; scale advantage sits with dedicated olefins specialists. The market structure tiers between state-affiliated energy conglomerates with captive supply chains and independent processors reliant on long-term offtake agreements. Three archetypes dominate: integrated national champions, regional cracking specialists, and import-terminal operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing dedicated very large ethane carrier fleets and cryogenic storage positions.
Among Asia-Pacific-based integrated majors, Sinopec, Reliance Industries Limited, and PTT Global Chemical Public Company Limited exemplify the state-affiliated champion archetype. Sinopec occupies a position leveraging integrated refining-petrochemical complexes to capture economies of scale in eastern China. Reliance Industries Limited anchors its position through dedicated ethane import infrastructure. PTT Global Chemical sits within the regional hub operator tier with pipeline-connected storage advantages.
| Leading Market Players |
|---|
| Formosa Petrochemical Corporation |
| Wanhua Chemical Group |
| Reliance Industries Limited |
| Sinopec |
| China National Offshore Oil |
| China National Petroleum Corporation |
| Yulong Petrochemical |
| Indorama Ventures |
| PTT Global Chemical Public Company Limited |
Pricing and Supply Chain Analysis
US Gulf Coast terminal concentration anchors Asia-Pacific ethane procurement, funneling Mont Belvieu-indexed supply through dedicated very large ethane carriers to Ningbo and Dalian. This upstream bottleneck concentrates margin capture at coastal import terminals while compressing delivered cost spreads for inland crackers lacking direct pipeline access.
Pricing Analysis
Long-term offtake agreements with embedded Henry Hub price collars dominate contract structures, displacing spot market participation among mid-sized polyethylene producers. Price differentiation rests on purity certification and volume scale, with polymer-grade specifications commanding premiums from Jiangsu automotive packaging processors. Cost compression in standard-grade supply is intensifying because of naphtha-ethane spread volatility. Mid-sized crackers without integrated refining show highest price sensitivity; integrated majors like Sinopec and Reliance Industries Limited exhibit lowest.
Supply Chain Analysis
US export-control regimes on cryogenic handling technology constrain vessel fleet expansion and terminal commissioning timelines. Supply concentrates in the United States, Qatar, and Australia as source markets, drawing from associated natural gas and shale liquids extraction. Feedstock rests on fractionation capacity at Mont Belvieu and Marcus Hook, plus specialized VLEC vessel availability. Single-source vulnerability runs through Panama Canal transit constraints. Distribution runs through dedicated coastal terminals with cryogenic storage before pipeline or truck transfer to crackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ethane market sits at a platform-economics inflection where dedicated import infrastructure interoperability determines competitive access. PTT Global Chemical's pipeline-integrated Map Ta Phut hub exemplifies how storage-terminal-cracker connectivity creates ecosystem lock-in.
For Market Incumbents: Build captive supply moats through backward integration into dedicated VLEC fleets and cryogenic storage positions. Secure fifteen-year offtake agreements with US Gulf suppliers before terminal bottlenecks worsen. Invest in furnace flexibility retrofits at Shandong and Jiangsu complexes to defend margin position against naphtha price volatility.
For New Entrants and Emerging Players: Build out Vietnam's Long Son and Nghi Son greenfield corridors where polyethylene demand growth outpaces established supply. Target marine fuel bunkering trials at Singapore and Busan as the most penetrable application segment. Pursue joint terminal development with Thai storage operators to leverage existing cross-border pipeline interconnectivity.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated olefins specialists with captive import infrastructure and pipeline-connected storage. Long-term viability over a multi-year horizon favors state-affiliated champions with refining-petrochemical integration and government-backed terminal approvals. Watch MEE carbon intensity benchmark tightening as the signal indicating accelerated feedstock substitution toward ethane-optimized capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated ethane crackers at Ningbo and Dalian capture MEE-mandated feedstock shift economics. |
| Backward Integration | VLEC fleet ownership at Reliance Industries Limited secures supply priority during US Gulf terminal congestion. |
| Long-term Supply Agreement | Fifteen-year offtake contracts with Henry Hub collars reduce margin volatility for Jiangsu polyethylene producers. |
| Joint Venture | Cross-border Thai-Vietnamese pipeline partnerships unlock inland demand beyond coastal terminal reach. |
| Green Certification Program | MEE carbon accounting compliance enables premium positioning in Shandong province petrochemical procurement. |
Research Methodology
Operator-level perspectives from terminal operations managers, cracker plant engineers, shipping fleet procurement leads, and petrochemical procurement directors anchored the qualitative base. These primary inputs combined with secondary validation from customs trade data, MEE emissions disclosure filings, Panama Canal transit statistics, and SEC 10-K petrochemical segment disclosures. Bottom-up capacity-by-cracker modeling and top-down regional demand triangulation cross-validated volume estimates.
Scenario-bracketing around MEE regulatory enforcement intensity and Panama Canal drought frequency framed the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, delivery mode, and regional production hub configuration. CAGRs derived from elasticity-adjusted demand curves incorporating polyethylene consumption growth and cracker feedstock switching economics. Industry-specific inputs encompassed Henry Hub-Mont Belvieu price spreads and VLEC fleet orderbook schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by national oil company affiliates would shift outcomes. Material shifts in MEE carbon intensity benchmark timelines or US LNG export prioritization over NGL fractionation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Tetraethyl Benzene Market
Solvents
Chloromethane Market
Solvents
Diethyl Ether Market
Solvents
Ethyl Acetate Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Decanol Market
Solvents
Ionic Liquids Market
Solvents
Aprotic Solvents Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Global Glycol Market
Solvents
Alpha-Methylstyrene Market
Solvents
Hydrocarbon Solvents Market
Solvents
Diethanolamine (DEA) Market
Solvents
Toluene Derivatives Market
Solvents
Reactive Diluents Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market