
 Butyl Acetate (BAC) Market | 2026-2036
Butyl Acetate (BAC) Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Acetate (BAC) Market Outlook
Acetone-based solvents is shifting toward butyl acetate in automotive refinish and industrial coating formulations due to superior evaporation control and lower photochemical reactivity. Eastman Chemical Company leverages integrated acetyl chain assets to secure feedstock cost advantages across North American and Asian supply points. Sasol Ltd. anchors its position through Fischer-Tropsch-derived alcohol feedstocks that differentiate purity grades for European pharmaceutical and electronics solvent buyers. BASF SE competes on scale, operating multi-purpose esterification trains that switch output between butyl acetate and specialty acetates based on regional margin signals.
Butyl acetate is a colorless ester with molecular formula C6H12O2, boiling point 126°C, and characteristic fruity odor, manufactured via esterification of n-butanol with acetic acid using sulfuric acid or solid acid catalysts. Its primary function is as a medium-evaporation solvent in nitrocellulose lacquers, acrylic coatings, and adhesive systems where balanced flow and dry time prove critical. Coatings applications dominate volume throughput, though solvent extraction for pharmaceutical and agrochemical purification represents the fastest-expanding margin pool as batch-size precision requirements intensify. Electronics end-use demand for ultra-high-purity grades is concentrating among Asian contract manufacturers with cleanroom solvent specifications that command premium pricing over standard industrial material.
EPA National Emission Standards for Hazardous Air Pollutants and REACH Annex XVII restrictions on VOC content in consumer and professional coatings are reshaping formulation chemistry and qualifying which solvent grades achieve market access. China's MEE enforcement of GB standards on industrial emissions and solvent storage is raising compliance costs for domestic esterification operators while accelerating consolidation toward integrated petrochemical complexes. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and EU F-Gas Regulation analogs for solvent containment, as compliance asymmetry will determine which production configurations retain cross-border shipment eligibility.
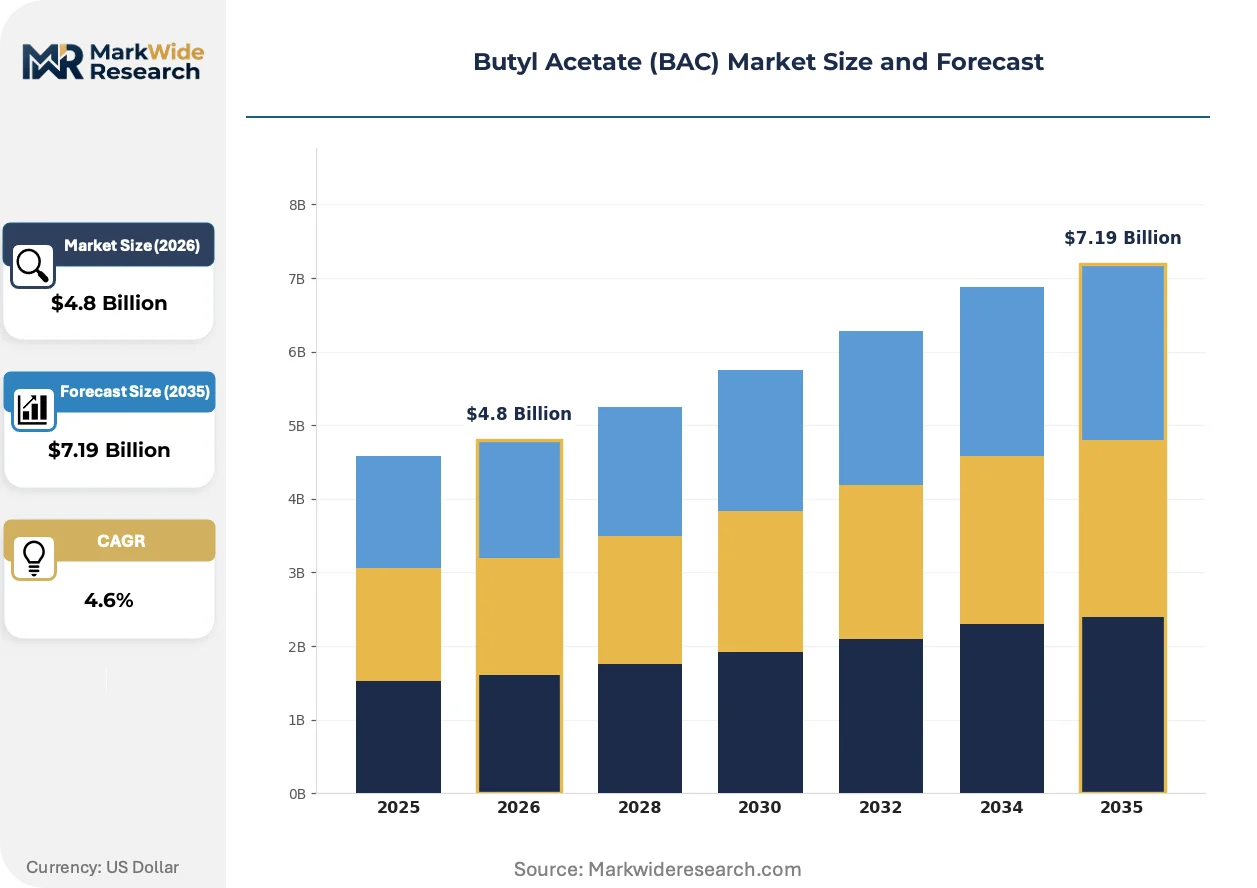
Market Dynamics
The shift from acetone-based solvents to butyl acetate in automotive and industrial coatings is restructuring procurement patterns, as formulators prioritize evaporation control and lower photochemical reactivity to meet tightening VOC regulations.
Growth Catalysts
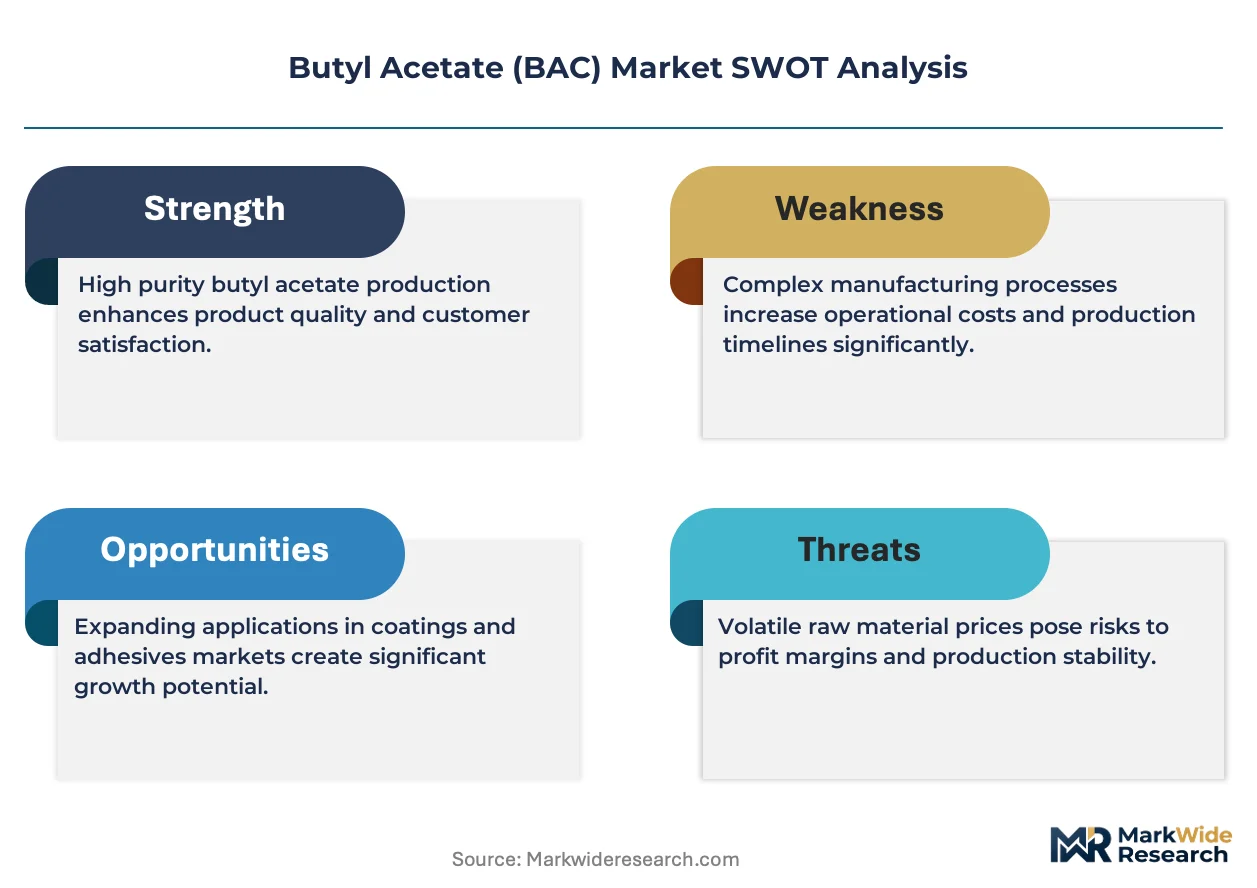
- REACH Annex XVII VOC limits:EU restrictions on volatile organic compounds in consumer coatings are compelling reformulation toward compliant ester solvents with balanced dry-time performance.
- Waterborne automotive coatings:Automotive OEMs and refinish shops are adopting butyl acetate as a co-solvent to manage flow and leveling in reduced-VOC basecoats and clearcoats.
- Electronics cleanroom demand:Asian contract manufacturers are qualifying ultra-high-purity grades for photoresist stripping and precision cleaning applications.
Market Restraints
- N-butanol feedstock volatility:Propylene-derived n-butanol pricing fluctuates with petrochemical crack spreads, compressing esterification margins during olefin upcycles.
- Integrated petrochemical concentration:Production capacity clusters in China, Germany, and the United States create geographic supply risk and logistical bottlenecks for non-integrated buyers.
- Isopropyl acetate substitution:Lower-cost acetate alternatives are capturing share in less demanding adhesive and ink applications where evaporation profile precision matters less.
Strategic Opportunities
- Pharmaceutical extraction growth:Batch-size precision requirements in agrochemical and active pharmaceutical ingredient purification are expanding demand for high-purity solvent grades.
- India specialty chemicals:PLI scheme incentives and import substitution policies are attracting esterification investment to serve domestic coatings and pharmaceutical markets.
- Solid acid catalysis:Heterogeneous catalyst systems replacing sulfuric acid are enabling modular plant designs with lower wastewater treatment burdens and faster product changeovers.
Industry Challenges
- Process analytical chemistry staffing:Ultra-high-purity electronics-grade production requires scarce talent in gas chromatography and trace-metal analysis.
- Multi-product train complexity:Esterification assets switching between butyl acetate and specialty acetates demand rigorous changeover protocols to prevent cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Acetate (BAC) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvents, Coatings, Inks, Adhesives End User: Automotive, Paints & Coatings, Chemical Manufacturing, Electronics Application: Solvent Extraction, Surface Coating, Thinning Agent, Chemical Intermediate Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Eastman Chemical Company, Sasol Ltd., BASF SE, Yangtze River Acetyls, Oxea GmbH, Celanese Corporation, INEOS Group Holdings SA, Baichuan Chemical Industrial Co., Ltd, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Acetate (BAC) Market Strategic Shifts
Process intensification and regulatory chemistry are converging to reshape how butyl acetate is manufactured, specified, and procured across industrial value chains.
Membrane-based separation technology for esterification product recovery is modularizing plant footprints and enabling distributed production closer to regional demand centers. Coatings formulators in North America and Europe are piloting these units to reduce working capital tied to bulk solvent inventory. The technology is compressing economies of scale advantages traditionally held by large integrated complexes.
EPA National Emission Standards for Hazardous Air Pollutants are tightening fugitive emission limits at solvent loading, storage, and handling facilities. Industrial coatings manufacturers are responding by specifying sealed-system delivery and closed-loop recycling services from suppliers. Small-batch architectural coatings blenders face disproportionate compliance costs relative to volume throughput.
Specification-driven procurement is consolidating solvent buying among qualified suppliers with documented purity certifications and chain-of-custody documentation. Electronics assemblers in Taiwan and South Korea are unbundling solvent supply from equipment maintenance contracts, creating direct material sourcing relationships with ester producers. This shift is compressing distributor margins and accelerating qualification timelines for ultra-high-purity grades.
Butyl Acetate (BAC) Market Segmentation
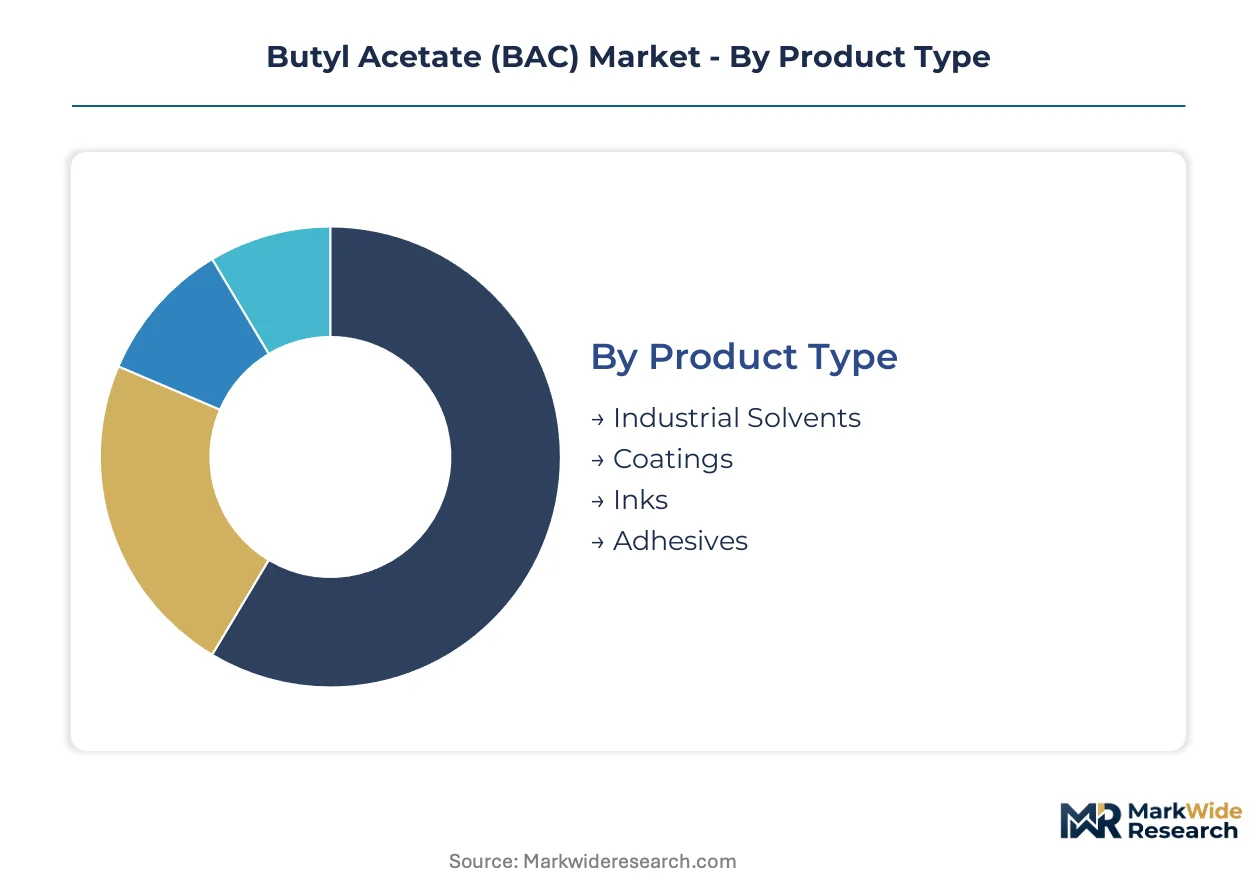
Butyl acetate demand fragments across distinct performance tiers and regulatory thresholds. Each segment imposes different purity specifications, volume scales, and compliance burdens that reshape supplier economics.
Product Type:
Capital intensity peaks in coatings-grade production, where integrated esterification trains and multi-product flexibility require the heaviest upfront investment.
- Industrial Solvents:Standard-grade material with 99.0-99.5% purity serves bulk chemical processing and general-purpose cleaning. Demand concentrates in China's Yangtze River Delta manufacturing clusters, where MEE enforcement of GB emission standards is accelerating consolidation toward captive production within petrochemical complexes.
- Coatings:Medium-evaporation formulations with controlled moisture content and low-butanol residuals dominate nitrocellulose lacquer and acrylic clearcoat systems. Automotive OEMs in Germany and the United States specify these grades for basecoat flow control as waterborne formulations displace higher-VOC alternatives.
- Inks:Fast-evaporation cuts with narrow distillation ranges serve flexographic and gravure printing applications.
- Adhesives:Plasticizer-compatible grades bond synthetic polymers in construction and packaging assembly.
Coatings absorbs the bulk of installed capacity; industrial solvents is expanding most quickly as pharmaceutical extraction applications multiply.
End User:
Margin structure varies sharply by customer scale and specification stringency, with electronics buyers commanding premium pricing for trace-metal documentation.
- Automotive:Refinish shops and OEM assembly plants specify low-photochemical reactivity grades to meet EPA National Emission Standards for Hazardous Air Pollutants. Waterborne coating adoption in Michigan and Stuttgart production facilities is restructuring procurement toward co-solvent formulations with precise evaporation control.
- Paints & Coatings:Architectural and industrial formulators represent the volume anchor, purchasing standard industrial grades through distributor networks. REACH Annex XVII VOC limits are compelling reformulation across EU-27 manufacturing sites, with sealed-system delivery requirements raising logistics costs for small-batch blenders.
- Chemical Manufacturing:Agrochemical and pharmaceutical producers drive high-purity demand for extraction and purification processes.
- Electronics:Taiwanese and South Korean contract manufacturers qualify ultra-high-purity grades for photoresist stripping and precision cleaning, unbundling solvent supply from equipment maintenance contracts.
Paints & coatings commands the deepest supplier relationships; electronics is climbing the fastest as cleanroom specifications proliferate.
Application:
Process knowledge intensity separates segments, with solvent extraction requiring the most sophisticated batch analytics and contamination control.
- Solvent Extraction:High-purity grades recover active pharmaceutical ingredients and agrochemical intermediates through liquid-liquid separation. Indian pharmaceutical manufacturers under PLI scheme incentives are expanding batch-size precision requirements, attracting esterification investment to serve domestic purification demand.
- Surface Coating:Flow and leveling control in nitrocellulose and acrylic systems represents the historical volume core. California Air Resources Board thresholds and EU F-Gas Regulation analogs are diverging compliance requirements, determining which production configurations retain cross-border shipment eligibility.
- Thinning Agent:Viscosity reduction in lacquers and adhesives demands consistent evaporation profiles.
- Chemical Intermediate:Feedstock for downstream ester synthesis requires minimal water content and acid value specifications.
Surface coating retains the broadest installed base; solvent extraction is gaining share fastest as batch analytics capabilities concentrate among qualified suppliers.
Distribution Channel:
Working capital requirements and inventory risk exposure differentiate channel economics, with direct sales locking in the longest contractual commitments.
- Direct Sales:Integrated producers such as Eastman Chemical Company and BASF SE supply automotive OEMs and electronics assemblers through multiyear offtake agreements with documented purity certifications and chain-of-custody documentation.
- Wholesale:Regional distributors aggregate standard industrial grades for mid-volume coatings manufacturers and chemical processors.
- Online Retail:Small-lot architectural and DIY purchasers access packaged solvents through e-commerce platforms with limited technical support.
- Distributors:Specialty chemical distributors serve pharmaceutical and electronics buyers with qualification assistance and inventory management services.
Direct sales captures the highest value per liter; distributors is expanding most quickly as specification-driven procurement consolidates buying among qualified intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate over half of global esterification capacity, with integrated petrochemical complexes capturing regulatory compliance advantages under MEE enforcement timelines.
United States
Automotive OEMs in Michigan and refinish networks across the Southeast drive coatings-grade consumption. EPA National Emission Standards for Hazardous Air Pollutants compel sealed-system delivery investments. Gulf Coast petrochemical corridors anchor n-butanol feedstock security for derivative ester output.
China
MEE enforcement of GB industrial emission standards is accelerating consolidation toward captive production within Yangtze River Delta and Pearl River Delta manufacturing clusters. Waterborne automotive coating adoption at Shanghai and Guangzhou assembly plants is restructuring co-solvent procurement. Domestic esterification operators face rising compliance costs.
Germany
REACH Annex XVII VOC limits are compelling reformulation across Baden-Württemberg and Bavaria coatings manufacturing sites. Stuttgart automotive OEMs specify low-photochemical reactivity grades for basecoat flow control. Ludwigshafen chemical complexes maintain multi-product esterification flexibility.
India
PLI scheme incentives are attracting esterification investment to serve Maharashtra and Gujarat pharmaceutical purification demand. CDSCO batch-size precision requirements are expanding high-purity solvent consumption. Dahej and Mundra industrial corridors concentrate import-substitution capacity builds.
South Korea
Electronics assemblers in Gyeonggi-do and Incheon free economic zones qualify ultra-high-purity grades for photoresist stripping applications. MFDS trace-metal documentation requirements command premium pricing over standard industrial material. Suwon and Pyeongtaek cleanroom clusters unbundle solvent supply from equipment maintenance contracts.
Butyl Acetate (BAC) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical complexes commanding feedstock cost advantages and modular operators capturing pharmaceutical extraction niches. The supplier base concentrates among acetyl-chain integrators and Fischer-Tropsch alcohol derivatives, creating tiered competition on purity certification rather than commodity scale. Three archetypes dominate: integrated petrochemical majors with multi-product esterification trains, regional specialists leveraging proprietary catalysis, and electronics-grade purifiers with cleanroom documentation capabilities. Capacity expansion and solid acid catalysis licensing represent the dominant competitive vectors.
Among integrated acetyl-chain operators, Eastman Chemical Company and Celanese Corporation exemplify feedstock-backward positioning across North American and Asian supply points. Sasol Ltd. anchors the Fischer-Tropsch derivative tier through South African alcohol feedstock integration. BASF SE occupies the scale-driven archetype with multi-purpose esterification assets that switch output between butyl acetate and specialty acetates based on regional margin signals. These three represent distinct strategic postures without implying specific market share figures or operational claims.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Sasol Ltd. |
| BASF SE |
| Yangtze River Acetyls |
| Oxea GmbH |
| Celanese Corporation |
| INEOS Group Holdings SA |
| Baichuan Chemical Industrial Co., Ltd |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Automotive OEMs and electronics assemblers concentrate procurement power through multiyear offtake agreements, anchoring contract-based long-term pricing that insulates integrated producers from spot volatility while squeezing modular operators on margin.
Pricing Analysis
Short lead-time premiums command substantial markups over standard delivery windows, with electronics cleanroom buyers paying steep differentials for qualified ultra-high-purity grades against standard industrial material. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification and trace-metal documentation, with pharmaceutical extraction applications least price-sensitive due to batch-precision requirements. Cost compression in coatings-grade material is intensifying because isopropyl acetate substitution captures share in less demanding adhesive applications. Small-batch architectural blenders face disproportionate price pressure relative to volume throughput.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's MEE enforcement timelines are reshaping sourcing toward captive production within Yangtze River Delta and Dahej industrial corridors. Feedstock security draws from propylene-derived n-butanol concentrated in Gulf Coast petrochemical corridors, South African Fischer-Tropsch complexes, and integrated Ludwigshafen chemical assets. Single-source vulnerability concentrates in acetyl-chain intermediates controlled by Eastman and Celanese acetyl integration. Distribution runs through direct sales relationships with documented purity certifications and chain-of-custody documentation for qualified buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into n-butanol feedstock and forward integration into specialty ester derivatives is accelerating as players race to capture margin pools and secure regulatory compliance advantages.
For Market Incumbents: Deepen captive n-butanol supply through Gulf Coast or Yangtze River Delta asset control to defend against propylene crack spread volatility. Solid acid catalysis licensing offers modular expansion with lower wastewater burdens. Isopropyl acetate substitution in adhesive applications demands rigorous changeover protocols to prevent cross-contamination on multi-product trains. For New Entrants and Emerging Players: Capture pharmaceutical extraction demand in Maharashtra and Gujarat under CDSCO batch-size precision requirements, where PLI scheme incentives reduce capital barriers. Electronics cleanroom qualification in Gyeonggi-do and Suwon clusters offers premium pricing escape from commodity coatings competition. Partner with specialty chemical distributors for qualification assistance and inventory management services. For Investors and Strategic Acquirers: The window for entry favors Fischer-Tropsch derivative specialists with proprietary alcohol feedstock integration and documented purity certification capabilities. Long-term viability hinges on regulatory compliance asymmetry between California Air Resources Board thresholds and EU F-Gas Regulation analogs. Watch for MEE enforcement acceleration in Yangtze River Delta manufacturing clusters as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Butanol Feedstock | Gulf Coast propylene security anchors esterification margin stability against olefin volatility. |
| Solid Acid Catalysis Licensing | Heterogeneous catalyst systems enable modular plant designs with faster product changeovers. |
| Ultra-High-Purity Grade Qualification | Taiwanese and South Korean electronics assemblers unbundle solvent supply for direct relationships. |
| Pharmaceutical Extraction Capacity Buildout | Indian PLI scheme incentives attract esterification investment to serve CDSCO precision demand. |
| Long-Term Supply Agreement with Automotive OEMs | Stuttgart and Michigan assembly plants specify low-photochemical reactivity grades for waterborne coatings. |
Study Parameters
SEC 10-K filings, customs and trade data, and ACC/Cefic industry reports formed the secondary backbone, cross-referenced against primary interviews with esterification plant managers, coatings procurement leads at automotive OEMs, pharmaceutical technical R&D directors, and specialty chemical distribution channel partners. Bottom-up and top-down triangulation validated volume estimates across production hub clusters.
Bottom-up modeling of grade-tier demand and end-use industry consumption patterns anchored value projections across the analysis window, with top-down macro validation against regional industrial production indices. Segmentation dimensions included purity grade tier, coatings versus electronics versus pharmaceutical end-use, and regional production hub concentration. CAGRs derived from regression analysis of historical capacity utilization and forward regulatory compliance cost trajectories, incorporating n-butanol feedstock pricing volatility and MEE enforcement timeline scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH Annex XVII VOC limit revisions, California Air Resources Board threshold divergence from EU F-Gas Regulation analogs, and propylene crack spread cyclicality. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
2-Phenylethanol Market
Solvents
Saudi Arabia Methanol Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Monochlorobenzene Market
Solvents
Xylene Market
Solvents
Aromatic Solvents Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
1, 1-Difluoroethane Market
Solvents
GCC Acetonitrile Market
Solvents
Potassium Formate Market
Solvents
Sugar Dissolvers Market
Solvents
Decanol Market
Solvents
Ethane Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
1,2-Ethanedithiol Market