
 Dimethyl Sulfoxide Market | 2026-2036
Dimethyl Sulfoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Sulfoxide Market Analysis
Project finance tied to green chemistry retrofits is rewriting competitive entry barriers for DMSO producers. Hubei Xingfa Chemicals Group leverages captive methanol supply chains to sustain cost leadership in industrial-grade output. Gaylord Chemical Company anchors North American pharmaceutical-grade capacity through specialized purification assets. Merck KGaA competes in laboratory-grade segments via stringent quality protocols that differentiate its catalog position.
Dimethyl sulfoxide is an organosulfur compound with the formula (CH3)2SO, typically manufactured through air oxidation of dimethyl sulfide or the NOx-catalyzed process, yielding a colorless, hygroscopic liquid with exceptional polar aprotic solvent properties and a boiling point of 189°C. Its primary industrial purpose centers on solubilizing polar and nonpolar substances across pharmaceutical synthesis, polymer processing, and agricultural formulations. Pharmaceutical-grade DMSO commands premium positioning due to cryopreservation and transdermal drug delivery applications, while industrial-grade volumes dominate tonnage flows into chemical processing and antifreeze formulations. The solvent application segment retains structural maturity, whereas pharmaceutical intermediate usage is accelerating fastest as biologics manufacturing expands.
EPA solvent emission standards and REACH registration requirements in Europe enforce purity thresholds and documentation burdens that filter marginal suppliers from qualified vendor lists. China's NMPA and evolving GB standards for chemical reagents impose parallel compliance layers on export-oriented producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Pharmaceutical-grade purity requirements are bifurcating the DMSO supply base into qualified and marginal tiers, with cryopreservation protocols and transdermal drug delivery specifications now dictating supplier selection criteria across contract manufacturing organizations.
Growth Catalysts
- Biologics manufacturing expansion:Cell and gene therapy production lines require pharmaceutical-grade DMSO for cryopreservation of cell cultures, pulling volume from industrial applications into higher-margin healthcare segments.
- REACH registration compliance:ECHA documentation mandates for dimethyl sulfoxide as a registered substance in Europe are filtering unqualified suppliers from qualified vendor lists, consolidating procurement toward certified producers.
- Green chemistry retrofits:Project finance for NOx-catalyzed process upgrades and carbon capture integration at production facilities is lowering lifecycle emissions profiles and unlocking preferential offtake agreements with sustainability-focused formulators.
Market Restraints
- Dimethyl sulfide feedstock volatility:Pulp and paper industry output fluctuations directly constrain DMSO production economics, as kraft pulping byproduct availability determines regional methanethiol and dimethyl sulfide supply.
- Chinese production concentration:Hubei and Shandong provinces anchor over sixty percent of global capacity, creating single-source risk for international buyers dependent on seaborne industrial-grade volumes.
- Aqueous cleaning substitute penetration:Semiconductor and electronics cleaning applications are migrating toward supercritical CO2 and formulated aqueous chemistries, compressing solvent-grade DMSO offtake in precision manufacturing.
Strategic Opportunities
- Indian pharmaceutical formulation growth:CDSCO-registered DMSO demand from injectable and topical drug manufacturers in Hyderabad and Ahmedabad clusters offers expansion runway for pharmaceutical-grade producers establishing local technical service presence.
- EU Green Deal solvent substitution incentives:REACH-authorized DMSO qualifies for preferential procurement under the EU Chemicals Strategy for Sustainability, displacing N-methyl-2-pyrrolidone in polymer processing and agricultural formulations.
- Direct-to-biotech distribution channels:Specialized cold-chain logistics partnerships with cell therapy developers are collapsing traditional distributor layers, enabling margin capture through qualified single-source supply agreements.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA Type II Drug Master File preparation and European Pharmacopoeia compliance testing require eighteen to twenty-four month qualification cycles, delaying market entry for new production assets.
- Purification asset intensity:Molecular sieve and fractional distillation infrastructure for pharmaceutical-grade output demands capital deployment multiples above industrial-grade capacity, constraining balance sheet flexibility for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Sulfoxide Market |
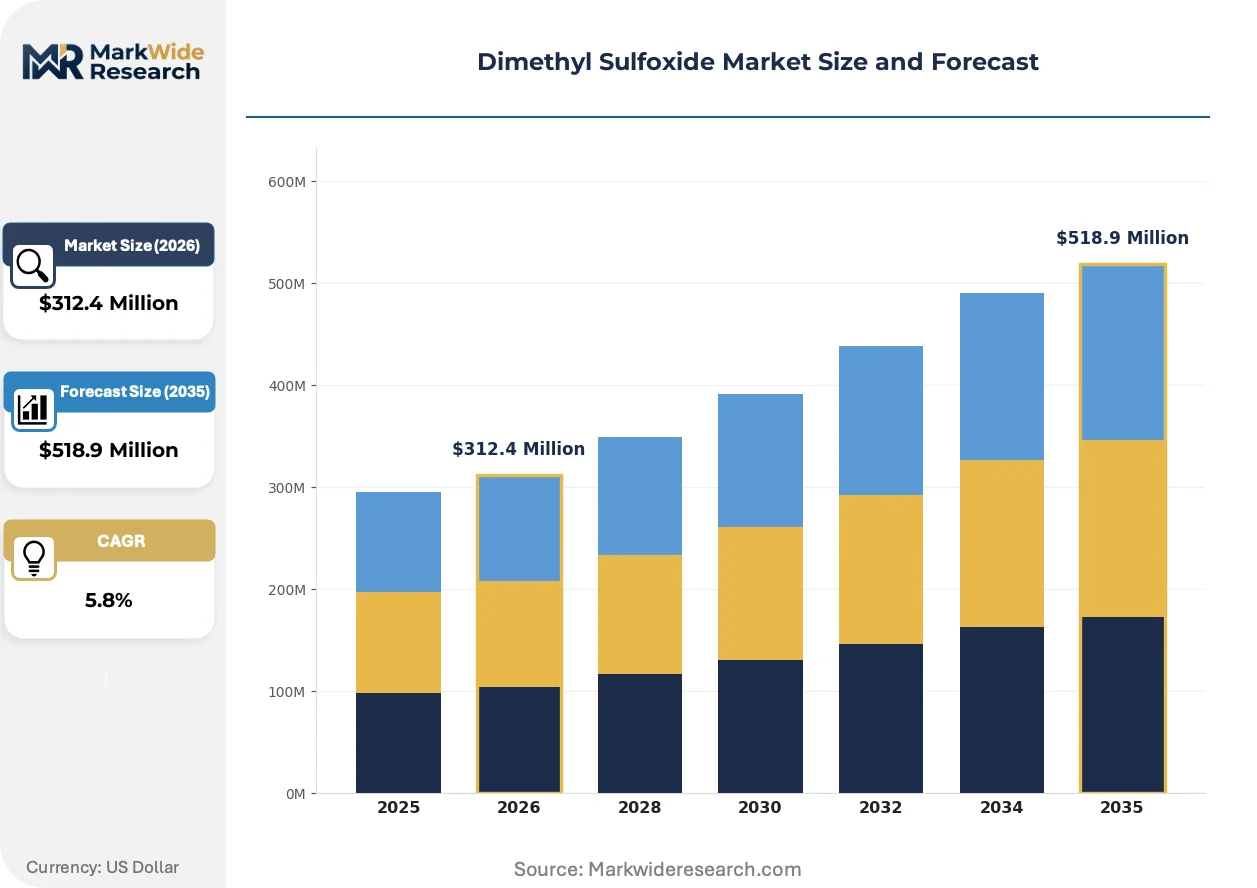
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Laboratory Grade Application: Solvent, Pharmaceutical Intermediate, Antifreeze Agent, Chemical Reagent End User: Pharmaceuticals, Chemicals, Agriculture, Cosmetics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Hubei Xingfa Chemicals Group, Yankuang Lunan Chemicals, Gaylord Chemical Company, Parchem Fine & Specialty Chemicals, Zhuzhou Hansen Chemicals, Toray Fine Chemicals, Merck KGaA, Sigma-Aldrich, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Sulfoxide Market Emerging Trajectories
Membrane separation technologies and continuous processing architectures are displacing batch purification in DMSO production, while regulatory alignment across FDA, EMA, and NMPA frameworks is compressing regional specification divergence.
Advanced pervaporation membranes for DMSO dehydration are collapsing energy requirements in the final purification stage. Pharmaceutical manufacturers in North America and Europe are adopting membrane-integrated production lines to secure USP-grade output with reduced thermal degradation risk. This technology is collapsing the capital cost differential between pharmaceutical-grade and industrial-grade production assets, enabling integrated producers to serve both segments from common infrastructure.
REACH authorization requirements for dimethyl sulfoxide as a non-restricted substance are tightening documentary burdens on importers into the European Economic Area. Downstream formulators must now verify full supply chain registration status to maintain compliant product placement. Specialty chemical distributors in Germany and the Netherlands are responding by consolidating procurement toward ECHA-registered producers with complete Only Representative documentation.
Long-term supply agreements with fixed-price escalators are replacing spot-market purchasing among large pharmaceutical contract manufacturers. This contractual shift is compressing working capital cycles for qualified DMSO producers while exposing unqualified suppliers to volume attrition. The behavior is most visible in United States biotech clusters, where cell therapy developers prioritize supply security over unit cost optimization in cryopreservation media formulation.
Dimethyl Sulfoxide Market Segmentation
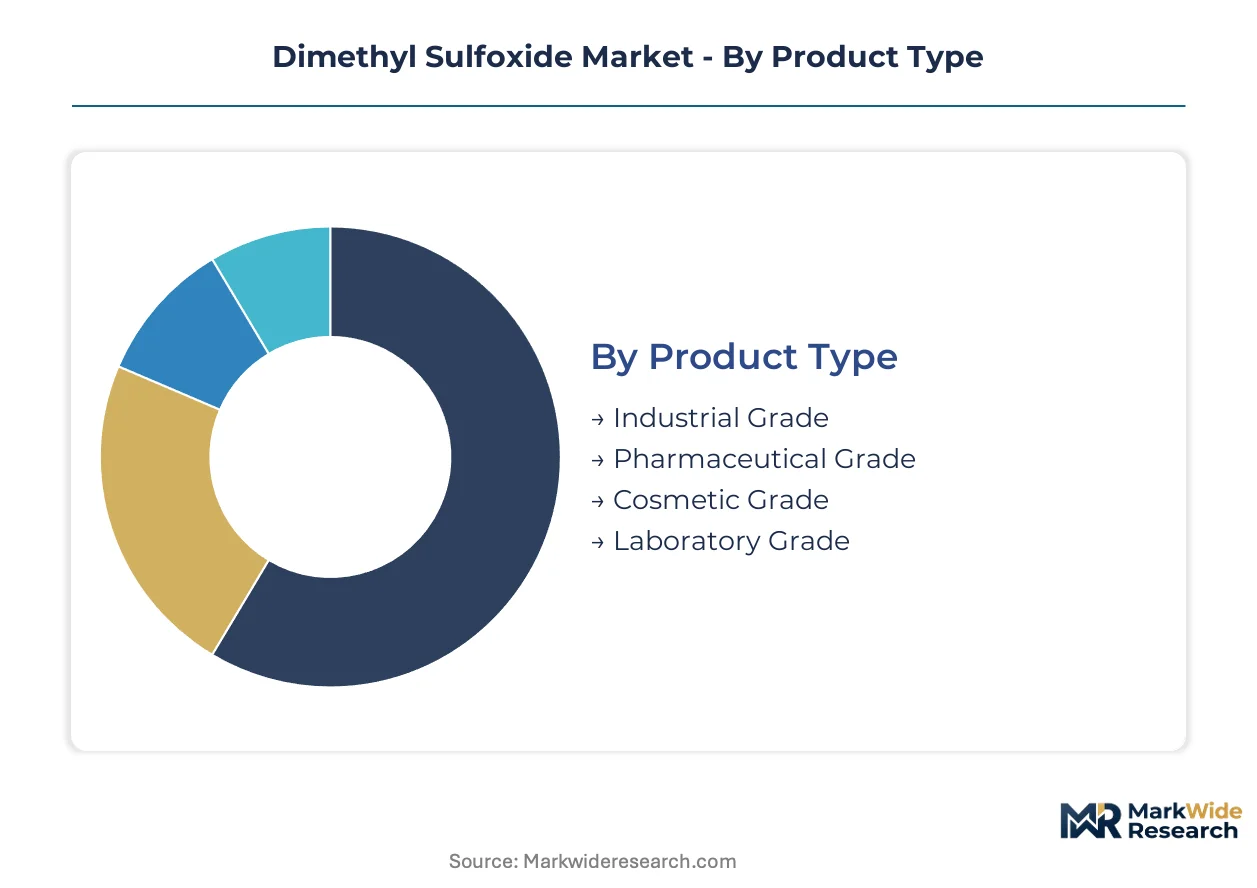
Dimethyl sulfoxide segmentation reflects divergent purity specifications and regulatory burdens that reshape procurement economics across pharmaceutical synthesis, polymer processing, and agricultural formulations. Understanding grade-specific qualification requirements and channel configurations enables suppliers to align capacity investments with margin-accretive demand pockets.
Product Type:
Use-case spectrum spans cryopreservation protocols requiring USP-grade certification through bulk chemical processing tolerating industrial-grade specifications.
- Industrial Grade:Specifications permit higher water content and trace sulfur compounds suitable for polymer spinning baths and paint stripping formulations. Chemical processors in Shandong province and the US Gulf Coast absorb volume through long-term supply contracts indexed to dimethyl sulfide feedstock costs.
- Pharmaceutical Grade:USP and European Pharmacopoeia compliance mandates sub-ppm impurity thresholds for cryopreservation and transdermal drug delivery applications. FDA Type II Drug Master File holders capture premium positioning as cell therapy manufacturers qualify single-source supply agreements.
- Cosmetic Grade:Restricted solvent residues and odor specifications serve topical formulation requirements in Korean and French personal care clusters.
- Laboratory Grade:ACS reagent specifications support analytical chemistry and research applications with modest volume but stable pricing.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Functional roles range from passive dissolution media through active pharmaceutical ingredients, with regulatory classification determining margin structure.
- Solvent:Polar aprotic characteristics enable dissolution of both polar and nonpolar compounds across polymer processing and electronics cleaning. Semiconductor manufacturers in Taiwan and Germany are migrating toward aqueous substitutes, compressing growth trajectories in precision cleaning.
- Pharmaceutical Intermediate:Cryopreservation of cell cultures and gene therapy vectors requires pharmaceutical-grade material with documented endotoxin and bioburden controls. Biologics manufacturing expansion in Massachusetts and Basel is climbing the fastest among application categories.
- Antifreeze Agent:Low toxicity profile relative to ethylene glycol supports deicing formulations and hydraulic fluid applications in cold-climate infrastructure.
- Chemical Reagent:Nucleophilic substitution reactions and oxidation chemistry consume laboratory-scale volumes with stable but limited expansion potential.
Structural maturity defines Solvent; steepest expansion trajectory defines Pharmaceutical Intermediate.
End User:
Customer concentration varies from consolidated pharmaceutical multinationals through fragmented agricultural formulators, reshaping contract structures and technical service requirements.
- Pharmaceuticals:Cryopreservation media and transdermal penetration enhancers drive qualification-intensive procurement with eighteen-month vendor approval cycles. Cell therapy developers in Cambridge and San Diego prioritize supply security over unit cost optimization.
- Chemicals:Polymer processing and agrochemical synthesis absorb industrial-grade volumes through spot-market and contract purchasing with price escalation clauses.
- Agriculture:Pesticide formulations and soil amendment applications in Brazil and India generate seasonal demand patterns with working capital intensity.
- Cosmetics:Korean and French personal care manufacturers specify cosmetic-grade material with sensory and stability testing protocols.
Margin concentration aligns with Pharmaceuticals; volume scale concentrates in Chemicals.
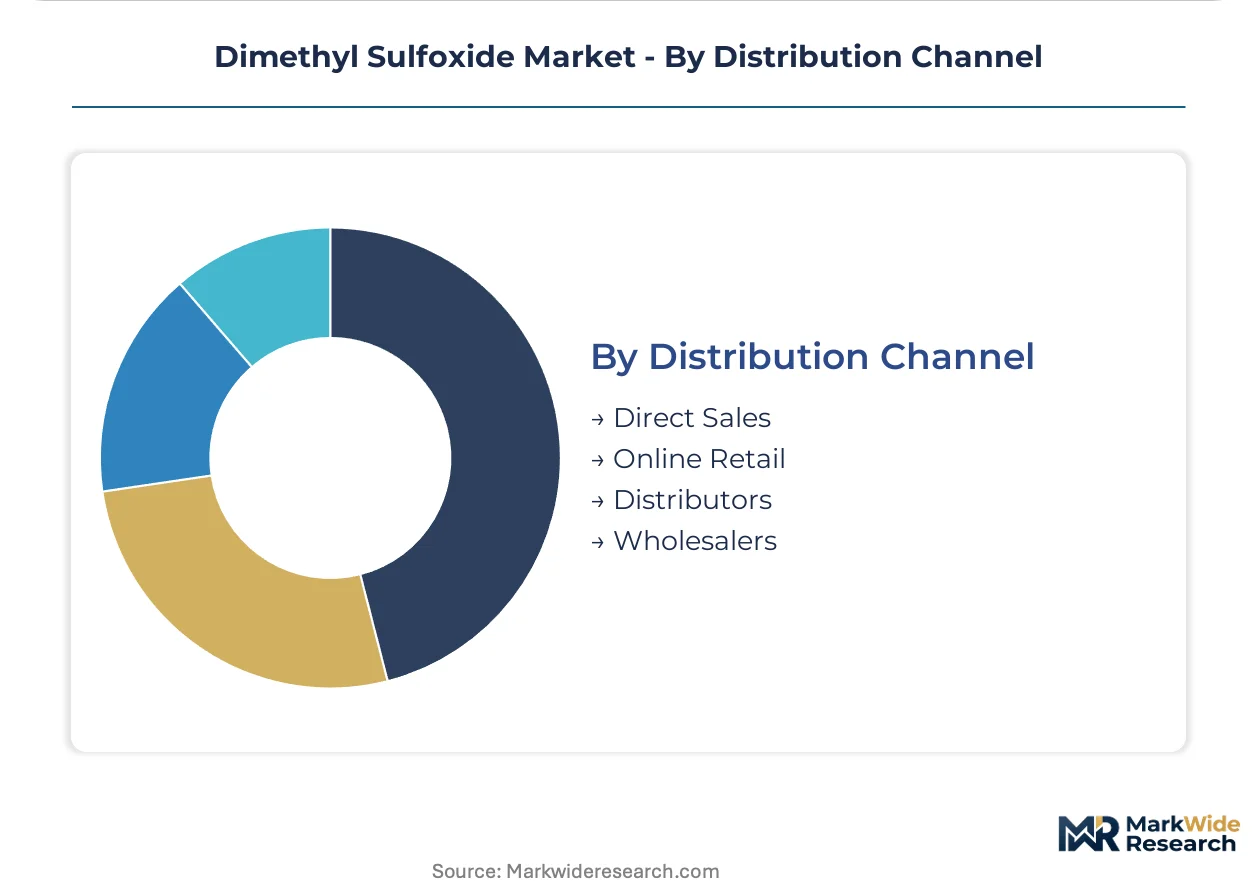
Distribution Channel:
Channel selection reflects customer scale, regulatory documentation burdens, and cold-chain requirements for pharmaceutical-grade material.
- Direct Sales:Large pharmaceutical contract manufacturers and biotech clusters negotiate multi-year supply agreements with fixed-price escalators and dedicated technical service support. This channel is expanding most quickly as cell therapy developers collapse traditional distributor layers.
- Distributors:Regional chemical distributors in Germany and the Netherlands consolidate procurement toward ECHA-registered producers with complete Only Representative documentation, filtering marginal suppliers from qualified vendor lists.
- Online Retail:Laboratory-grade and small-volume industrial purchases migrate to specialized chemical marketplaces with documented certificates of analysis.
- Wholesalers:Bulk industrial-grade volumes flow through inventory-positioning intermediaries serving fragmented chemical processors and agricultural formulators.
Relationship intensity favors Direct Sales; geographic coverage favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in Basel, Cambridge, and San Diego drive qualification-intensive procurement for cryopreservation-grade material. Chemical processors in Shandong and the US Gulf Coast absorb industrial-grade volumes through long-term supply contracts. Regulatory divergence between FDA, EMA, and NMPA frameworks reshapes supplier qualification timelines across major demand centers.
United States
Cell therapy developers in Cambridge and San Diego prioritize pharmaceutical-grade DMSO for cryopreservation media with eighteen-month vendor approval cycles. EPA solvent emission standards enforce purity thresholds that filter marginal suppliers from qualified vendor lists. The Greater Boston biotech cluster anchors North American demand for USP-grade material with documented endotoxin controls.
China
Hubei and Shandong provinces anchor over sixty percent of global production capacity, creating single-source risk for international buyers dependent on seaborne industrial-grade volumes. NMPA and evolving GB standards for chemical reagents impose compliance layers on export-oriented producers. The Yangtze River Delta concentration of methanol-based feedstock supply sustains cost leadership in industrial-grade output.
Germany
Specialty chemical distributors in Germany consolidate procurement toward ECHA-registered producers with complete Only Representative documentation. REACH authorization requirements tighten documentary burdens on importers into the European Economic Area. The Rhine-Ruhr industrial corridor absorbs polymer processing volumes through qualified supply agreements with fixed-price escalators.
India
CDSCO-registered DMSO demand from injectable and topical drug manufacturers in Hyderabad and Ahmedabad clusters offers expansion runway for pharmaceutical-grade producers. The country's national pharmaceutical regulator imposes parallel compliance requirements on imported raw materials. Gujarat's chemical processing belt generates seasonal demand patterns for industrial-grade material in agrochemical synthesis.
Japan
Electronics manufacturers in the Kanto region migrate toward aqueous substitutes and supercritical CO2, compressing solvent-grade DMSO offtake in precision cleaning applications. METI industrial standards guide solvent substitution incentives in semiconductor fabrication. The Osaka-Kobe chemical corridor maintains stable laboratory-grade consumption for analytical chemistry applications.
Dimethyl Sulfoxide Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered qualification requirements. The supply base concentrates around methanol-integrated producers with captive feedstock supply and specialized purification assets serving pharmaceutical-grade segments. Three archetypes dominate: integrated chemical conglomerates with backward control over dimethyl sulfide supply, standalone specialty solvent refiners with fractional distillation infrastructure, and laboratory chemical distributors with catalog positioning. Capacity expansion in pharmaceutical-grade assets and strategic partnerships with cell therapy developers represent the dominant competitive moves.
Within the integrated chemical tier, Hubei Xingfa Chemicals Group and Yankuang Lunan Chemicals exemplify producers with regional concentration in Shandong and Hubei provinces. Gaylord Chemical Company occupies a position among North American pharmaceutical-grade specialists. These three entities represent divergent geographic and qualification-tier positioning within the broader competitive structure.
| Leading Market Players |
|---|
| Hubei Xingfa Chemicals Group |
| Yankuang Lunan Chemicals |
| Gaylord Chemical Company |
| Parchem Fine & Specialty Chemicals |
| Zhuzhou Hansen Chemicals |
| Toray Fine Chemicals |
| Merck KGaA |
| Sigma-Aldrich |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Dimethyl sulfide feedstock volatility determines both pricing tier spreads and supply chain shape across pharmaceutical and industrial-grade segments. Kraft pulping byproduct availability constrains regional methanethiol supply, forcing contract structures that transfer commodity risk from producers to downstream formulators.
Pricing Analysis
Cost-plus contracts with dimethyl sulfide indexation dominate long-term supply agreements between Hubei producers and Gulf Coast chemical processors. Pricing stratifies across pharmaceutical-grade, industrial-grade, and laboratory-grade tiers based on purification intensity and certification documentation. Cost compression in industrial-grade volumes is intensifying because aqueous cleaning substitutes displace solvent-grade offtake in semiconductor fabrication. Agricultural formulators in Brazil exhibit highest price sensitivity, while cell therapy developers in Cambridge accept premium positioning for supply security.
Supply Chain Analysis
Contract manufacturing concentration among Lonza, Catalent, and Samsung Biologics drives pharmaceutical-grade DMSO procurement patterns. Production gravity centers on China, the United States, and Germany, with Shandong and Hubei provinces anchoring industrial-grade capacity. Feedstock draws from pulp and paper kraft pulping, methanol steam reforming, and NOx-catalyzed oxidation processes. Single-source vulnerability concentrates in Chinese industrial-grade exports dependent on Yangtze River Delta methanol supply. Distribution runs through specialty chemical distributors with ECHA-registered Only Representative documentation for European Economic Area placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by biologics manufacturing expansion, justifying capacity investments in pharmaceutical-grade purification assets.
For Market Incumbents: Insulate qualified supplier positioning by securing captive dimethyl sulfide supply through backward integration into kraft pulping partnerships or methanol-based synthesis routes. Expand molecular sieve and fractional distillation capacity in Basel and Cambridge corridors to serve cell therapy developers with eighteen-month vendor approval cycles. Prioritize FDA Type II Drug Master File maintenance and European Pharmacopoeia compliance testing to defend against emerging membrane separation technology entrants.
For New Entrants and Emerging Players: Pursue CDSCO-registered pharmaceutical-grade supply agreements with injectable manufacturers in Hyderabad and Ahmedabad clusters, where technical service presence gaps create white-space opportunity. Target direct-to-biotech distribution channels with specialized cold-chain logistics partnerships, collapsing traditional distributor layers to capture margin in cryopreservation media formulation. Lead with REACH-authorized positioning to qualify for EU Green Deal solvent substitution incentives displacing N-methyl-2-pyrrolidone.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated producers with backward feedstock control and pharmaceutical-grade certification infrastructure. Long-term viability hinges on sustainability-linked project finance access for NOx-catalyzed process upgrades and carbon capture integration. Acquisition focus should center on mid-scale Chinese producers with Yangtze River Delta methanol integration and incomplete export certification documentation. Watch for inflection in pulp and paper industry output fluctuations as early signal of feedstock cost pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dimethyl Sulfide Supply | Captive kraft pulping byproduct access secures cost leadership against methanol-based competitors in Shandong. |
| Pharmaceutical-Grade Purification Asset Expansion | Molecular sieve and fractional distillation infrastructure in Cambridge corridor serves cell therapy cryopreservation demand. |
| REACH Authorization and Only Representative Documentation | ECHA-registered status filters marginal suppliers from qualified vendor lists serving German specialty chemical distributors. |
| Direct-to-Biotech Cold-Chain Distribution Partnership | Specialized logistics agreements with San Diego cell therapy developers collapse distributor layers and capture premium margin. |
| Green Chemistry Retrofit and Carbon Capture Integration | Project finance for NOx-catalyzed process upgrades unlocks preferential offtake with sustainability-focused formulators. |
Methodological Framework
A spread of perspectives from plant managers at dimethyl sulfide oxidation facilities, procurement leads at pharmaceutical contract manufacturers, distribution channel partners in Germany and the Netherlands, and technical R&D directors at membrane separation technology developers converged on the working assumptions. Primary interview insights combined with customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed producers, and ECHA registration databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators to validate volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning grade tier, end-use industry, regional production hub, and regulatory compliance cluster. CAGRs derived from historical volume trajectories adjusted for biologics manufacturing expansion rates and solvent substitution patterns in semiconductor cleaning applications. Forecast inputs incorporated pulp and paper industry output cycles, methanol feedstock cost movements, and pharmaceutical-grade certification timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, currency exchange rates affecting Chinese export competitiveness, and energy costs governing NOx-catalyzed process economics would shift the trajectory. Forecasts reflect documented assumptions on feedstock availability, regulatory timeline adherence, and technology adoption curves. Quarterly review of kraft pulping output statistics, EMA and FDA drug approval pipelines for cell and gene therapies, and semiconductor capital expenditure announcements for cleaning equipment substitution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Meta-Xylene Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Dihydromyrcenol Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
Solvent Recovery Systems Market
Solvents
Ketone-Based Solvents Market
Solvents
Oxygenated Solvents Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Dihydromyrcene Market
Solvents
Allyl Cyanide Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Global Ethyl Lactate Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Global Tert-Butanol Market
Solvents
Europe Acetonitrile Market
Solvents
Benzene Market