
 Electronic Cleaning Solvents Market | 2026-2036
Electronic Cleaning Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Cleaning Solvents Market Intelligence
The formulation of application-specific, high-purity solvents is rewriting the competitive landscape for legacy, general-purpose degreasers. The 3M Company leverages its expertise in fluorochemicals to offer specialized solutions for sensitive components. BASF SE competes with a broad portfolio of both aqueous and solvent-based cleaners for the electronics industry. Henkel AG differentiates through its adhesive and sealant integration, offering a systems approach to electronics assembly and maintenance.
Electronic cleaning solvents are chemical formulations designed to remove contaminants like flux residues, oils, and particulates from printed circuit boards and other electronic components. These products often feature low surface tension and high solvency power to penetrate tight spaces without damaging sensitive substrates. Flux removers and surface cleaners represent the largest product type segments, essential for manufacturing quality control. Within applications, demand for PCB cleaning solutions is growing fastest, driven by the miniaturization of consumer electronics.
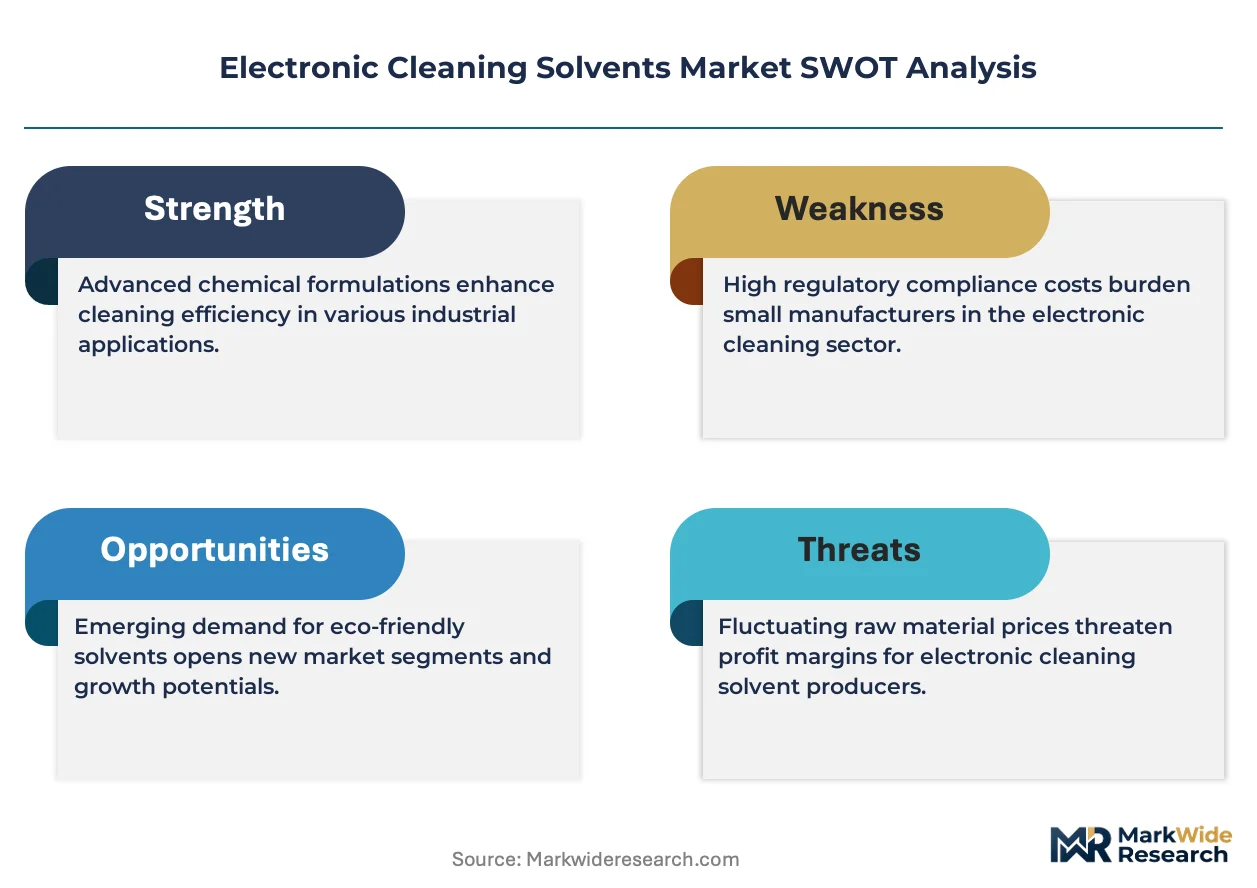
Regulatory frameworks like the EU's REACH and the US EPA's Significant New Alternatives Policy (SNAP) program steer formulation away from hazardous chemicals. These rules mandate lower volatile organic compound (VOC) content and restrict specific fluorinated compounds, impacting product availability in key markets like Germany and the United States. Vendor selection will increasingly hinge on the ability to provide globally compliant formulations that meet evolving performance and environmental standards.
Market Dynamics
The push for electronics miniaturization, coupled with stringent environmental regulations like the EU's RoHS directive, creates a dual pressure. This forces a market-wide shift from general-purpose degreasers toward high-purity, substrate-specific cleaning formulations for complex assemblies.
Growth Catalysts
- Semiconductor Expansion:Proliferation of advanced semiconductor fabs in Taiwan and South Korea requires ultra-high purity solvents for critical wafer cleaning and photolithography processes.
- Regulatory Mandates:The EU's RoHS directive compels assemblers to adopt compliant, low-VOC solvents, creating a premium for environmentally sound formulations.
- Component Miniaturization:Densely packed PCBs in consumer electronics require solvents with low surface tension to clean under low-profile components without causing damage.
Market Restraints
- Fluorochemical Price Volatility:Pricing for fluorinated solvents is tied to volatile raw material costs, compressing formulator margins and creating uncertainty for electronics assemblers.
- Regulatory Phase-Outs:The EU's REACH and US EPA's SNAP program force costly reformulation cycles by continuously restricting specific chemical compounds.
- Aqueous Cleaning Systems:Advanced aqueous cleaning technologies substitute solvent-based products for less sensitive components, limiting the addressable market for some formulations.
Strategic Opportunities
- EV Power Electronics:Electric vehicle manufacturing creates demand for solvents to clean battery management systems, inverters, and high-voltage connectors, ensuring long-term reliability.
- Bio-Based Formulations:Green chemistry incentives create an opportunity for developing bio-derived solvents as sustainable alternatives to traditional petroleum-based products.
- Indian Electronics Manufacturing:India's PLI scheme for electronics manufacturing opens a new market for suppliers supporting domestic production of smartphones and consumer devices.
Industry Challenges
- Global Compliance Complexity:Formulators face significant operational hurdles in managing a product portfolio that complies with a fragmented and evolving patchwork of chemical regulations across the EU, US, and Asia.
- Supply Chain Purity Control:Ensuring consistent, ultra-high purity levels from raw material sourcing through to final packaging is a major logistical and quality control challenge, especially for solvents used in semiconductor fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Cleaning Solvents Market |
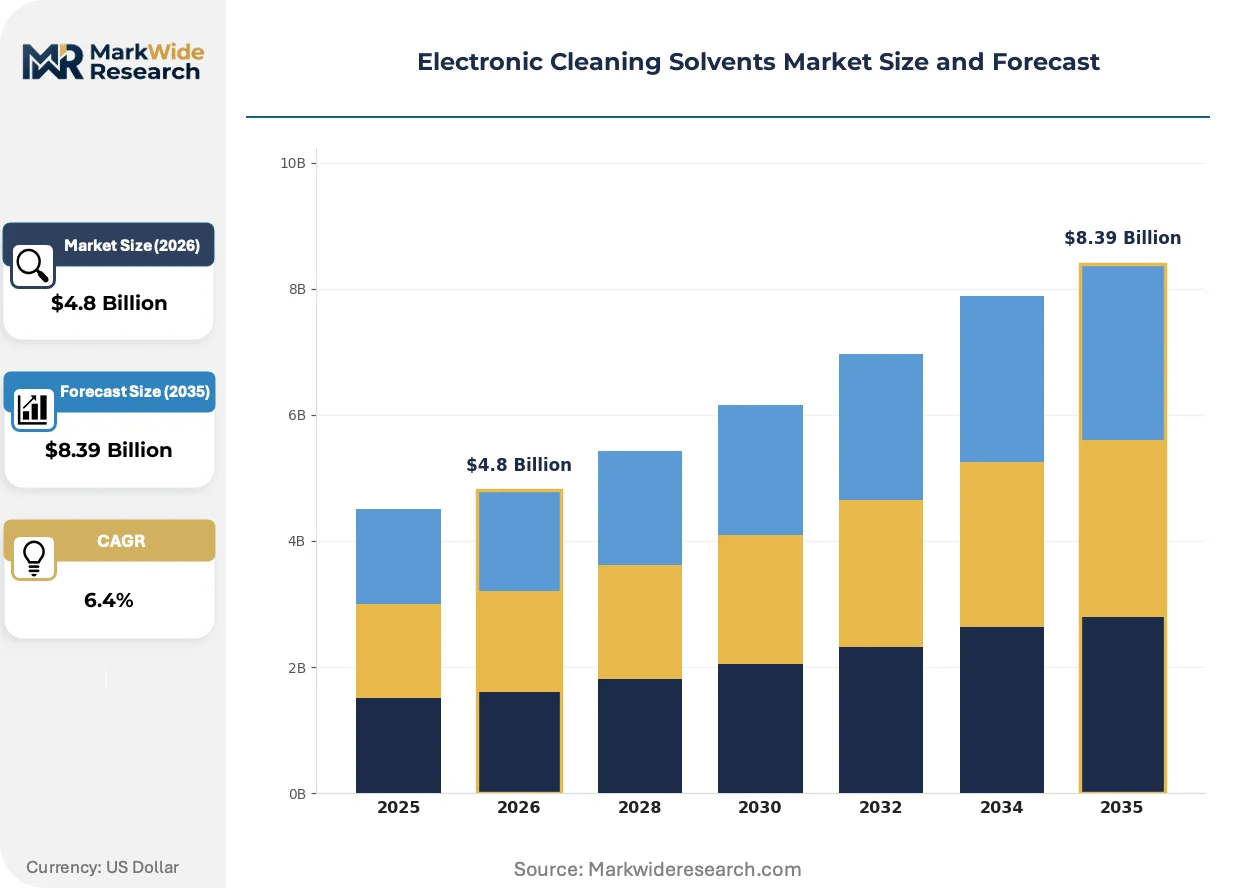
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Degreasers, Flux Removers, Surface Cleaners, Thinners Form: Aerosol, Liquid, Wipe, Gel Application: Component Cleaning, PCB Cleaning, Equipment Cleaning, Maintenance End User: Manufacturers, Repair Services, Electronic Assemblers, DIY Users |
| Companies Covered | Arkema SA, Aervoe Industries, 3M Company, Techspray, Henkel AG, BASF SE, Eastman Chemical Company, MG Chemicals, CRC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Cleaning Solvents Market Strategic Shifts & Innovations
A fundamental re-evaluation of chemical safety and performance is underway. This shift prioritizes the development of highly specialized, sustainable solvent systems designed to meet the dual demands of advanced electronics and global environmental stewardship.
Co-solvent systems, blending different chemical families, offer tailored solvency and evaporation rates for specific cleaning tasks. Electronics assemblers working with complex, multi-material components are rapidly adopting these customized blends for precision cleaning. This trend toward tailored co-solvent blends is rendering obsolete the one-size-fits-all approach of using single-chemistry, general-purpose degreasers for critical applications.
The European Union's F-Gas Regulation imposes strict quotas on fluorinated gases with high global warming potential. This impacts the availability and cost of certain HFCs and HFOs used in electronic cleaning solvents. Formulators are accelerating development of low-GWP alternatives, especially for European medical and aerospace electronics markets.
End-users in automotive and aerospace are specifying solvents with material compatibility certifications from component manufacturers. This preference bypasses traditional distributors, creating a direct technical relationship between the formulator and the end-user's engineers. The trend is most visible in Germany’s automotive electronics supply chain.
Electronic Cleaning Solvents Market Segmentation
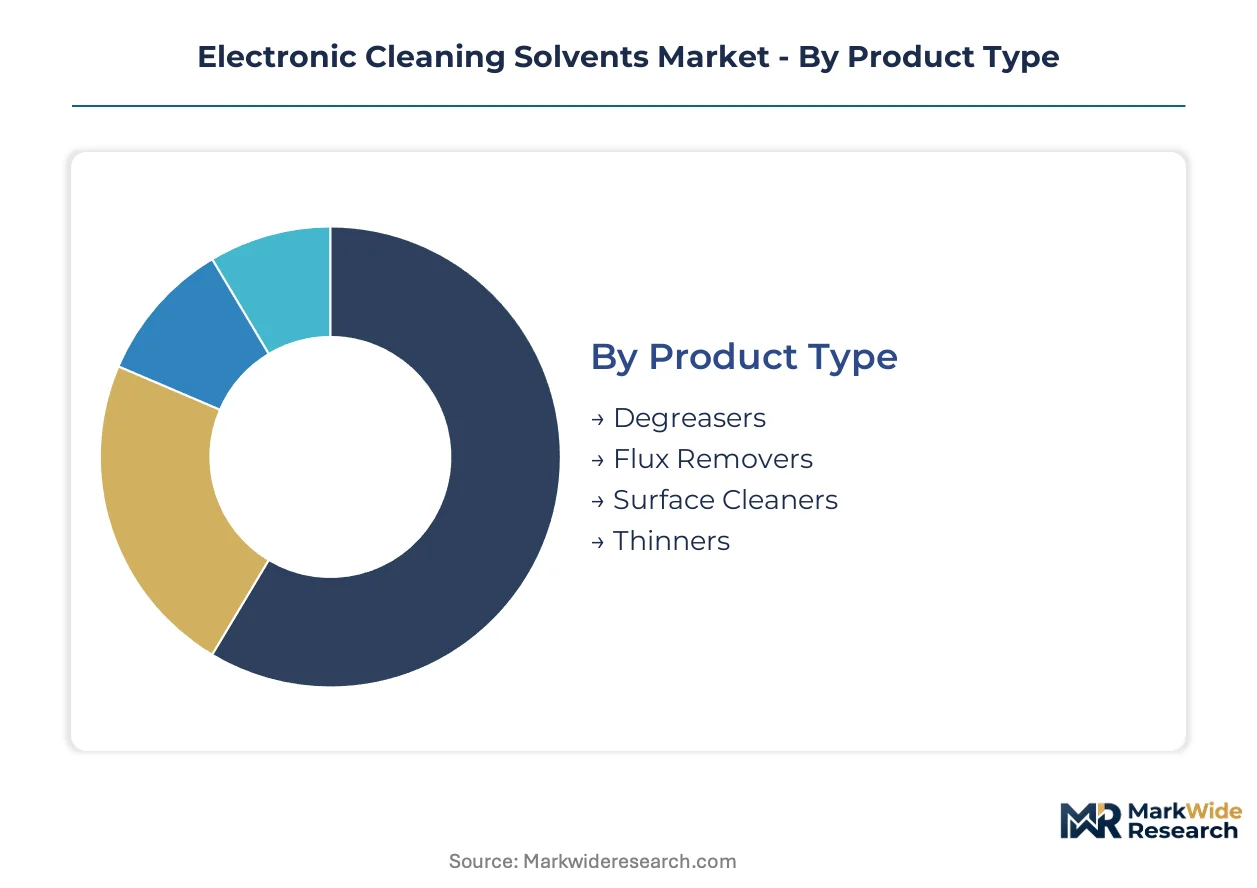
The Electronic Cleaning Solvents market structure reflects diverse requirements across manufacturing processes and maintenance protocols. Segmentation provides a granular view of product types, delivery forms, application areas, and end-user profiles. This detailed classification helps stakeholders understand specific demand patterns and regulatory influences shaping the industry.
Product Type:
The market for electronic cleaning solvents spans a wide use-case spectrum, from initial manufacturing steps to final assembly and maintenance.
- Flux Removers:These formulations are specifically engineered to dissolve and remove flux residues left after soldering processes on printed circuit boards. Demand concentrates in high-volume electronics assembly hubs like Taiwan and South Korea, driven by stringent quality control requirements for finished devices.
- Surface Cleaners:Surface cleaners are designed for broad-spectrum contaminant removal, targeting oils, dust, and particulate matter from electronic components and enclosures. Their application is expanding across consumer electronics manufacturing, particularly for densely packed PCBs requiring precision cleaning without material degradation.
- Degreasers:Degreasers are general-purpose solvents used to remove greases and heavy oils from larger electronic components or industrial equipment.
- Thinners:Thinners adjust the viscosity of conformal coatings or other protective layers applied to electronic assemblies, ensuring proper application.
Established volume favors Flux Removers; emerging adoption favors Surface Cleaners.
Form:
Product form significantly impacts application method and user convenience, contributing to varied volume contributions across segments.
- Liquid:Liquid solvents are dispensed from bulk containers for immersion cleaning, ultrasonic baths, or precision spray applications in automated systems. High-purity liquid formulations are critical for semiconductor fabrication processes in facilities across South Korea and Japan.
- Aerosol:Aerosol formats deliver solvents as a fine mist or targeted spray, ideal for spot cleaning, rework, and field maintenance where portability is essential. This delivery method sees significant demand from repair services and DIY users in the United States and Germany.
- Wipe:Solvent-saturated wipes offer controlled application and minimal waste, commonly used for surface preparation or light cleaning tasks.
- Gel:Gel formulations provide extended contact time for stubborn contaminants, preventing rapid evaporation on vertical surfaces or intricate components.
The preference for liquid forms reflects industrial scale and precision cleaning needs, while aerosol formats satisfy immediate, localized cleaning requirements.
Application:
The criticality of the cleaning process dictates the specific solvent formulation and application method within electronic manufacturing.
- PCB Cleaning:This segment involves removing flux residues, solder paste, and other contaminants from printed circuit boards to ensure electrical integrity and reliability. Demand for PCB cleaning solutions is expanding fastest, driven by the miniaturization of consumer electronics and automotive control units.
- Component Cleaning:Component cleaning focuses on preparing individual electronic parts before assembly or removing debris from sensitive components like sensors or connectors. This application demands ultra-high purity solvents to prevent damage or performance degradation in critical aerospace and medical devices.
- Equipment Cleaning:Solvents for equipment cleaning maintain manufacturing machinery, jigs, and fixtures, ensuring optimal performance and preventing cross-contamination.
- Maintenance:Maintenance applications encompass routine cleaning of electronic devices in operation, extending their lifespan and ensuring consistent functionality.
The necessity of PCB Cleaning drives demand, with Component Cleaning addressing specific high-purity requirements for sensitive parts.
End User:
Different end-user groups exhibit distinct purchasing behaviors and require tailored solvent solutions based on operational scale and technical expertise.
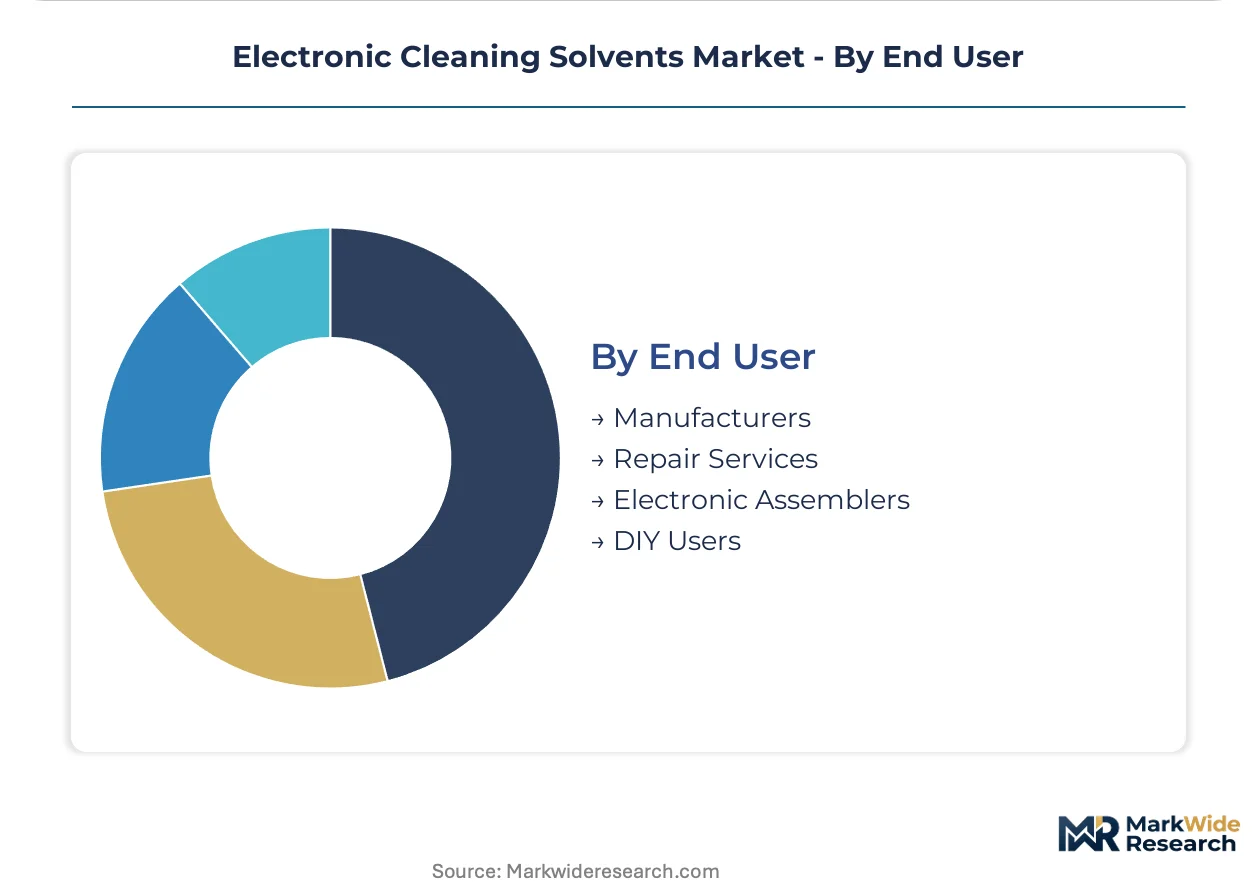
- Electronic Assemblers:These users integrate various electronic components onto printed circuit boards, requiring high-performance solvents for flux removal and surface preparation. Electronic assemblers in Germany and the United States prioritize globally compliant, low-VOC formulations due to strict environmental regulations.
- Manufacturers:Manufacturers produce electronic components, devices, or systems, utilizing cleaning solvents throughout their production lines for various stages. Advanced semiconductor fabs in Taiwan and South Korea represent a significant segment of manufacturers requiring ultra-high purity solvents for wafer processing.
- Repair Services:Repair services utilize cleaning solvents for diagnostics, component replacement, and refurbishment of electronic devices across various industries.
- DIY Users:Do-It-Yourself users employ electronic cleaning solvents for personal device maintenance, hobbyist projects, or small-scale repairs.
Demand from Electronic Assemblers dominates, though Repair Services represent a specialized niche requiring versatile solvent solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for electronic cleaning solvents varies significantly by end-use segment. High-purity solvents for semiconductor fabrication exhibit low price sensitivity, driven by critical performance requirements. Conversely, general-purpose degreasers for maintenance applications face greater price pressure from alternative cleaning methods.
South Korea
South Korea's robust semiconductor industry drives substantial demand for ultra-high purity cleaning solvents. The country's MFDS regulations influence formulation choices for electronics used in medical devices. Major semiconductor fabrication facilities in Suwon and Gyeonggi Province require specialized solvents for critical wafer cleaning processes.
Taiwan
Taiwan anchors global demand for advanced PCB cleaning solutions due to its dominant position in electronics manufacturing. Local environmental regulations increasingly compel manufacturers to adopt low-VOC and compliant formulations. The Hsinchu Science Park, a key technology hub, concentrates production of high-density PCBs requiring precision cleaning.
United States
The United States market requires high-performance solvents for aerospace, defense, and medical electronics manufacturing. The US EPA's Significant New Alternatives Policy (SNAP) program steers product development away from hazardous chemicals. Silicon Valley in California remains a significant cluster for high-tech electronics production and R&D.
Germany
Germany's automotive electronics and precision engineering sectors generate consistent demand for specialized cleaning solvents. EU's REACH and the F-Gas Regulation significantly impact the availability and formulation of fluorinated compounds. Automotive electronics suppliers in Stuttgart and Bavaria prioritize material compatibility certifications for critical components.
India
India's burgeoning electronics manufacturing sector, supported by the PLI scheme, creates new demand for cleaning solvents. BIS standards are becoming increasingly relevant for products sold within the domestic market. Bengaluru, a major tech hub in Karnataka, sees expansion in smartphone and consumer electronics assembly.
Electronic Cleaning Solvents Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the electronic cleaning solvents market. The industry exhibits a tiered structure, with specialized formulators competing on performance and compliance, while larger chemical conglomerates leverage broad portfolios. Strategic archetypes include niche specialists, diversified chemical suppliers, and integrated electronics solution providers. Key competitive moves involve portfolio diversification into compliant formulations and strategic partnerships for specialized component material certification.
Within the diversified chemical supplier archetype, BASF SE, a German-based AG, exemplifies a broad portfolio approach, offering both aqueous and solvent-based cleaning solutions. The 3M Company, a US-based entity, represents specialized solutions, leveraging its expertise in fluorochemicals for sensitive components. Henkel AG, another German-based company, occupies a position focused on integrated adhesive and sealant solutions, supporting a systems approach to electronics assembly and maintenance. These entities anchor the market for high-performance and compliant formulations required by advanced electronics manufacturing.
| Leading Market Players |
|---|
| Arkema SA |
| Aervoe Industries |
| 3M Company |
| Techspray |
| Henkel AG |
| BASF SE |
| Eastman Chemical Company |
| MG Chemicals |
| CRC Industries |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, crucial for transporting specialty chemicals, directly impact the cost dynamics of electronic cleaning solvents, influencing both supply concentration and downstream price differentiation. The market's structural evolution reflects a fundamental re-evaluation of chemical safety and performance.
Pricing Analysis
Technical support contracts and application engineering services often drive lifetime value for high-purity solvent suppliers, moving beyond transactional sales. The dominant pricing model for specialty electronic cleaning solvents is contract-based long-term offtake, particularly for large manufacturers. Price differentiation stems from the solvent's purity grade and specific compliance certifications like EU REACH. Pricing pressure stems from fluorochemical price volatility, compressing formulator margins for certain product types. Semiconductor fabrication facilities exhibit the lowest price sensitivity, prioritizing performance and purity, while DIY users show higher price sensitivity.
Supply Chain Analysis
Fluorochemical price volatility dominates the supply chain risk profile for many advanced electronic cleaning solvents, impacting raw material costs. Geographic supply concentration for specialty chemical inputs primarily involves Germany, the United States, and South Korea. Raw material dependencies center on fluorochemicals and petroleum-based feedstocks. Ensuring consistent, ultra-high purity levels from sourcing through final packaging presents a significant logistical and quality control challenge. Downstream distribution runs through a hybrid model of direct sales to major electronic assemblers and manufacturers, supplemented by specialized distributors for smaller-scale users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Cleaning Solvents market represents an early-cycle expansion story, driven by the increasing demand from EV power electronics manufacturing. This sector requires highly reliable, precision cleaning solutions for critical components.
For Market Incumbents:Pre-empt regulatory phase-outs by accelerating R&D into low-GWP alternatives and bio-based formulations. Diversify product portfolios to offer globally compliant formulations, addressing the fragmented regulatory landscape. Invest in advanced purity control systems to meet the stringent demands of semiconductor fabrication. Form strategic partnerships with component manufacturers to secure material compatibility certifications, a critical lever in Germany's automotive electronics supply chain.
For New Entrants and Emerging Players:Build out specialized co-solvent systems tailored for complex, multi-material components, targeting precision cleaning applications. Focus on India's burgeoning electronics manufacturing sector, leveraging the PLI scheme for market entry. The most penetrable segment for new players involves application-specific solutions for consumer electronics, particularly in regions with less established local supply. Establish direct technical relationships with end-user engineers to co-develop and certify novel cleaning solutions.
For Investors and Strategic Acquirers:Specialized formulators with robust intellectual property in green chemistry and application-specific solutions present attractive long-term acquisition targets. These firms often possess critical expertise in navigating complex regulatory frameworks and developing high-purity formulations. A key signal to watch as an inflection indicator is the increasing adoption rates of low-GWP alternatives across European medical and aerospace electronics markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry R&D Investment | Develop sustainable, bio-based alternatives to traditional petroleum-derived solvents, aligning with global environmental stewardship goals. |
| Global Regulatory Compliance Certification | Ensure product portfolios meet evolving chemical regulations across the EU, US, and Asia, facilitating market access. |
| Strategic Partnership with OEM Engineers | Co-develop and certify cleaning solutions directly with end-users, ensuring material compatibility for critical components. |
| Advanced Purity Control Systems | Implement rigorous quality control throughout the supply chain, vital for ultra-high purity solvents in semiconductor fabrication. |
| Targeted Geographic Expansion | Enter high-growth markets like India, supporting domestic electronics manufacturing initiatives under the PLI scheme. |
Research Approach
Initial hypotheses were tested against primary input from R&D chemists, procurement managers at semiconductor fabs, environmental compliance officers, and electronics assembly line supervisors and refined iteratively. This process combined in-depth interviews with extensive secondary validation, utilizing EU REACH/RoHS documents, US EPA SNAP reports, industry association publications, and patent databases. Bottom-up and top-down triangulation ensured data consistency and comprehensive market coverage.
The analytical framework focused on demand-supply balance, integrating macroeconomic indicators with industry-specific drivers across the analysis window. Segmentation dimensions modeled included product type, form, application, end-user, and purity grade. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected market dynamics, incorporating key inputs such as semiconductor capital expenditure and consumer electronics production volumes.
Stress conditions across major geopolitical trade shifts and unforeseen chemical bans were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Nitrochlorobenzene Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Tetraethyl Benzene Market
Solvents
Aliphatic Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Coating Solvents Market
Solvents
Isopropylamine Market
Solvents
North America Toluene Market
Solvents
Global Ethyl Lactate Market
Solvents
Hydrocarbon Solvents Market
Solvents
Butane Market
Solvents
Japan Acetonitrile Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Europe Acetonitrile Market
Solvents
Ethoxydiglycol Market