
 Ethylene Glycol Market | 2026-2036
Ethylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Glycol Market Intelligence
A shift from single-source ethylene supply toward multi-source feedstock procurement is restructuring procurement economics for integrated glycol producers. SABIC leverages captive naphtha cracking in the Middle East to sustain cost-advantaged monoethylene glycol output for Asian polyester makers. Indorama Ventures anchors its competitive position through backward integration into PET resin, while BASF SE differentiates via specialty-grade diethylene glycol formulations for European coatings customers.
Ethylene glycol is a vicinal diol with the formula C₂H₆O₂, produced industrially through ethylene oxide hydration at temperatures near 200°C and pressures of 10-30 bar, serving primarily as a polyester precursor and engine coolant base stock. Monoethylene glycol dominates volume demand as the essential feedstock for polyethylene terephthalate bottle and fiber production, while triethylene glycol commands premium pricing in natural gas dehydration applications where ultra-low dew points are specified. Diethylene glycol occupies a mature niche in unsaturated polyester resins, with margin pools shifting toward high-purity grades for pharmaceutical excipient use.
The US EPA regulates ethylene glycol under TSCA Section 5 for new chemical notifications, while REACH in Europe mandates registration and hazard communication for imported volumes above one tonne annually. China's MEE enforces GB 31571 emissions standards for ethylene oxide plants, tightening air-quality compliance costs for coal-based producers. Stakeholders must monitor feedstock-switching economics as naphtha-gas differentials and carbon-border adjustment mechanisms reshape location decisions for new capacity additions.
Market Dynamics
Polyester fiber manufacturers are consolidating procurement around ethylene glycol suppliers with verified bio-based feedstock chains, pressuring conventional naphtha-derived producers to certify carbon intensity or lose volume commitments.
Growth Catalysts
- EU Green Deal textile mandates:Recycled PET quotas in apparel manufacturing are pulling virgin-grade monoethylene glycol through certified mass-balance accounting, rewarding producers with ISCC PLUS accreditation.
- Natural gas dehydration expansion:Triethylene glycol specifications for ultra-low dew point processing in LNG export terminals are tightening purity requirements and extending contract durations.
- Coal-to-chemicals retrofitting:China's dual carbon goals are forcing syngas-based ethylene oxide plants to install carbon capture, creating temporary supply tightness during upgrade cycles.
Market Restraints
- Naphtha-ethane feedstock volatility:Cracker operators in the Middle East face margin compression when ethane export quotas tighten and naphtha differentials swing beyond $150 per tonne.
- MEE emissions compliance costs:China's GB 31571 standards for ethylene oxide stack emissions are forcing coal-based producers to install wet electrostatic precipitators, adding $8-12 per tonne to delivered costs.
- Biopolymer substitution threat:Polyhydroxyalkanoate packaging films are capturing niche beverage applications where brand owners prioritize marine biodegradability over mechanical recycling compatibility.
Strategic Opportunities
- India polyester capacity buildout:Reliance Industries and Indorama Ventures are expanding purified terephthalic acid complexes in Gujarat, creating captive offtake demand for imported monoethylene glycol.
- Pharmaceutical-grade diethylene glycol:Excipient certification under USP and EP monographs is opening margin pools 3-4x above industrial grades for producers with dedicated GMP lines.
- Electrolyte additive convergence:Battery-grade ethylene carbonate synthesis is converging with ethylene oxide derivatives, allowing glycol producers to pivot toward electric vehicle chemical supply chains.
Industry Challenges
- Process safety engineering scarcity:Ethylene oxide plant design and hazard operability review expertise has concentrated among retiring specialists, extending project timelines for new capacity.
- Legacy DCS integration friction:Brownfield glycol units running Honeywell TDC 3000 or Yokogawa CENTUM systems face cybersecurity retrofit costs when connecting to cloud-based predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Glycol Market |
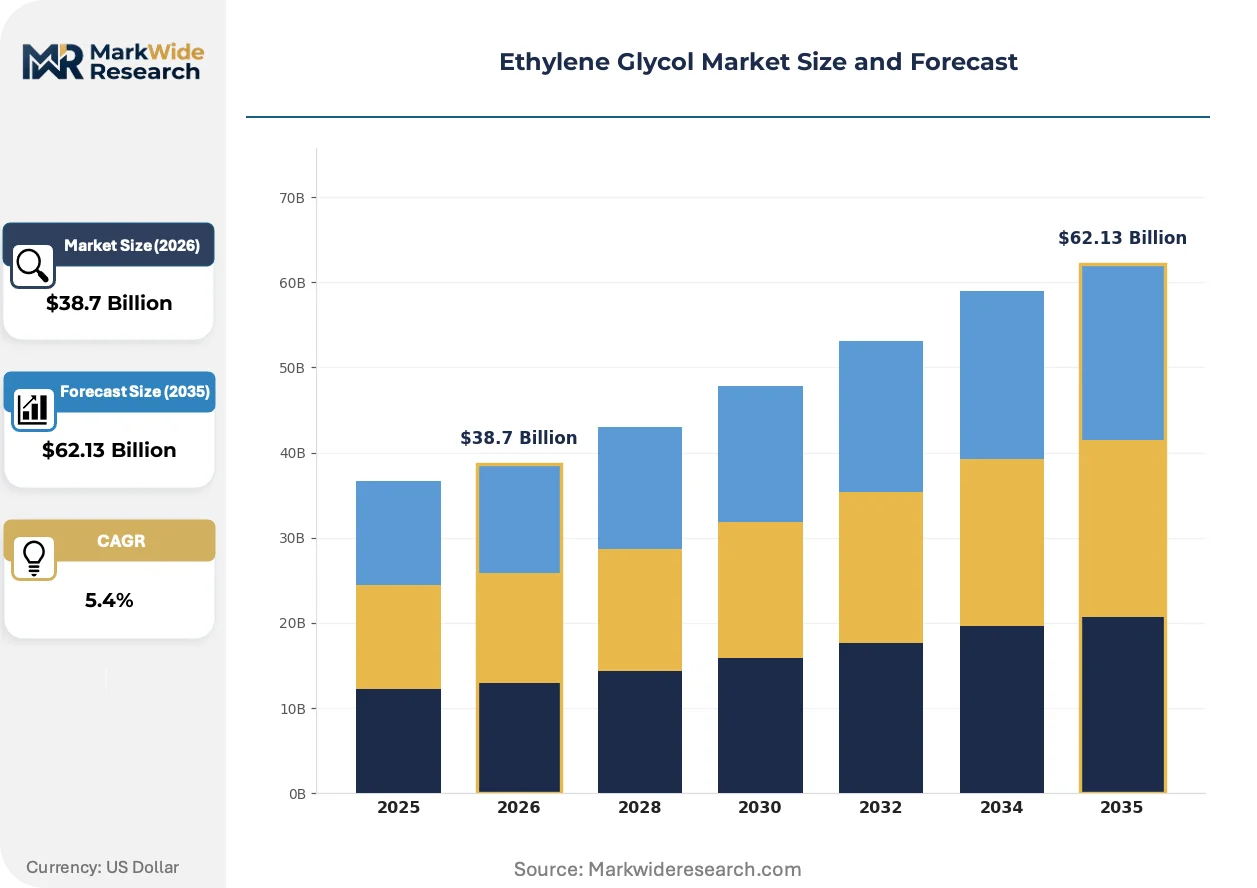
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Diethylene Glycol, Triethylene Glycol, Others End Use Industry: Automotive, Pharmaceuticals, Textiles, Antifreeze Application: Coolants, Polyesters, Resins, Dehydrating Agents Distribution Channel: Direct Sales, Distributors, Online Retail, B2B Platforms |
| Companies Covered | SABIC, Indorama Ventures, BASF SE, Eastman Chemical Company, INEOS Group Holdings, China Petrochemical Corporation, ExxonMobil Corporation, Reliance Industries, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Glycol Market Strategic Shifts & Innovations
Catalytic process intensification and carbon-accounting transparency are restructuring how ethylene glycol producers compete on cost and compliance simultaneously.
Membrane-based ethylene oxide purification is converging with electrochemical ethylene production, allowing pilot plants in the Netherlands to bypass conventional thermal cracking entirely. Textile brands with Science Based Targets initiative commitments are prioritizing offtake from these demonstration facilities despite 15-20% cost premiums.
REACH authorization requirements for ethylene oxide under Annex XIV are forcing European coatings formulators to document substitution plans or secure time-limited exemptions. German and Belgian glycol distributors are consolidating warehousing to shared tank terminals with automated sampling, reducing per-tonne handling costs while maintaining chain-of-custody records for downstream audit trails.
Buyers in the unsaturated polyester resin segment are unbundling technical service from material supply, contracting directly with application laboratories for formulation support while sourcing commodity diethylene glycol through spot markets. This disintermediation is compressing distributor margins in Italy and Spain, where historical relationships had sustained premium pricing for bundled offerings.
Ethylene Glycol Market Segmentation
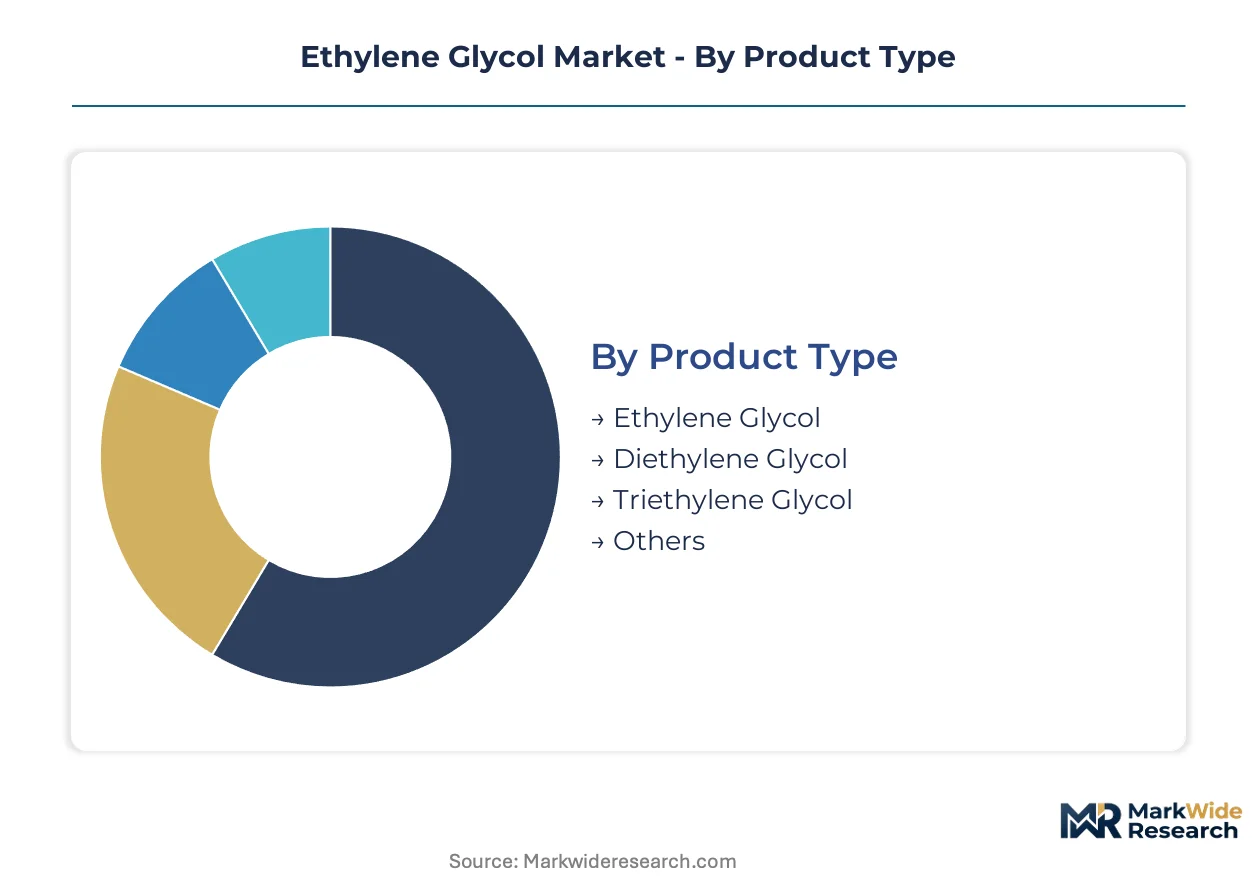
Ethylene glycol producers face divergent capital requirements across product grades, with pharmaceutical and battery-grade specifications demanding dedicated purification trains while industrial volumes flow through commodity-scale units. Segmentation discipline separates margin-accretive specialty positions from cost-driven bulk supply, determining where integrated players allocate incremental capacity investments.
Product Type:
Capital intensity varies sharply across glycol homologues, with ultra-high-purity triethylene glycol requiring multi-stage distillation trains that cost multiples of standard monoethylene glycol units.
- Ethylene Glycol:The simplest vicinal diol, produced via direct hydration of ethylene oxide under catalytic conditions. Demand concentrates in China, where Sinopec and private refiners anchor integrated ethylene-to-EG capacity along the Yangtze River Delta, driven by polyester fiber and PET resin offtake from textile manufacturers.
- Diethylene Glycol:A co-product from ethylene oxide hydration, distinguished by its higher molecular weight and hygroscopic properties. Pharmaceutical-grade specifications for excipient use under USP and EP monographs command premium positioning in European and North American markets, with margin pools substantially above industrial grades.
- Triethylene Glycol:Purified to sub-ppm water specifications for natural gas dehydration, requiring specialized molecular sieve integration.
- Others:Higher glycols including tetraethylene glycol, serving niche solvent and lubricant additive applications.
Most installed capacity flows through Ethylene Glycol. Expansion is steepest in Triethylene Glycol.
End Use Industry:
Customer concentration patterns determine contract structures, with automotive OEMs negotiating multi-year offtake agreements while pharmaceutical buyers demand batch-level certification.
- Automotive:Engine coolant formulations specify corrosion-inhibited ethylene glycol blends with defined pH buffering and foam suppression characteristics. OEM procurement in Germany, Japan, and the United States favors suppliers with IATF 16949 certification and regional blending capabilities.
- Textiles:Polyester fiber and PET resin production consumes monoethylene glycol at massive scale, with recycled PET mandates under EU Green Deal frameworks pulling certified mass-balance material through verified supply chains.
- Pharmaceuticals:Excipient-grade diethylene glycol demands dedicated GMP production lines with full batch traceability.
- Antifreeze:Seasonal demand patterns in cold-climate markets drive inventory management complexity.
Volume concentrates in Textiles. Value expansion is fastest in Pharmaceuticals.
Application:
Performance specifications fragment the addressable market, with dehydration applications tolerating narrow purity bands while battery electrolyte precursors require sub-10 ppm chloride levels.
- Coolants:Heat transfer fluids for internal combustion engines and industrial systems, formulated with corrosion inhibitor packages meeting ASTM D3306 or OEM-specific standards. Demand in the United States and Europe is stabilizing as electric vehicle penetration reduces engine coolant volumes per vehicle.
- Polyesters:PET resin and fiber production, where monoethylene glycol reacts with purified terephthalic acid in continuous polymerization trains. India's Gujarat corridor is attracting capacity expansion from Reliance Industries and Indorama Ventures, creating captive offtake demand for imported glycol.
- Resins:Unsaturated polyester formulations for composites and coatings.
- Dehydrating Agents:Triethylene glycol absorption systems for natural gas processing, specifying ultra-low dew point performance.
Polyesters absorb the greatest volume. Dehydrating Agents are climbing the fastest.
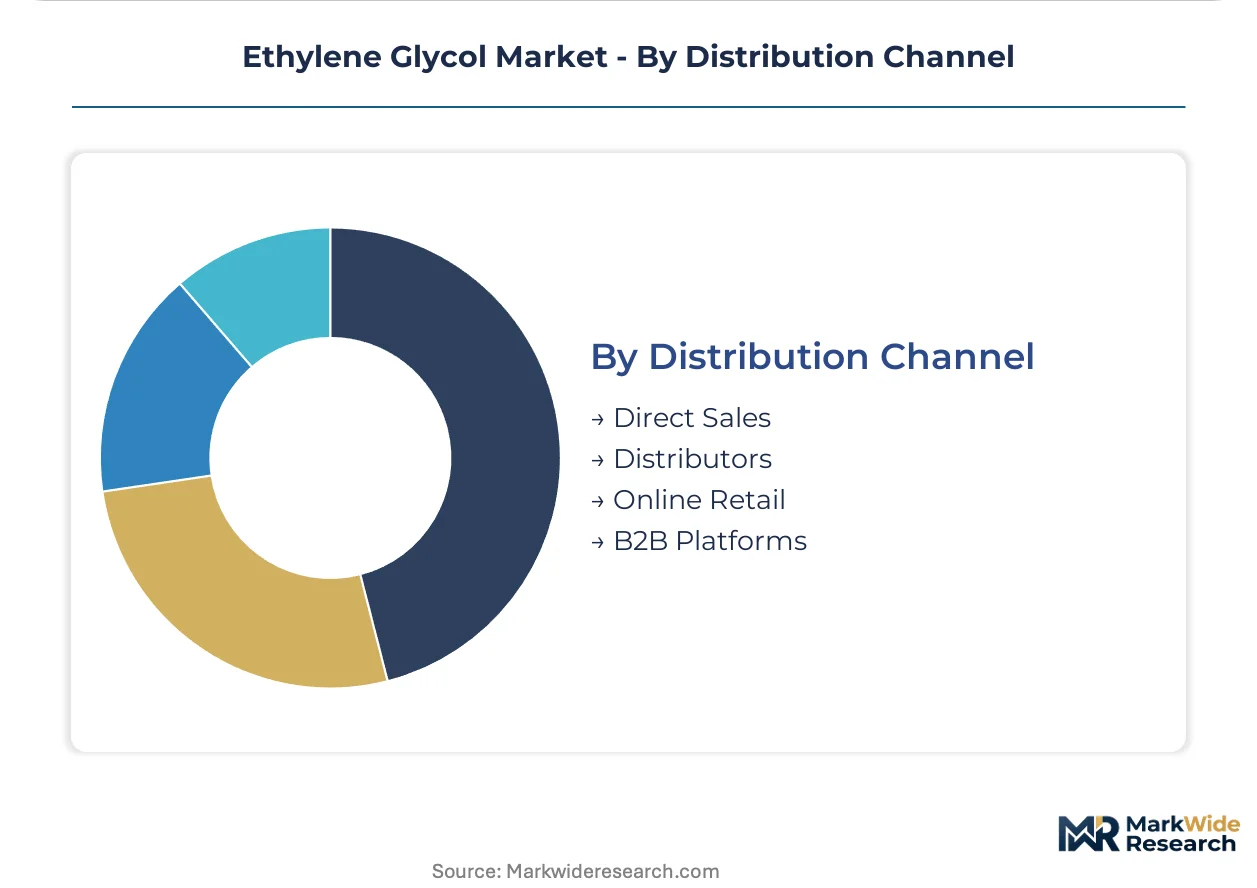
Distribution Channel:
Channel economics reflect shipment scale and certification burden, with direct sales capturing bulk industrial volumes while distributors manage fragmented specialty offtake.
- Direct Sales:Tanker-truck and railcar deliveries to integrated polyester producers and automotive coolant blenders, minimizing handling costs for high-volume, specification-stable material. SABIC and Indorama Ventures leverage captive logistics networks across Middle Eastern and Asian production hubs.
- Distributors:Regional warehousing with automated sampling and chain-of-custody documentation, consolidating compliance costs for smaller coatings and pharmaceutical formulators in Italy, Spain, and Belgium.
- Online Retail:Packaged coolant and antifreeze products for aftermarket consumption.
- B2B Platforms:Spot market liquidity for standard-grade material, enabling price discovery for non-integrated buyers.
Direct Sales handles the largest tonnage. B2B Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global ethylene glycol production capacity, with Sinopec and private refiners operating integrated ethylene-to-EG complexes that feed polyester fiber mills throughout East China. National regulators across major consuming markets are tightening emissions standards and carbon-accounting requirements, reshaping where producers locate new capacity and how they certify feedstock origins.
China
Coal-to-chemicals producers in Shaanxi and Inner Mongolia face MEE enforcement of GB 31571 emissions standards, forcing wet electrostatic precipitator installations that add compliance costs. The dual carbon policy is accelerating syngas-based plant retrofits with carbon capture, creating temporary supply tightness during upgrade cycles at facilities supplying Yangtze Delta polyester manufacturers.
United States
Gulf Coast ethane crackers supply cost-advantaged ethylene feedstock to EG units in Texas and Louisiana, though EPA TSCA Section 5 notifications add regulatory friction for new chemical introductions. The Permian Basin's associated gas production underpins feedstock economics, while automotive coolant demand stabilizes as electric vehicle penetration reduces per-vehicle engine fluid volumes.
Germany
REACH Annex XIV authorization requirements for ethylene oxide are forcing coatings formulators to document substitution plans or secure time-limited exemptions. BASF SE operates specialty-grade diethylene glycol purification trains in Ludwigshafen serving pharmaceutical excipient customers, with ECHA hazard communication mandates adding documentation burdens for imported volumes above one tonne annually.
Saudi Arabia
SABIC leverages captive naphtha cracking at Jubail Industrial City to sustain cost-advantaged monoethylene glycol output for Asian polyester makers. The Kingdom's ethane allocation policies and export quota frameworks determine cracker operator margins, with Red Sea shipping routes connecting production to Gujarat's expanding PTA complexes.
India
Reliance Industries and Indorama Ventures are expanding purified terephthalic acid complexes in Gujarat, creating captive offtake demand for imported monoethylene glycol. CDSCO pharmaceutical regulations and BIS industrial standards shape import specifications, while the PLI scheme for textiles is pulling certified mass-balance material through verified supply chains.
Ethylene Glycol Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock certification and electrochemical process demonstration. The market structure reflects moderate consolidation among integrated petrochemical majors with captive ethylene supply, alongside regional specialists serving pharmaceutical and coatings grades. Three archetypes dominate: Gulf-based feedstock-advantaged suppliers, Asian polyester-integrated producers, and European specialty-grade formulators. Competitive moves center on backward integration into PET resin and capacity expansion in high-growth demand corridors.
Within the integrated multinational tier, SABIC and Indorama Ventures exemplify divergent strategic positions. SABIC anchors Middle Eastern supply through Jubail-based operations, while Indorama Ventures pursues polyester chain integration from glycol through resin. BASF SE occupies the specialty-grade vector, with Ludwigshafen facilities serving European pharmaceutical and coatings customers under REACH compliance frameworks. These three entities represent the dominant competitive archetypes: feedstock-advantaged Gulf supply, Asian demand-integrated production, and European premium-grade formulation.
| Leading Market Players |
|---|
| SABIC |
| Indorama Ventures |
| BASF SE |
| Eastman Chemical Company |
| INEOS Group Holdings |
| China Petrochemical Corporation |
| ExxonMobil Corporation |
| Reliance Industries |
| LyondellBasell Industries |
| Others |
Cost & Logistics Intelligence
Process safety engineering scarcity in Jubail and the Yangtze River Delta compresses labor-cost differentials between Middle Eastern and Chinese production hubs, widening pricing-tier spreads as pharmaceutical-grade specifications command premium positioning over industrial monoethylene glycol volumes.
Pricing Analysis
Input-cost pass-through from naphtha-ethane cracker feedstock differentials dominates contract structures, with Middle Eastern producers leveraging ethane allocations to sustain cost-advantaged positioning against naphtha-dependent Asian competitors. Price differentiation separates ISCC PLUS-certified mass-balance material from conventional naphtha-derived supply, with EU Green Deal textile mandates pulling certified volumes at substantial premiums. Pricing pressure stems from coal-to-chemicals retrofitting cycles in China, where MEE emissions compliance adds processing costs. Polyester fiber manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch traceability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with ethylene oxide purification technology licensors, where hazard operability review expertise has concentrated among retiring specialists. Geographic supply concentration centers on China, Saudi Arabia, and the United States, with the Yangtze River Delta and Jubail Industrial City anchoring integrated production. Raw material dependencies draw from naphtha, ethane, and coal-based syngas feedstocks. Supply chain risk manifests in logistics chokepoint exposure through Red Sea and Strait of Malacca shipping corridors. Distribution runs through direct tanker-truck and railcar deliveries to integrated polyester producers, with regional distributors managing fragmented pharmaceutical and coatings offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene glycol market functions as a regulatory compounder, with EU Green Deal recycled PET mandates and REACH Annex XIV authorization requirements for ethylene oxide restructuring procurement economics and certification premiums.
For Market Incumbents: Cement backward integration into purified terephthalic acid complexes to capture downstream margin pools, particularly in Gujarat where Reliance Industries and Indorama Ventures are expanding capacity. Invest in ISCC PLUS accreditation and dedicated GMP production lines to defend against bio-based feedstock entrants threatening conventional naphtha-derived supply. Prioritize carbon capture retrofitting at coal-based facilities to preempt MEE enforcement tightening.
For New Entrants and Emerging Players: Pharmaceutical-grade diethylene glycol excipient buyers represent an underserved buyer archetype with margin pools substantially above industrial grades. Target battery-grade ethylene carbonate synthesis for electric vehicle electrolyte additive applications, where sub-10 ppm chloride specifications create technical barriers to incumbent pivot. Pursue electrochemical ethylene production demonstration partnerships with Dutch pilot facilities to bypass conventional thermal cracking entirely.
For Investors and Strategic Acquirers: Polyester-integrated petrochemical majors are the most active acquirer in this space, seeking captive glycol supply for PTA complex expansion. Long-term viability hinges on feedstock-switching flexibility and carbon-intensity certification infrastructure. Acquisition target archetypes include regional distributors with automated sampling capabilities and chain-of-custody documentation systems. Watch for carbon-border adjustment mechanism implementation as inflection indicator reshaping location decisions for new capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captures margin pools from glycol through PET resin in Gujarat corridor expansion. |
| Green Manufacturing Transition | ISCC PLUS accreditation unlocks EU Green Deal textile mandate premiums. |
| Capacity Expansion | Triethylene glycol units serving LNG dehydration tighten purity specifications. |
| Long-term Supply Agreement | Multi-year offtake with automotive OEMs stabilizes coolant formulation volumes. |
| Joint Venture | Electrochemical ethylene pilot partnerships bypass conventional thermal cracking. |
Research Approach
Direct dialogue with plant managers, procurement leads at polyester manufacturers, distribution channel partners, and technical R&D directors grounded qualitative findings, validated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE emissions disclosure records. Bottom-up capacity modeling and top-down demand triangulation reconciled volume estimates across the analysis window.
Bottom-up segmentation analysis modeled grade tier, end-use industry, regional production hub, and certification status dimensions throughout the forecast period. CAGRs were derived from ethylene-to-glycol capacity utilization rates, polyester fiber production forecasts, and natural gas dehydration project pipelines across consuming markets.
Underlying measurement precision varies by segment; pharmaceutical-grade and battery-grade specifications carry tighter precision than industrial commodity volumes. Forecasts reflect assumptions around MEE enforcement timelines, EU carbon-border adjustment implementation, and coal-to-chemicals retrofitting completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Borates Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market