
 Solvent Cement Market | 2026-2036
Solvent Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent Cement Market Analytics
Capital-intensity divergence between integrated resin producers and formulation specialists is bifurcating the competitive landscape. DOW Chemical Company leverages its upstream chlor-alkali and vinyl chloride monomer position to control raw material costs across PVC cement lines. Henkel sustains premium positioning in specialty cements through R&D intensity focused on fast-cure industrial formulations. IPS Corporation dominates the North American contractor channel with deep distribution relationships and private-label partnerships.
Solvent cement is a thermoplastic bonding agent formulated from dissolved polymer resins, active solvents, and stabilizers that chemically weld substrates through polymer chain entanglement and solvent evaporation, typically achieving handling strength within minutes and full cure within 24 hours depending on ambient temperature and substrate porosity. PVC cement anchors the largest volume pool given its dominance in residential and municipal piping systems, while CPVC cement captures higher margins through fire-rated and hot-water applications that demand more stringent certification. Specialty cement represents the fastest-expanding category as automotive lightweighting and medical device assembly drive demand for bonded joints in temperature-sensitive substrates.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent volatility in domestic manufacturing, while REACH and the EU F-Gas Regulation limit certain chlorinated carrier solvents in European formulations. India's BIS certification requirements for potable water contact materials create a compliance threshold that filters substandard imports from neighboring markets. Stakeholders must monitor how state-level plumbing code harmonization and evolving green building standards will reshape product qualification requirements and channel access across priority construction markets.
Market Dynamics
Municipal water infrastructure replacement cycles are compressing demand timelines across North America and Europe, while REACH and EPA emission limits are forcing reformulation investments that favor integrated resin producers over standalone blenders.
Growth Catalysts
- EPA NESHAP compliance deadlines:US manufacturers must reduce hazardous air pollutant emissions from solvent cement production, accelerating facility upgrades and consolidating capacity among compliant producers.
- India's Jal Jeevan Mission:Rural household tap water connections are expanding PVC pipe networks into tier-2 and tier-3 cities, creating concentrated demand for potable-water-certified solvent cements.
- CPVC fire-rated certification:Commercial building codes in high-rise construction are mandating fire-resistant piping systems, pulling premium formulations into multi-family residential and hospitality verticals.
Market Restraints
- Vinyl chloride monomer supply concentration:Gulf Coast petrochemical corridor disruptions expose formulators to feedstock volatility that integrated producers absorb internally.
- Mechanical fastening substitution:Push-fit and press-fit polymer piping systems eliminate adhesive bonding in residential plumbing, capturing share in single-family new construction.
- REACH authorization timelines:ECHA's substance evaluation delays for chlorinated carrier solvents extend product re-registration cycles, freezing formulation portfolios for 18-24 month windows.
Strategic Opportunities
- Medical device assembly:Temperature-sensitive substrate bonding in diagnostic equipment and disposable surgical instruments is opening specialty cement applications beyond construction.
- EU F-Gas Regulation phase-down:Low-global-warming-potential solvent carriers qualify for accelerated approval pathways, rewarding early movers with preferential market access.
- E-commerce contractor supply:Direct-to-installer platforms are disintermediating traditional distributor networks in residential repair and maintenance channels.
Industry Challenges
- BIS potable water certification backlog:India's testing laboratory capacity constraints extend product approval timelines, delaying market entry for reformulated low-emission products.
- Automotive lightweighting integration:Bonded joint specifications in electric vehicle battery enclosures require thermal cycling validation protocols that exceed standard construction cement test matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent Cement Market |
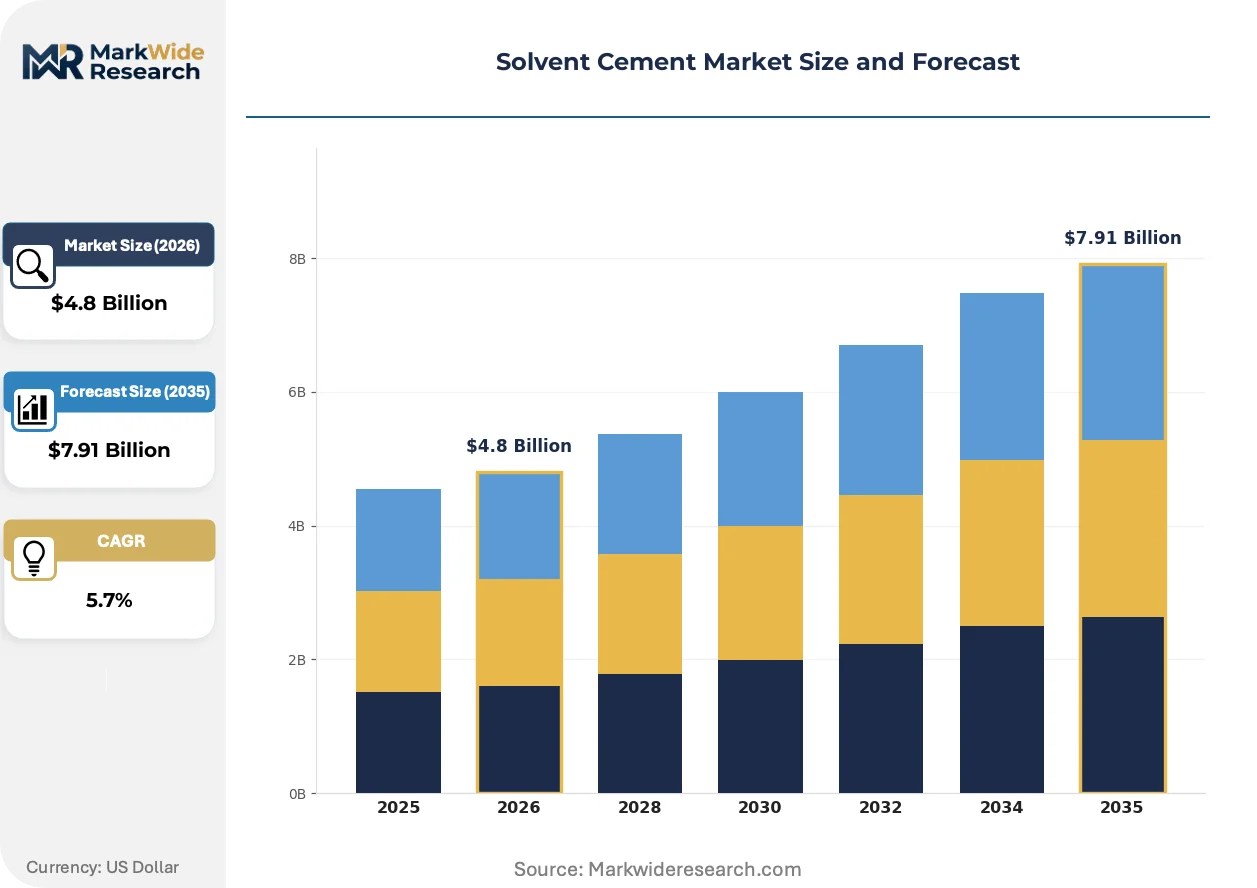
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Cement, CPVC Cement, ABS Cement, Specialty Cement Application: Piping, Furniture Assembly, Automotive, Construction End User: Contractors, Manufacturers, Distributors, DIY Consumers Form: Liquid, Gel, Paste, Others |
| Companies Covered | DOW Chemical Company, Oatey, Henkel, Bostik, H.B. Fuller, Sika, IPS Corporation, Wacker Chemie, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent Cement Market Evolving Landscape
Reformulation chemistry is diverging between emission-compliant water-based systems and high-performance solvent blends, while procurement patterns compress specification cycles and digital channels restructure contractor access.
Reactive acrylic solvent cement is decomposing the traditional PVC-CPVC formulation hierarchy by enabling universal substrate compatibility across dissimilar thermoplastics. Automotive tier-1 suppliers are piloting these systems for interior trim bonding at scale. The technology is decomposing historical product-line segmentation and forcing blenders to consolidate SKU portfolios around multi-substrate platforms.
REACH Annex XVII restrictions on chlorinated solvents are compelling European formulators to migrate toward acetate ester and ketone carrier systems with lower photochemical reactivity. ECHA's 2024 substance evaluation roadmap identifies four cement additives for authorization review. Industrial piping contractors in Germany and France are pre-qualifying reformulated products to avoid specification lockout.
Specification authority is migrating from distributor sales representatives to digital platforms where contractors compare cure times, temperature ratings, and certification compliance in real time. Large mechanical contractor chains in the United States are consolidating purchasing through centralized procurement portals that bypass regional distributor relationships. This shift is most visible in Florida and Texas residential construction markets where labor mobility drives product standardization across job sites.
Solvent Cement Market Segmentation
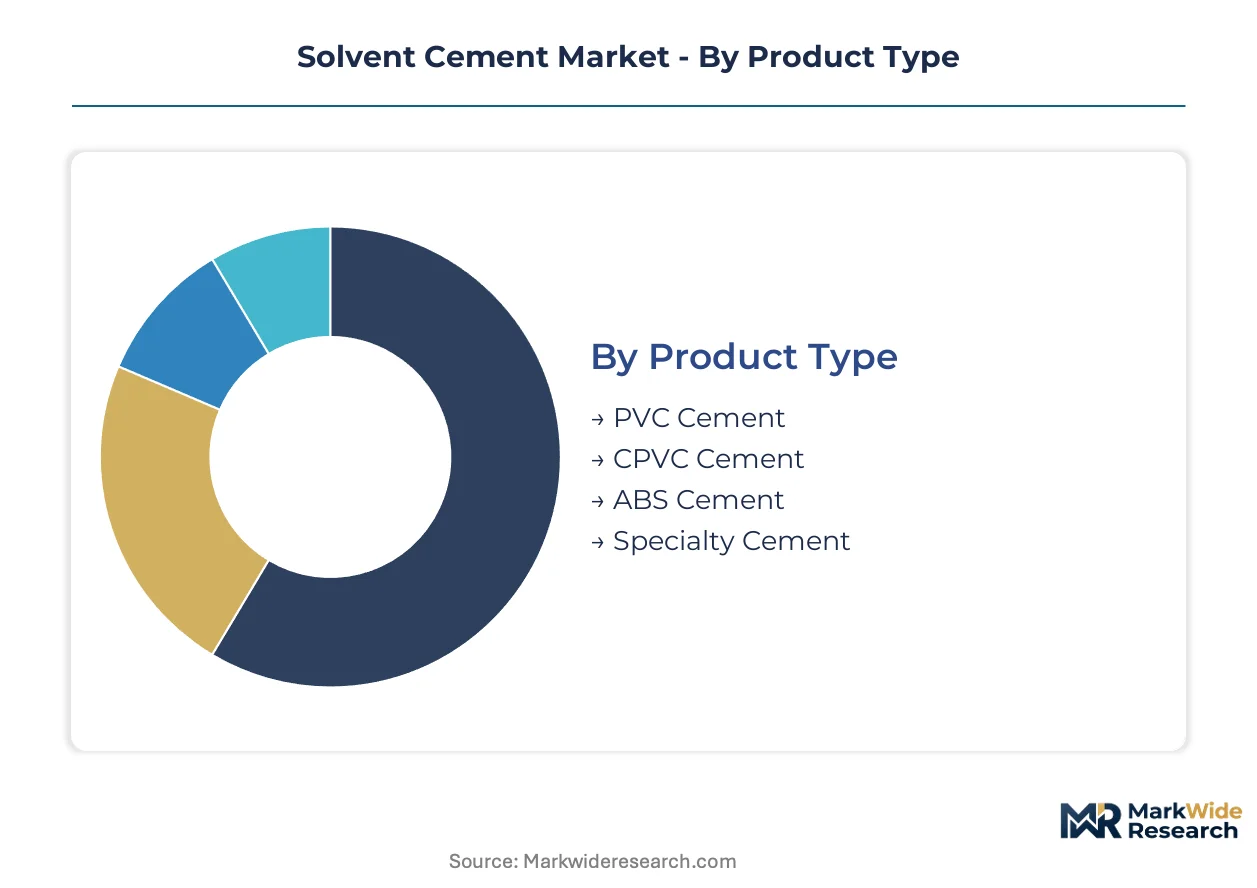
Solvent cement segmentation reveals how formulation chemistry, application environment, and procurement channel collectively determine margin structure. Product type and application verticals show the sharpest divergence in substitution vulnerability and regulatory exposure.
Product Type:
Push-fit mechanical systems threaten commodity-grade formulations most severely, while certified industrial grades defend position through code-mandated performance specifications.
- PVC Cement:Formulated from dissolved polyvinyl chloride resin in tetrahydrofuran and methyl ethyl ketone carriers, achieving handling strength within minutes through solvent welding. Municipal water infrastructure replacement across the United States concentrates demand, though residential plumbing faces encroachment from press-fit polymer systems that eliminate adhesive bonding entirely.
- CPVC Cement:Higher resin solids content and elevated temperature resistance distinguish formulations for hot-water distribution and fire-rated commercial piping. Multi-family residential and hospitality construction in high-rise zones pull premium volumes, with building code mandates for fire-resistant systems creating specification stickiness that mechanical alternatives cannot satisfy.
- ABS Cement:Acrylonitrile butadiene styrene formulations serve drainage, waste, and vent applications with faster cure profiles than PVC systems. Industrial process piping and marine applications sustain niche demand.
- Specialty Cement:Temperature-sensitive substrate bonding for medical device assembly and automotive interior trim. Diagnostic equipment manufacturers and electric vehicle battery enclosure fabricators drive qualification protocols.
PVC Cement retains volume leadership; Specialty Cement holds the steepest expansion curve.
Application:
Code compliance requirements segment the market into specification-driven infrastructure verticals versus discretionary industrial assembly.
- Piping:Potable water distribution, sanitary drainage, and industrial process lines constitute the dominant consumption pool. India's Jal Jeevan Mission rural tap water expansion and North American municipal network replacement compress demand timelines.
- Furniture Assembly:Thermoplastic edge banding and modular component bonding for mass-produced office and residential furniture. Southeast Asian manufacturing clusters concentrate procurement.
- Automotive:Lightweight interior trim bonding and battery enclosure assembly for electric vehicle platforms. Thermal cycling validation requirements exceed standard construction cement test matrices.
- Construction:General building trades including HVAC ductwork, signage, and architectural fabrication. Project-based demand fluctuates with residential and commercial construction cycles.
Piping commands the largest revenue pool; Automotive exhibits the most rapid application expansion.
End User:
Procurement authority migration from distributor representatives to digital platforms restructures channel economics across user categories.
- Contractors:Mechanical and plumbing installation professionals purchasing through distributor networks or direct e-commerce portals. Large US contractor chains consolidate buying through centralized procurement systems.
- Manufacturers:Industrial fabricators and OEMs specifying cement for production-line bonding operations. Automotive tier-1 suppliers and medical device assemblers drive qualification-intensive demand.
- Distributors:Wholesale and retail intermediaries maintaining inventory for contractor and consumer channels. Private-label partnerships with formulators defend margin position against direct manufacturer sales.
- DIY Consumers:Residential repair and maintenance purchasers through home improvement retail and online marketplaces. Price sensitivity and convenience preference dominate selection criteria.
Contractors generate the highest transaction volumes; Manufacturers deliver the strongest pricing power.
Form:
Viscosity and rheology specifications align with joint geometry and substrate porosity requirements.
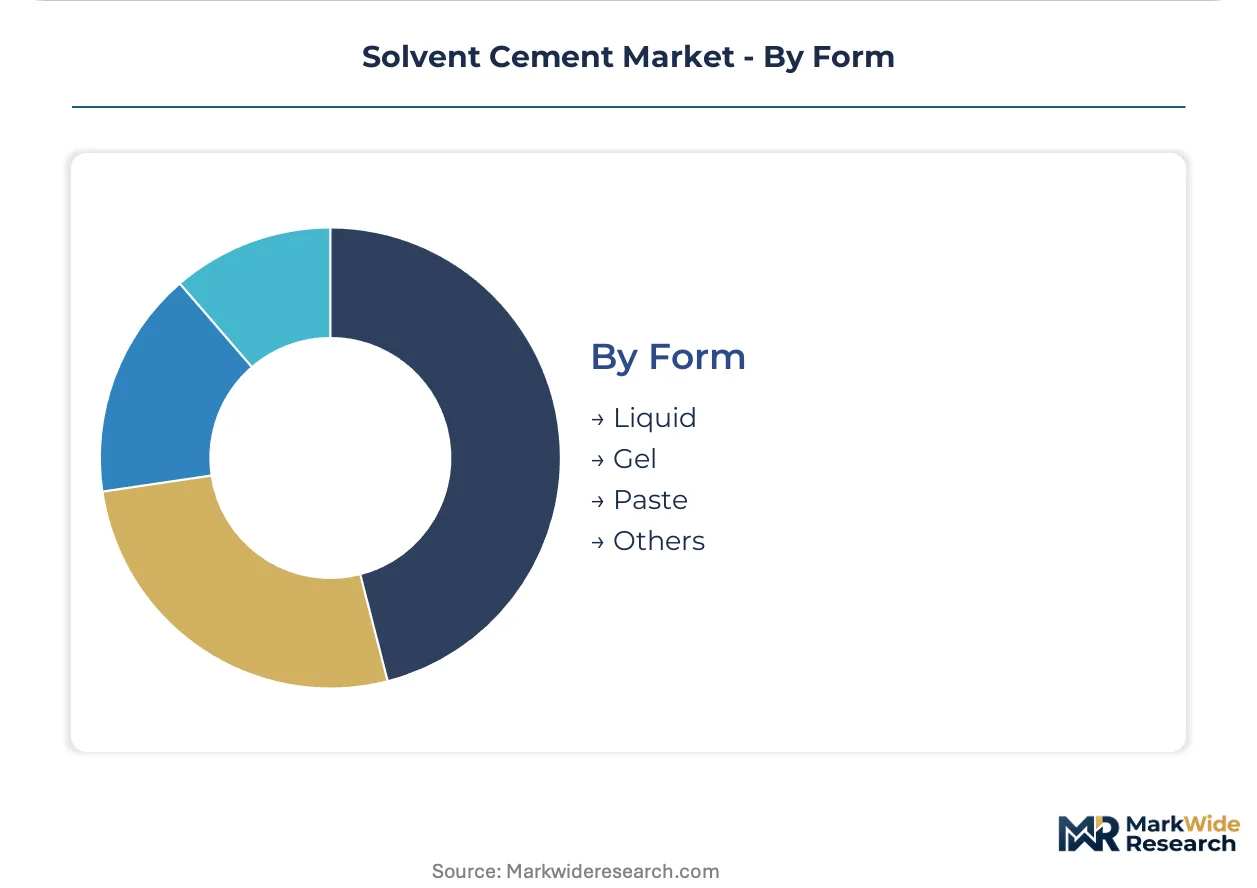
- Liquid:Low-viscosity formulations for tight-fitting pipe joints and capillary action-dependent applications. Standard grades for residential plumbing dominate volume.
- Gel:Thixotropic systems resisting sag on vertical surfaces and overhead applications. Industrial piping and structural assemblies require controlled flow characteristics.
- Paste:High-build formulations for gap-filling and large-diameter pipe connections. Municipal infrastructure and commercial drainage systems specify heavier consistencies.
- Others:Sprayable and two-component systems for specialized industrial applications. Custom formulations for automated assembly lines.
Liquid forms capture the broadest usage base; Gel formulations gain share fastest in industrial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial formulations while Indian volume markets operate on thinner margins. European regulatory stringency sustains premium positioning. Asian infrastructure expansion compresses procurement cycles across tier-2 urban clusters.
United States
Municipal water infrastructure replacement drives demand across aging pipe networks in the Midwest and Northeast. EPA NESHAP compliance deadlines force facility upgrades among domestic manufacturers. Houston-Gulf Coast petrochemical corridors supply vinyl chloride monomer feedstock to integrated producers.
Germany
Industrial piping contractors pre-qualify reformulated products ahead of ECHA authorization reviews. REACH Annex XVII restrictions on chlorinated solvents accelerate acetate ester carrier migration. Ruhr industrial clusters and Bavarian manufacturing zones concentrate specification-intensive demand.
India
Jal Jeevan Mission rural tap water connections expand PVC networks into tier-2 and tier-3 cities. BIS certification requirements for potable water contact materials filter substandard imports. Maharashtra and Gujarat industrial corridors face testing laboratory capacity constraints extending product approval timelines.
China
Construction chemical demand concentrates in Yangtze River Delta infrastructure projects. GB standards for construction materials enforce quality thresholds on domestic and imported formulations. Pearl River Delta manufacturing clusters absorb specialty cement volumes for automotive supplier networks.
Brazil
Sanitation expansion programs in São Paulo and Rio de Janeiro metro areas stimulate PVC piping demand. ANVISA regulatory frameworks govern construction chemical imports. Southeastern industrial zones concentrate distributor networks serving contractor channels.
Solvent Cement Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated resin producers control upstream raw material costs while formulation specialists defend premium positioning through R&D intensity. The market stratifies around three archetypes: petrochemical-integrated manufacturers, specialty chemical blenders, and regional distribution-focused suppliers. Capacity consolidation and portfolio diversification toward low-emission formulations represent the dominant competitive moves.
Among petrochemical-integrated manufacturers, DOW Chemical Company exemplifies upstream control over chlor-alkali and vinyl chloride monomer supply chains. Henkel occupies a position within specialty formulation tiers focused on fast-cure industrial applications. IPS Corporation anchors North American contractor channel access through distribution relationship depth.
| Leading Market Players |
|---|
| DOW Chemical Company |
| Oatey |
| Henkel |
| Bostik |
| H.B. Fuller |
| Sika |
| IPS Corporation |
| Wacker Chemie |
| 3M |
| Others |
Value Network & Pricing Analysis
Sixty-day vinyl chloride monomer inventory cycles at Gulf Coast petrochemical hubs concentrate pricing leverage among integrated producers while exposing standalone blenders to feedstock volatility that compresses margin buffers during supply disruptions.
Pricing Analysis
Configured-to-order pricing for fire-rated CPVC formulations commands a 40-60% premium over standard PVC grades, with certification tier and cure-speed specifications driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by resin solids content and temperature rating. Cost compression in commodity PVC tiers is intensifying because push-fit mechanical systems eliminate adhesive bonding in residential new construction. DIY consumers through home improvement retail channels exhibit the highest price sensitivity, while municipal procurement officers prioritize specification compliance over unit cost.
Supply Chain Analysis
Vinyl chloride monomer production clustering along the Texas-Louisiana Gulf Coast creates a chokepoint where hurricane-season disruptions propagate through formulation networks. Feedstock supply concentrates in the United States, Germany, and China, with chlor-alkali capacity anchoring regional cost structures. Formulation draws from tetrahydrofuran carriers, methyl ethyl ketone solvents, and stabilizer packages sourced from petrochemical intermediates. Single-source vulnerability in VCM railcar logistics exposes just-in-time blenders to force majeure events. Distribution runs through regional distributor networks, contractor supply houses, and emerging direct-to-installer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as specification authority migrates from distributor sales representatives to digital procurement platforms, creating entry niches for specialized formulators who can navigate certification complexity faster than incumbents.
For Market Incumbents: Secure BIS potable water certification capacity in India ahead of Jal Jeevan Mission procurement waves, and lock in multi-year VCM offtake agreements to neutralize Gulf Coast feedstock volatility. Backward integration into chlor-alkali production or captive solvent recovery systems defends margin position against integrated resin producers. Channel control through private-label partnerships with national distributor chains remains critical as contractor purchasing consolidates through centralized portals.
For New Entrants and Emerging Players: Anchor in specialty cement applications for electric vehicle battery enclosures and medical device assembly where thermal cycling validation requirements exceed standard construction test matrices and create qualification moats. The automotive tier-1 supplier network offers the most penetrable entry point, with direct technical sales to OEM engineering teams as the preferred go-to-market angle. Target tier-2 and tier-3 Indian cities where BIS certification backlogs delay incumbent product approvals.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH authorization timelines and EPA NESHAP compliance deadlines will force subscale blenders toward exit or acquisition by integrated producers with reformulation R&D capacity. Acquisition target archetype: regional formulators with established distributor relationships and pending low-emission product certifications. The signal to watch is ECHA substance evaluation delays freezing competitor formulation portfolios while early movers capture specification lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Production | Gulf Coast chlor-alkali capacity secures feedstock cost parity with DOW Chemical Company. |
| Low-Emission Formulation Certification | REACH-compliant acetate ester carriers unlock preferential access to German industrial piping contractors. |
| Direct-to-Installer E-Commerce Platform | Florida and Texas contractor chains disintermediate regional distributor markups through centralized procurement portals. |
| Medical Device Assembly Qualification | ISO 10993 biocompatibility certification opens temperature-sensitive substrate bonding for diagnostic equipment manufacturers. |
| Joint Venture with Indian Testing Laboratory | BIS certification backlog clearance accelerates market entry for reformulated potable-water-grade cements in Maharashtra and Gujarat. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, municipal procurement officers, and mechanical contractor purchasing managers and secondary validation through customs trade data, ACC resin production reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down capacity assessments across chlor-alkali and VCM production hubs. Plant managers at integrated petrochemical facilities, distribution channel partners in North American contractor supply, and technical R&D directors at specialty chemical blenders provided operational perspective on reformulation economics and certification timelines.
Sensitivity analysis around EPA NESHAP compliance cost assumptions and REACH authorization timeline scenarios frames the projection envelope. Segmentation dimensions modeled include resin type tier, application vertical, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, infrastructure spending trajectories, and penetration rates of mechanical fastening alternatives. Forecast inputs incorporate Jal Jeevan Mission connection targets, municipal water main replacement schedules, and electric vehicle production forecasts driving battery enclosure bonding demand.
Material uncertainties — ECHA substance evaluation delays, Gulf Coast hurricane disruption frequency, and BIS laboratory capacity expansion — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and infrastructure appropriation continuity. Practitioners should keep alternative scenarios live as REACH Annex XVII restriction scope and state-level plumbing code harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Glycidol Market
Solvents
Isoamylene Market
Solvents
Hydrosol Market
Solvents
Epoxy Thinner Market
Solvents
Fluid Neutralizing Market
Solvents
Ethane Market
Solvents
3-Butylene Glycol Market
Solvents
Dibutyl Ether Market
Solvents
Global Glycol Market
Solvents
Dihydromyrcenol Market
Solvents
Propylene Glycol Ether Market
Solvents
Wax Dispersion Market
Solvents
Diethyl Ether Market
Solvents
Natural Distillates Market
Solvents
Ketene Market
Solvents
6-Xylenol Market