
 Global Glycol Ether Market | 2026-2036
Global Glycol Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycol Ether Market Analysis
ISO 9001 certification is rotating as a baseline qualifier for supplier qualification programs among multinational coatings formulators. BASF SE leverages integrated ethylene oxide feedstock positions to sustain cost-competitive glycol ether output across European and Asian manufacturing hubs. Dow Chemical Company anchors North American supply through proprietary continuous-process technology at its Texas operations. Eastman Chemical Company differentiates via specialty-grade propylene glycol ethers serving electronics solvent niches.
Glycol ethers comprise alkyl ether derivatives of ethylene glycol or propylene glycol, typically formulated with boiling points between 120°C and 230°C and solvent power parameters matched to resin systems in coatings and cleaning applications. These compounds function primarily as coupling agents, coalescing aids, and active solvents in waterborne formulations where they reduce surface tension and control drying kinetics. Paints and coatings applications dominate value capture given formulation complexity and specification intensity, while cleaners represent a faster-growing segment driven by industrial degreasing and household hard-surface formulations. Propylene glycol ethers are gaining share as formulators respond to toxicity profile preferences in consumer-facing and occupational exposure settings.
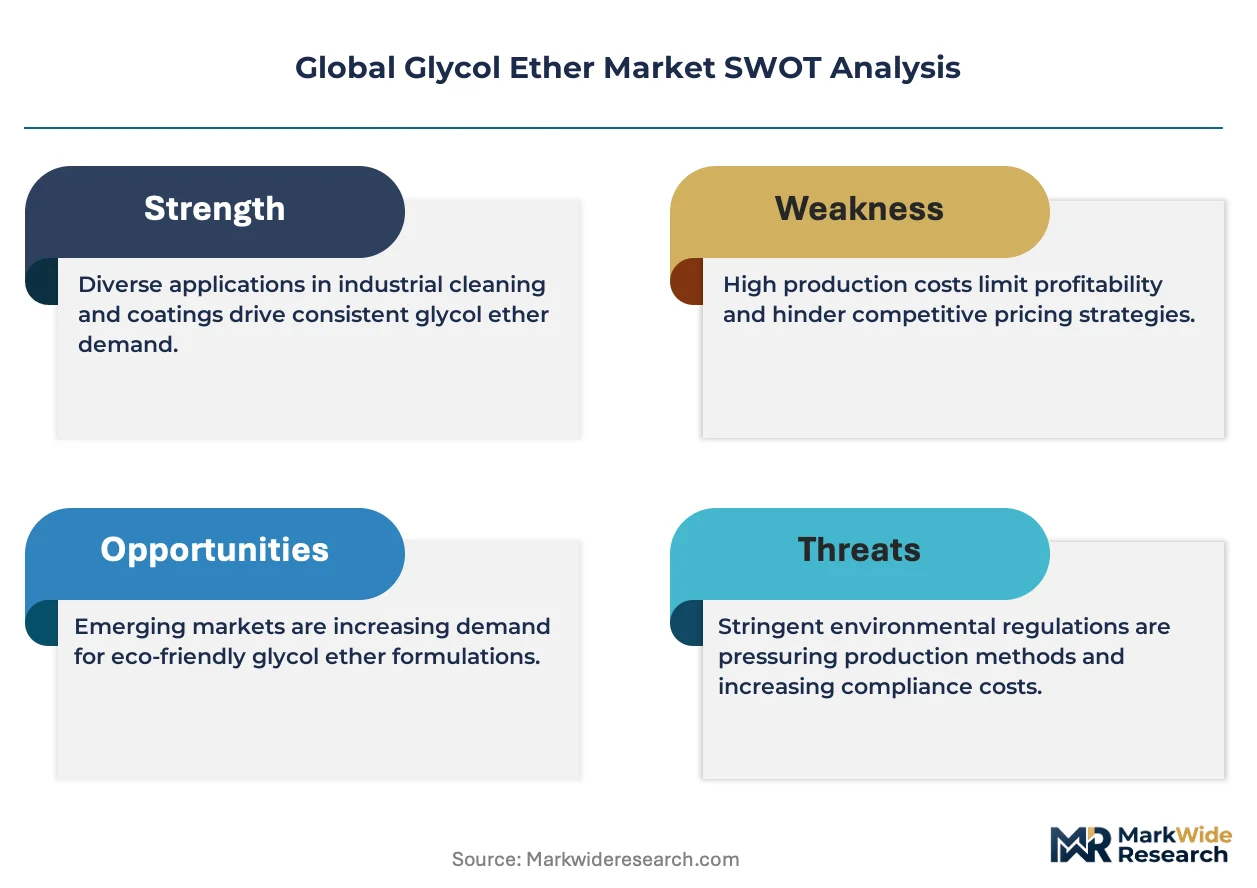
REACH registration requirements and EPA VOC emission standards are tightening permissible solvent characteristics, pushing reformulation toward propylene glycol-based alternatives with favorable toxicological profiles. ECHA hazard classifications for certain ethylene glycol ethers are restricting their use in consumer applications across Europe, while EPA risk evaluations under TSCA are generating comparable pressure in the United States. China MEE enforcement of GB standards for industrial emissions is accelerating domestic producer migration to cleaner process technologies. Stakeholders must monitor regulatory divergence between jurisdictions where product registrations approved in one geography face automatic exclusion in another.
Market Dynamics
REACH restrictions on volatile organic compounds are redirecting formulation strategies toward lower-emission glycol ether variants, compressing permissible solvent characteristics and forcing molecular redesign across European coatings operations.
Growth Catalysts
- Waterborne coating expansion:Automotive refinishing shops in Germany and the United States are converting solvent-borne systems to waterborne alternatives, requiring glycol ethers as coupling agents and coalescing aids to control drying kinetics and surface tension reduction.
- Electronics manufacturing clustering:Printed circuit board cleaning and semiconductor wet processing operations in the Yangtze River Delta are concentrating demand for high-purity propylene glycol ethers with ultra-low metal ion specifications.
- EPA VOC emission standards:The 2023 amendments to National Emission Standards for Hazardous Air Pollutants are accelerating reformulation timelines for architectural and industrial maintenance coatings across North American manufacturing facilities.
Market Restraints
- Ethylene oxide feedstock volatility:Cracker economics and ethylene oxide spot pricing in the US Gulf Coast create margin compression for ethylene-based glycol ether producers during olefin cycle downturns.
- ECHA hazard classifications:Reproductive toxicity categorizations for certain ethylene glycol monoethyl ether acetates are restricting consumer-facing applications across European Union member states and triggering substitution mandates.
- Propylene glycol ether capacity concentration:Asian producers control approximately three-quarters of global P-series capacity, creating supply security concerns for European and North American formulators seeking geographic diversification.
Strategic Opportunities
- Brazilian industrial degreasing:ANVISA is harmonizing solvent safety standards with OECD guidelines, opening formulation opportunities for propylene glycol ethers in metal cleaning applications previously served by chlorinated solvents.
- India PLI scheme for electronics:Production-linked incentives for semiconductor and display manufacturing are attracting solvent suppliers to establish local blending operations serving fabs in Gujarat and Tamil Nadu.
- Green chemistry procurement mandates:US federal purchasing guidelines under the Federal Acquisition Regulation are creating preference tiers for bio-based glycol ethers in military and infrastructure coating specifications.
Industry Challenges
- REACH registration timelines:The 2023 deadline for complete substance dossier submissions created bottlenecks at European Chemicals Agency consultancies, delaying market access for novel propylene glycol ether variants.
- Process analytical technology integration:Continuous manufacturing transitions at specialty chemical plants require revalidation of in-process control systems for glycol ether purification, extending commissioning schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycol Ether Market |
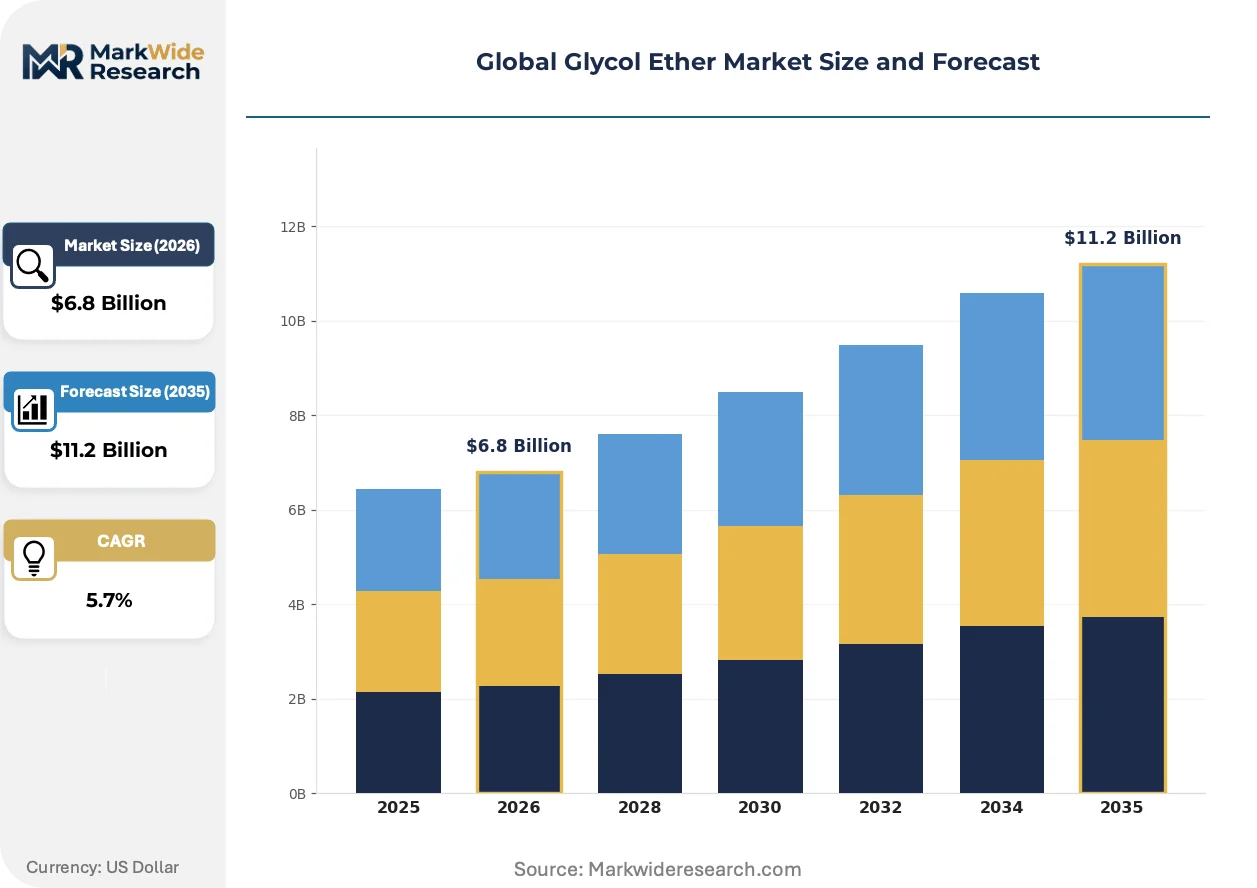
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Glycol, Ethyl Glycol, Propylene Glycol, Diethylene Glycol Application: Paints, Coatings, Cleaners, Personal Care End User: Automotive, Chemical Manufacturing, Aerospace, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, Dow Chemical Company, Eastman Chemical Company, LyondellBasell Industries Holdings B.V., Shell plc, INEOS Group Ltd., Huntsman Corporation, SABIC, Sasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycol Ether Market Emerging Trajectories
Formulation chemistry is pivoting toward molecular architectures that satisfy multiple regulatory jurisdictions simultaneously, requiring solvent designers to anticipate divergence between EPA risk evaluations and ECHA hazard classifications.
Hybrid glycol ether-ester molecules are fragmenting traditional product category boundaries in coatings applications. These compounds function simultaneously as active solvents and coalescing aids, eliminating the need for separate additive packages. Automotive OEM clearcoat formulators in Japan and South Korea are adopting these materials at accelerated rates. The technology is fragmenting established procurement patterns where buyers previously sourced solvents and coalescents through separate supplier relationships.
China MEE enforcement of GB 31570 and GB 31571 standards for volatile organic compound emissions is tightening permissible solvent characteristics for architectural coatings manufactured in the Pearl River Delta and Yangtze River Delta clusters. Domestic producers are retrofitting continuous-process units with closed-loop purification systems to meet stack monitoring requirements. Waterborne industrial maintenance coatings are experiencing the most acute formulation pressure, with manufacturers reformulating to reduce glycol ether vapor pressure profiles below 0.3 kPa at 20°C.
Specification intensity is compressing switching cycles among multinational coatings formulators. Procurement departments at tier-one automotive refinish suppliers now require 18-month qualification timelines for new glycol ether sources, up from 6-9 months in prior decades. This elongation reflects expanded testing protocols for color match stability, humidity resistance, and crash-repair compatibility. The pattern is most visible in Germany and the United States, where collision repair networks consolidate purchasing through national distribution agreements.
Global Glycol Ether Market Segmentation
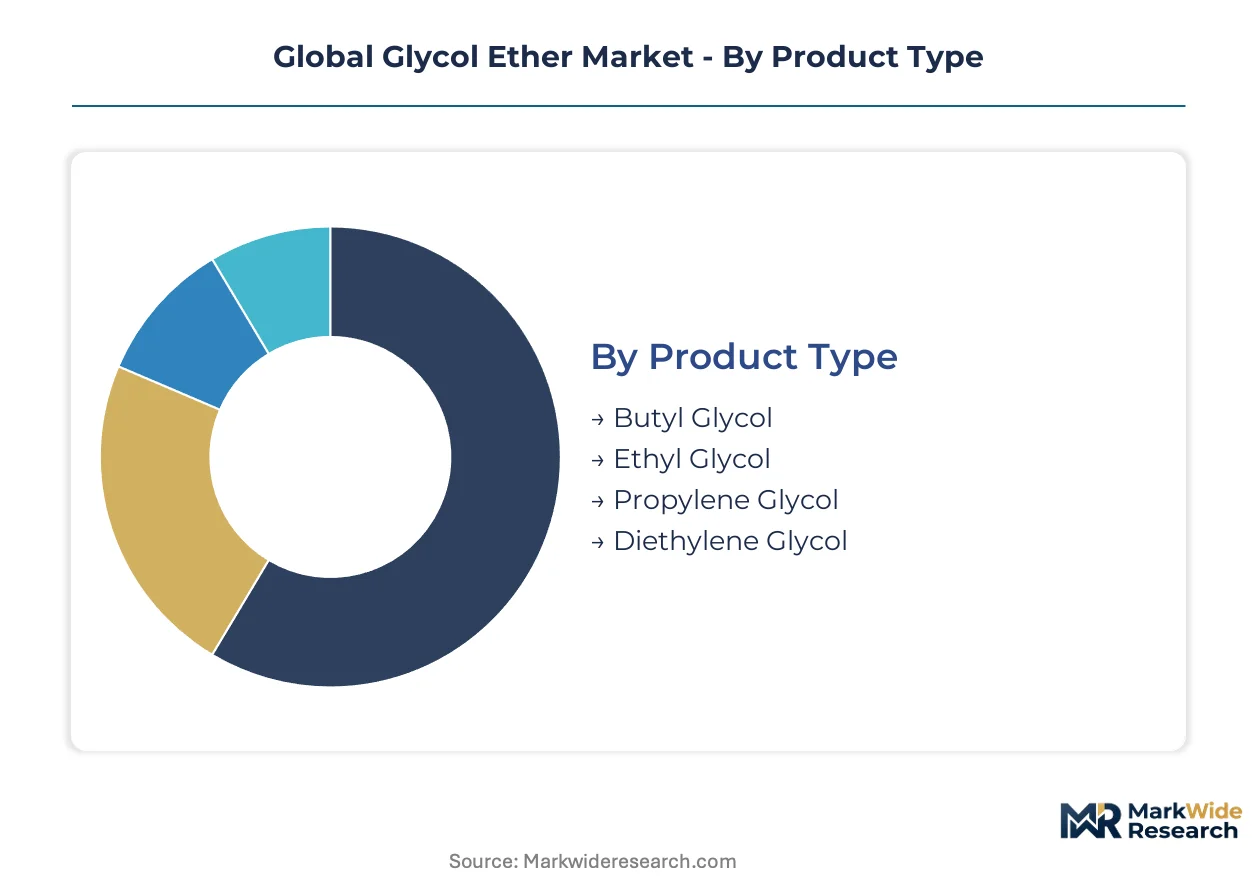
Glycol ether segmentation reveals divergent margin structures across molecular families and end-use specifications. Product type categories separate commodity-scale ethylene derivatives from specialty-grade propylene variants with divergent regulatory fates. Application and end-user dimensions expose where formulation complexity commands premium positioning versus where solvent substitution erodes value capture.
Product Type:
Propylene glycol ethers command the widest margin spreads as ECHA hazard classifications and EPA risk evaluations redirect demand away from ethylene-based alternatives.
- Butyl Glycol:Ethylene glycol monobutyl ether delivers strong solvency for alkyd and acrylic resins in industrial maintenance coatings. Waterborne architectural formulations in Germany and the United States concentrate consumption as collision repair networks consolidate procurement through national distribution agreements.
- Ethyl Glycol:Lower molecular weight variant with faster evaporation profiles suited to lacquer thinners and quick-dry enamel systems. REACH registration timelines and reproductive toxicity categorizations are restricting consumer-facing applications across European Union member states.
- Propylene Glycol:Favorable toxicological profile supports electronics-grade specifications with ultra-low metal ion requirements for semiconductor wet processing in the Yangtze River Delta.
- Diethylene Glycol:Higher boiling point ether serving as a coalescing aid in latex paints and brake fluid formulations with slower drying kinetics.
Butyl Glycol holds installed capacity. Propylene Glycol is rotating up the share rankings.
Application:
Paints and coatings concentrate specification intensity where procurement departments enforce 18-month qualification timelines for new solvent sources.
- Paints:Architectural and decorative formulations represent the volume anchor, with waterborne latex systems requiring glycol ethers as coalescing aids to control minimum film formation temperature. China MEE enforcement of GB 31570 standards is tightening permissible vapor pressure profiles below 0.3 kPa.
- Coatings:Automotive OEM clearcoats and industrial maintenance systems command premium positioning through hybrid glycol ether-ester molecules that function simultaneously as active solvents and coalescing aids.
- Cleaners:Metal degreasing and hard-surface formulations in Brazil are expanding as ANVISA harmonizes solvent safety standards with OECD guidelines.
- Personal Care:Fragrance solubilizers and cosmetic coupling agents with strict dermal exposure limits.
Coatings capture the steepest expansion trajectory. Cleaners are climbing the fastest in absolute volume terms.
End User:
Electronics manufacturing imposes the most stringent purity specifications, separating commodity suppliers from qualified vendors.
- Automotive:Refinish shops in Germany and the United States are converting solvent-borne systems to waterborne alternatives, requiring glycol ethers to reduce surface tension and control drying kinetics.
- Chemical Manufacturing:Process solvents and intermediate feedstocks for downstream derivative production with cyclical margin exposure to ethylene oxide spot pricing.
- Aerospace:Specialty coatings and cleaning applications with MIL-SPEC qualification requirements and extended approval cycles.
- Electronics:Printed circuit board cleaning and semiconductor wet processing in the Yangtze River Delta and Gujarat clusters concentrate demand for high-purity propylene glycol ethers.
Electronics holds the specification ceiling. Automotive is rotating toward waterborne conversion mandates.
Distribution Channel:
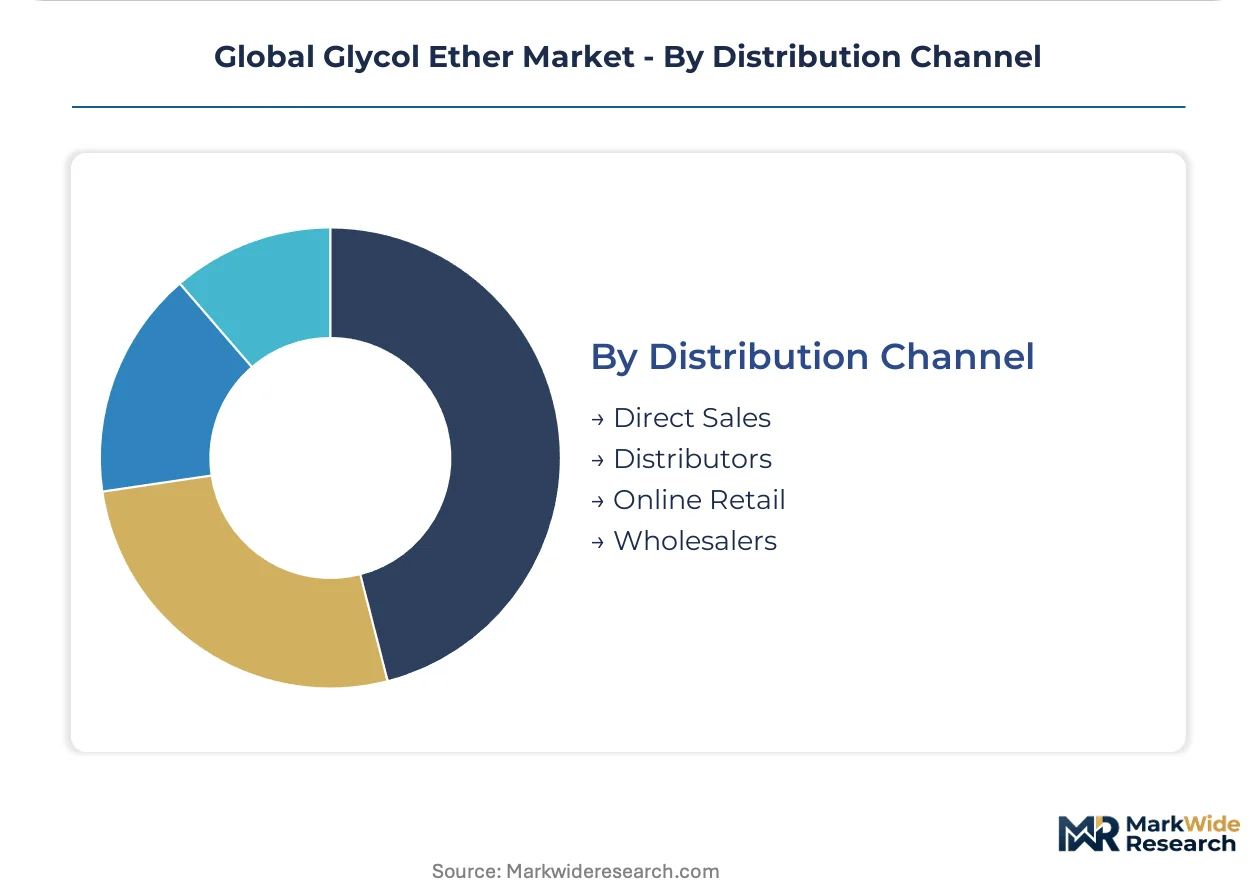
Direct sales concentrate where formulation technical service determines specification adherence and batch certification requirements.
- Direct Sales:Multinational coatings formulators in Germany and the United States procure through long-term supply agreements with integrated technical support for color match stability testing.
- Distributors:Regional blending operations serving mid-tier automotive refinish suppliers with shorter lead times and fragmented order patterns.
- Online Retail:Small-volume specialty chemical procurement with limited penetration in specification-intensive end uses.
- Wholesalers:Commodity-grade solvents for industrial maintenance and cleaner formulations with price-sensitive switching behavior.
Direct Sales holds the contract value. Distributors are gaining share in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational coatings formulators concentrate procurement through direct supply agreements in Germany and the United States, while electronics manufacturers cluster demand in China's Yangtze River Delta. Regulatory divergence between EPA risk evaluations and ECHA hazard classifications is fragmenting formulation strategies across jurisdictions.
United States
Automotive refinish shops in Michigan and Ohio are converting solvent-borne systems to waterborne alternatives, requiring glycol ethers as coupling agents. EPA amendments to National Emission Standards for Hazardous Air Pollutants are accelerating reformulation timelines for architectural coatings. The Texas Gulf Coast hosts Dow Chemical Company's continuous-process operations serving North American supply.
Germany
Collision repair networks are consolidating procurement through national distribution agreements with 18-month qualification timelines for new solvent sources. REACH registration deadlines for complete substance dossiers created bottlenecks at European Chemicals Agency consultancies. The Ruhr industrial corridor concentrates demand for industrial maintenance coatings with strict VOC compliance.
China
Printed circuit board cleaning and semiconductor wet processing operations in the Yangtze River Delta are concentrating demand for high-purity propylene glycol ethers. Ministry of Ecology and Environment enforcement of GB 31570 and GB 31571 standards is tightening permissible solvent characteristics. Domestic producers in the Pearl River Delta are retrofitting continuous-process units with closed-loop purification systems.
Japan
Automotive OEM clearcoat formulators are adopting hybrid glycol ether-ester molecules at accelerated rates. METI guidelines on industrial chemical safety are influencing procurement specifications for electronics-grade solvents. The Nagoya industrial cluster serves tier-one suppliers with extended testing protocols for color match stability.
Brazil
Metal cleaning applications previously served by chlorinated solvents are expanding demand for propylene glycol ethers in industrial degreasing. ANVISA is harmonizing solvent safety standards with OECD guidelines, opening formulation opportunities. São Paulo state concentrates automotive manufacturing and refinishing operations driving waterborne coating conversion.
Global Glycol Ether Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive ethylene oxide feedstock positions. Three to five multinational chemical producers control the majority of installed capacity across ethylene and propylene glycol ether families. Strategic archetypes separate integrated feedstock players from specialty-grade refiners and regional toll manufacturers. Dominant competitive moves include backward integration into ethylene oxide supply and geographic expansion through joint venture structures in Asian manufacturing hubs.
Within the integrated petrochemical tier, BASF SE and Dow Chemical Company exemplify archetypes defined by scale and feedstock control. Eastman Chemical Company occupies a position representing specialty-grade orientation, particularly in propylene glycol ethers for electronics applications. These three anchors illustrate how competitive positioning separates commodity-scale producers from specification-intensive specialists serving semiconductor and automotive OEM segments.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| Shell plc |
| INEOS Group Ltd. |
| Huntsman Corporation |
| SABIC |
| Sasol |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification timelines for new solvent sources concentrate buyer power among multinational coatings formulators in Germany and the United States, compressing margin capture for suppliers while amplifying price leverage for procurement departments managing national distribution agreements.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide spot pricing on the US Gulf Coast dominate procurement arrangements between integrated producers and tier-one automotive refinish suppliers. Three-tier pricing structure across premium electronics-grade, standard industrial-grade, and economy cleaner-grade levels separates qualified vendors from commodity traders. Pricing pressure stems from Asian producers controlling three-quarters of global propylene glycol ether capacity, forcing European and North American suppliers to absorb logistics premiums. Small-volume hard-surface cleaner formulators exhibit the highest price sensitivity, while semiconductor wet processing operations prioritize specification adherence over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Rotterdam and Shanghai Yangshan terminals fluctuate with container availability on Asia-Europe trade lanes, compressing landed margins for spot purchasers. Manufacturing gravity centers on China, the United States, and Germany, with ethylene oxide feedstock anchoring production economics. The supply chain rests on ethylene oxide, propylene oxide, and methanol as primary inputs, with cracker economics determining regional cost competitiveness. Single-source vulnerability concentrates in propylene glycol ether capacity, where Chinese producers dominate high-purity grades for electronics applications. Distribution runs through direct sales agreements for specification-intensive coatings and regional distributors for fragmented cleaner formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through national distribution agreements among collision repair networks and automotive OEM procurement departments, fragmenting supplier leverage across fragmented downstream channels.
For Market Incumbents: Compound technical service capabilities to extend 18-month qualification timelines into captive supplier relationships, defending against Asian propylene glycol ether imports. Deepen backward integration into ethylene oxide supply through Texas Gulf Coast cracker economics or European naphtha feedstock positions. Prioritize ISO 9001 certification maintenance as baseline qualifiers harden among multinational formulators. For New Entrants and Emerging Players: Electronics-grade blending services in Gujarat and Tamil Nadu represent the most penetrable white-space opportunity, where India's PLI scheme for semiconductor manufacturing outpaces local solvent supply infrastructure. Target industrial degreasing applications in Brazil as ANVISA harmonization displaces chlorinated solvents. Establish toll manufacturing partnerships with domestic Chinese producers to circumvent REACH registration bottlenecks for European market access. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because regulatory divergence between EPA risk evaluations and ECHA hazard classifications favors multi-jurisdictional formulation capabilities that mid-scale regional producers cannot replicate independently. Acquisition targets should combine captive ethylene oxide feedstock with established semiconductor customer qualifications. Monitor ECHA hazard classification updates for ethylene glycol monoethyl ether acetates as inflection signals for substitution-driven demand shifts toward propylene-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates margin compression during US Gulf Coast olefin cycle downturns. |
| Electronics-Grade Capacity Expansion | Ultra-low metal ion specifications for Yangtze River Delta semiconductor fabs command premium positioning. |
| Green Chemistry Certification Program | Bio-based glycol ethers qualify for US Federal Acquisition Regulation preference tiers in military coatings. |
| Joint Venture in Asian Manufacturing Hubs | Local blending operations circumvent India's PLI scheme logistics constraints for Gujarat semiconductor clusters. |
| Long-term Supply Agreement with Automotive OEMs | Collision repair network consolidation in Germany favors contracted volume commitments over spot procurement. |
Methodological Framework
Operator-level perspectives from plant managers at integrated petrochemical complexes, procurement leads at multinational coatings formulators, distribution channel partners serving automotive refinish networks, and technical R&D directors specializing in waterborne formulations anchored the qualitative base. Primary interviews combined with secondary validation through customs and trade data, American Chemistry Council and Cefic industry reports, and SEC 10-K filings from listed chemical producers. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates across the analysis window.
Sensitivity analysis tested ethylene oxide feedstock volatility scenarios and REACH registration timeline delays against base-case demand projections. Segmentation dimensions modeled include product type tier, end-use industry, purity specification level, and regional production hub. CAGRs were derived from annualized growth rate calculations applied to 2026 baseline values. Industry-specific forecast inputs incorporated automotive waterborne conversion rates and electronics manufacturing cluster expansion in the Yangtze River Delta and Gujarat.
Forecasts assume regulatory continuity in EPA National Emission Standards, ECHA REACH classifications, and China MEE GB standards enforcement; material policy shifts would require re-modeling of substitution dynamics and permissible solvent characteristics. Practitioners should keep alternative scenarios live as ECHA hazard classification updates and EPA TSCA risk evaluations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzhydrol Market
Chemicals
Chemical Distribution Market
Chemicals
Amyl Nitrite Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Global Syringaldehyde Market
Chemicals
Potassium Fluoride Market
Chemicals
Detergent Alcohols Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Superplasticizer Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Inorganic Chemicals Market
Chemicals
Global Organobromine Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
5 Dinitroaniline Market
Chemicals
Peracetic Acid Market