
 Green Solvents Market | 2026-2036
Green Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Green Solvents Market Intelligence
ISO 14001 environmental management certification is rotating as a baseline qualifier for green solvent suppliers seeking industrial contracts. BASF SE leverages its integrated biorefinery network to secure feedstock cost advantages across European coatings markets. Dow Inc. anchors North American supply through its glycol ether and bio-derived alcohol platforms. Evonik Industries AG differentiates via specialty ester solvents targeting pharmaceutical purity grades.
Green solvents comprise renewable-origin or low-toxicity liquid media formulated to replace petroleum-derived alternatives in dissolution, dispersion, and surface preparation processes, typically meeting volatility thresholds below 50 grams per liter and biodegradability standards exceeding 60 percent within 28 days. Their primary industrial purpose centers on reducing hazardous air pollutant emissions and worker exposure risks during manufacturing and product application. Bio-based solvents command expanding volume share in coatings formulation, while ethanol maintains cost leadership across cleaning agent applications; pharmaceutical-grade glycerol derivatives capture concentrated margin pools due to stringent USP and EP monograph compliance requirements.
EPA hazardous air pollutant standards under NESHAP constrain conventional solvent use in coatings and cleaning operations, while REACH registration obligations in Europe enforce substitution principles for substances of very high concern. FDA pharmaceutical manufacturing guidelines and USP monograph specifications govern solvent purity thresholds for drug synthesis and extraction applications. Stakeholders must monitor evolving state-level volatile organic compound regulations and biobased content certification schemes to align product portfolios with procurement specifications.
Market Dynamics
REACH substitution mandates are forcing pharmaceutical and coatings formulators to purge substances of very high concern from supply chains, compressing procurement timelines and elevating bio-based solvent specifications.
Growth Catalysts
- REACH SVHC substitution deadlines:ECHA's rolling candidate list expansions compel European coatings manufacturers to reformulate with bio-based esters and glycol ethers ahead of authorization sunsets.
- Pharmaceutical extraction purity grades:USP and EP monograph compliance requirements for residual solvent limits drive demand for pharmaceutical-grade glycerol derivatives in active pharmaceutical ingredient synthesis.
- Automotive waterborne coating transitions:Germany's industrial chemical corridor serves as the primary demand cluster as OEMs phase out high-VOC primers and clearcoats.
Market Restraints
- Feedstock price volatility:Corn and sugarcane ethanol costs fluctuate with agricultural commodity cycles, squeezing margin predictability for bio-based alcohol producers.
- Biorefinery supply concentration:Integrated chemical majors in Northwestern Europe control upstream fermentation and catalytic upgrading capacity, limiting independent formulator access.
- Performance gaps in high-solids applications:Bio-derived solvents exhibit slower evaporation profiles than petroleum-based ketones in certain industrial coating systems.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives for green chemistry manufacturing attract capacity investments serving domestic pharmaceutical and agrochemical formulators.
- Supercritical CO2 extraction convergence:Pairing bio-based co-solvents with supercritical fluid technology opens pharmaceutical and nutraceutical extraction applications requiring solvent-free final products.
- Direct supplier-formulator partnerships:Long-term offtake agreements between biorefinery operators and coatings manufacturers bypass traditional distributor markups.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits and third-party verification create 12-18 month qualification delays for new supplier entrants.
- Multinational formulation standardization:Regional regulatory divergence between EPA NESHAP, REACH, and state-level VOC rules fragments product portfolio requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Solvents Market |
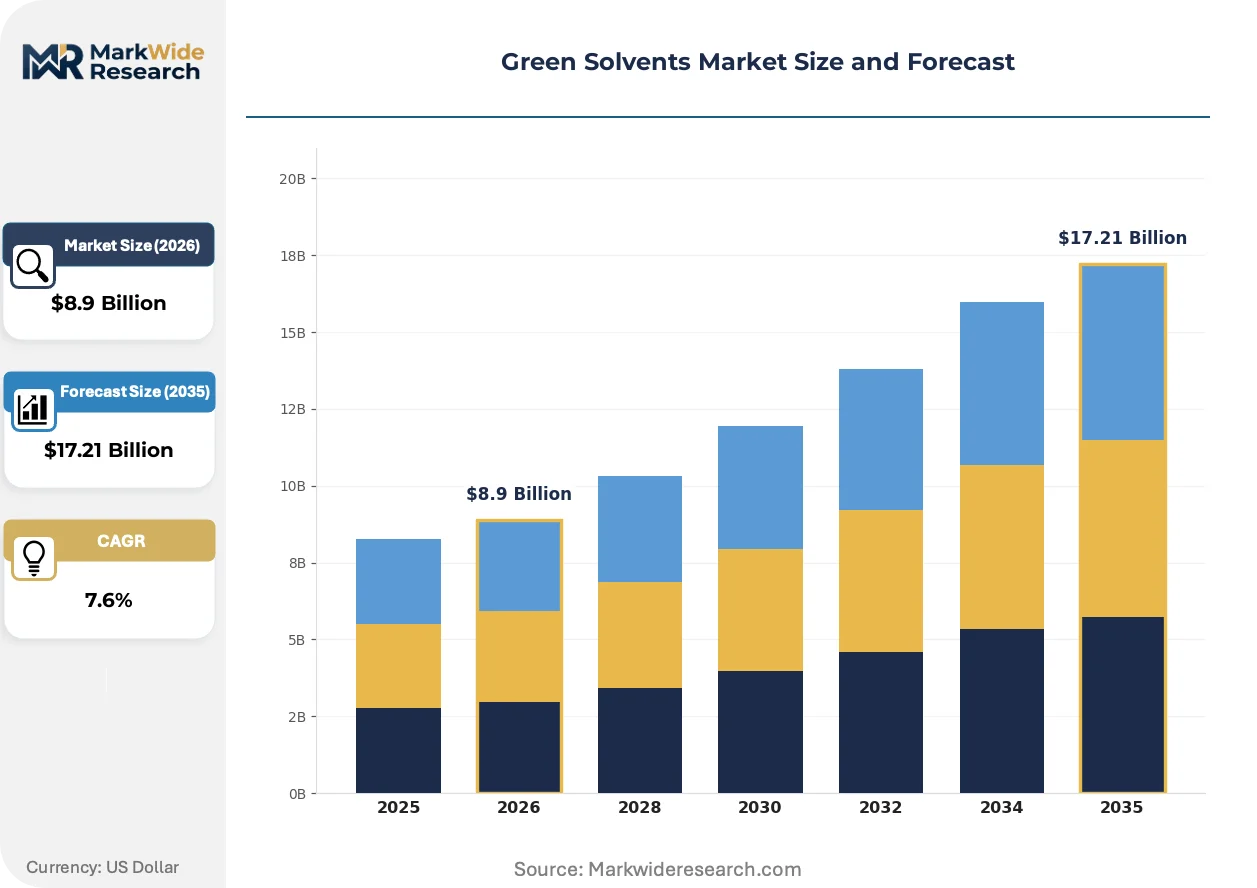
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $17.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Solvents, Ethanol, D-limonene, Glycerol Application: Coatings, Adhesives, Cleaning Agents, Paints End User: Paints & Coatings, Pharmaceuticals, Personal Care, Automotive Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | LyondellBasell Industries N.V., Solvay S.A., Dow Inc., Clariant AG, Ashland Global Holdings Inc., BASF SE, Evonik Industries AG, DuPont de Nemours, Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Solvents Market Strategic Shifts & Innovations
Enzymatic esterification processes are reshaping how specialty solvent manufacturers achieve chirality and purity specifications without petrochemical feedstocks.
Next-generation bio-ester solvents derived from waste glycerol and fatty acid methyl esters are supplanting conventional petroleum-based glycol ethers in automotive refinish and industrial maintenance coatings. Tier-1 automotive suppliers in Stuttgart and Wolfsburg have accelerated qualification timelines from 24 months to 12 months. This compression is collapsing traditional supplier incumbency periods and opening procurement windows for biorefinery-integrated challengers.
EPA NESHAP amendments for hazardous air pollutants in coating operations are tightening residual solvent emission limits for facilities above threshold capacity. Metal fabrication and aerospace finishing shops face capital expenditure decisions for abatement equipment versus solvent substitution. The Midwestern US manufacturing belt exhibits the fastest compliance-driven switching behavior, with formulators actively qualifying bio-based alternatives to avoid permit modifications.
Certification-driven procurement mandates from ISO 14001-certified OEMs are restructuring supplier evaluation criteria. Coatings buyers now require documented biodegradability exceeding 60 percent within 28 days and volatility thresholds below 50 grams per liter as baseline qualifiers. Germany's automotive supply chain demonstrates the most stringent enforcement, with sustainability scorecards directly influencing contract renewal decisions.
Green Solvents Market Segmentation
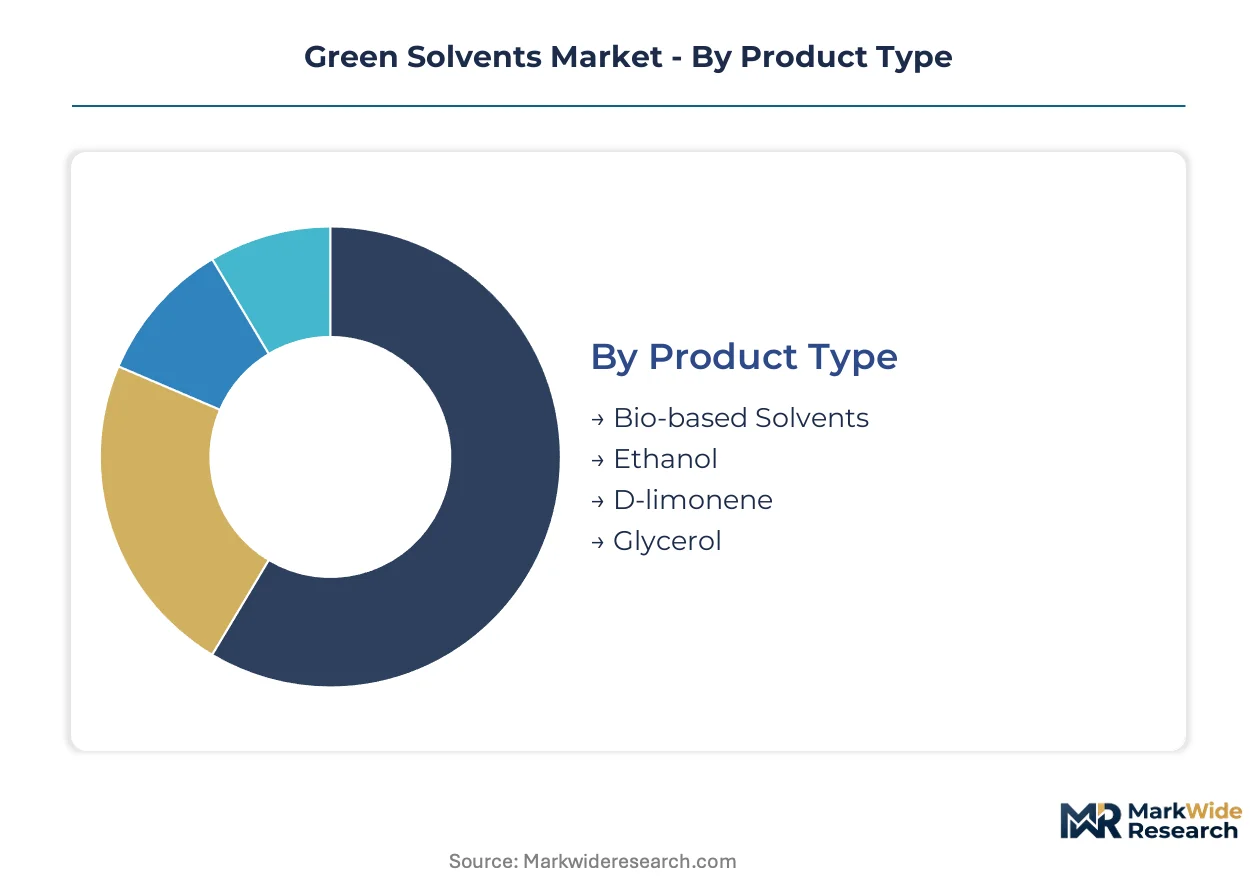
Green solvent procurement patterns diverge sharply across product chemistries and end-use specifications. Regulatory thresholds for volatility and biodegradability create tiered compliance burdens that reshape volume allocation across segments.
Product Type:
REACH SVHC authorization timelines and EPA NESHAP emission thresholds differentiate solvent categories by substitution urgency and purity requirements.
- Bio-based Solvents:Formulated from renewable feedstocks including corn starch, sugarcane bagasse, and waste glycerol through enzymatic or catalytic conversion. German automotive OEMs in Stuttgart and Wolfsburg compress qualification windows to 12 months as waterborne coating mandates tighten.
- Ethanol:Fermentation-derived alcohol meeting pharmaceutical USP and EP monograph specifications for residual solvent limits. Cleaning agent manufacturers favor its cost position despite agricultural commodity price swings.
- D-limonene:Citrus peel extract solvent carrying GRAS status for food-contact applications.
- Glycerol:Pharmaceutical-grade derivatives commanding premium positioning through USP and EP compliance.
Bio-based solvents handle the majority of throughput; glycerol derivatives are gaining share fastest on margin expansion.
Application:
End-use performance requirements segment demand by evaporation rate, solids compatibility, and surface preparation standards.
- Coatings:Waterborne and high-solids formulations for automotive refinish, industrial maintenance, and architectural finishes. Germany's industrial chemical corridor concentrates demand as OEMs phase out high-VOC primers.
- Cleaning Agents:Precision degreasing and surface preparation for metal fabrication, electronics, and aerospace finishing. Midwestern US manufacturing belt exhibits fastest compliance-driven switching to avoid EPA NESHAP permit modifications.
- Adhesives:Bonding applications requiring controlled volatility and substrate compatibility.
- Paints:Decorative and protective formulations with biodegradability thresholds exceeding 60 percent within 28 days.
Coatings commands the largest volume position; cleaning agents are expanding most quickly on regulatory enforcement.
End User:
ISO 14001 certification mandates and sustainability scorecards restructure procurement criteria across buyer categories.
- Paints & Coatings:Formulators serving automotive, industrial, and architectural end markets with documented volatility below 50 grams per liter.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and extraction operations governed by FDA guidelines and USP monograph specifications. Residual solvent limits drive pharmaceutical-grade glycerol derivative procurement.
- Personal Care:Cosmetic and hygiene product manufacturers seeking GRAS and ECOCERT compliance.
- Automotive:Tier-1 suppliers and OEM coating operations with the most stringent sustainability scorecard enforcement.
Paints & Coatings carries the dominant share; pharmaceuticals climbs the fastest on purity grade premiums.
Distribution Channel:
Supply chain configuration determines margin capture between biorefinery operators and formulator end users.
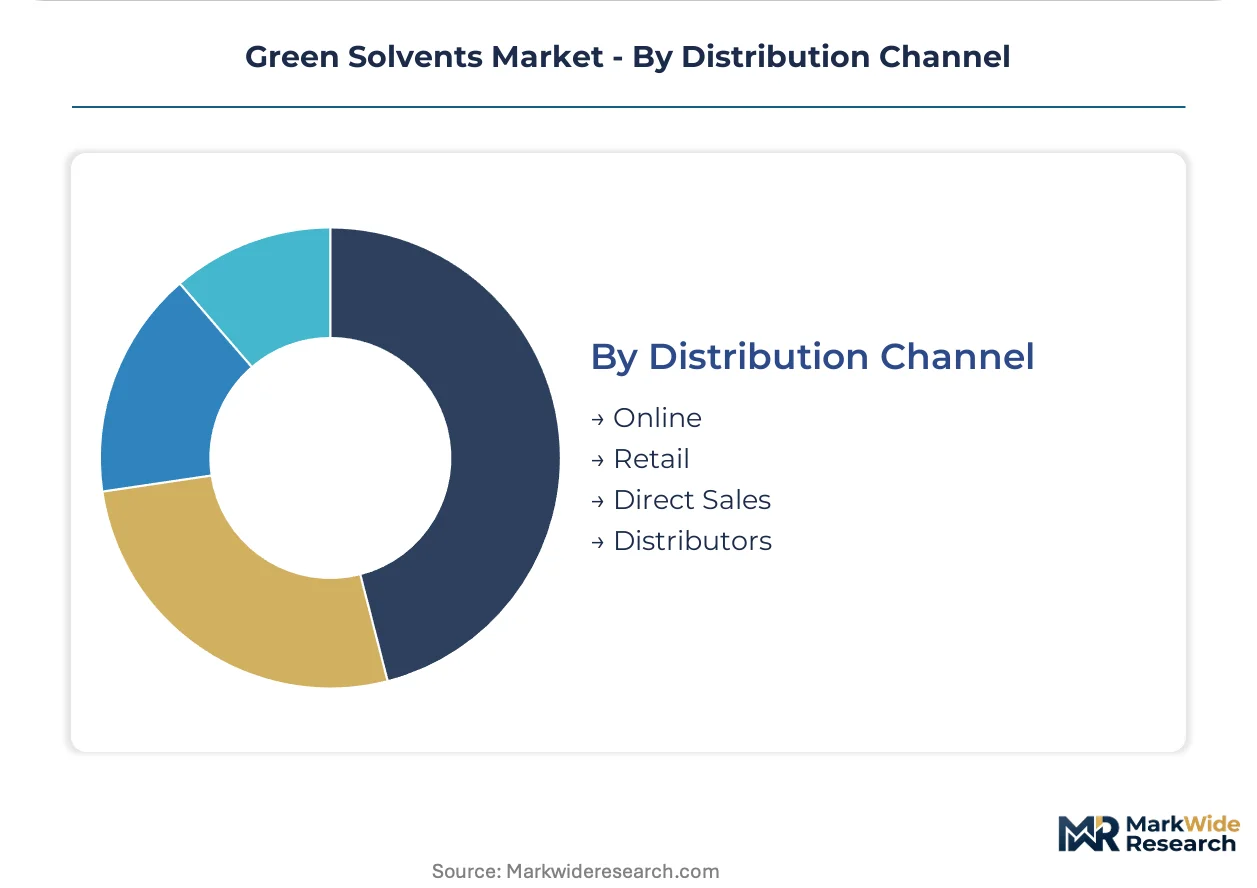
- Direct Sales:Long-term offtake agreements between integrated biorefinery operators and coatings manufacturers bypass traditional distributor markups. BASF SE leverages its network for feedstock cost advantages.
- Distributors:Regional chemical distributors serving independent formulators lacking integrated supply access. Northwestern European concentration limits independent formulator participation.
- Online:Digital procurement platforms for standardized solvent grades and spot volume requirements.
- Retail:Small-volume sales to maintenance shops and specialty applicators.
Direct sales handles the majority of contracted volume; online channels are gaining share fastest on spot market flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and tightening environmental mandates are redirecting green solvent capacity investments across major manufacturing economies. Regulatory divergence between EPA NESHAP, REACH, and national biobased certification programs fragments procurement specifications while creating localized competitive advantages.
Germany
Automotive OEMs in Stuttgart and Wolfsburg compress supplier qualification windows from 24 months to 12 months as waterborne coating mandates tighten. ECHA REACH SVHC substitution deadlines force coatings formulators to purge substances of very high concern ahead of authorization sunsets. The industrial chemical corridor between Ludwigshafen and Leverkusen concentrates biorefinery-integrated supply serving automotive Tier-1 suppliers.
United States
EPA NESHAP amendments for hazardous air pollutants tighten residual solvent emission limits for metal fabrication and aerospace finishing shops above threshold capacity. The Midwestern manufacturing belt exhibits fastest compliance-driven switching behavior as formulators qualify bio-based alternatives to avoid permit modifications. Chicago and Detroit clusters anchor demand for precision degreasing applications in automotive and industrial maintenance.
China
Dual carbon goals and provincial VOC emission trading schemes accelerate waterborne coating transitions in automotive and architectural applications. The national pharmaceutical regulator enforces residual solvent limits for active pharmaceutical ingredient synthesis that mirror USP monograph specifications. Yangtze River Delta chemical parks concentrate fermentation-derived alcohol capacity serving domestic coatings and cleaning agent manufacturers.
India
PLI scheme incentives for specialty chemicals manufacturing attract green chemistry capacity investments serving domestic pharmaceutical and agrochemical formulators. BIS standards for industrial solvent biodegradability create compliance thresholds for imported alternatives. Gujarat and Maharashtra industrial corridors concentrate formulation activity for domestic paints and coatings producers expanding waterborne product lines.
Japan
METI biobased content certification schemes and JIS standards for industrial solvents restructure procurement criteria for automotive and electronics manufacturers. Pharmaceutical-grade glycerol derivative demand climbs on USP and EP compliance requirements for export-oriented API synthesis. Kansai region chemical manufacturers integrate enzymatic esterification processes to achieve chirality specifications without petrochemical feedstocks.
Green Solvents Market Key Industry Players
Player mix skews toward integrated chemical majors with captive biorefinery networks and independent specialty ester producers serving pharmaceutical purity grades. Market structure concentrates upstream capacity among Northwestern European operators while fragmenting downstream formulation across regional distributors. Strategic archetypes include biorefinery-integrated conglomerates, pharmaceutical-grade specialists, and agricultural-commodity-linked alcohol producers. Dominant competitive moves encompass direct supplier-formulator offtake agreements and enzymatic process licensing for specialty ester production.
Within the integrated chemical major tier, BASF SE and Dow Inc. anchor positions through captive feedstock networks spanning European and North American coatings markets. Evonik Industries AG occupies a specialist position targeting pharmaceutical-grade ester solvents governed by USP and EP monograph compliance. Solvay S.A. and Clariant AG represent diversified European operators with biobased platform diversification across industrial solvent applications. These archetypes exemplify how upstream integration and certification-grade specialization structure competitive positioning.
| Leading Market Players |
|---|
| LyondellBasell Industries N.V. |
| Solvay S.A. |
| Dow Inc. |
| Clariant AG |
| Ashland Global Holdings Inc. |
| BASF SE |
| Evonik Industries AG |
| DuPont de Nemours, Inc. |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Integrated biorefinery scale in Northwestern Europe establishes minimum efficient scale thresholds that compress independent formulator margins while elevating price floors for pharmaceutical-grade certification tiers. Capacity utilization rates above eighty percent at major fermentation facilities translate directly into feedstock cost advantages that reshape competitive positioning across coatings and cleaning agent markets.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade glycerol derivatives and industrial ethanol grades. Three-tier pricing structure across premium, standard, and economy levels reflects USP and EP monograph compliance, ISO 14001 environmental management certification, and volatility thresholds below fifty grams per liter. Cost compression in industrial ethanol runs through agricultural commodity price cycles, squeezing margin predictability for fermentation-based producers. Cleaning agent manufacturers exhibit highest price sensitivity due to volume procurement and specification flexibility, while pharmaceutical API synthesis operations accept premium positioning for residual solvent limit compliance.
Supply Chain Analysis
Germany, the United States, and China anchor green solvent production across biorefinery-integrated chemical majors, Midwestern manufacturing belt demand clusters, and Yangtze River Delta fermentation capacity. Upstream supply draws from corn starch, sugarcane bagasse, and waste glycerol feedstocks. Single-source vulnerability concentrates at enzymatic esterification catalyst suppliers serving specialty solvent chirality specifications. Distribution runs through direct long-term offtake agreements between integrated producers and automotive OEMs, bypassing traditional chemical distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC substitution deadlines and EPA NESHAP amendments are compressing procurement timelines from twenty-four months to twelve months, creating a high-growth disruption window for biorefinery-integrated challengers.
For Market Incumbents: Fortify captive feedstock networks through backward integration into corn and sugarcane sourcing regions to offset agricultural commodity volatility. Expand enzymatic esterification licensing programs to capture specialty solvent margin pools threatened by pharmaceutical-grade purity requirements. Lock in direct supplier-formulator partnerships with Stuttgart and Wolfsburg automotive clusters before qualification windows collapse further.
For New Entrants and Emerging Players: Lead with India's PLI scheme for specialty chemicals manufacturing as a white-space entry point serving domestic pharmaceutical and agrochemical formulators. Target precision degreasing applications in the Midwestern US manufacturing belt where EPA NESHAP compliance drives fastest switching behavior. Pursue supercritical CO2 extraction convergence partnerships with nutraceutical processors requiring solvent-free final products.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biorefinery-integrated specialists with enzymatic process capabilities over commodity alcohol producers. Five-to-ten year viability hinges on regulatory substitution mandates hardening across European and North American jurisdictions. Watch ECHA candidate list expansion velocity as the primary inflection signal for authorization-driven demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn and sugarcane sourcing control insulates margin predictability from agricultural commodity cycles. |
| Enzymatic Esterification Licensing | Specialty solvent chirality specifications unlock pharmaceutical-grade premium positioning without petrochemical inputs. |
| Direct Supplier-Formulator Partnerships | Long-term offtake agreements with Stuttgart automotive OEMs bypass distributor markups and compress qualification timelines. |
| Supercritical CO2 Extraction Convergence | Pairing bio-based co-solvents with supercritical fluid technology opens nutraceutical applications requiring solvent-free outputs. |
| ISO 14001 Certification Investment | Environmental management system qualification serves as baseline entry ticket for industrial coatings procurement scorecards. |
Research Approach
Operator-level perspectives from biorefinery plant managers, coatings formulator procurement leads, pharmaceutical API synthesis directors, and specialty chemical distribution channel partners anchored the qualitative base. Primary interview findings triangulated against secondary validation from ECHA REACH registration databases, EPA NESHAP regulatory filings, SEC 10-K disclosures of listed chemical majors, and customs trade data tracking fermentation-derived alcohol flows. Bottom-up volume modeling across product chemistries and end-use specifications converged with top-down macroeconomic demand elasticity assessments.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios, regulatory timeline acceleration cases, and automotive OEM qualification compression patterns. Segmentation dimensions modeled include product chemistry tier, application performance requirements, end-user certification mandates, and regional regulatory framework clusters. CAGRs were derived from regression analysis of historical volume trajectories against substitution deadline schedules and purity grade premium evolution. Industry-specific forecast inputs incorporated enzymatic process yield improvements and waterborne coating transition rates at German automotive facilities.
Forecasts assume regulatory continuity in REACH SVHC authorization timelines and EPA NESHAP amendment implementation; material policy shifts would require re-modeling substitution urgency and compliance cost burdens. Specific risks that could revise projections include ECHA candidate list expansion velocity exceeding modeled scenarios, agricultural commodity price spikes disrupting ethanol cost positions, and performance gap closures in high-solids coating applications accelerating bio-derived solvent displacement. Recalibration cycles align with material shifts in regulatory deadline schedules, biorefinery capacity commissioning announcements, and automotive OEM sustainability scorecard criterion updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ethyl Pyruvate Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Global Droppers Market
Solvents
Benzene Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Dimethyl Formamide Market
Solvents
Ortho-Xylene Market
Solvents
Diethanolamine (DEA) Market
Solvents
Global Solvent Evaporation Market
Solvents
Methyl Undecylenate Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Alpha-Methylstyrene Market
Solvents
Butane Market