
 Global Xylenols Market | 2026-2036
Global Xylenols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Xylenols Market Analysis
Specialized chemical engineering talent is bifurcating the competitive landscape, with experienced process chemists commanding premium wages at established producers while newer entrants struggle to replicate legacy expertise. Sasol leverages its Fischer-Tropsch heritage to sustain integrated xylenol production from coal-derived feedstocks in South Africa. Solvay anchors European supply through its phenol derivatives chain, competing on specification consistency for pharmaceutical-grade output. LANXESS specializes in high-purity meta-xylenol for agrochemical intermediates, dominating niche specifications that generic producers cannot match.
Xylenols comprise six dimethylphenol isomers derived from coal tar distillation or petroleum reformate extraction, with melting points ranging from 24°C to 75°C and critical solubility parameters governing their use as chemical intermediates. These compounds serve primarily as precursors for antioxidants, disinfectants, and pesticide formulations where isomeric purity determines downstream performance. Para-xylenol leads volume consumption in antioxidant applications for rubber and plastics, while meta-xylenol represents the fastest-growing isomer segment driven by demand in pharmaceutical synthesis and veterinary disinfectants. The solvents application category captures concentrated margin pools where technical-grade specifications command pricing premiums over commodity industrial uses.
REACH registration requirements in Europe and EPA toxic substance controls in the United States constrain product entry pathways, forcing producers to maintain exhaustive substance documentation and exposure assessments. China's GB standards for phenolic derivatives and India's BIS certification for chemical imports further fragment compliance obligations across supply chains. Stakeholders must monitor regulatory divergence on isomer-specific hazard classifications, as reclassification under ECHA review or MEE environmental priority lists would force reformulation investments across multiple end-use segments.
Market Dynamics
REACH compliance deadlines in Europe are forcing xylenol producers to reformulate antioxidant and disinfectant lines, redirecting technical resources toward isomer-specific hazard documentation rather than capacity expansion.
Growth Catalysts
- Agrochemical intermediates:Meta-xylenol demand from veterinary disinfectant and crop protection synthesis is accelerating in India and China as domestic agrochemical manufacturing scales.
- REACH registration completion:European producers who secured full substance dossiers before 2023 deadlines now capture specification-driven contracts that exclude non-registered competitors.
- Rubber antioxidant reformulation:Para-xylenol derivatives are replacing legacy phenolic antioxidants in tire manufacturing as durability standards tighten under NHTSA performance mandates in the United States.
Market Restraints
- Coal tar feedstock volatility:Coking rate reductions at European steel plants have tightened coal tar availability, elevating input costs for traditional distillation-based xylenol production.
- South African supply concentration:Fischer-Tropsch-derived xylenol output from a single integrated complex creates geographic vulnerability for global meta-xylenol supply.
- Petroleum reformate competition:Refinery optimization for gasoline blending is displacing xylenol extraction economics at North American and Middle Eastern aromatics complexes.
Strategic Opportunities
- Pharmaceutical-grade meta-xylenol:Unmet demand from CDMOs in Switzerland and Germany exceeds certified European production capacity, creating entry points for qualified importers.
- India BIS certification alignment:Producers who pre-certify technical-grade xylenols under Bureau of Indian Standards specifications gain preferential access to agrochemical formulation houses in Gujarat and Maharashtra.
- Biomass-derived phenolics convergence:Lignin pyrolysis pathways are approaching commercial viability for dimethylphenol production, offering carbon-intensity advantages under EU Green Deal border adjustment mechanisms.
Industry Challenges
- Process chemist scarcity:Isomer separation expertise concentrated among retiring specialists at legacy coal tar distillers cannot be replicated through standard chemical engineering curricula.
- Dual-use export licensing:Xylenol precursors with pesticide applications trigger chemical weapons convention controls, extending shipment documentation timelines by 60-90 days for certain destinations.
- Legacy distillation asset retrofit:Cryogenic separation upgrades required for pharmaceutical-grade purity demand capital commitments that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Xylenols Market |
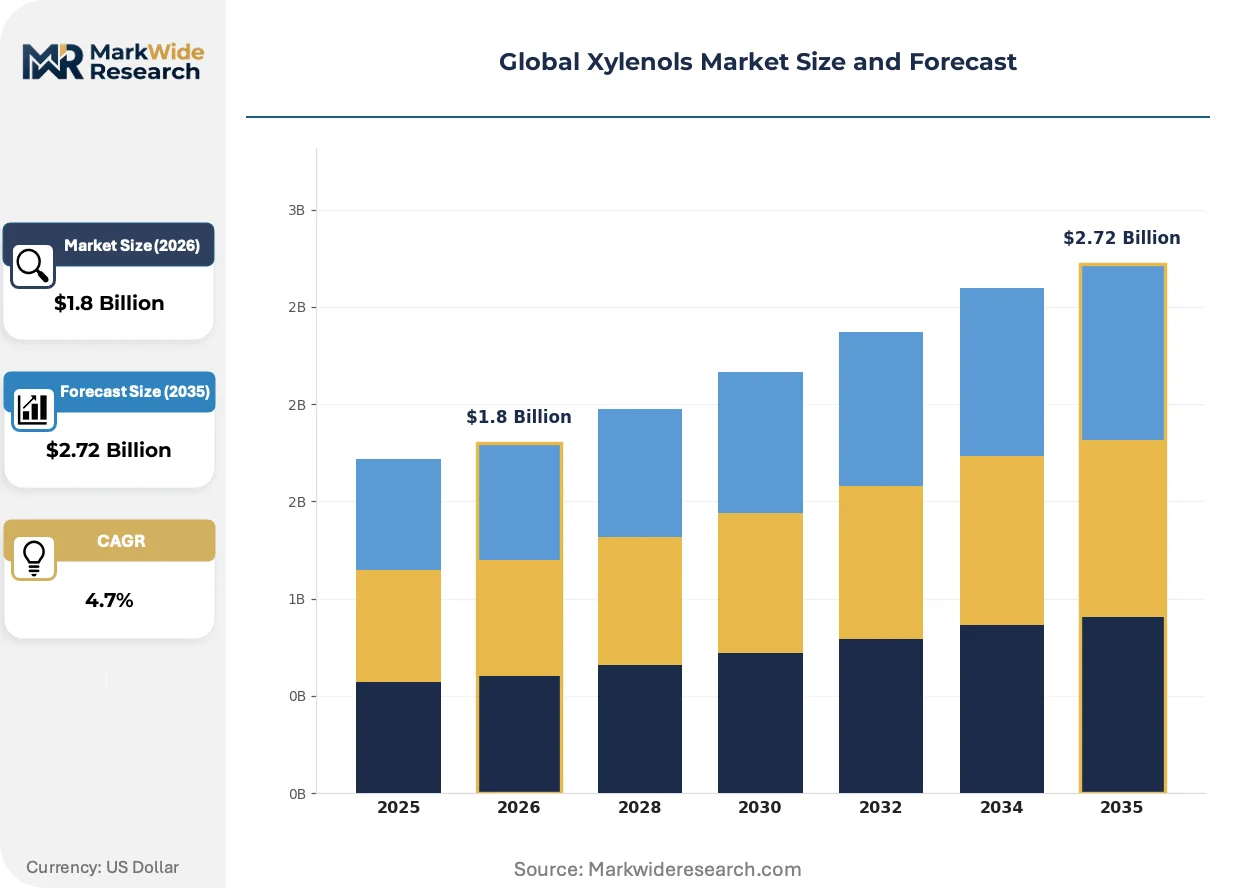
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ortho-Xylenol, Para-Xylenol, Meta-Xylenol, Mixed Xylenols End Use Industry: Healthcare, Chemicals, Agriculture, Textiles Application: Solvents, Pesticides, Resins, Coatings Form: Liquid, Solid, Powder, Granules |
| Companies Covered | Sasol, Solvay, LANXESS, SABIC, Deepak Novochem Technologies Limited, SI Group, TCI Chemicals (India) Pvt. Ltd, Nanjing Datang Chemical, DEZA a. s., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Xylenols Market Emerging Trajectories
Process intensification and regulatory data requirements are compressing the viable producer base while opening technical entry points for specialized purification technologies. Isomer-specific value capture is replacing commodity volume strategies across the supply chain.
Membrane-based isomer separation is displacing traditional fractional crystallization in xylenol purification operations. Agrochemical intermediate producers in China are adopting ceramic nanofiltration modules to achieve meta-xylenol purities above 99.5 percent without solvent-intensive recrystallization. This displacement is compressing energy consumption per ton by 30-40 percent while tightening specification consistency for downstream pharmaceutical applications.
EU F-Gas Regulation amendments are accelerating refrigerant sector demand for xylenol-derived antioxidants in compressor lubricants. The regulation's phasedown of hydrofluorocarbons is forcing equipment manufacturers to reformulate with alternative working fluids that degrade faster without phenolic stabilization. European HVAC component suppliers are now specifying high-purity para-xylenol antioxidants in procurement contracts that exclude technical-grade alternatives.
Specification-driven procurement contracts are consolidating buyer power among agrochemical multinationals with internal analytical capabilities. These buyers now require isomer-specific certificates of analysis with every shipment, displacing spot-market purchasing for standard technical grades. The shift is most visible in Germany and the Netherlands, where formulation houses have eliminated inventory positions for uncertified xylenol streams.
Global Xylenols Market Segmentation
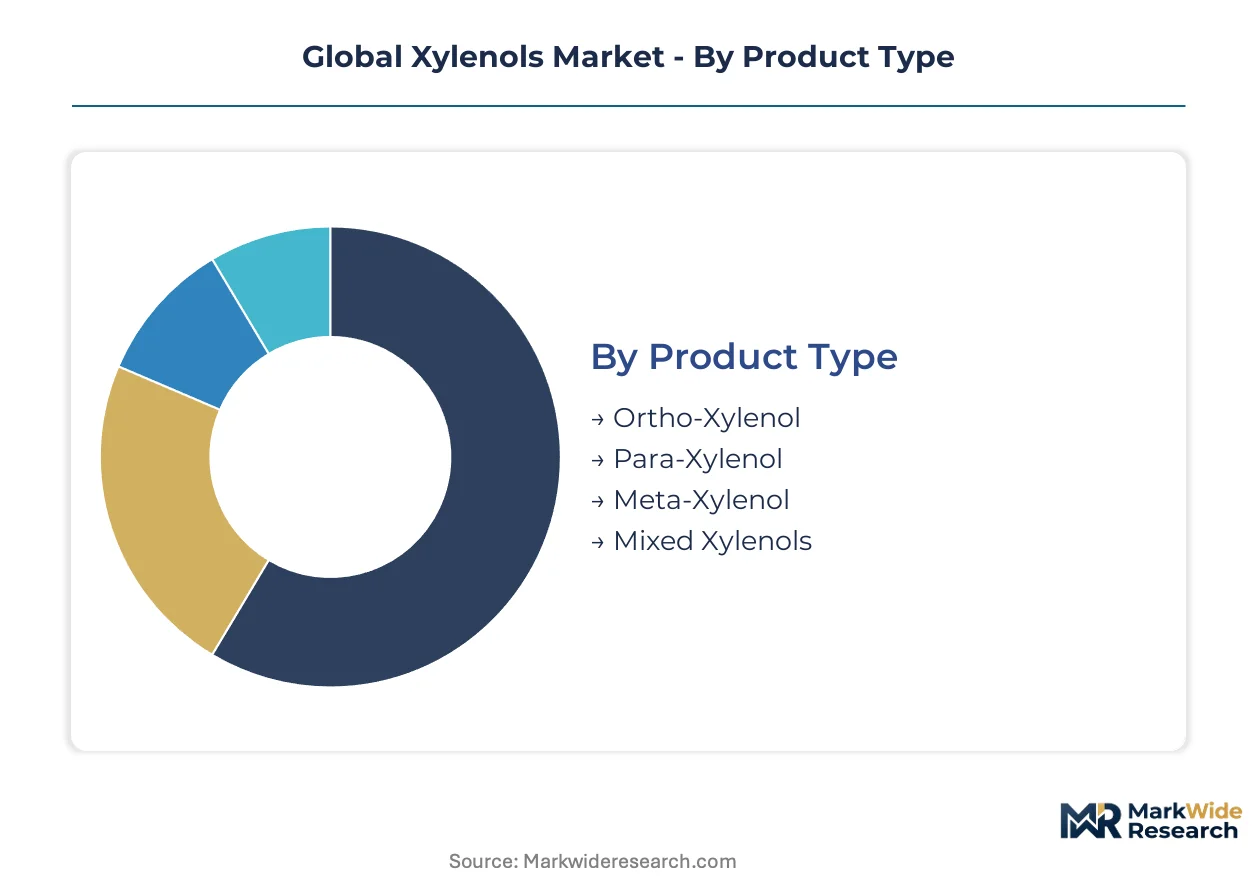
Xylenol isomeric purity and physical form specifications determine downstream performance in antioxidants, disinfectants, and agrochemical intermediates. Regulatory compliance requirements fragment procurement patterns across pharmaceutical-grade, technical-grade, and industrial-grade tiers. Buyers now demand substance dossiers and certificates of analysis that align with REACH, EPA, and BIS certification standards.
Product Type:
REACH registration deadlines and isomer-specific hazard classifications differentiate commercial viability across dimethylphenol variants. ECHA review timelines and MEE environmental priority lists force producers to maintain exhaustive documentation for each structural isomer.
- Para-Xylenol:The 2,5-dimethylphenol isomer dominates antioxidant applications for rubber and plastics stabilization. Tire manufacturers in Germany and the United States specify para-xylenol derivatives under NHTSA durability mandates and EU F-Gas Regulation refrigerant system requirements. Specification contracts now exclude non-registered suppliers.
- Meta-Xylenol:This isomer commands premium positioning in pharmaceutical synthesis and veterinary disinfectant formulations. CDMOs in Switzerland and Germany face certified supply shortages, while agrochemical intermediate producers in Gujarat and Maharashtra scale domestic meta-xylenol consumption.
- Ortho-Xylenol:The 2,6-dimethylphenol variant serves specialized solvent applications with narrower commercial penetration than para- and meta- isomers.
- Mixed Xylenols:Technical-grade blends capture industrial solvent markets where isomeric separation economics prove prohibitive for downstream users.
Established volume favors para-xylenol; emerging adoption favors meta-xylenol.
End Use Industry:
Cost tier differentiation separates specification-driven pharmaceutical procurement from commodity industrial purchasing. Internal analytical capabilities at multinational buyers consolidate contract power toward certified supply chains.
- Chemicals:Antioxidant and resin intermediate manufacturers represent the foundational demand base. Para-xylenol derivatives stabilize rubber and plastics across tire, HVAC compressor lubricant, and industrial polymer applications where phenolic antioxidant reformulation accelerates.
- Agriculture:Veterinary disinfectant and crop protection synthesis drives meta-xylenol volume expansion. Domestic agrochemical manufacturing in India and China scales technical-grade consumption while European formulation houses demand pharmaceutical-grade certificates.
- Healthcare:Pharmaceutical-grade meta-xylenol serves CDMO synthesis operations with purity requirements exceeding standard technical specifications.
- Textiles:Dye intermediate and fiber treatment applications consume mixed xylenol grades at lower specification thresholds than pharmaceutical or agrochemical segments.
Margin concentration sits with chemicals; steepest expansion trajectory belongs to agriculture.
Application:
Customer type fragmentation separates spot-market industrial buyers from long-term contract holders with isomer-specific analytical requirements. Procurement departments with internal GC-MS capabilities now mandate certificates of analysis per shipment.
- Solvents:Technical-grade specifications command pricing premiums over commodity industrial uses in extraction and cleaning applications. Membrane-based isomer separation at Chinese producers achieves purity above 99.5 percent without solvent-intensive recrystallization.
- Pesticides:Meta-xylenol precursors trigger dual-use export licensing under chemical weapons convention controls. Shipment documentation extends 60-90 days for certain destinations, constraining supply chain responsiveness.
- Resins:European manufacturers reformulate products under REACH compliance deadlines, redirecting technical resources toward hazard documentation rather than capacity expansion.
- Coatings:Industrial protective and decorative applications consume mixed xylenol grades at lower purity thresholds than pharmaceutical or agrochemical segments.
Contract stability favors resins; regulatory friction weighs on pesticides.
Form:
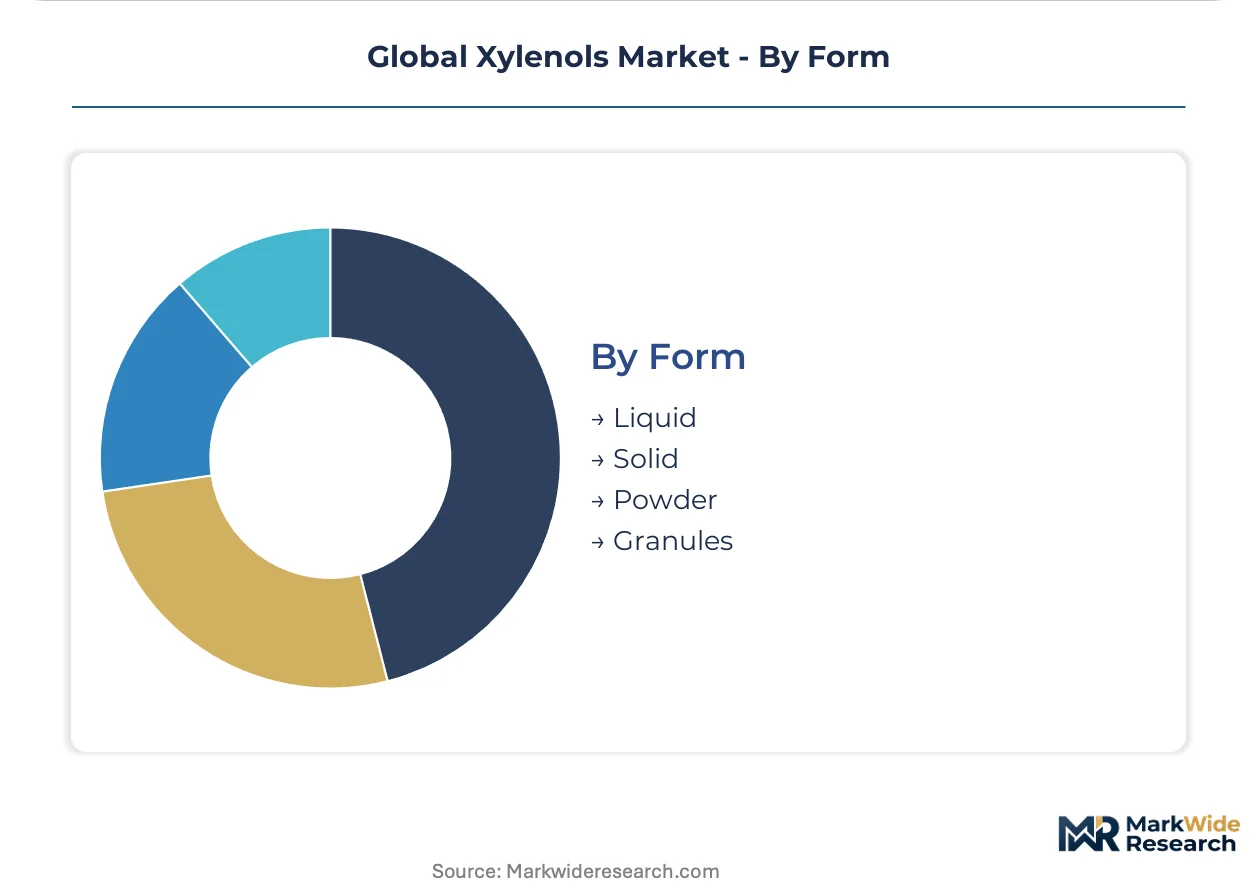
Supply concentration in South African Fischer-Tropsch output and European coal tar distillation shapes physical form availability. Cryogenic separation upgrades for pharmaceutical-grade purity demand capital commitments that mid-scale producers struggle to finance.
- Liquid:Molten or dissolved xylenol streams dominate bulk industrial handling and continuous process integration. Coking rate reductions at European steel plants tighten coal tar feedstock availability for traditional distillation-based production.
- Solid:Crystalline forms suit pharmaceutical and high-purity agrochemical applications where melting point precision matters. Meta-xylenol solidification at 68°C enables specification-controlled dosing in veterinary disinfectant manufacturing.
- Powder:Micronized grades serve specialized coating and rapid-dissolution applications with narrower commercial penetration than liquid or standard solid forms.
- Granules:Controlled-release and bulk handling applications favor granular morphology for agricultural and industrial chemical blending operations.
Process efficiency favors liquid; specification premium attaches to solid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements in Europe anchor regulatory complexity for xylenol producers, while demand expansion concentrates in Asian manufacturing clusters and German specialty chemical hubs.
China
Domestic agrochemical manufacturing in Jiangsu and Zhejiang provinces drives meta-xylenol consumption for veterinary disinfectant synthesis. GB standards for phenolic derivatives enforce purity documentation that filters smaller producers from pharmaceutical-grade supply chains. Shanghai-based CDMOs now mandate certificates of analysis with every shipment, displacing spot-market purchasing.
Germany
Tire manufacturers in North Rhine-Westphalia specify para-xylenol antioxidants under NHTSA durability mandates and EU F-Gas Regulation refrigerant requirements. ECHA substance dossiers for isomer-specific hazard classifications consume technical resources at phenol derivatives producers. The Cologne-Düsseldorf chemical corridor concentrates REACH-registered supply chains that exclude non-compliant competitors.
India
Agrochemical formulation houses in Gujarat and Maharashtra scale technical-grade xylenol consumption for crop protection intermediates. BIS certification requirements for chemical imports create preferential access pathways for pre-certified producers. Domestic manufacturing clusters in Vapi and Ankleshwar now source certified meta-xylenol for veterinary disinfectant production.
United States
EPA toxic substance controls constrain product entry pathways for antioxidant and disinfectant applications. Rubber manufacturers in Ohio and South Carolina reformulate with para-xylenol derivatives as tire durability standards tighten. Gulf Coast aromatics complexes face petroleum reformate competition from gasoline blending optimization.
South Africa
Fischer-Tropsch-derived xylenol output from Sasol's integrated Secunda complex supplies global meta-xylenol demand. Geographic concentration creates supply vulnerability for pharmaceutical-grade specifications. Coal-derived feedstock integration sustains cost positioning unavailable to petroleum-based competitors.
Global Xylenols Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the xylenol supply base. Fischer-Tropsch heritage producers command integrated feedstock economics while phenol derivatives specialists compete on specification consistency. The market structure separates legacy coal tar distillers with isomer separation expertise from membrane-technology adopters in Asia. Three archetypes dominate: integrated energy-chemical conglomerates with captive feedstock, European phenol derivatives specialists with REACH registration advantages, and Chinese purification technology adopters. Competitive moves concentrate on cryogenic separation upgrades for pharmaceutical-grade purity and BIS certification alignment for Indian market access.
Within the integrated feedstock tier, Sasol anchors coal-derived xylenol production through Fischer-Tropsch integration. Solvay and LANXESS exemplify European phenol derivatives specialists competing on REACH-registered specification consistency. Deepak Novochem Technologies Limited occupies a position among India-based producers targeting BIS-certified supply chains for domestic agrochemical formulation.
| Leading Market Players |
|---|
| Sasol |
| Solvay |
| LANXESS |
| SABIC |
| Deepak Novochem Technologies Limited |
| SI Group |
| TCI Chemicals (India) Pvt. Ltd |
| Nanjing Datang Chemical |
| DEZA a. s. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day shipment documentation timelines for dual-use xylenol precursors concentrate pricing power with registered European producers while compressing margins for spot-market traders dependent on expedited customs clearance.
Pricing Analysis
Geographic price spreads between South African Fischer-Tropsch output and European pharmaceutical-grade supply exceed 40 percent on a purity-equivalent basis. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade tiers separates CDMO procurement contracts from agrochemical spot purchases. Cost compression in technical-grade para-xylenol is intensifying because Chinese membrane-separation adopters are expanding capacity without REACH registration overhead. Agrochemical formulation houses in India demonstrate highest price sensitivity, while Swiss CDMOs absorb premiums for certified meta-xylenol without volume negotiation.
Supply Chain Analysis
Secunda complex concentration in South Africa creates single-source vulnerability for global meta-xylenol supply, with any operational disruption propagating through pharmaceutical and veterinary disinfectant channels within weeks. Production gravity centers on South Africa, Germany, and China, with each node serving distinct specification tiers. Feedstock dependence draws from coal tar distillation, petroleum reformate extraction, and Fischer-Tropsch synthesis. Tariff exposure on Chinese ceramic nanofiltration modules threatens cost positioning for membrane-based purifiers. Distribution runs through long-term offtake contracts with agrochemical multinationals and spot-market traders serving industrial solvent buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based isomer separation is reshaping cost structures faster than incumbent cryogenic assets can retrofit, creating a narrow window for technology-led disruption before regulatory consolidation hardens.
For Market Incumbents: Shield specification-registered positions by accelerating cryogenic separation upgrades for pharmaceutical-grade purity before membrane-technology adopters achieve comparable certification. Secure backward integration into coal tar feedstocks or Fischer-Tropsch synthesis to isolate input cost volatility from European steel plant coking rate reductions.
For New Entrants and Emerging Players: Anchor in India BIS certification pathways for technical-grade meta-xylenol supply to Gujarat and Maharashtra agrochemical clusters, where domestic formulation houses are displacing uncertified imports. Pursue joint development agreements with CDMOs in Switzerland and Germany facing certified supply shortages, offering membrane-purified product under tolling arrangements rather than spot-market exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH-registered substance dossiers and isomer-specific hazard documentation create durable moats that capital cannot rapidly replicate. Target producers with completed ECHA registrations and existing pharmaceutical-grade capacity. Monitor ECHA review timelines for isomer reclassification as the signal indicating forced reformulation investments and contract reshuffling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal Tar Feedstocks | Sasol's Fischer-Tropsch heritage demonstrates captive supply economics unavailable to petroleum-dependent competitors. |
| Membrane Separation Technology Adoption | Chinese producers achieve 99.5 percent meta-xylenol purity without solvent-intensive recrystallization, compressing energy consumption. |
| REACH Registration Completion | European producers with full substance dossiers capture specification-driven contracts excluding non-registered competitors. |
| BIS Certification Alignment | Pre-certified producers gain preferential access to agrochemical formulation houses in Gujarat and Maharashtra. |
| Cryogenic Separation Upgrade | Pharmaceutical-grade purity demands capital commitments that mid-scale producers struggle to finance. |
Methodological Framework
Initial hypotheses were tested against primary input from phenol derivatives plant managers, agrochemical procurement leads at multinational formulation houses, distribution channel partners in India and China, and technical R&D directors specializing in isomer separation. These perspectives were refined against customs and trade data, chemical industry association reports from ACC and Cefic, SEC 10-K filings of listed producers, and ECHA substance dossier databases. Bottom-up capacity and consumption estimates were triangulated with top-down market sizing derived from end-use industry consumption patterns.
Variance decomposition across isomer type, grade tier, end-use industry, and regional production hub informed the analytical framework. CAGRs were derived from segmented growth rate modeling applied across the projection horizon. Key forecast inputs included REACH registration completion rates, coking rate trajectories at European steel plants, and membrane-technology adoption curves at Chinese producers.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory divergence and stable coal tar feedstock availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA isomer reclassification reviews and EU Green Deal border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
1, 1-Difluoroethane Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Japan Acetonitrile Market
Solvents
Ethyl Pyruvate Market
Solvents
Ketone-Based Solvents Market
Solvents
Mineral Turpentine Market
Solvents
Nitroglycerin Market
Solvents
Toluene Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
N-Hexane Market
Solvents
Hydrosol Market
Solvents
Diethanolamide Market
Solvents
Europe Hydrocarbon Solvents Market