
 Natural Distillates Market | 2026-2036
Natural Distillates Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Distillates Market Foresight
Direct procurement partnerships between flavor houses and botanical growers is reshaping how raw materials reach finished goods manufacturers. Kerry Group leverages captive sourcing networks across multiple growing regions to secure consistent feedstock quality. ADM anchors its position through integrated extraction and refining infrastructure that spans cultivation to concentrated output. Treatt specializes in citrus and herb distillates, competing on technical specification breadth rather than volume scale.
Natural distillates are volatile aromatic compounds recovered through steam distillation, hydrodistillation, or mechanical expression of plant biomass, typically containing terpenes, phenylpropanoids, and oxygenated derivatives at concentrations of 0.5% to 5% of raw plant weight. These extracts serve as functional ingredients where scent profiles, antimicrobial properties, or solvent characteristics determine formulation value. Essential oils and terpenes dominate current revenue contribution due to established demand from flavor and fragrance compounding, while hydrosols represent the fastest-expanding category as formulators seek water-soluble, lower-concentration botanical actives for sensitive-skin personal care. Distillate oils capture concentrated margin pools in pharmaceutical-grade applications where USP and EP monograph compliance commands price premiums over technical grades.
REACH registration requirements in Europe mandate full toxicological dossiers for fragrance ingredients above one-tonne annual volumes, pushing smaller distillers toward toll manufacturing arrangements with registered importers. FDA oversight of botanical drug substances under 21 CFR 312 demands identity testing and marker compound standardization that favors producers with analytical chemistry capabilities. USDA organic certification and EPA pesticide residue limits further constrain allowable agricultural inputs, filtering supplier eligibility for North American natural product channels. Stakeholders must monitor evolving restriction proposals under ECHA's CLH process, as reclassification of key terpenes as skin sensitizers would force reformulation investments across multiple end-use categories.
Market Dynamics
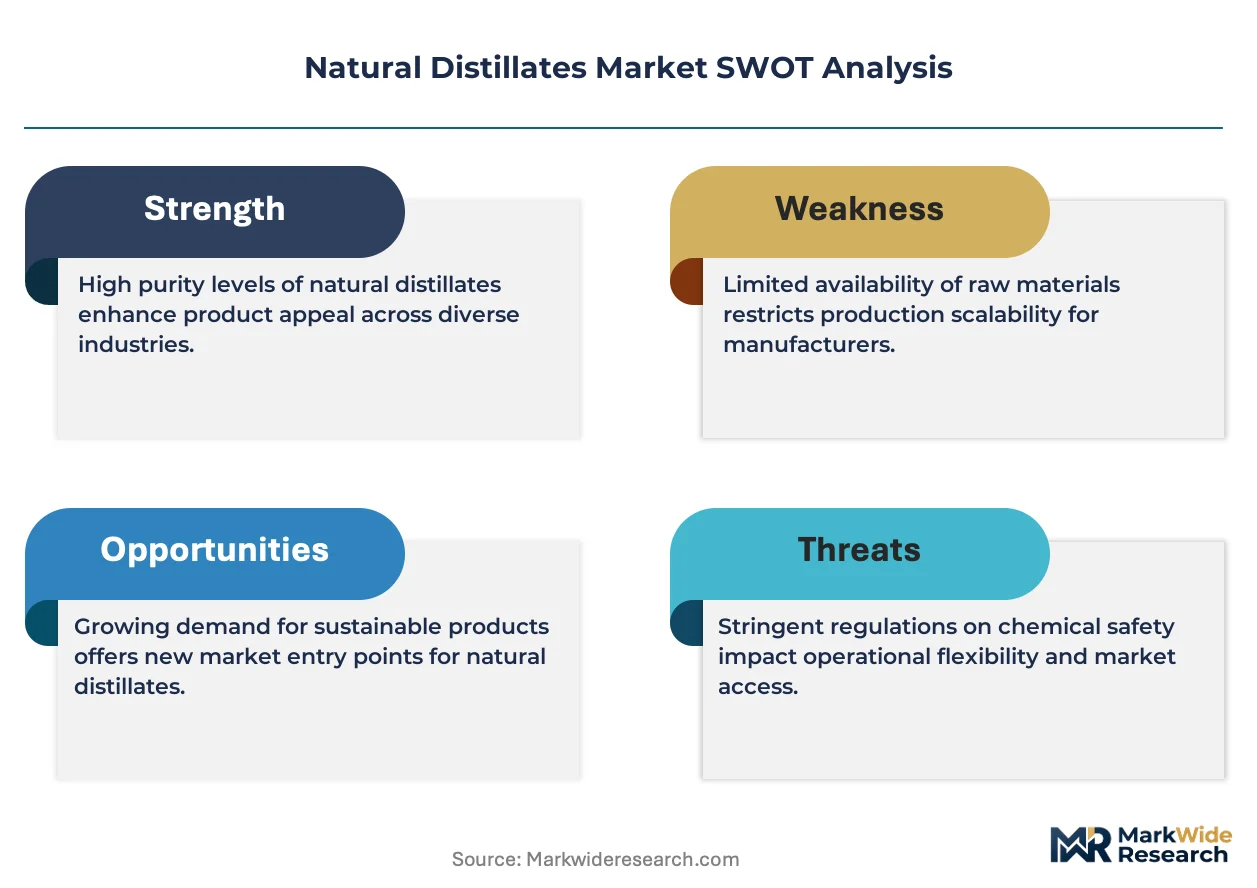
REACH registration dossiers and EU Green Deal purity mandates are compressing supplier eligibility, forcing distillers to consolidate analytical capabilities or exit European cosmetics supply chains entirely.
Growth Catalysts
- Pharmaceutical-grade standardization:USP and EP monograph compliance opens premium pricing tiers for terpene isolates used in botanical drug substances. FDA oversight under 21 CFR 312 accelerates identity testing investments.
- India:Domestic essential oil production and Ayurvedic product exports generate concentrated raw material demand from fragrance compounders.
- Hydrosol formulation adoption:Water-soluble botanical actives at lower concentrations penetrate sensitive-skin personal care segments where essential oils trigger irritation.
Market Restraints
- Input cost volatility:Agricultural feedstock prices fluctuate with climate-induced yield variability in Mediterranean citrus and Southeast Asian spice growing regions.
- Regulatory friction:ECHA's CLH process threatens reclassification of key terpenes as skin sensitizers, forcing preemptive reformulation investments across fragrance categories.
- Substitution threat:Synthetic aroma chemicals and biotechnology-derived terpenes displace natural extracts in cost-sensitive flavor applications.
Strategic Opportunities
- Captive sourcing networks:Direct procurement partnerships between flavor houses and botanical growers bypass traditional trader intermediaries, securing batch-to-batch consistency.
- Water-soluble actives:Hydrosol extraction capacity expansion targets clean-label personal care formulators seeking antimicrobial properties without oil-phase incompatibility.
- PLI scheme incentives:India's production-linked incentive framework subsidizes domestic distillation infrastructure for export-oriented Ayurvedic ingredient supply.
Industry Challenges
- Analytical chemistry talent scarcity:Marker compound standardization and chromatographic fingerprinting require specialized phytochemists in short supply across growing regions.
- Certification timeline compression:USDA organic and EPA pesticide residue compliance extends qualification cycles for new agricultural suppliers entering North American channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Distillates Market |
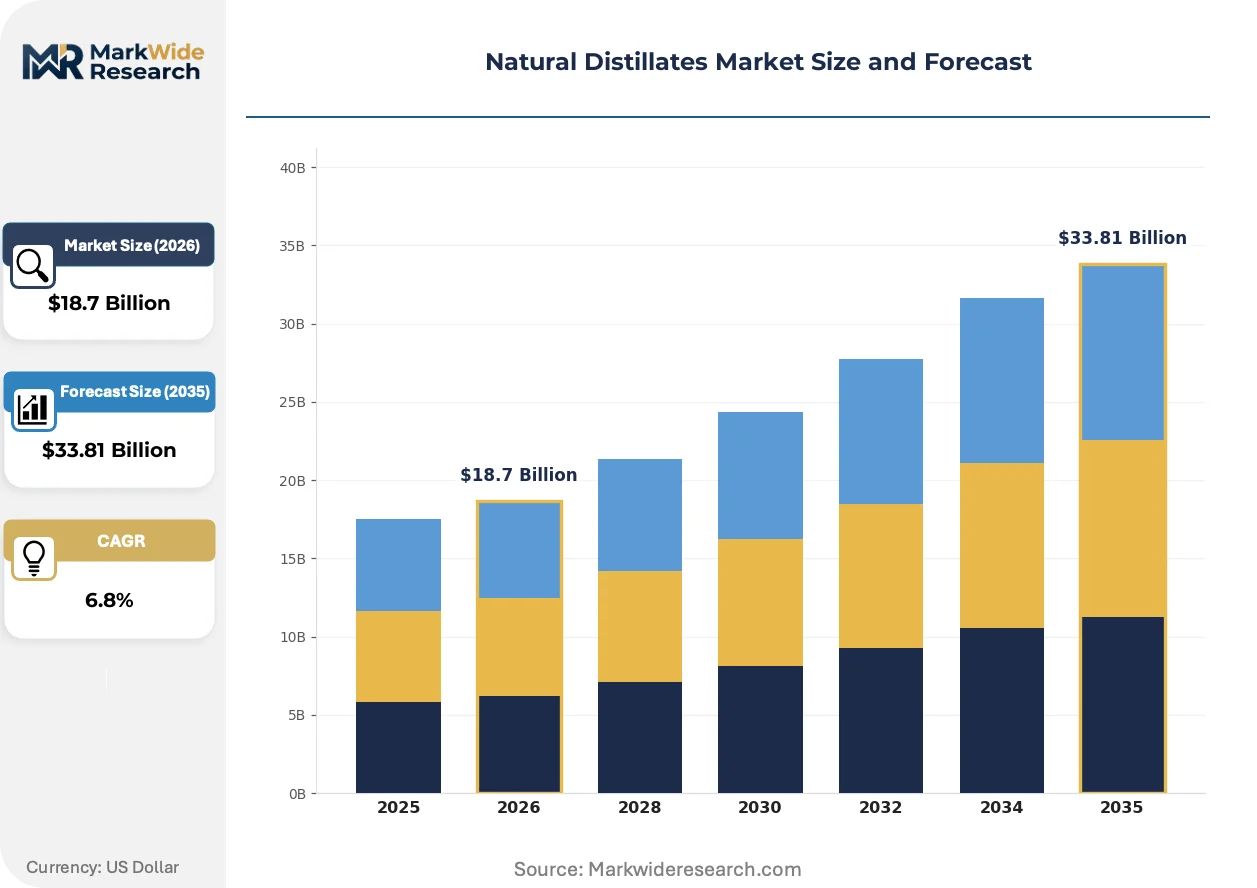
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Terpenes, Hydrosols, Distillate Oils Application: Pharmaceuticals, Cosmetics, Food & Beverage, Cleaning Products Industry Vertical: Healthcare, Personal Care, Food Industry, Chemical Manufacturing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Kerry Group, Shank's Extracts, ADM, Treatt, Flavorjen, Kanegrade, Kerr Concentrates, Rudolf Wild GmbH & Co. KG, MUL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Distillates Market Shifts & Advancements
Digital traceability platforms and extraction technology advances are compressing quality assurance cycles while regulatory pressure on chemical transparency accelerates substitution patterns across fragrance compounding.
Supercritical CO2 extraction is virtualizing traditional steam distillation for heat-sensitive terpene recovery. Pharmaceutical-grade botanical extractors adopt this method to preserve oxygenated derivatives prone to thermal degradation. The technology is virtualizing capital allocation decisions, redirecting investment from batch stills toward continuous processing infrastructure.
REACH registration requirements mandate full toxicological dossiers for fragrance ingredients above one-tonne annual volumes. Smaller distillers face compliance cost barriers that favor toll manufacturing arrangements with registered importers. European cosmetics supply chains respond by consolidating supplier panels and demanding pre-registered feedstock documentation.
Personal care brands now specify certificate-of-origin documentation and pesticide residue testing in procurement contracts. Traditional spot-market purchasing through botanical traders loses share to multi-year supply agreements with disclosed growing coordinates. This pattern concentrates most visibly in Indian sandalwood and jasmine supply chains serving premium fragrance houses.
Natural Distillates Market Segmentation
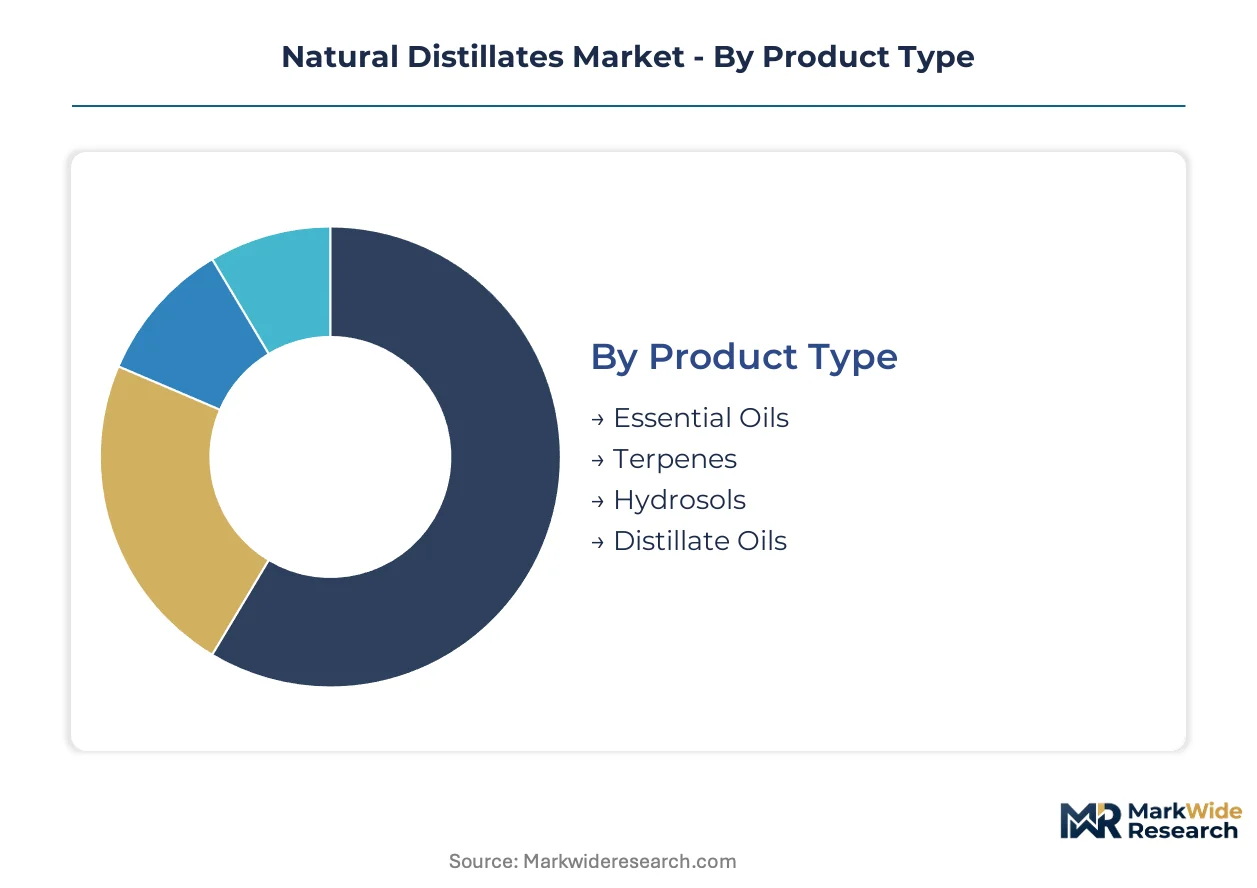
Natural distillates serve divergent functional requirements across fragrance compounding, therapeutic formulation, and antimicrobial applications. Segmentation reveals how extraction chemistry and purity grades align with end-use specifications and regulatory thresholds.
Product Type:
Steam distillation and mechanical expression yield distinct aromatic fractions with varying concentration profiles and stability characteristics.
- Essential Oils:Concentrated terpene and phenylpropanoid mixtures recovered through hydrodistillation, typically comprising 0.5% to 3% of raw plant biomass. Fragrance compounders in Grasse and Geneva concentrate procurement of lavender, rose, and citrus oils for fine perfumery, with USP-grade specifications commanding substantial premiums over technical grades for therapeutic applications.
- Hydrosols:Aqueous condensates containing water-soluble botanical actives at 0.02% to 0.1% concentration, co-produced during essential oil steam distillation. Sensitive-skin personal care formulators in California and Scandinavia specify hydrosols for antimicrobial toners and mist products where oil-phase incompatibility or irritation risk excludes conventional essential oils.
- Terpenes:Isolated monoterpene and sesquiterpene fractions used as flavor precursors and solvent adjuvants.
- Distillate Oils:Refined concentrates meeting pharmaceutical monograph standards for botanical drug substances.
The dominant share belongs to essential oils, while hydrosols are closing the gap fastest.
Application:
Formulation requirements span therapeutic efficacy, sensory performance, and antimicrobial functionality across regulated consumer categories.
- Pharmaceuticals:Botanical drug substances and excipients requiring USP and EP monograph compliance with marker compound standardization. FDA oversight under 21 CFR 312 drives identity testing investments for peppermint oil and eucalyptus distillates used in respiratory and gastrointestinal preparations.
- Cosmetics:Fragrance accords and active ingredients subject to REACH registration and EU Green Deal purity mandates. Paris-based luxury houses and Korean skincare brands specify certificate-of-origin documentation and pesticide residue testing in multi-year supply agreements.
- Food & Beverage:Flavoring substances regulated by FSSAI in India and FDA GRAS listings in the United States.
- Cleaning Products:Natural antimicrobial agents replacing synthetic biocides in household and industrial formulations.
Cosmetics generates the largest volume commitment, though pharmaceuticals yields the steepest margin expansion.
Industry Vertical:
End-user sophistication determines specification stringency and supplier qualification depth.
- Healthcare:Hospital and clinical settings deploying distillates for antiseptic and respiratory therapy applications.
- Personal Care:Clean-label brands seeking water-soluble actives and transparent supply chains.
- Food Industry:Flavor houses and beverage manufacturers requiring batch-to-batch consistency for compounded formulations.
- Chemical Manufacturing:Industrial terpene buyers sourcing solvent and precursor feedstocks.
Personal care exhibits the most rapid specification evolution, while healthcare maintains the highest barrier to entry.
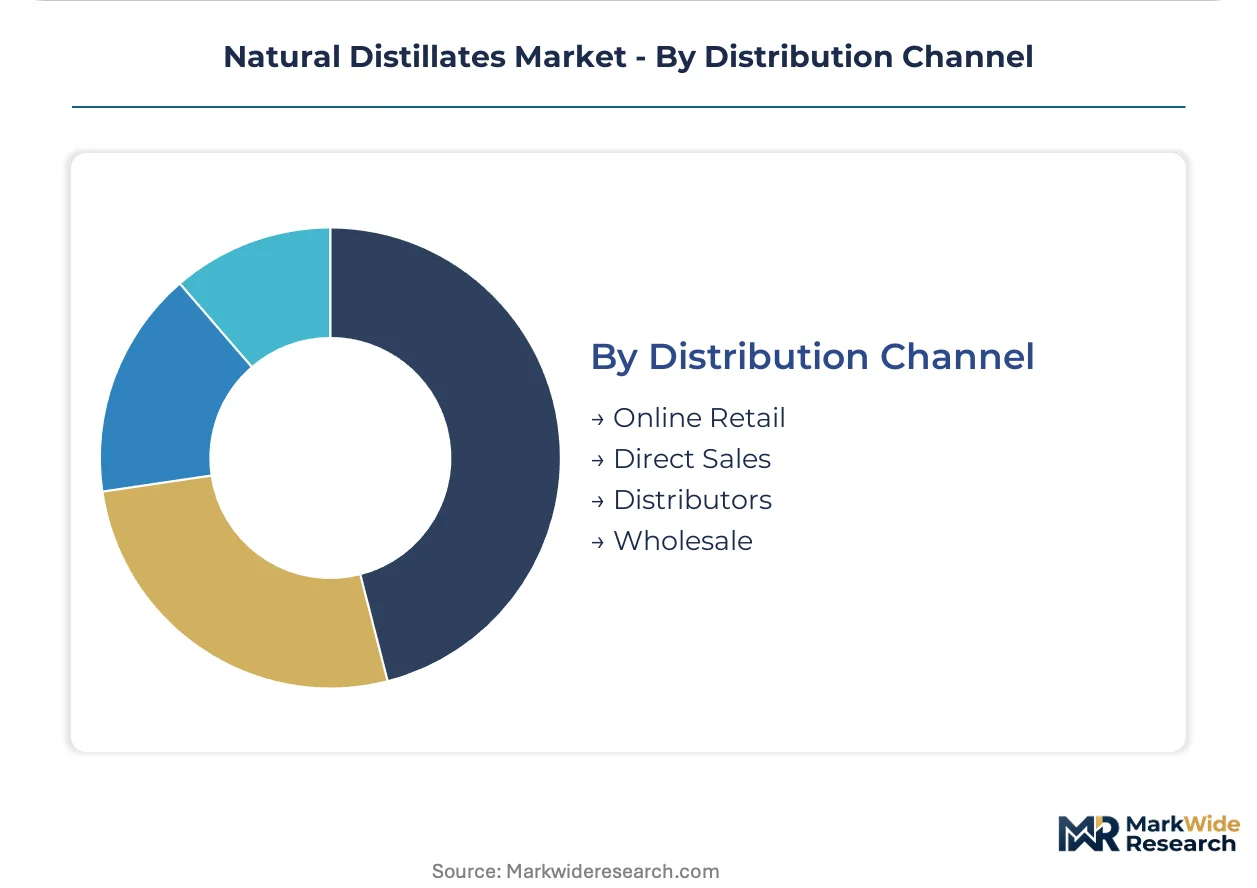
Distribution Channel:
Procurement patterns reflect traceability requirements and volume scale across customer tiers.
- Direct Sales:Long-term agreements between distillers and fragrance houses with disclosed growing coordinates and analytical documentation. Kerry Group and ADM leverage captive sourcing networks to bypass trader intermediaries for premium botanical feedstocks.
- Distributors:Regional intermediaries aggregating smaller distillery output for formulation customers lacking direct procurement capabilities. European cosmetics supply chains consolidate supplier panels around pre-registered feedstock documentation to satisfy REACH compliance.
- Online Retail:Small-volume sales to artisan formulators and independent cosmetic brands.
- Wholesale:Bulk transactions for industrial terpene and cleaning product manufacturers.
Direct sales captures the premium tier, with distributor consolidation accelerating among mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European natural distillate flows, handling concentrated botanical extracts from Mediterranean citrus belts and Southeast Asian spice origins before redistribution to fragrance compounders in Grasse and Geneva.
India
Domestic essential oil production and Ayurvedic product exports generate concentrated raw material demand from fragrance compounders. The PLI scheme subsidizes domestic distillation infrastructure for export-oriented ingredient supply. Kannauj in Uttar Pradesh and Mysore in Karnataka concentrate traditional sandalwood and jasmine distillation operations serving premium fragrance houses.
United States
Clean-label personal care brands in California and sensitive-skin formulators in the Pacific Northwest specify certificate-of-origin documentation and pesticide residue testing. FDA oversight under 21 CFR 312 drives identity testing investments for botanical drug substances. The agricultural processing corridor through California's Central Valley and Florida's citrus belt anchors domestic citrus and herb distillate production.
France
Fine perfumery houses in Grasse concentrate procurement of lavender, rose, and citrus oils for luxury fragrance compounding. REACH registration requirements mandate full toxicological dossiers for fragrance ingredients above one-tonne annual volumes. The Provence-Alpes-Côte d'Azur region maintains historical distillation infrastructure for rose and lavender essential oils serving Geneva-based fragrance laboratories.
Germany
Pharmaceutical-grade botanical extractors adopt supercritical CO2 extraction to preserve oxygenated derivatives prone to thermal degradation. ECHA's CLH process threatens reclassification of key terpenes as skin sensitizers, forcing preemptive reformulation investments. The chemical processing cluster around Ludwigshafen and Frankfurt anchors refining infrastructure for USP and EP monograph-compliant terpene isolates.
China
Flavor houses and industrial terpene buyers source solvent and precursor feedstocks from domestic spice and citrus processing regions. GB standards and SAMR oversight constrain allowable agricultural inputs for botanical extracts entering food and cosmetic channels. The Yangtze River Delta and Guangdong Province concentrate extraction infrastructure serving both domestic formulation and export markets.
Natural Distillates Market Competitive Landscape
On the supply side, the industry is consolidating around integrated extraction and refining infrastructure that spans cultivation to concentrated output. Mid-scale distillers face compliance cost barriers that favor toll manufacturing arrangements with registered importers. Three archetypes dominate: captive sourcing networks securing batch-to-batch consistency, technical specification specialists competing on breadth rather than volume, and integrated agricultural processors controlling upstream feedstock quality. Competitive moves concentrate on direct procurement partnerships bypassing trader intermediaries, and hydrosol extraction capacity expansion targeting water-soluble actives demand.
Within the integrated processing tier, Kerry Group and ADM exemplify archetypes leveraging captive sourcing networks across multiple growing regions to secure consistent feedstock quality. Treatt occupies a position among technical specification specialists, competing on citrus and herb distillate breadth rather than scale. Rudolf Wild GmbH & Co. KG anchors the German specialist segment. These named entities represent positioning patterns rather than exhaustive market coverage, with the competitive field extending to additional distillers, flavor houses, and botanical extractors operating across regulated cosmetics, pharmaceutical, and food-grade supply chains.
| Leading Market Players |
|---|
| Kerry Group |
| Shank's Extracts |
| ADM |
| Treatt |
| Flavorjen |
| Kanegrade |
| Kerr Concentrates |
| Rudolf Wild GmbH & Co. KG |
| MUL Group |
| Others |
Supply & Pricing Matrix
Kannauj's sandalwood and jasmine distillation cluster in Uttar Pradesh anchors premium essential oil pricing power through controlled batch release and documented provenance chains. Fragrance houses in Grasse and Geneva pay substantial premiums for certificate-of-origin documentation that trace volatile aromatic compounds to specific growing coordinates.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade USP monograph distillates from technical fragrance grades and bulk industrial terpenes. Price differentiation rests on REACH registration status and organic certification tier, with EU Green Deal compliance commanding substantial premiums. Cost compression in technical grades is intensifying because biotechnology-derived terpenes displace natural extracts in cost-sensitive flavor applications. Industrial terpene buyers exhibit highest price sensitivity, while fine perfumery houses absorb premiums for documented provenance.
Supply Chain Analysis
Export-control regimes under India's DGFT and China's SAMR constrain unrestricted flow of sandalwood oil and certain spice distillates classified as restricted botanical materials. Geographic supply concentrates in India, Indonesia, and Madagascar for spice and floral origins, with Mediterranean citrus belts anchoring terpene feedstocks. Raw material dependencies draw from climate-vulnerable agricultural zones, with jasmine and rose harvests tethered to monsoon patterns. Single-source vulnerability runs through Kannauj's traditional sandalwood distillers and Grasse's rose extraction infrastructure. Distribution runs through Rotterdam's liquid bulk terminals for European fragrance compounders and direct procurement agreements for pharmaceutical-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in analytical certification and regulatory dossier preparation expand faster than commodity distillate sales, as REACH compliance and organic verification become recurring revenue layers.
For Market Incumbents: Insulate margin pools by deepening captive sourcing networks across multiple growing regions to secure batch-to-batch consistency against climate-induced yield volatility. Invest in supercritical CO2 extraction capacity to preserve oxygenated derivatives for pharmaceutical-grade applications. ECHA's CLH reclassification threat demands preemptive reformulation partnerships with fragrance houses.
For New Entrants and Emerging Players: Hydrosol extraction capacity for sensitive-skin personal care formulators in California and Scandinavia represents the most penetrable entry point, bypassing entrenched essential oil supply relationships. India's PLI-subsidized distillation infrastructure offers white-space access for export-oriented Ayurvedic ingredient supply. A go-to-market angle anchored on certificate-of-origin transparency and disclosed growing coordinates differentiates against opaque trader intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because REACH dossier capabilities and organic certification infrastructure create durable moats that biotechnology substitutes cannot easily replicate. Acquisition targets should screen for analytical chemistry talent density and pre-registered feedstock documentation. The signal to watch is ECHA's CLH process timeline for terpene reclassification, which would force accelerated reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sourcing Network Expansion | Kerry Group and ADM secure consistent feedstock quality across Mediterranean citrus and Southeast Asian spice belts. |
| Supercritical CO2 Capacity Buildout | Pharmaceutical-grade extractors in Germany preserve heat-sensitive oxygenated derivatives for USP monograph compliance. |
| Hydrosol Extraction Scale-Up | Water-soluble actives target clean-label personal care formulators seeking antimicrobial properties without oil-phase incompatibility. |
| REACH Dossier Investment | Registration capabilities above one-tonne annual volumes open European cosmetics supply chains to premium pricing tiers. |
| Digital Traceability Platform Deployment | Certificate-of-origin documentation and pesticide residue testing compress qualification cycles for North American channels. |
Research Methodology
Desk research of customs trade data, FAO agricultural statistics, and ECHA registration databases preceded structured interviews with distillery operations managers, fragrance house procurement directors, regulatory affairs specialists at botanical extractors, and personal care brand formulators. Primary fieldwork across Kannauj, Grasse, and California's Central Valley validated secondary estimates of distillation capacity and yield variability. Bottom-up aggregation of distillery output and top-down triangulation against fragrance compounding demand calibrated market sizing.
Assumptions held fixed include REACH registration thresholds and USDA organic certification timelines, while agricultural yield variability and biotechnology substitution rates were modeled as stochastic inputs across the analysis window. Segmentation dimensions spanned product type, application, purity grade, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical essential oil and hydrosol adoption patterns, with pharmaceutical-grade standardization and PLI scheme incentives as industry-specific demand accelerators.
Practitioners should monitor ECHA CLH reclassification proposals, monsoon disruption patterns in Indian growing regions, and biotechnology terpene cost curves for early signals of forecast revision. Material shifts in regulatory classification thresholds or synthetic biology production economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Furfural Solvent Market
Solvents
Chloroacetonitrile Market
Solvents
Benzylamine Market
Solvents
Green Solvents Market
Solvents
Global Solvent Evaporation Market
Solvents
Aprotic Solvents Market
Solvents
Diethanolamine (DEA) Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Global Acetonitrile Market
Solvents
Mixed Xylene Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
1, 1-Difluoroethane Market
Solvents
Glycerol Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Diethylene Glycol Monobutyl Ether Market