
 Dimethyl Ether (DME) Market | 2026-2036
Dimethyl Ether (DME) Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Ether (DME) Market Analysis
A capital-intensity divergence between methanol-to-DME specialists and integrated gas-to-liquids operators is unwinding competitive stability across the industry. Oberon Fuels leverages small-scale modular production to anchor niche transportation fuel markets in North America. China Energy Investment Corporation sustains massive syngas-based output that dominates Asian chemical intermediates supply. Royal Dutch Shell Plc navigates downstream integration pressures by controlling liquefied petroleum gas blending infrastructure across multiple continents.
Dimethyl ether is a colorless, non-toxic organic compound with the formula CH3OCH3, produced through catalytic dehydration of methanol or direct synthesis from syngas, and functions primarily as a clean-burning aerosol propellant, diesel alternative, and chemical feedstock. Fuel-grade output leads volume given LPG substitution mandates in residential and automotive applications, while chemical intermediates command margin concentration due to pharmaceutical and specialty polymer demand. Bio-DME technology attracts capital fastest as renewable feedstock pathways mature, though conventional synthesis retains scale advantages in coal-rich geographies.
The EPA regulates DME as an alternative fuel under the Clean Air Act, while China's MEE enforces emissions standards that favor DME-diesel blends in heavy transport; the EU F-Gas Regulation simultaneously restricts fluorinated refrigerants and expands addressable market for DME-based cooling systems. Stakeholders must monitor feedstock cost spreads between natural gas, biomass, and coal-to-chemical routes to calibrate capacity commitments.
Market Dynamics
The capital-intensity divergence between methanol-to-DME specialists and integrated gas-to-liquids operators is unwinding competitive stability across the industry. Feedstock cost spreads between natural gas, biomass, and coal-to-chemical routes now dictate capacity commitment decisions more than technology maturity.
Growth Catalysts
- LPG Blending Mandates:China's residential heating sector drives fuel-grade DME consumption through national energy security directives. Municipal gas distribution networks in Shandong and Jiangsu provinces prioritize DME-LPG mixtures for household cooking.
- F-Gas Regulation:The EU F-Gas Regulation restricts fluorinated refrigerants and expands addressable market for DME-based cooling systems. Commercial refrigeration OEMs in Germany and France accelerate R-134a substitution programs.
- Bio-DME Pathway Maturation:Renewable feedstock technologies attract capital fastest as lignocellulosic gasification achieves commercial scale. Pilot plants in Scandinavia demonstrate forestry waste-to-DME economics.
Market Restraints
- Coal Price Volatility:Syngas production costs swing with thermal coal benchmarks in Shanxi and Inner Mongolia. Integrated coal-to-chemical operators face margin compression when import parity rises.
- Distribution Infrastructure Gaps:Cryogenic storage and pressurized transport networks remain concentrated near Rotterdam, Houston, and Singapore. Inland consumers in Brazil and India absorb logistics premiums.
- Diesel Engine Retrofit Complexity:Compression ignition systems require fuel injection modifications for DME compatibility. Fleet operators defer conversion capex pending OEM warranty clarity.
Strategic Opportunities
- Marine Fuel Bunkering:Singapore and Rotterdam port authorities evaluate DME as IMO 2020 sulfur compliance pathway. Dual-fuel vessel orders from Korean shipyards include methanol-DME flexibility.
- Aerosol Propellant Premiumization:Personal care brands reformulate hydrocarbon-free spray products. DME solvency properties enable water-based active ingredient delivery.
- Carbon Border Adjustment Alignment:EU CBAM implementation rewards low-carbon DME imports from biomass-rich geographies. Nordic producers leverage certified renewable certificates for tariff advantage.
Industry Challenges
- Catalyst Deactivation Management:Methanol dehydration catalysts suffer rapid coking in high-throughput reactors. Operations teams struggle to predict regeneration cycles.
- ASME Pressure Vessel Certification:Transport and storage equipment requires jurisdiction-specific approvals. Chinese fabricators face extended timeline for European PED compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Ether (DME) Market |
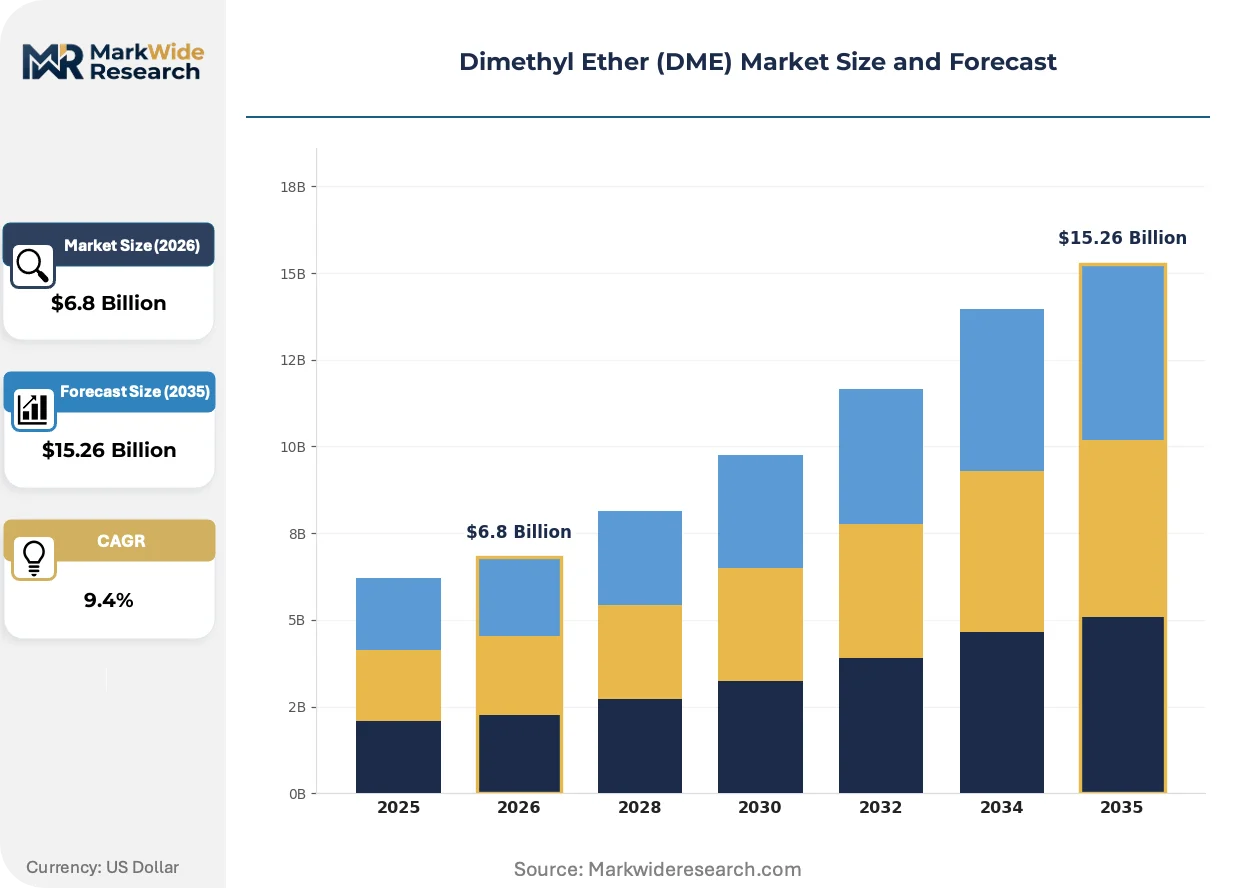
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel, Propellant, Chemical Intermediates, Refrigerant Application: Aerospace, Automotive, Industrial, Residential End User: Manufacturers, Oil & Gas Companies, Energy Providers, Retailers Technology: Catalytic Conversion, Gas-to-Liquid, Bio-DME, Conventional Synthesis |
| Companies Covered | The Chemours Company, Korea Gas Corporation, Royal Dutch Shell Plc, Air Liquide S.A., Oberon Fuels, Akzo Nobel N.V., Grillo-Werke AG, China Energy Investment Corporation, Mitsubishi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Ether (DME) Market Emerging Trajectories
Process intensification and modular plant architectures are compressing minimum efficient scale thresholds. Technology licensors now compete on deployment velocity rather than unit production cost alone.
Small-scale skid-mounted DME production is fragmenting the traditional mega-plant paradigm. Remote gas field operators in West Africa and Central Asia deploy containerized units to monetize stranded methane. This distributed model bypasses pipeline economics and enables supply to isolated mining and power generation sites.
The EU F-Gas Regulation's phasedown schedule accelerates refrigerant formulation R&D. Chemical engineers optimize DME-pentane blends for commercial cold chain applications. German supermarket chains pilot retrofit programs in Bavaria and North Rhine-Westphalia ahead of 2027 quota reductions.
Buyer procurement for chemical-grade DME is consolidating around long-term offtake contracts with fixed-price escalators. Specialty polymer manufacturers in Japan and South Korea bypass spot markets to secure pharmaceutical-intermediate purity. This contractual shift squeezes trading house margins and transfers inventory risk upstream to producers.
Dimethyl Ether (DME) Market Segmentation
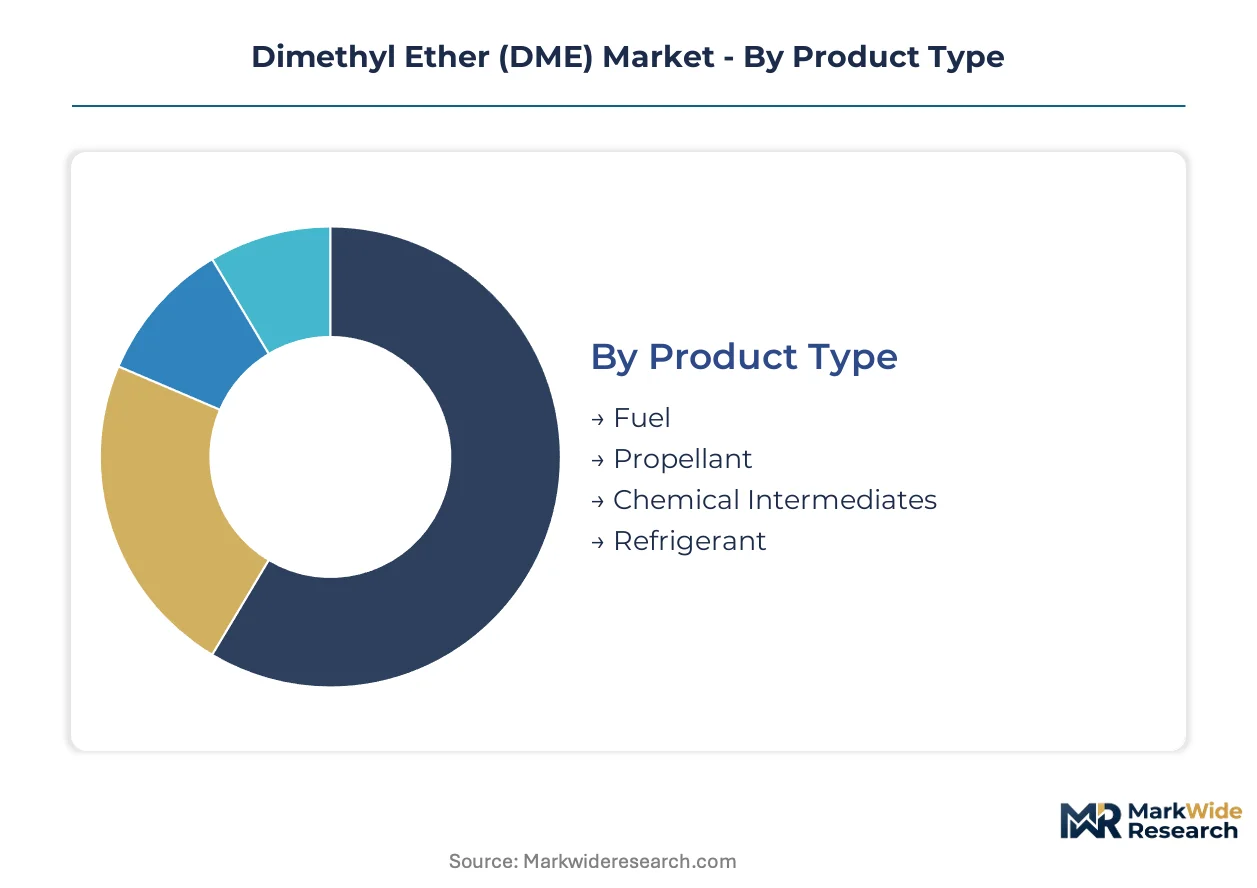
Dimethyl ether's functional versatility creates distinct commercial pathways where fuel-grade specifications, propellant purity standards, and chemical-intermediate grades each answer to separate regulatory regimes and customer procurement protocols. Segmentation clarity determines which production assets can pivot across applications and which remain locked to single-use contracts.
Product Type:
EPA fuel certification requirements, EU F-Gas refrigerant quotas, and China's GB standards for residential gas create divergent compliance burdens that reshape margin structures across each grade.
- Fuel:Fuel-grade DME meets compression-ignition specifications for diesel substitution and LPG blending, with demand concentrating in China's Shandong and Jiangsu provinces where municipal gas networks enforce national energy security mandates for household cooking. The MEE's emissions standards for heavy transport reinforce fleet adoption, though diesel engine retrofit complexity delays conversion timelines.
- Chemical Intermediates:Pharmaceutical-grade purity specifications command premium pricing from specialty polymer manufacturers in Japan and South Korea, who bypass spot markets through long-term offtake contracts with fixed-price escalators. This contractual shift transfers inventory risk upstream to producers.
- Propellant:Aerosol-grade DME serves personal care reformulation trends as brands eliminate hydrocarbon propellants; solvency properties enable water-based active ingredient delivery.
- Refrigerant:DME-based cooling systems expand as the EU F-Gas Regulation restricts fluorinated refrigerants, with German supermarket chains piloting retrofit programs ahead of quota reductions.
Established volume favors Fuel; emerging adoption favors Refrigerant.
Application:
Cost tier differentiation separates mass-market residential heating from aerospace qualification protocols that demand batch traceability and ASME pressure vessel certification.
- Residential:China's municipal gas distribution networks prioritize DME-LPG mixtures for household cooking, anchoring baseline demand through national energy security directives. Thermal coal price volatility in Shanxi and Inner Mongolia directly impacts syngas production economics for this segment.
- Automotive:Heavy transport fleets evaluate DME-diesel blends under MEE emissions standards, though OEM warranty clarity gaps defer fleet conversion capex decisions.
- Industrial:Mining and power generation sites in West Africa and Central Asia deploy containerized skid-mounted production to monetize stranded methane, bypassing pipeline economics.
- Aerospace:Qualification protocols for propellant-grade DME require batch traceability and extended ASME certification timelines for pressure vessel compliance.
Residential commands current volume share; automotive holds the steepest expansion trajectory pending engine compatibility resolution.
End User:
Customer type determines contract structure, with integrated energy providers favoring captive supply arrangements while retailers absorb logistics premiums from concentrated storage hubs.
- Manufacturers:Specialty polymer and pharmaceutical intermediate producers in East Asia secure pharmaceutical-grade purity through consolidated procurement around long-term offtake contracts, squeezing trading house margins.
- Oil & Gas Companies:Integrated operators control liquefied petroleum gas blending infrastructure across multiple continents, navigating downstream integration pressures through infrastructure ownership.
- Energy Providers:Municipal gas utilities in China enforce national blending mandates for residential heating security.
- Retailers:Inland consumers in Brazil and India absorb cryogenic storage and pressurized transport logistics premiums due to infrastructure concentration near Rotterdam, Houston, and Singapore.
Integrated oil and gas operators dominate infrastructure control; retailers face persistent logistics cost disadvantages.
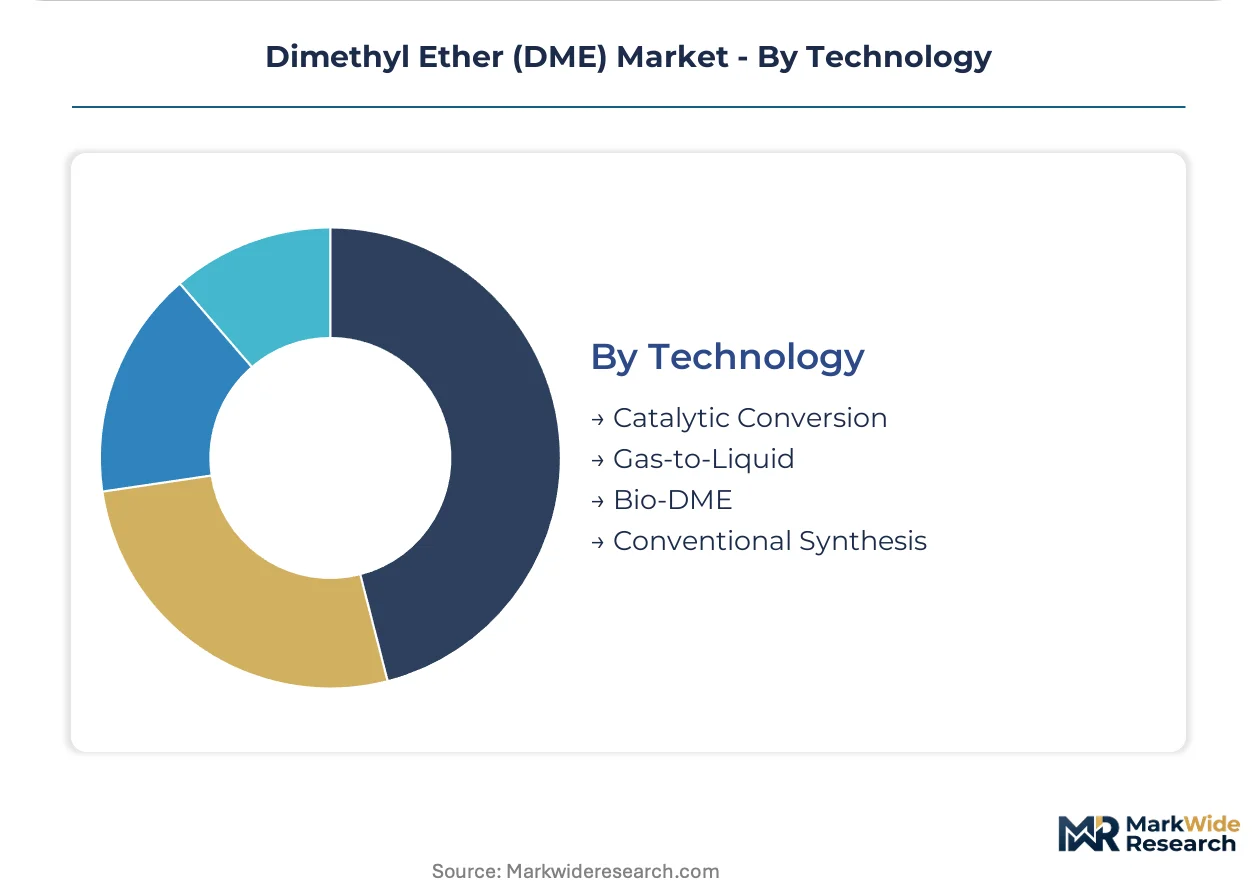
Technology:
Maturity curves separate commercial-scale conventional synthesis from pilot-phase bio-DME pathways, with capital intensity diverging between methanol-to-DME specialists and integrated gas-to-liquids operators.
- Conventional Synthesis:Coal-to-chemical routes retain scale advantages in coal-rich geographies, particularly China Energy Investment Corporation's massive syngas-based output that dominates Asian chemical intermediates supply. Catalyst deactivation from rapid coking in high-throughput reactors constrains operational predictability.
- Bio-DME:Lignocellulosic gasification achieves commercial scale in Scandinavian pilot plants demonstrating forestry waste-to-DME economics, attracting capital fastest as renewable feedstock pathways mature and EU CBAM implementation rewards low-carbon imports.
- Catalytic Conversion:Methanol dehydration via solid acid catalysts remains the dominant production pathway for fuel and propellant grades.
- Gas-to-Liquid:Remote gas field operators deploy modular architectures to compress minimum efficient scale thresholds, competing on deployment velocity rather than unit production cost alone.
Conventional synthesis anchors current capacity; bio-DME gains share fastest on carbon border adjustment alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes DME predominantly as an LPG blending component for residential heating, while European buyers prioritize refrigerant-grade specifications under F-Gas phasedown mandates. This consumption-mix differential fragments regional procurement protocols and pricing benchmarks.
China
Shandong and Jiangsu provinces anchor fuel-grade consumption through municipal gas distribution networks enforcing national energy security directives for household cooking. The MEE's emissions standards for heavy transport reinforce fleet adoption of DME-diesel blends. China Energy Investment Corporation sustains massive syngas-based output that dominates Asian chemical intermediates supply from coal-rich Shanxi and Inner Mongolia.
Germany
Commercial refrigeration OEMs in Bavaria and North Rhine-Westphalia accelerate R-134a substitution programs ahead of 2027 F-Gas quota reductions. The EU F-Gas Regulation restricts fluorinated refrigerants and expands addressable market for DME-based cooling systems. Grillo-Werke AG exemplifies the specialty chemical fabricator archetype within this regulatory corridor.
United States
The EPA regulates DME as an alternative fuel under the Clean Air Act, anchoring transportation fuel trials in California and Texas. Oberon Fuels leverages small-scale modular production to serve niche transportation fuel markets. Cryogenic storage infrastructure concentrates near Houston, creating logistics premiums for inland consumers.
Japan
Specialty polymer manufacturers in Osaka and Nagoya secure pharmaceutical-intermediate purity through long-term offtake contracts with fixed-price escalators. METI industrial policy supports bio-DME pathway maturation. Mitsubishi Corporation occupies a position bridging chemical trading and integrated energy infrastructure.
South Korea
Korea Gas Corporation anchors national DME distribution through liquefied petroleum gas blending infrastructure. Daegu-Gyeongbuk chemical manufacturing corridors demand fuel-grade specifications for industrial heating applications. Dual-fuel vessel orders from Korean shipyards include methanol-DME flexibility for IMO 2020 sulfur compliance.
Dimethyl Ether (DME) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the DME market. Royal Dutch Shell Plc and China Energy Investment Corporation control downstream infrastructure across multiple continents, while methanol-to-DME specialists compete on deployment velocity. Three archetypes dominate: integrated gas-to-liquids operators, small-scale modular producers, and chemical-grade purity specialists. Competitive moves center on capacity expansion in coal-rich geographies and strategic partnerships for bio-DME technology licensing.
Within the integrated operator tier, Royal Dutch Shell Plc and China Energy Investment Corporation exemplify scale-driven positioning through liquefied petroleum gas blending infrastructure ownership. Oberon Fuels represents the modular production archetype, occupying a position in North American niche transportation fuel markets. Korea Gas Corporation anchors national distribution networks in East Asia. Akzo Nobel N.V. and Grillo-Werke AG sit within the European specialty chemical fabricator segment, reflecting regional regulatory alignment with F-Gas phasedown requirements. The Chemours Company and Air Liquide S.A. exemplify diversified industrial gas and chemical operators with potential DME adjacencies.
| Leading Market Players |
|---|
| The Chemours Company |
| Korea Gas Corporation |
| Royal Dutch Shell Plc |
| Air Liquide S.A. |
| Oberon Fuels |
| Akzo Nobel N.V. |
| Grillo-Werke AG |
| China Energy Investment Corporation |
| Mitsubishi Corporation |
| Others |
Supply Flow & Price Mechanics
Coal-to-methanol feedstock substitution in Shanxi and Inner Mongolia simultaneously redraws production geography and compresses syngas-based DME economics, forcing buyers to absorb volatility premiums or pivot toward bio-DME contracts with Nordic forestry waste suppliers.
Pricing Analysis
Contract-based long-term offtake agreements with fixed-price escalators dominate procurement for pharmaceutical-grade purity, insulating specialty polymer manufacturers in Japan and South Korea from spot market swings. Price differentiation rests on certification tier and volume scale, with chemical-intermediate grades commanding substantial premiums over fuel specifications. Cost compression in coal-syngas routes is intensifying because thermal coal benchmarks swing with import parity, eroding margins for integrated operators. Municipal gas utilities in China demonstrate lowest price sensitivity due to national energy security mandates, while inland retailers in Brazil and India face acute logistics-driven cost pressure.
Supply Chain Analysis
Rotterdam port cryogenic storage capacity acts as a chokepoint for European refrigerant-grade distribution, constraining German supermarket retrofit timelines ahead of F-Gas quota reductions. Manufacturing concentrates in China, the United States, and South Korea, with syngas-based output anchored in Shanxi province and modular production scaling in California and Texas. Feedstock draws from thermal coal, natural gas, and lignocellulosic biomass streams. Single-source vulnerability runs through catalyst supply chains dominated by German and Japanese specialty chemical fabricators. Distribution runs through liquefied petroleum gas blending infrastructure controlled by integrated energy providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales catalyst regeneration services and long-term purity certification programs expand faster than base chemical production, creating attach-rate opportunities for operators who bundle technical support with molecule supply.
For Market Incumbents: Secure backward integration into syngas production or methanol supply to defend margin position against coal price volatility in Shanxi and Inner Mongolia. Anchor capacity expansion in jurisdictions with EU CBAM alignment to capture tariff advantages on low-carbon DME exports. Deepen vertical control over liquefied petroleum gas blending infrastructure to lock out modular competitors. For New Entrants and Emerging Players: Remote gas field catalyst management and stranded methane monetization services represent the most penetrable white-space target, as integrated operators under-serve West African and Central Asian mining sites with containerized deployment expertise. Target marine fuel bunkering qualification support in Singapore and Rotterdam, where port authorities seek IMO sulfur compliance pathways without legacy infrastructure entanglement. Lead with deployment velocity rather than unit cost to outrun minimum efficient scale thresholds. For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown milestones reshape the acquisition landscape toward refrigerant-grade purity specialists with German supermarket chain relationships. Position for five-to-ten year viability around bio-DME pathway maturation and carbon border adjustment mechanics. Monitor lignocellulosic gasification pilot economics in Scandinavia as the inflection signal for renewable feedstock competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Syngas Production | China Energy Investment Corporation's captive coal supply insulates margin from import parity swings. |
| Bio-DME Technology Licensing | Nordic forestry waste gasification pilots attract EU CBAM-aligned capital fastest. |
| Long-term Supply Agreement | Japanese specialty polymer manufacturers bypass spot markets through fixed-escalator contracts. |
| Marine Fuel Bunkering Qualification | Singapore port authority evaluation of DME for IMO sulfur compliance opens vessel retrofit demand. |
| Refrigerant Grade Capacity Expansion | German supermarket chains pilot retrofit programs ahead of F-Gas quota reductions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across plant managers at coal-to-chemical facilities, procurement leads at LPG distribution utilities, technical R&D directors at catalyst fabricators, and aftermarket service heads at modular equipment providers. Secondary validation drew from customs and trade data, China MEE emissions filings, EU F-Gas Regulation quota tracking, and SEC disclosures from integrated energy operators. Bottom-up capacity tallies and top-down demand modeling were triangulated to anchor volume estimates.
Across the analysis window, projections segment by product grade, end-use application, technology pathway, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity commissioning timelines. Forecast inputs incorporated syngas production cost spreads, catalyst regeneration cycle predictability, and marine fuel specification adoption curves.
Forecasts assume regulatory continuity in EU F-Gas phasedown schedules and China MEE emissions standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as bio-DME pathway economics and carbon border adjustment implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ketene Market
Solvents
Allyl Cyanide Market
Solvents
Trifluoroethanol Market
Solvents
Triacetin Market
Solvents
Europe Acetonitrile Market
Solvents
Nitrobenzene Market
Solvents
Ionic Liquids Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
2-Butanone Market
Solvents
Fluid Neutralizing Market
Solvents
Piperylene Market
Solvents
Mineral Turpentine Market
Solvents
Global Solvents Market
Solvents
Meta-Xylene Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Global Furfural Solvent Market