
 Vapor Degreasing Solvents Market | 2026-2036
Vapor Degreasing Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Degreasing Solvents Market Outlook
ISO 10993 biocompatibility certification for medical device cleaning processes is redrawing competitive boundaries in precision solvent supply. Honeywell International Inc. leverages its fluorinated materials portfolio to sustain dominance in aerospace-qualified formulations. Solvay SA anchors its position through backward integration into specialty alcohol feedstocks for electronics-grade solvents. MicroCare Corporation differentiates via regional distribution density across North American industrial clusters.
Vapor degreasing solvents are formulated cleaning media designed for condensation-based contaminant removal, typically operating at controlled boiling points between 40°C and 180°C to dissolve oils, fluxes, and particulate residues from metal and electronic components. The process relies on saturated vapor zones where parts suspend above boiling solvent, allowing condensed liquid to flush surfaces with near-zero moisture exposure. Chlorinated solvents retain volume leadership in heavy industrial applications despite regulatory headwinds, while hydrocarbon solvents capture the fastest expansion as manufacturers substitute perchloroethylene in automotive and electronics cleaning. Alcohol-based formulations concentrate margin pools in semiconductor and medical device segments where residue specifications tighten.
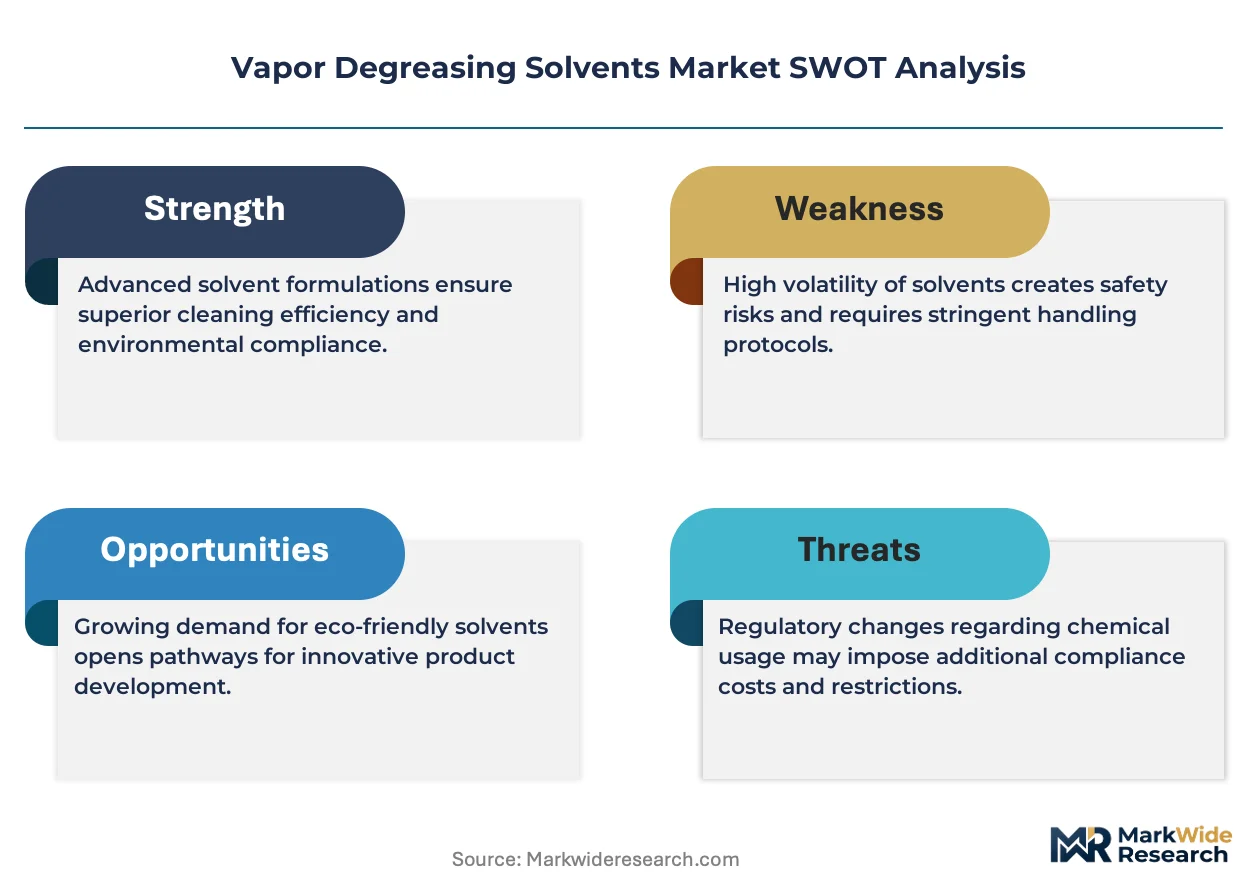
EPA Significant New Alternatives Policy (SNAP) rules and EU F-Gas Regulation constrain hydrofluorocarbon and chlorinated solvent availability, forcing reformulation investments across the supply base. OSHA permissible exposure limits for methylene chloride and trichloroethylene directly shape workplace engineering controls and solvent selection in metal fabrication facilities. REACH substance authorization requirements in the European Union add compliance cost layers that favor suppliers with established registration dossiers. Stakeholders must track state-level solvent bans in California and New York alongside evolving EPA risk evaluations, as regulatory fragmentation increasingly determines product viability and geographic market access.
Market Dynamics
REACH substance authorization deadlines and EPA SNAP phase-down rules are forcing simultaneous solvent reformulation across three continents, compressing product lifecycles while opening margin pools for compliant suppliers.
Growth Catalysts
- EU F-Gas Regulation phase-down:Aerospace manufacturers in Germany and France are accelerating procurement of hydrofluorocarbon alternatives ahead of compliance deadlines, expanding addressable volume for fluorinated solvent suppliers.
- Semiconductor node advancement:Sub-7nm chip fabrication requires residue specifications below 0.1 micrograms per square centimeter, pulling alcohol-based formulations into front-end cleaning stages.
- Medical device sterilization:ISO 10993 biocompatibility certification is becoming a procurement gate for precision cleaning solvents in implantable device manufacturing.
Market Restraints
- Feedstock concentration:Specialty alcohol precursors for electronics-grade solvents concentrate among three integrated chemical producers in Germany and Belgium.
- Substitution economics:Aqueous cleaning systems with vacuum drying modules are capturing mid-precision automotive applications above 50 microns residue tolerance.
- Exposure limit compression:OSHA permissible exposure limits for methylene chloride below 25 ppm are forcing engineering control investments that extend payback periods for metal fabricators.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor and component assembly are creating first-mover advantage for solvent suppliers establishing local blending facilities.
- Closed-loop vapor recovery:Distillation and reclamation service contracts are shifting revenue from product sales to performance-based cleaning-as-a-service models.
- California solvent ban cascade:State-level restrictions on perchloroethylene in dry cleaning and metal finishing are preempting federal action and accelerating hydrocarbon adoption.
Industry Challenges
- Formulation chemist scarcity:Expertise in azeotropic blending for low-global-warming-potential solvents concentrates among retiring specialists at legacy chlorinated solvent producers.
- Dual-registration burden:REACH dossier maintenance alongside EPA TSCA Section 5 notifications stretches compliance timelines to 18-24 months for new molecular entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Degreasing Solvents Market |
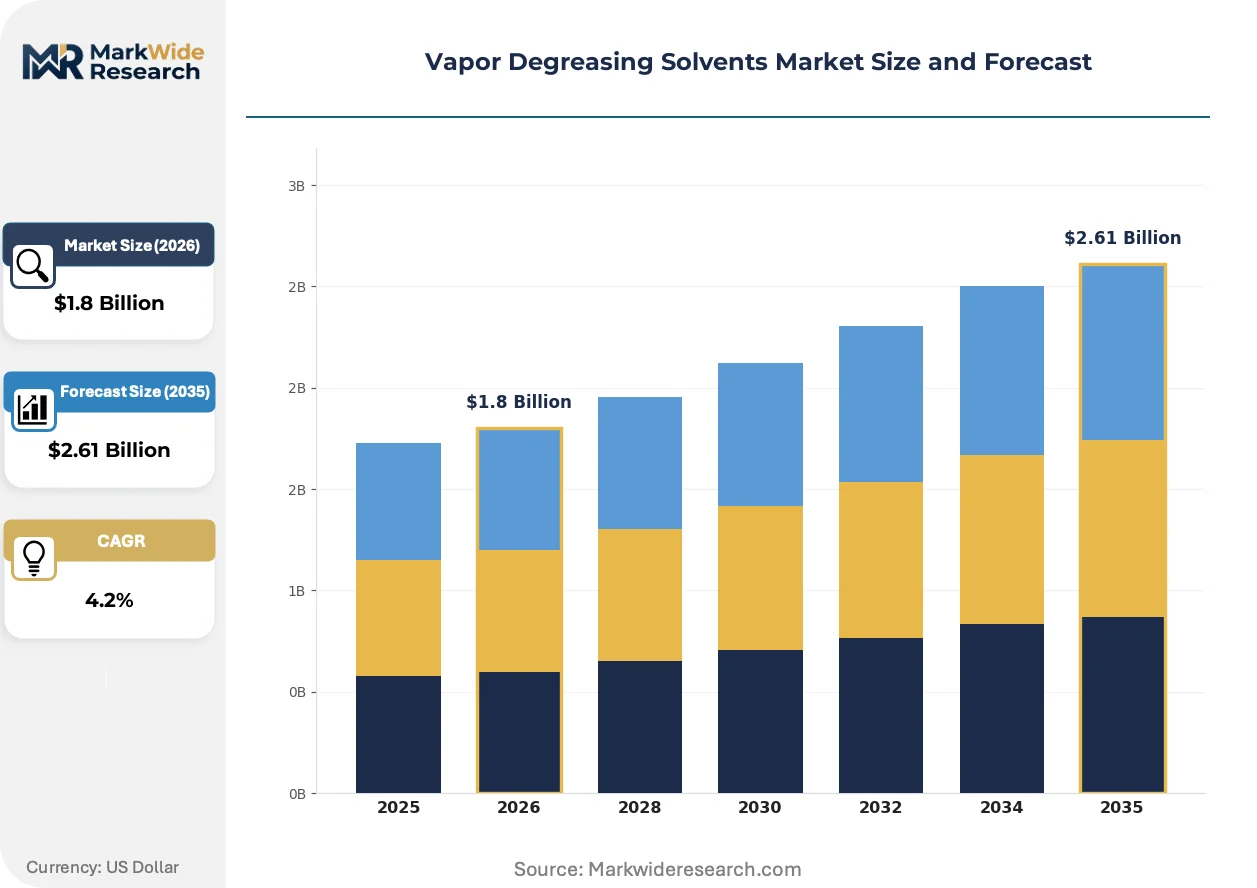
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorinated Solvents, Hydrocarbon Solvents, Alcohol-Based Solvents, Aqueous Solvents End User: Aerospace, Electronics, Automotive Manufacturing, Industrial Cleaning Application: Component Cleaning, Surface Preparation, Residue Removal, Parts Degreasing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Honeywell International Inc., 3M Company, Chemours Company, Solvay SA, MicroCare Corporation, Reliance Specialty Products Inc., Florachem Precision Cleaning Products, Tech Spray LP, Asahi Glass Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Degreasing Solvents Market Strategic Shifts
Refrigerant-grade fluorinated materials are crossing into precision cleaning applications, while regulatory phase-downs compress the window for legacy chemistry commercialization.
Trans-1,2-dichloroethylene formulations are miniaturizing vapor degreasing equipment footprints through lower boiling points and reduced energy demand. Medical device contract manufacturers in Minnesota and Massachusetts are adopting compact benchtop units for cleanroom integration. Equipment miniaturization is enabling distributed cleaning nodes that reduce work-in-process inventory and contamination risk in just-in-time manufacturing.
EPA SNAP Rule 23 is banning hydrofluorocarbon solvents with global warming potential above 150 in aerosol and precision cleaning applications. Metal fabricators and electronics assemblers must reformulate or retrofit recovery systems before the prohibition takes effect. Aerospace-qualified suppliers with existing low-GWP portfolios are capturing specification locks while competitors navigate the 12-18 month validation cycle.
Certificate-of-analysis requirements are migrating from spot-check sampling to continuous digital chain-of-custody documentation. Automotive tier-one suppliers in Stuttgart and Detroit are rejecting solvent lots without batch-level residue and moisture data. Electronics-grade distributors with in-house analytical laboratories are consolidating procurement relationships as buyers eliminate secondary testing costs.
Vapor Degreasing Solvents Market Segmentation
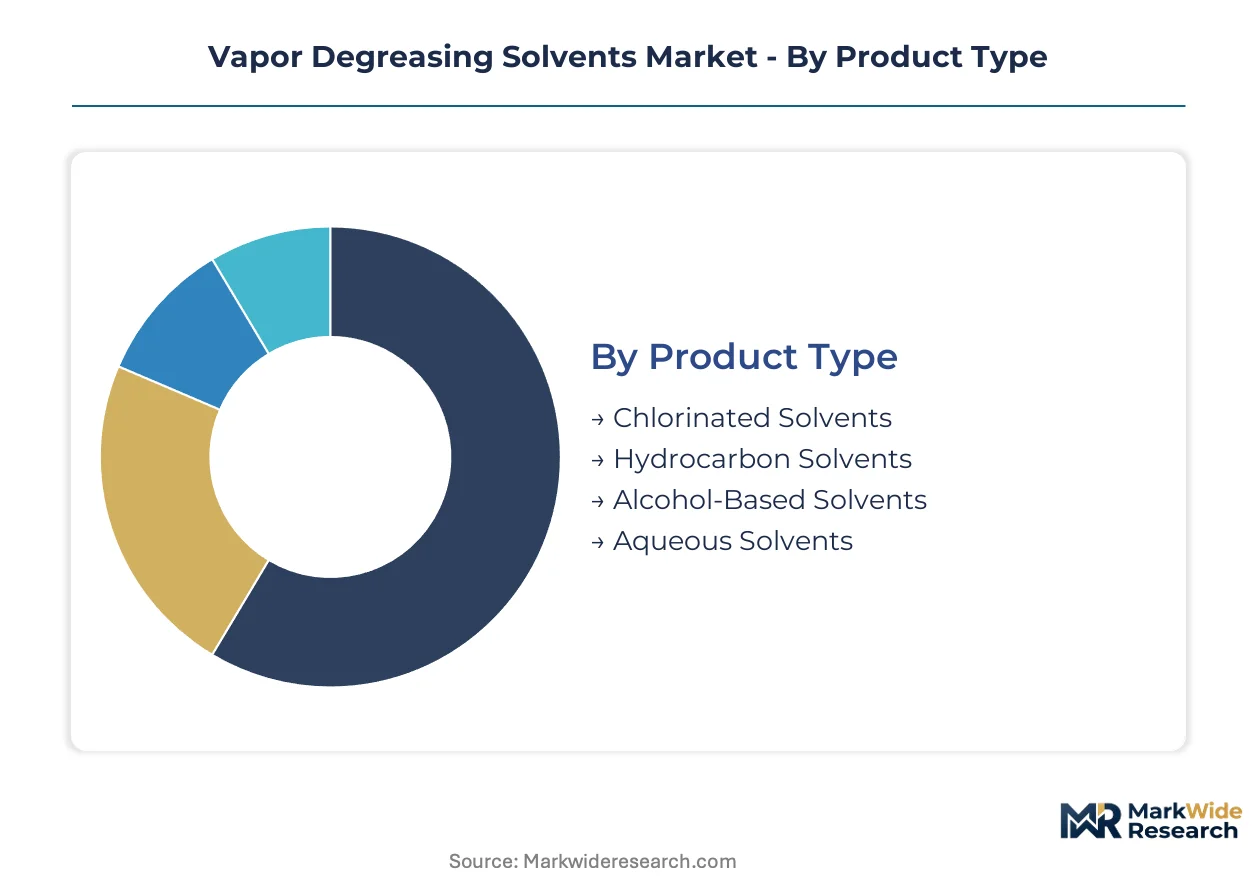
Vapor degreasing solvent suppliers face divergent substitution economics across product chemistries and end-use specifications. Segmentation reveals where regulatory pressure compresses margins versus where residue tolerances sustain premium pricing.
Product Type:
Substitution pressure concentrates in chlorinated formulations facing REACH authorization and EPA SNAP phase-downs, while hydrocarbon alternatives capture specification migration.
- Chlorinated Solvents:Perchloroethylene and trichloroethylene formulations retain dominance in heavy industrial degreasing where residue tolerance exceeds 50 microns. Aerospace maintenance facilities in Germany and France face compressed procurement windows under F-Gas Regulation deadlines.
- Hydrocarbon Solvents:Aliphatic and aromatic hydrocarbon blends are displacing chlorinated chemistries in automotive component cleaning. REACH-compliant suppliers with established registration dossiers capture specification locks while competitors navigate 18-24 month authorization timelines.
- Alcohol-Based Solvents:Isopropyl alcohol and specialty alcohol formulations serve semiconductor front-end cleaning with sub-0.1 microgram residue specifications.
- Aqueous Solvents:Water-based formulations with vacuum drying modules are capturing mid-precision applications above 50 microns tolerance.
Chlorinated Solvents anchors the volume base while Hydrocarbon Solvents gains share at the steepest rate.
End User:
Cost tier stratification separates aerospace-qualified formulations from commodity industrial cleaning, with electronics-grade solvents commanding the widest margin spreads.
- Aerospace:Honeywell International Inc. and Solvay SA dominate qualified fluorinated solvent supply for turbine component cleaning. EPA SNAP Rule 23 is forcing reformulation investments for hydrofluorocarbon-dependent maintenance operations.
- Electronics:Sub-7nm chip fabrication pulls alcohol-based formulations into front-end wafer cleaning stages. Certificate-of-analysis requirements are migrating to continuous digital chain-of-custody documentation.
- Automotive Manufacturing:Stuttgart and Detroit tier-one suppliers are rejecting solvent lots without batch-level residue data, consolidating procurement around distributors with in-house analytical laboratories.
- Industrial Cleaning:Metal fabricators face OSHA methylene chloride exposure limits below 25 ppm, extending payback periods for vapor degreasing equipment investments.
Industrial Cleaning generates the highest shipment volumes while Electronics expands most quickly on node advancement.
Application:
Application maturity curves diverge sharply, with residue removal specifications tightening fastest in medical device and semiconductor segments.
- Component Cleaning:Precision cleaning of machined metal parts and electronic assemblies requires controlled boiling points between 40°C and 180°C. Minnesota and Massachusetts medical device contract manufacturers are adopting compact benchtop vapor degreasing units for cleanroom integration.
- Surface Preparation:Pre-coating and pre-bonding surface treatment demands near-zero moisture exposure. Saturated vapor zone processes enable condensation-based contaminant removal without water contact.
- Residue Removal:Post-machining oil and particulate elimination in implantable device manufacturing requires ISO 10993 biocompatibility certification.
- Parts Degreasing:Bulk metal component cleaning in automotive and general industrial applications faces displacement by aqueous systems with vacuum drying modules.
Parts Degreasing maintains the broadest installed base while Residue Removal climbs the fastest on medical device sterilization requirements.
Distribution Channel:
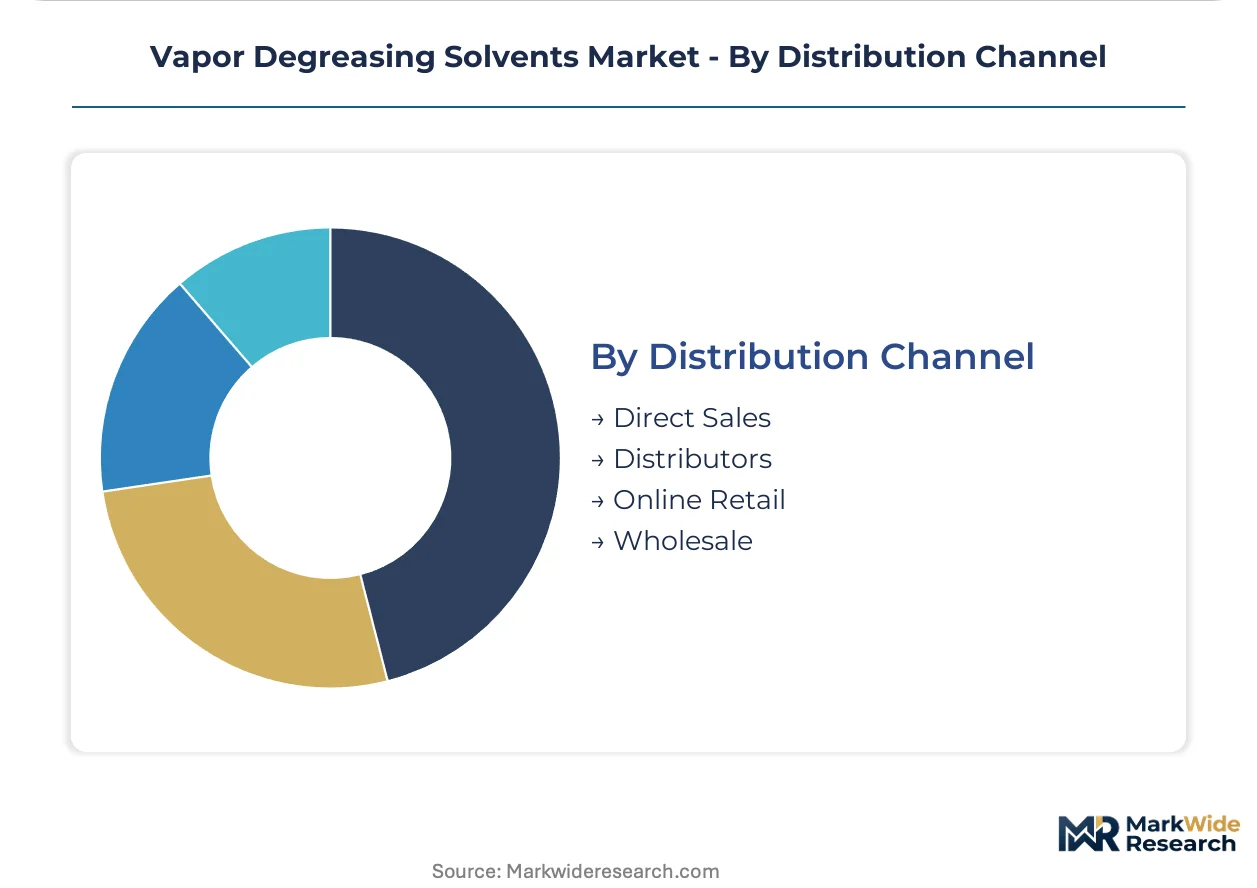
Customer type fragmentation separates specification-intensive direct relationships from price-sensitive wholesale transactions.
- Direct Sales:Aerospace and semiconductor manufacturers procure fluorinated and electronics-grade solvents through qualified supplier programs with locked specifications.
- Distributors:Regional chemical distributors with blending capabilities and analytical laboratories are consolidating automotive and industrial procurement relationships.
- Online Retail:Small-batch solvent sales for maintenance and repair operations are migrating to digital platforms with certificate-of-analysis downloads.
- Wholesale:Volume hydrocarbon solvent sales to metal fabricators and general industrial users operate on commodity pricing with minimal technical service attachment.
Direct Sales captures the highest value per liter while Distributors expands most quickly on regional density investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace maintenance hubs and semiconductor fabrication clusters concentrate solvent procurement in Germany, the United States, Japan, and South Korea, with regulatory deadlines compressing supplier selection windows.
Germany
Stuttgart automotive tier-one suppliers and Hamburg aerospace facilities are accelerating hydrocarbon solvent procurement ahead of F-Gas Regulation phase-down deadlines. ECHA REACH substance authorization requirements favor suppliers with established registration dossiers for chlorinated alternatives. Munich industrial clusters are rejecting solvent shipments lacking continuous digital chain-of-custody documentation.
United States
EPA SNAP Rule 23 is banning hydrofluorocarbon solvents with global warming potential above 150 in precision cleaning applications. Minnesota and Massachusetts medical device contract manufacturers are adopting compact benchtop vapor degreasing units for cleanroom integration. California state-level restrictions on perchloroethylene are preempting federal action and accelerating hydrocarbon adoption in metal finishing.
Japan
Osaka-based electronics assemblers are migrating procurement to alcohol-based formulations for sub-7nm chip fabrication residue specifications. METI industrial standards are tightening certificate-of-analysis requirements for imported solvent batches. Nagoya automotive component manufacturers are consolidating procurement around distributors with in-house analytical laboratories.
South Korea
Samsung and SK Hynix semiconductor fabs are pulling specialty alcohol formulations into front-end wafer cleaning stages. The country's national chemical regulator is aligning exposure limit standards with OSHA methylene chloride thresholds below 25 ppm. Busan-Ulsan industrial corridors are investing in closed-loop vapor recovery distillation systems to extend solvent lifecycle economics.
France
Toulouse aerospace maintenance facilities face compressed procurement windows under EU F-Gas Regulation compliance deadlines. ANSM pharmaceutical and medical device standards are extending ISO 10993 biocompatibility requirements to precision cleaning solvent supply chains. Lyon industrial clusters are adopting aqueous cleaning systems with vacuum drying modules for mid-precision automotive applications.
Vapor Degreasing Solvents Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with fluorinated materials portfolios and regional specialists with distribution density advantages. The vendor base separates into three tiers: aerospace-qualified suppliers with locked specifications, electronics-grade distributors with analytical capabilities, and commodity hydrocarbon blenders serving metal fabrication. Consolidation pressure is intensifying as REACH dossier maintenance costs and EPA notification timelines stretch to 18-24 months for new molecular entrants.
Within the diversified chemical tier, Honeywell International Inc. and Solvay SA occupy positions anchored by backward integration into specialty feedstocks and fluorinated material production. MicroCare Corporation exemplifies the regional distribution archetype, consolidating procurement relationships through North American industrial cluster density. These three companies represent the competitive spectrum from global specification lock to localized service attachment.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| Chemours Company |
| Solvay SA |
| MicroCare Corporation |
| Reliance Specialty Products Inc. |
| Florachem Precision Cleaning Products |
| Tech Spray LP |
| Asahi Glass Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation in medical device cleaning solvents, creating tiered access where certified formulations command substantial premiums over industrial grades. REACH registration dossiers and EPA SNAP compliance timelines further stratify the supply base, concentrating pricing power among incumbents with established regulatory assets.
Pricing Analysis
Cost-plus contracts with specialty alcohol feedstock indexation dominate electronics-grade solvent procurement, insulating suppliers from propylene and ethylene derivative volatility. Three-tier pricing structure across aerospace-qualified, electronics-grade, and industrial-standard levels reflects certification depth and residue specification stringency. Pricing pressure stems from aqueous cleaning system substitution in automotive applications above 50 microns tolerance. Metal fabricators exhibit highest price sensitivity due to OSHA exposure limit compliance costs, while semiconductor fabs accept premium pricing for sub-0.1 microgram residue guarantees.
Supply Chain Analysis
Inbound logistics costs from Antwerp-Rotterdam port congestion and Rhine River low-water episodes disrupt specialty alcohol feedstock flows into German blending facilities. Supply concentrates in Germany, Belgium, and the United States for fluorinated and electronics-grade formulations, drawing from chlorinated precursor plants and integrated alcohol crackers. Single-source vulnerability pervades azeotropic blending expertise as legacy chlorinated solvent producers retire. Distribution runs through qualified direct sales for aerospace and semiconductor segments, with regional distributors capturing automotive and industrial procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vapor degreasing solvents market is recovering from regulatory compression cyclicality, with F-Gas Regulation phase-downs and EPA SNAP deadlines restocking specification pipelines across aerospace and electronics verticals.
For Market Incumbents: Consolidate formulation chemist expertise through targeted acquisition of retiring specialists from legacy chlorinated solvent producers, anchoring azeotropic blending capabilities before knowledge attrition accelerates. Deepen backward integration into specialty alcohol feedstocks to secure electronics-grade supply chains against Antwerp-Rotterdam logistics chokepoints. Lock aerospace specification relationships ahead of competitor validation cycles.
For New Entrants and Emerging Players: Lead with closed-loop vapor recovery service contracts in Indian electronics manufacturing corridors, where PLI scheme incentives are greenfielding semiconductor assembly capacity without incumbent solvent infrastructure. Target medical device contract manufacturers in Minnesota and Massachusetts with compact benchtop unit leasing bundled with ISO 10993-certified formulations. Penetrate through cleaning-as-a-service models that shift capital burden from fabricators to solvent suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hydrocarbon solvent blending as aqueous system substitution compresses equipment payback periods in mid-precision automotive tiers. Long-term viability favors suppliers with dual REACH-EPA registration dossiers and captive fluorinated materials production. Monitor California state-level solvent ban cascades as leading indicators of federal preemption timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alcohol Feedstocks | Solvay SA's captive supply of electronics-grade precursors insulates margin pools from Antwerp-Rotterdam logistics volatility. |
| Closed-Loop Vapor Recovery Service Contracts | Distillation reclamation models shift revenue from commodity solvent sales to performance-based cleaning-as-a-service in Indian PLI corridors. |
| ISO 10993 Biocompatibility Certification Investment | Medical device sterilization procurement gates in Minnesota and Massachusetts consolidate around certified precision cleaning suppliers. |
| Compact Benchtop Equipment Miniaturization | Trans-1,2-dichloroethylene formulations enable distributed cleaning nodes that reduce work-in-process inventory for just-in-time manufacturers. |
| REACH Dossier Maintenance and Expansion | ECHA authorization timelines of 18-24 months for new molecular entrants entrench incumbents with established registration assets. |
Study Parameters
A standing panel of vapor degreasing equipment engineers, solvent procurement leads at aerospace OEMs, electronics-grade chemical distributors, and plant managers at metal fabrication facilities provided ongoing calibration against primary interview findings. Secondary validation drew from ECHA REACH registration databases, EPA SNAP rule dockets, SEC 10-K filings of diversified chemical conglomerates, and customs trade data for specialty alcohol feedstock flows. Bottom-up volume estimates from end-use segment interviews triangulated against top-down market sizing from chemical production and trade statistics.
Consistency checks against fluorinated materials consumption disclosures and semiconductor fab capacity announcements validated volume and value outputs across the projection horizon. Segmentation modeling incorporated chemistry type, end-use industry, residue specification tier, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical substitution patterns and regulatory deadline impacts, with aerospace procurement cycle timing and semiconductor node advancement schedules as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained F-Gas Regulation enforcement or accelerated aqueous system substitution would require recalibration. Forecasts reflect assumptions regarding REACH authorization timelines and OSHA exposure limit trajectories. Recalibration cycles align with material shifts in EPA SNAP rule implementation and state-level solvent ban adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Diethanolamide Market
Solvents
Nitromethane Market
Solvents
Ethoxydiglycol Market
Solvents
Aromatic Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
Butyl Glycol Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Saudi Arabia Methanol Market
Solvents
North America Acetonitrile Market
Solvents
Ionic Liquids Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
High Purity Solvents Market
Solvents
Hydrosol Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Industrial Solvents Market