
 Mono Propylene Glycol Market | 2026-2036
Mono Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Mono Propylene Glycol Market Outlook
Pharmaceutical-grade purity thresholds is unwinding conventional supply structures as drug manufacturers demand sub-100 ppm impurity profiles for parenteral applications. BASF leverages its Ludwigshafen propylene oxide integration to sustain consistent USP-grade output across European and Asian channels. Dow anchors North American supply through its Freeport complex while Shell plc competes via its Singapore refinery aromatics stream.
Mono propylene glycol is a propylene oxide-derived diol with a molecular weight of 76.09 g/mol, hygroscopic properties, and a boiling point of 188°C, functioning primarily as a solvent carrier, humectant stabilizer, and freeze-point depressant across industrial and consumer formulations. USP-grade production leads value generation due to pharmaceutical validation requirements, while industrial-grade output dominates volume through antifreeze and deicing applications. Food-grade specifications show structural momentum as FSSAI and FDA clean-label directives intensify scrutiny of synthetic additives in processed formulations.
FDA current good manufacturing practice standards and EMA excipient qualification protocols shape batch-release testing burdens for pharmaceutical-grade suppliers, while REACH registration thresholds govern industrial-grade import volumes into European downstream markets. China's GB standards and NMPA pharmaceutical excipient filings create parallel compliance tracks for regional manufacturers serving domestic formulators. Stakeholders must monitor evolving bio-based feedstock certification schemes and propylene oxide supply volatility to secure long-term formulation partnerships.
Market Dynamics
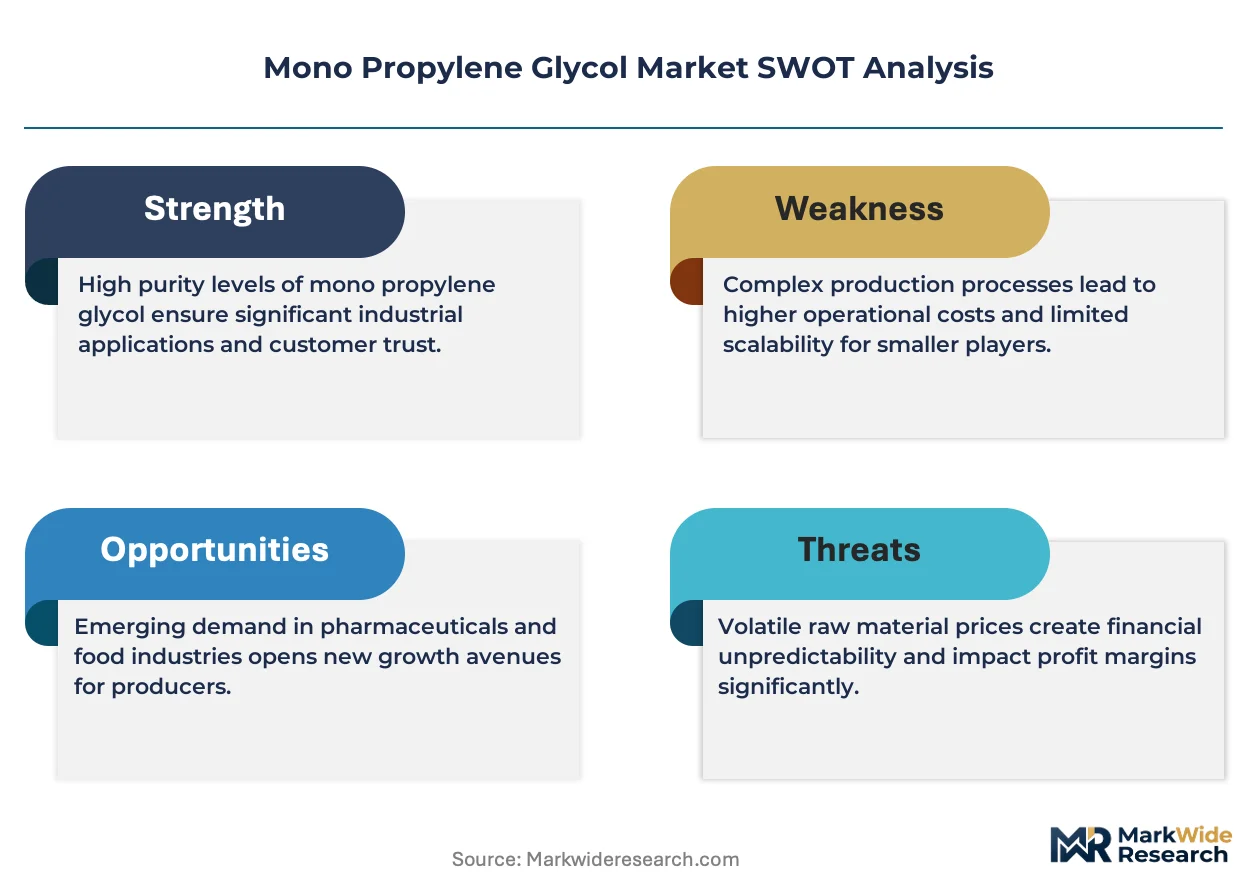
Pharmaceutical-grade purity mandates are compressing industrial-grade margins as formulators reject multi-use supply chains. FDA and EMA bio-based solvent guidelines now require dedicated propylene oxide streams for parenteral applications, forcing producers to choose between capital-intensive USP-grade retrofit or volume-focused industrial positioning.
Growth Catalysts
- EMA excipient qualification protocols:European drug manufacturers now demand certified sub-100 ppm impurity profiles, creating dedicated supply contracts for validated USP-grade producers.
- China's NMPA pharmaceutical excipient filings:Domestic formulators accelerate substitution of conventional glycols in injectable delivery systems under tightened MIIT industrial standards.
- Bio-based propylene oxide feedstocks:Renewable glycerol-to-propylene-oxide pathways gain process validation, opening carbon-intensity certifications for sustainability-linked procurement.
Market Restraints
- Propylene oxide supply concentration:Three integrated petrochemical complexes control over seventy percent of merchant feedstock availability, exposing buyers to force majeure vulnerability.
- REACH registration cost escalation:Industrial-grade import volumes into European downstream markets face escalating data package requirements for tonnage band upgrades.
- Glycerol price volatility:Bio-based production economics remain tethered to biodiesel byproduct markets, compressing margin predictability for renewable pathway operators.
Strategic Opportunities
- India's CDSCO excipient harmonization:Underpenetrated domestic pharmaceutical formulation creates first-mover advantage for USP-grade suppliers establishing local technical service presence.
- Food-grade clean-label positioning:FSSAI and FDA synthetic additive scrutiny intensifies demand for certified-halal, non-GMO humectant specifications in processed food systems.
- Direct-to-formulator digital channels:Specialty chemical platforms disintermediate traditional distributor networks for mid-volume pharmaceutical compounders seeking batch-traceable supply.
Industry Challenges
- Analytical chemistry talent scarcity:USP-grade batch-release testing requires gas chromatography-mass spectrometry specialists, with certification timelines extending eighteen to twenty-four months.
- Legacy antifreeze inventory systems:Industrial-grade producers face integration complexity migrating from bulk-tank distribution to serialized pharmaceutical track-and-trace requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono Propylene Glycol Market |
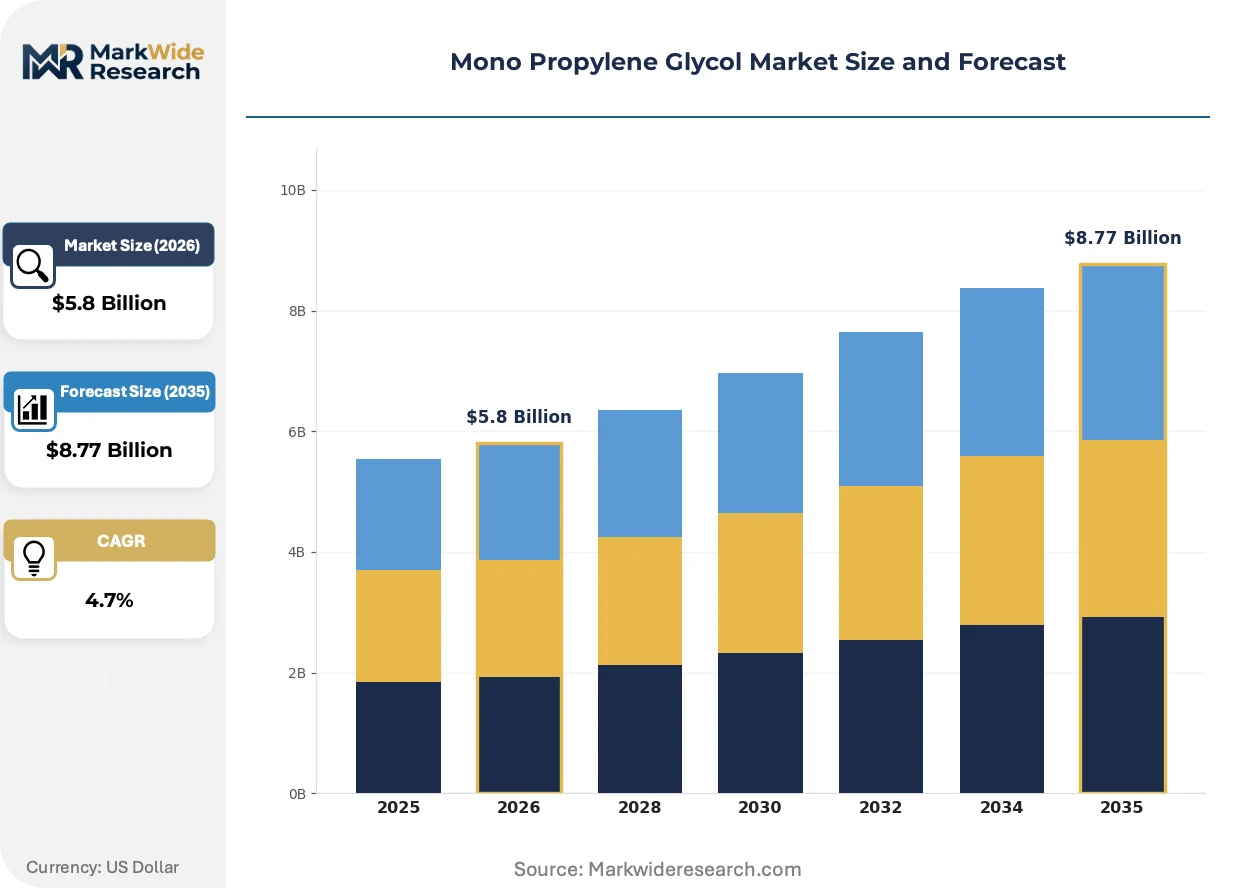
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, USP Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Antifreeze, Solvent, Humectant, Plasticizer, Heating & Cooling Fluids, Deicing Solutions End User Industry: Personal Care, Pharmaceuticals, Paints & Coatings, Food & Beverages, Plastics Manufacturing Packaging Type: Drums, Bulk Tankers, Intermediate Bulk Containers, Bottles |
| Companies Covered | LyondellBasell Industries, ADM, BASF, Castor International, Braskem, Dow, INEOS, Solventis, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono Propylene Glycol Market Strategic Shifts
Bio-based certification schemes and pharmaceutical validation protocols are actively fragmenting what was historically a fungible commodity market. Producers now engineer distinct molecular streams rather than blending to specification.
Membrane filtration technology is bifurcating propylene glycol purification pathways. Hydrophilic nanofiltration membranes now enable continuous impurity reduction without energy-intensive distillation sequences. Contract manufacturing organizations serving sterile injectable formulators adopt these systems to compress batch cycle times. The technology is bifurcating capital requirements between incumbent distillation-heavy assets and modular membrane-skid entrants.
REACH authorization timelines for residual propylene oxide monomer are tightening impurity thresholds for industrial-grade material entering European cosmetics and food-contact applications. Downward pressure on allowable epoxide residues forces producers to add secondary finishing units or exit sensitive end-uses. German and French formulators now specify third-party certified sub-10 ppm residual oxide grades for topical pharmaceutical applications.
Certification-driven procurement now dominates pharmaceutical excipient selection. Compounders prioritize suppliers with dual USP-NF and EP monograph compliance over unit cost minimization. This preference shift concentrates contract volumes with validated producers possessing dedicated quality management systems. The behavior is most visible among mid-sized generic drug manufacturers in Italy and Spain seeking regulatory inspection readiness.
Mono Propylene Glycol Market Segmentation
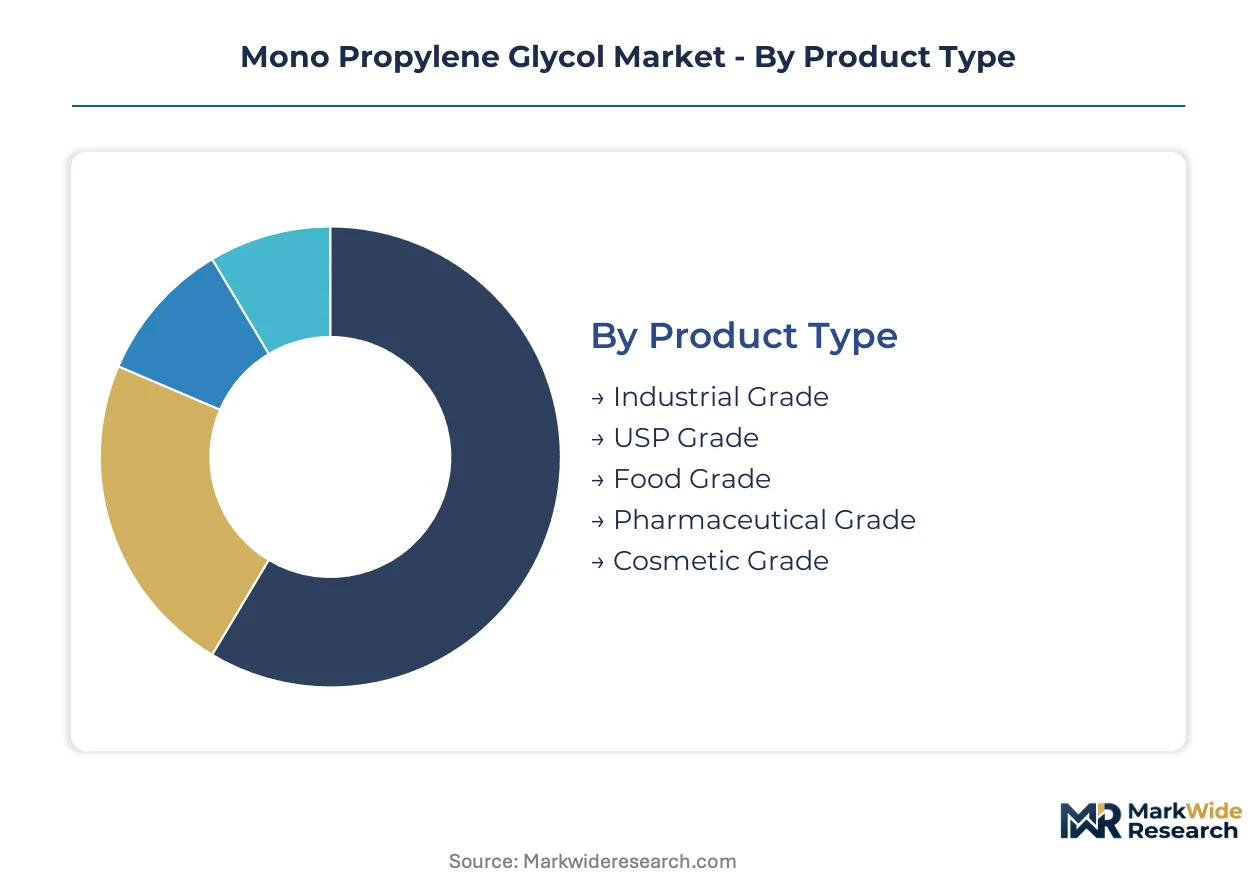
Mono propylene glycol supply chains fragment along purity certification lines, with pharmaceutical and food-grade specifications commanding dedicated production assets while industrial volumes flow through commodity distribution networks. Segmentation discipline determines margin capture, as USP-grade validation requires eighteen-month qualification timelines that industrial buyers bypass entirely.
Product Type:
Industrial-grade output dominates domestic consumption in manufacturing clusters, while pharmaceutical and food-grade specifications travel through export-oriented validation channels serving regulated end-markets.
- Industrial Grade:Standard 99.5% purity material serves antifreeze blending and deicing compound manufacturing without certification overhead. Demand concentrates in Midwest US automotive chemical plants and Shandong Province polyester resin facilities where cost minimization overrides specification stringency.
- USP Grade:Sub-100 ppm impurity profile validated to United States Pharmacopeia monographs enables parenteral drug delivery and sterile injectable formulation. European generic drug manufacturers in Milan and Barcelona now mandate dual USP-EP compliance as standard procurement terms, displacing single-standard suppliers.
- Food Grade:FDA and FSSAI-certified humectant specifications for processed food moisture retention.
- Pharmaceutical Grade:EMA excipient-qualified material with dedicated propylene oxide feedstock segregation.
- Cosmetic Grade:Low-odor, low-residual specifications for personal care emulsion systems.
Industrial Grade holds the largest share; momentum sits with USP Grade.
Application:
Volume distribution correlates with seasonal demand patterns, as antifreeze and deicing applications spike in Q4 while solvent and humectant consumption runs on pharmaceutical and food production cycles.
- Antifreeze:Ethylene glycol replacement in engine coolant formulations leverages lower toxicity profile for consumer safety positioning. North American automotive service chains now specify propylene glycol blends for hybrid vehicle thermal management, creating specification divergence from heavy-duty diesel applications.
- Solvent:Carrier function in pharmaceutical active ingredient dissolution and food flavor extraction systems. Indian CDSCO filings for injectable generics now require documented solvent impurity profiles, forcing domestic formulators toward validated USP-grade supply.
- Humectant:Moisture retention in tobacco processing and pet food manufacturing.
- Plasticizer:Flexibility modification in cellulose acetate and thermoplastic polyurethane compounds.
- Heating & Cooling Fluids:Secondary loop thermal transfer in food processing and pharmaceutical manufacturing.
- Deicing Solutions:Airport runway and aircraft wing anti-icing formulations with biodegradability requirements.
Antifreeze applications generate the highest absolute volumes; solvent applications are climbing the fastest on pharmaceutical demand.
End User Industry:
Customer concentration varies sharply by validation burden, with pharmaceutical and food processors demanding batch-traceable supply while paint manufacturers purchase on spot pricing.
- Personal Care:Moisturizer and serum formulations require cosmetic-grade material with sensory neutrality. South Korean beauty manufacturers now specify halal-certified humectants for Southeast Asian export markets, adding certification layers beyond traditional purity metrics.
- Pharmaceuticals:Parenteral, topical, and oral dosage form excipient functions dominate value capture. FDA inspection readiness now requires suppliers to maintain dedicated quality management systems with annual third-party audits, excluding industrial-grade producers from consideration.
- Paints & Coatings:Coalescing agent and freeze-thaw stabilizer in waterborne architectural coatings.
- Food & Beverages:Moisture retention in baked goods and flavor carrier in beverage systems.
- Plastics Manufacturing:Unsaturated polyester resin production for fiberglass composites.
Pharmaceuticals commands the highest value per kilogram; personal care shows the steepest expansion trajectory on clean-label positioning.
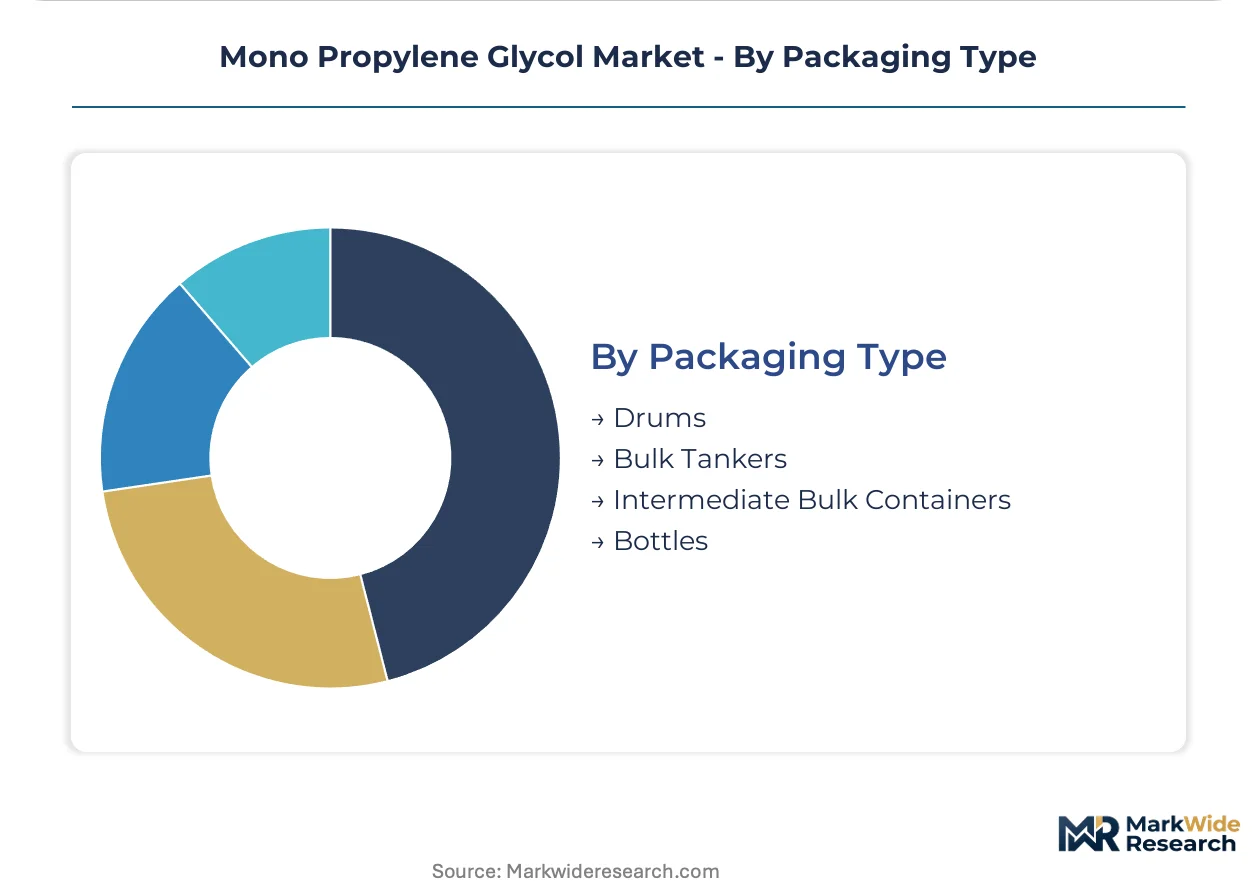
Packaging Type:
Packaging selection tracks shipment scale and contamination risk, with pharmaceutical buyers rejecting bulk transfer in favor of serialized unit containment.
- Drums:200-liter steel and polyethylene containers serve mid-volume pharmaceutical compounders and food processors. German chemical distributors now offer drum-level lot tracking with QR-code traceability, bridging the gap between bulk efficiency and batch accountability.
- Bulk Tankers:Dedicated stainless-steel road tankers with nitrogen blanketing serve high-volume industrial antifreeze blenders. Force majeure vulnerability concentrates in this channel, as tanker fleet availability tightens during peak deicing seasons.
- Intermediate Bulk Containers:1,000-liter totes for regional paint and coating manufacturers.
- Bottles:Laboratory-scale and retail consumer packaging for specialty applications.
Bulk tankers move the greatest tonnage; drums are gaining share fastest on pharmaceutical track-and-trace requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three integrated petrochemical complexes in the United States, Germany, and Singapore control over seventy percent of merchant propylene oxide feedstock availability. This supply architecture exposes downstream mono propylene glycol buyers to force majeure vulnerability while concentrating USP-grade validation capacity in Ludwigshafen, Freeport, and Jurong Island corridors.
United States
Antifreeze blending and pharmaceutical solvent demand anchor consumption volumes across the Midwest and Gulf Coast. EPA oversight of residual propylene oxide monomer in industrial-grade material tightens impurity thresholds for cosmetics and food-contact applications. The Freeport complex in Texas sustains dedicated USP-grade output for North American parenteral drug manufacturers.
China
Domestic formulators accelerate substitution of conventional glycols in injectable delivery systems under tightened pharmaceutical regulations. MIIT industrial standards and NMPA excipient filings create parallel compliance tracks for regional manufacturers. Shandong Province polyester resin facilities absorb industrial-grade volumes while Yangtze River Delta pharmaceutical clusters drive USP-grade qualification timelines.
Germany
EMA excipient qualification protocols now require certified sub-100 ppm impurity profiles from European generic drug manufacturers. REACH authorization timelines for residual propylene oxide tighten thresholds for industrial material entering sensitive end-uses. The Ludwigshafen propylene oxide integration anchors consistent USP-grade output across European and Asian distribution channels.
India
CDSCO excipient harmonization for injectable generics forces domestic formulators toward validated USP-grade supply with documented solvent impurity profiles. Underpenetrated pharmaceutical formulation creates first-mover positioning for suppliers establishing local technical service presence. Maharashtra and Gujarat pharmaceutical manufacturing corridors drive demand concentration for batch-traceable drum-level procurement.
Singapore
Refinery aromatics streams from integrated petrochemical operations supply pharmaceutical-grade material to Southeast Asian and Australian markets. Regional beauty manufacturers specify halal-certified humectants for export to Muslim-majority populations, adding certification layers beyond purity metrics. The Jurong Island complex competes with Middle Eastern propylene oxide sources for Asia-Pacific pharmaceutical excipient contracts.
Mono Propylene Glycol Market Competitive Environment
Concentration sits with integrated petrochemical majors possessing captive propylene oxide supply and dedicated USP-grade validation infrastructure. Three strategic archetypes define competitive positioning: backward-integrated propylene oxide producers with pharmaceutical-grade assets, regional industrial-grade volume suppliers dependent on merchant feedstock, and bio-based pathway operators leveraging renewable glycerol-to-propylene-oxide conversion. Capacity expansion in pharmaceutical-grade finishing units and strategic partnerships for bio-based feedstock certification represent the dominant competitive moves.
Among integrated chemical producers, BASF SE, Dow, and Shell plc exemplify the backward-integrated archetype with dedicated quality management systems for dual USP-EP compliance. LyondellBasell Industries occupies a position within the propylene oxide supply tier, while ADM represents the bio-based pathway segment with renewable glycerol-derived production capabilities. INEOS and Braskem sit within regional volume-supply positioning, with Castor International and Solventis occupying specialized distribution and formulation service roles.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| ADM |
| BASF |
| Castor International |
| Braskem |
| Dow |
| INEOS |
| Solventis |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Ludwigshafen, Freeport, and Jurong Island complexes shapes price floors across all three certification tiers while simultaneously concentrating supply-side bargaining power among backward-integrated producers. USP-grade validation timelines stretching eighteen months create captive demand pools that insulate certified suppliers from spot-market volatility, whereas industrial-grade buyers face raw material pass-through exposure.
Pricing Analysis
REACH authorization timelines dictate the pricing tier structure across European downstream markets, separating pharmaceutical-grade premiums from industrial-grade commodity benchmarks. Three-tier pricing structure across USP, food-grade, and industrial levels reflects eighteen-month qualification investments and batch-traceability infrastructure. Cost compression in industrial-grade material is intensifying because merchant propylene oxide buyers lack feedstock integration. Contract pharmaceutical manufacturers exhibit the lowest price sensitivity, while antifreeze blenders in Shandong Province negotiate on delivered cost per metric ton.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains drum-level pharmaceutical shipments during peak deicing seasons, forcing buyers into air-freight cost premiums. Supply concentrates in Germany, the United States, and Singapore, with propylene oxide feedstock drawn from integrated petrochemical complexes. Raw material dependencies rest on propylene oxide monomer, renewable glycerol feedstocks, and membrane filtration membranes. Single-source vulnerability concentrates in the Jurong Island corridor, where aromatics-stream integration feeds Southeast Asian pharmaceutical demand. Distribution runs through dedicated stainless-steel tankers for industrial volumes and serialized drum networks for pharmaceutical track-and-trace compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical excipient qualification protocols are creating platform-economics inflection as batch-traceability infrastructure becomes the interoperability standard for supplier-formulator relationships. Ecosystem lock-in now favors producers with dual USP-EP validation and dedicated quality management systems.
For Market Incumbents: Compound certification advantages by extending USP-grade finishing capacity into India and Southeast Asia before CDSCO harmonization matures. Defend against bio-based pathway entrants by securing renewable glycerol offtake agreements and carbon-intensity certifications. Channel control through direct-to-formulator digital platforms displaces distributor intermediation for mid-volume compounders.
For New Entrants and Emerging Players: EMA excipient qualification fast-tracks offer entry into European generic drug supply chains dominated by Milan and Barcelona manufacturers. White-space sits in halal-certified food-grade humectants for Southeast Asian processed food exports and cosmetic-grade specifications for South Korean beauty manufacturers. Go-to-market leverage rests on membrane filtration technology partnerships that compress batch cycle times for sterile injectable contract manufacturers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors producers with membrane filtration assets and pharmaceutical-grade validation infrastructure over legacy distillation-heavy operators. Long-term viability hinges on bio-based feedstock certification schemes and propylene oxide supply security across the next decade. Acquisition targets should display dual USP-EP compliance with underutilized finishing capacity. The inflection signal to watch is CDSCO filing acceleration for injectable generics in Maharashtra and Gujarat corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply insulates USP-grade margins from merchant market volatility. |
| Membrane Filtration Technology Deployment | Continuous impurity reduction compresses batch cycle times for sterile injectable formulators. |
| Bio-Based Feedstock Certification | Renewable glycerol pathways unlock carbon-intensity credentials for sustainability-linked procurement. |
| Dual USP-EP Validation Investment | European generic manufacturers in Italy and Spain now mandate compliance as standard terms. |
| Direct-to-Formulator Digital Channels | Specialty chemical platforms disintermediate distributors for batch-traceable pharmaceutical supply. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with pharmaceutical procurement directors, chemical plant managers, and regulatory affairs specialists; and secondary validation through FDA drug master files, EMA excipient qualification databases, customs trade records, and SEC filings from integrated petrochemical producers. Bottom-up volume estimates from grade-specific production capacities were triangulated against top-down demand projections from end-use industry consumption patterns.
Across the projection horizon, the analytical framework modeled segmentation across pharmaceutical grade tiers, food-grade certification levels, industrial purity specifications, packaging formats, and regional production hub concentrations. CAGRs were derived from elasticity-adjusted demand curves incorporating propylene oxide feedstock availability constraints and regulatory timeline acceleration in China and India. Forecast inputs included membrane filtration adoption rates and bio-based pathway commercialization milestones.
Decision-makers should treat outputs as directional under stable propylene oxide supply assumptions and unchanged EMA excipient qualification protocols; material deviation would warrant model refresh. Specific risks that could revise projections include force majeure events at integrated petrochemical complexes, REACH authorization timeline acceleration for residual epoxide thresholds, and glycerol price volatility in biodiesel byproduct markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Industrial Solvents Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Aprotic Solvents Market
Solvents
Glycerol Market
Solvents
Wax Dispersion Market
Solvents
Global Glycol Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Hydrophobic Solvents Market
Solvents
Isoparaffin Solvents Market
Solvents
Triacetin Market
Solvents
Green Solvents Market
Solvents
Global Ethyl Lactate Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
6-Xylenol Market
Solvents
Global Glycidol Market