
 North America Oriented Strand Board Market | 2026-2036
North America Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oriented Strand Board Market Analytics
Millwright and industrial mechanic availability is collapsing across the US South and Canadian Prairie provinces, forcing producers to automate panel presses and reduce unplanned downtime. West Fraser sustains its output advantage through captive timberland holdings and integrated veneer operations in British Columbia and the US Southeast. Louisiana-Pacific Corporation differentiates via specialty engineered wood products and precision strand orientation technology at its Houlton, Maine and Sagola, Michigan facilities. Georgia-Pacific competes through scale economics at its Clarendon County, South Carolina OSB complex, one of the continent's largest continuous presses.
Oriented Strand Board is an engineered wood panel manufactured from cross-oriented layers of thin wood strands bonded with waterproof phenol-formaldehyde or polymeric diphenylmethane diisocyanate resin under heat and pressure, typically rated for structural load-bearing applications at thicknesses from 7/16 inch to 3/4 inch. Structural OSB dominates residential wall sheathing and roof decking specifications, while moisture-resistant variants command premium positioning in coastal and humid climate zones where building codes mandate enhanced dimensional stability. Fire-retardant OSB occupies a narrower but expanding niche in multi-family mid-rise construction where ASTM E84 Class A surface burning ratings apply, and the 7/16 inch thickness category anchors volume production due to its ubiquity in single-family starter homes and production builder programs.
EPA TSCA Title VI formaldehyde emission limits and California Air Resources Board ATCM Phase II standards govern panel certification for US distribution, while Canadian Standards Association O437 and CSA O325 product standards regulate structural performance claims in Canadian provinces. US Department of Housing and Urban Development code adoption cycles and International Building Code updates shape specification thresholds for fire-rated and moisture-resistant grades in multi-story and flood-prone construction. Stakeholders must monitor evolving state-level embodied carbon disclosure requirements and mass timber code expansions that could redirect structural panel demand toward cross-laminated timber hybrids or solid-sawn alternatives in certain building typologies.
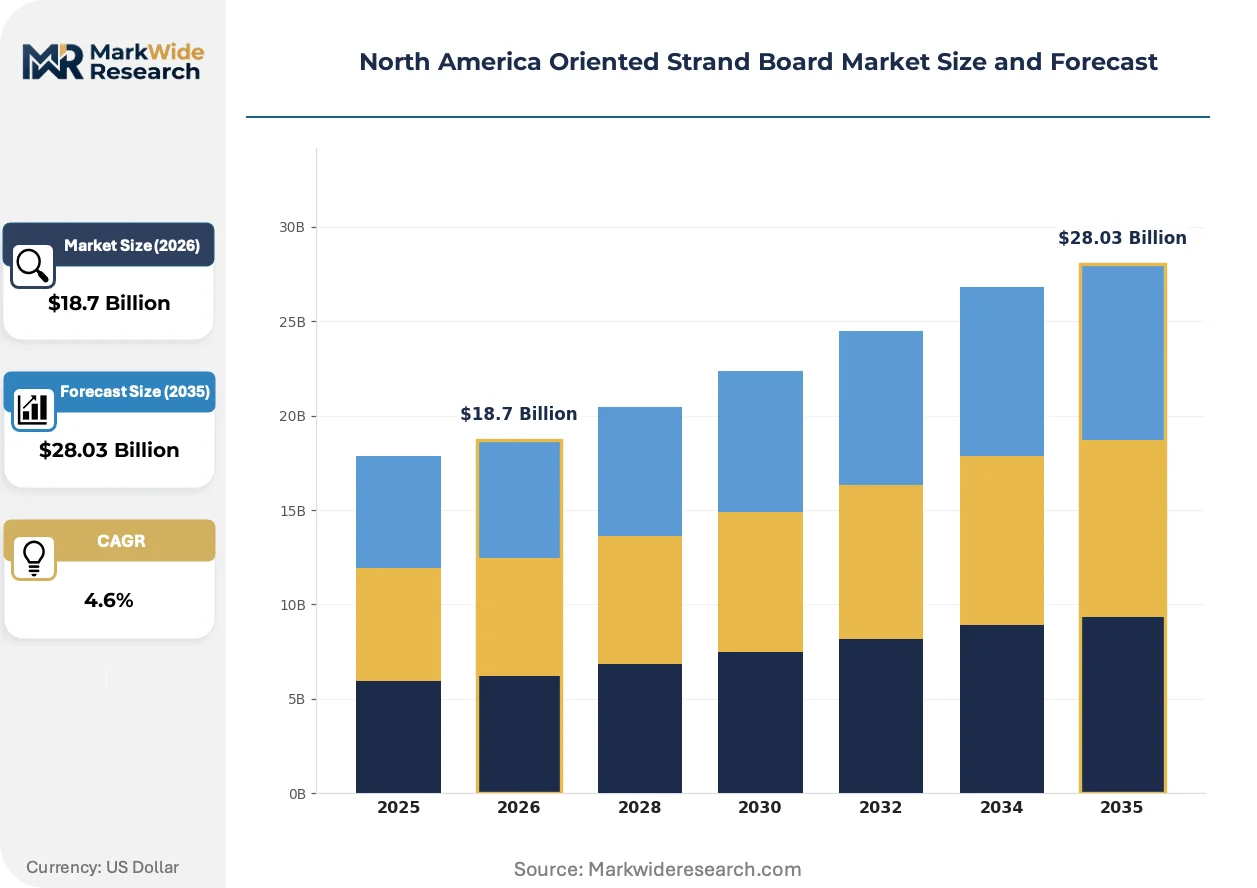
Market Dynamics
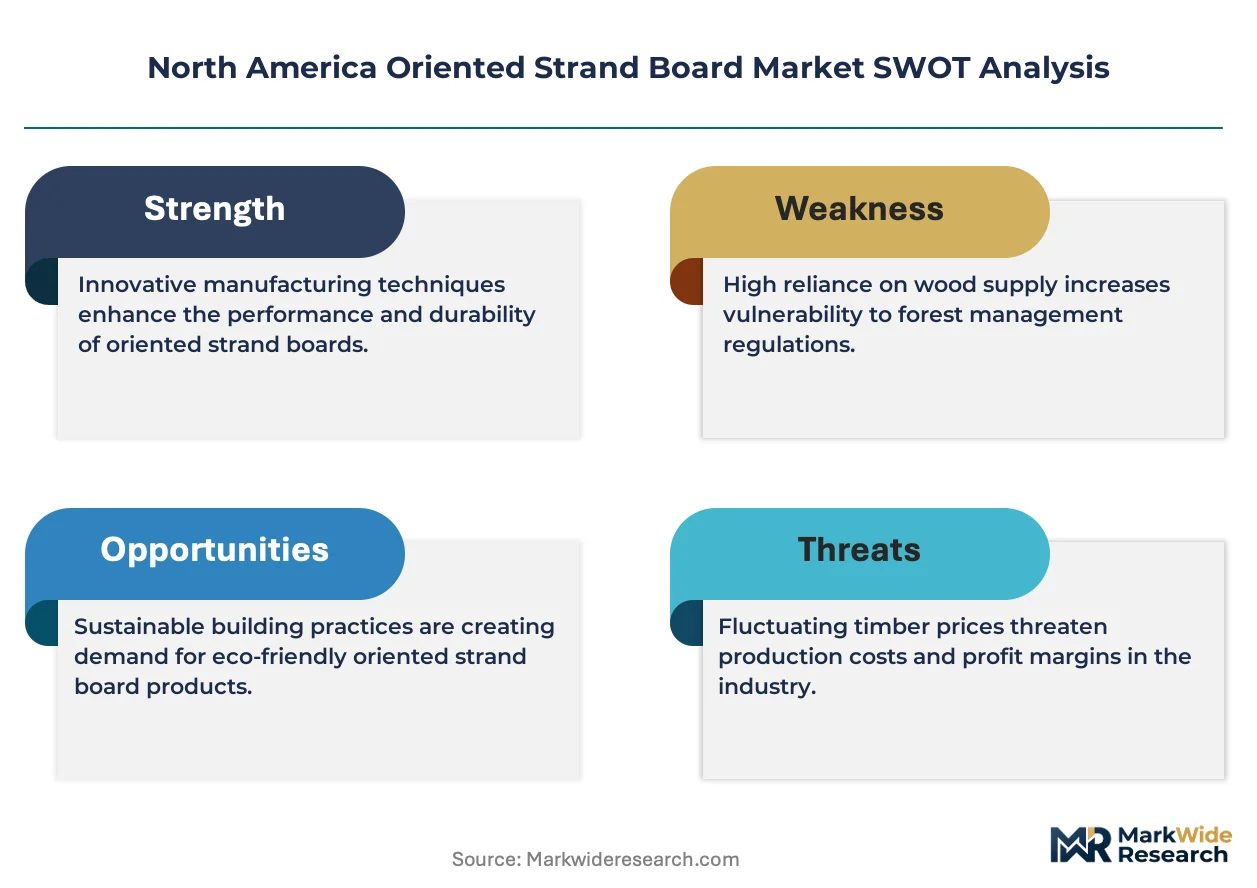
OSB producers face a structural squeeze between formaldehyde emission compliance costs and resin input volatility, forcing capital reallocation toward automated press lines and captive timberland integration to defend margin structures.
Growth Catalysts
- EPA TSCA Title VI:Stricter formaldehyde limits are accelerating plant retrofits and certification upgrades, consolidating supply toward compliant producers.
- Single-family wall sheathing:Persistent lumber price swings are redirecting builder specifications toward OSB structural panels in starter home construction.
- US Southeast mill clustering:Georgia, Alabama, and Mississippi pine belt access is drawing capacity expansions and feedstock security investments.
Market Restraints
- Phenol-formaldehyde resin volatility:Petrochemical input cost swings compress operating margins and destabilize contract pricing.
- Canadian Prairie supply concentration:British Columbia timberland ownership concentration creates feedstock access bottlenecks for non-integrated producers.
- Cross-laminated timber substitution:Mass timber code expansions in mid-rise multi-family construction threaten OSB share in floor and wall systems.
Strategic Opportunities
- Moisture-resistant grade expansion:Gulf Coast and Atlantic seaboard building code upgrades are creating premium positioning for enhanced dimensional stability products.
- Fire-retardant ASTM E84 Class A:Mid-rise multi-family construction mandates are opening specification pathways for surface-burning-rated panels.
- Automated press line integration:Robotics and predictive maintenance convergence is reducing unplanned downtime where millwright scarcity bites hardest.
Industry Challenges
- Millwright and industrial mechanic scarcity:US South and Canadian Prairie labor pools cannot sustain manual maintenance regimes, forcing premature automation capex.
- CARB ATCM Phase II timeline compression:Certification pathway bottlenecks delay product launches and lock out non-compliant inventory from California distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oriented Strand Board Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OSB, Structural OSB, Fire-Retardant OSB, Moisture-Resistant OSB Application: Residential Construction, Commercial Construction, Industrial Applications, Furniture Manufacturing End User: Contractors, Builders, Manufacturers, Distributors Thickness: 7/16 Inch, 1/2 Inch, 5/8 Inch, 3/4 Inch |
| Companies Covered | West Fraser, Louisiana-Pacific Corporation, Georgia-Pacific, Weyerhaeuser, J M Huber Corporation, Norbord Inc., Huber Engineered Woods LLC, Tolko Industries Ltd., Arbec Forest Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oriented Strand Board Market Evolving Landscape
Panel manufacturing is splitting between commodity scale operations and precision-engineered specialty lines, with regulatory chemistry constraints and labor scarcity driving divergent capital deployment strategies.
Precision strand orientation technology is bifurcating the OSB category into high-performance engineered grades and basic structural commodities. Custom home builders and light commercial contractors are specifying oriented-strand panels with optimized fiber alignment for load-bearing applications. This technical split is compressing mid-tier positioning and forcing producers to choose between scale economics or specialty premium capture.
EPA formaldehyde emission standards are tightening test protocols and third-party certification requirements for US distribution. Panel producers must maintain chain-of-custody documentation and laboratory testing partnerships to sustain compliance. The regulatory burden falls heaviest on smaller mills lacking in-house quality infrastructure, accelerating consolidation toward integrated producers with captive labs.
Builder procurement is consolidating toward direct mill relationships and volume commitment contracts, bypassing traditional distribution intermediaries. Large production homebuilders in Texas, Florida, and the Carolinas are negotiating annual offtake agreements with specified grade mixes. This channel compression is most visible in the US Southeast where mill proximity enables just-in-time delivery schedules and reduces working capital requirements.
North America Oriented Strand Board Market Segmentation
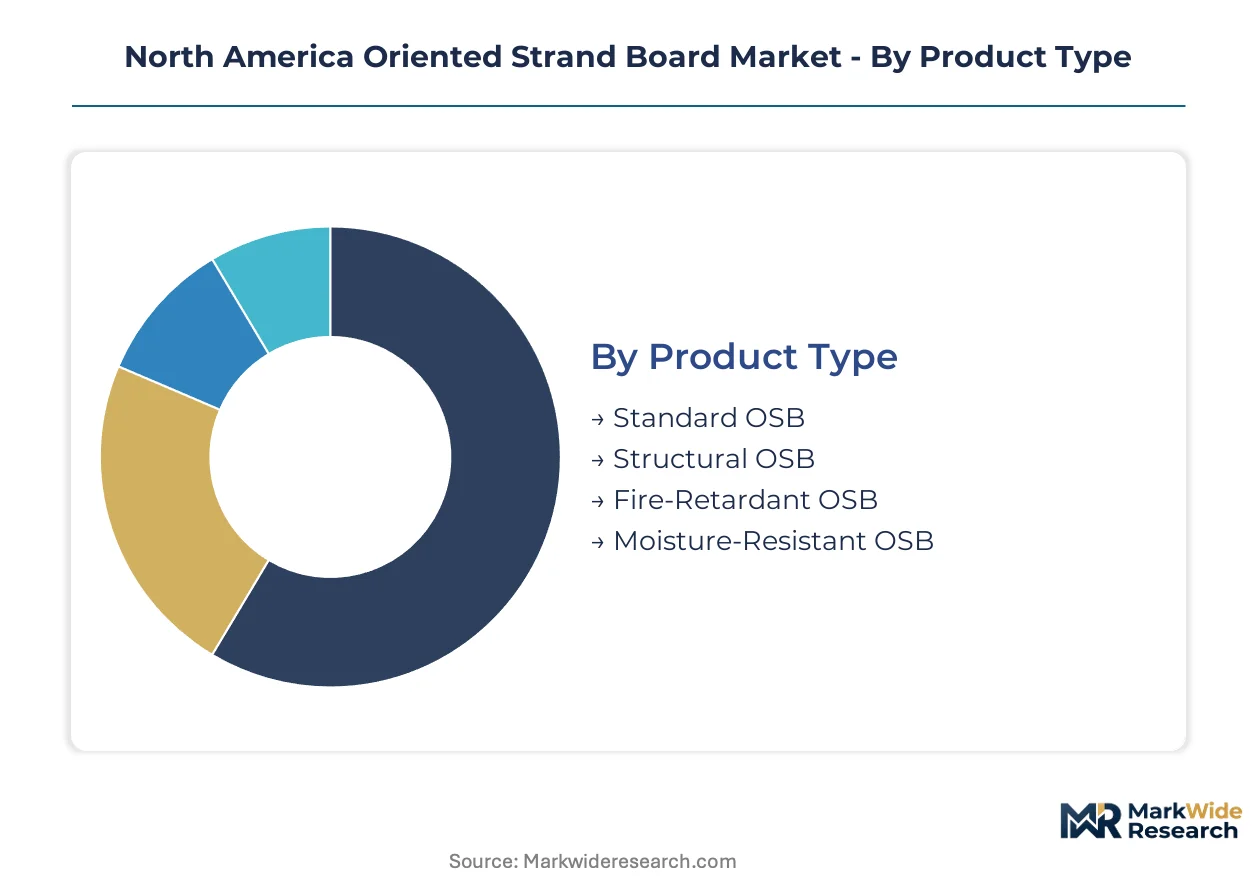
Segmentation in the North America Oriented Strand Board Market reflects divergent channel economics and specification requirements. Product grades, application contexts, and dimensional standards each command distinct procurement patterns and margin structures across the value chain.
Product Type:
Channel flow varies sharply by product tier: commodity grades move through distributor networks to volume builders, while specialty grades bypass intermediaries via direct mill contracts.
- Standard OSB:Manufactured with basic phenol-formaldehyde resin systems and minimal strand orientation optimization for cost-sensitive structural applications. Demand concentrates in US Southeast starter home construction where production builders specify 7/16 inch wall sheathing at scale, though resin cost volatility compresses margins for non-integrated producers.
- Structural OSB:Engineered with enhanced strand alignment and higher-density face layers to achieve greater span ratings and load-bearing capacity. Texas and Florida contractors are specifying structural grades for roof decking in hurricane-prone zones, driven by International Building Code wind uplift requirements.
- Fire-Retardant OSB:Impregnated with intumescent chemicals to achieve ASTM E84 Class A surface burning ratings for mid-rise multi-family construction.
- Moisture-Resistant OSB:Formulated with wax emulsion systems and edge sealing for Gulf Coast and Atlantic seaboard humidity exposure.
By volume, Standard OSB leads. By growth pace, Moisture-Resistant OSB is climbing the fastest.
Application:
Cost tier stratification separates high-specification commercial work from price-elastic residential volume.
- Residential Construction:Single-family wall sheathing and subflooring dominate procurement volumes, with US Southeast production builders negotiating annual offtake agreements.
- Commercial Construction:Light commercial and multi-family mid-rise projects specify fire-rated and structural grades at premium positioning, though cross-laminated timber substitution threatens floor system share.
- Industrial Applications:Pallet manufacturing and crating consume lower-grade OSB through secondary market channels.
- Furniture Manufacturing:Industrial-grade panels serve core material applications for ready-to-assemble furniture producers.
Residential Construction captures the largest volume share. Commercial Construction is gaining share fastest amid multi-family code expansion.
End User:
Customer type determines contract structure and working capital requirements across the procurement landscape.
- Contractors:Regional framing contractors in the Carolinas and Georgia purchase through distributor yards on project-based schedules.
- Builders:National production builders in Texas and Florida negotiate direct mill relationships with specified grade mixes and just-in-time delivery.
- Manufacturers:Secondary processors and furniture fabricators source through wholesale distribution with volume commitments.
- Distributors:Lumber yard networks and building material dealers carry inventory for spot market sales to smaller contractors.
Builders represent the highest volume channel. Contractors are expanding fastest as custom home activity rises.
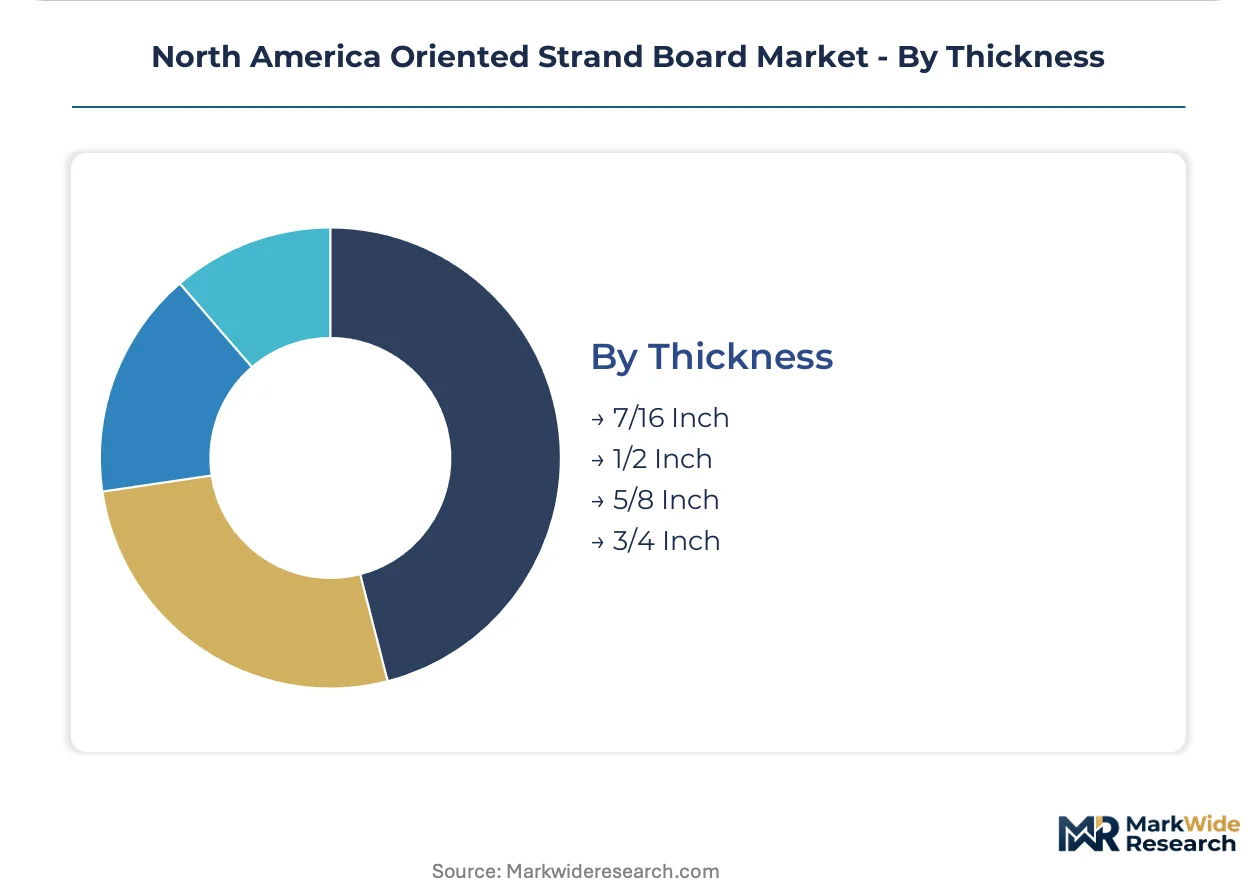
Thickness:
Volume concentration and margin profile diverge across dimensional specifications.
- 7/16 Inch:The dominant specification for single-family wall sheathing, produced at highest line speeds and lowest per-unit cost. Georgia-Pacific's Clarendon County complex and West Fraser's Southeast mills anchor supply for this thickness category.
- 1/2 Inch:Common for roof decking in jurisdictions with moderate snow load requirements, serving Midwest and Mid-Atlantic residential markets.
- 5/8 Inch:Specified for floor underlayment and heavier roof loads where enhanced stiffness is required.
- 3/4 Inch:Reserved for high-load commercial applications and specialty engineered systems with premium pricing.
7/16 Inch leads by volume. 5/8 Inch is expanding most quickly as floor system specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast consumes OSB predominantly for single-family wall sheathing, while Canadian Prairie provinces allocate larger shares to industrial crating and export-oriented panel production. Mexico's construction sector sources lower-grade OSB for informal housing and light commercial work. This demand-mix differential shapes mill location decisions and product slate optimization across the three-country bloc.
United States
Georgia, Alabama, and Mississippi anchor North American OSB capacity through pine belt feedstock access and deepwater port connectivity. EPA TSCA Title VI formaldehyde emission limits govern panel certification for interstate commerce, with California CARB ATCM Phase II creating additional compliance thresholds for West Coast distribution. Texas and Florida production builders negotiate direct mill contracts for 7/16 inch wall sheathing, bypassing traditional lumber yard intermediaries.
Canada
British Columbia timberland ownership concentration gives integrated producers captive feedstock security for Asian export markets and US border-state supply. Canadian Standards Association O437 and CSA O325 standards regulate structural performance claims in provincial building codes. Prairie province mills in Alberta and Saskatchewan face millwright labor scarcity that accelerates automation capex and reduces unplanned press downtime.
Mexico
Northern border states consume OSB for maquiladora industrial construction and cross-border logistics facility expansion. The country's national environmental regulator enforces emissions protocols for imported engineered wood panels, though enforcement intensity varies by customs port. Mexico City metro area contractors source lower-grade OSB through informal distribution channels for self-built housing and small commercial projects.
North America Oriented Strand Board Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ownership of captive timberland and continuous press scale separating the two groups. The top tier commands pricing power through backward integration into veneer operations and resin chemistry control. Mid-scale regional producers compete on freight-advantaged delivery to specific builder clusters. Dominant competitive moves include automated press line upgrades to offset labor scarcity and specialty grade development for moisture-resistant and fire-retardant specification capture.
Among North American-integrated producers, West Fraser exemplifies the timberland-captive archetype through British Columbia and US Southeast holdings. Louisiana-Pacific Corporation occupies a position within the specialty-engineered tier, with precision strand orientation capabilities distinguishing its product slate. Georgia-Pacific anchors the scale-driven end through continuous press economics at its Clarendon County complex. These three represent divergent strategic postures: captive resource control, technical differentiation, and manufacturing scale.
| Leading Market Players |
|---|
| West Fraser |
| Louisiana-Pacific Corporation |
| Georgia-Pacific |
| Weyerhaeuser |
| J M Huber Corporation |
| Norbord Inc. |
| Huber Engineered Woods LLC |
| Tolko Industries Ltd. |
| Arbec Forest Products Inc. |
| Others |
Value Network & Pricing Analysis
Continuous press capacity utilization at Georgia-Pacific's Clarendon County complex and West Fraser's Southeast mills anchors price floors across the North American OSB market, concentrating supply-side leverage among integrated producers with captive timberland holdings while forcing smaller competitors toward specialty grade differentiation to escape commodity margin compression.
Pricing Analysis
Long-term offtake agreements between US Southeast mills and national production builders in Texas and Florida dominate contract structures, locking in volume commitments for 7/16 inch wall sheathing at scale-based tiers. Price differentiation separates fire-retardant ASTM E84 Class A panels and moisture-resistant wax-emulsion grades from basic structural commodities, with certification level and geographic delivery cost as primary drivers. Cost compression in standard OSB intensifies because phenol-formaldehyde resin volatility feeds directly into operating margins. Production builders exhibit lowest price sensitivity due to just-in-time delivery requirements, while regional framing contractors in the Carolinas and Georgia face highest sensitivity through spot-market distributor purchases.
Supply Chain Analysis
Pine belt feedstock access in Georgia, Alabama, and Mississippi constitutes the critical chokepoint for North American OSB supply, with British Columbia timberland ownership concentration creating parallel bottlenecks for Asian export-oriented production. Raw material dependencies center on southern yellow pine strands, phenol-formaldehyde resin systems, and polymeric MDI binders. Tariff exposure on Canadian softwood lumber imports into the US threatens cross-border supply stability. Distribution runs through direct mill relationships for volume builders and lumber yard networks for smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American OSB market functions as a defensive-moat industry where regulatory entrenchment through EPA TSCA Title VI certification requirements creates substantial switching costs for builder procurement teams.
For Market Incumbents: Fortify position through backward integration into captive timberland in the US Southeast pine belt and automated press line deployment to offset millwright scarcity. Cross-laminated timber substitution in mid-rise multi-family construction demands fire-retardant grade expansion as the priority response. Certification investment in CARB ATCM Phase II compliance locks out non-compliant inventory from California distribution channels. For New Entrants and Emerging Players: Precision strand orientation technology for custom home builders represents the most penetrable service-layer gap where incumbents under-serve high-specification load-bearing applications. White-space targets include moisture-resistant grade supply to Gulf Coast contractors facing Atlantic seaboard code upgrades and fire-retardant panel production for ASTM E84 Class A mid-rise mandates. Go-to-market execution should anchor on direct mill contracts bypassing traditional lumber yard intermediaries. For Investors and Strategic Acquirers: Specialty-engineered producers with precision strand orientation capabilities and established laboratory testing partnerships constitute the optimal acquisition target archetype for medium-term consolidation plays. Long-term viability over the next decade hinges on regulatory chemistry adaptation and mass timber code displacement risk. The signal to monitor is embodied carbon disclosure requirement adoption at state level, which could redirect structural panel specification toward cross-laminated timber hybrids.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Press Line Integration | Robotics deployment at Georgia-Pacific's Clarendon County complex reduces unplanned downtime where millwright availability collapses. |
| Moisture-Resistant Grade Expansion | Wax emulsion formulation investments capture Gulf Coast and Atlantic seaboard building code upgrade premiums. |
| Captive Timberland Acquisition | Backward integration into Georgia and Alabama pine belt holdings secures feedstock against resin cost volatility. |
| Fire-Retardant Certification Pathway | ASTM E84 Class A surface burning rating investments open mid-rise multi-family specification channels. |
| Direct Mill Contract Structuring | Annual offtake agreements with Texas and Florida production builders bypass distributor working capital requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mill operations directors, residential construction procurement managers, lumber yard category buyers, and EPA compliance officers at panel manufacturing facilities. Secondary validation drew from EPA TSCA Title VI certification databases, CARB ATCM Phase II compliance registries, SEC 10-K filings from integrated producers, and building permit data from US Census construction spending reports. Bottom-up volume modeling across product grades and applications was triangulated against top-down macroeconomic indicators for residential construction activity.
Across the analysis window, the forecasting framework incorporated product type segmentation by performance tier, application context by construction vertical, end-user channel structure, and thickness specification by load-bearing requirement. CAGRs were derived from historical shipment data and forward-looking capacity expansion announcements. Key inputs included resin price indices, southern yellow pine stumpage rates, and International Building Code adoption cycles for fire-rated and moisture-resistant grades.
Forecasts assume regulatory continuity in EPA TSCA Title VI and CARB ATCM Phase II regimes; material policy shifts would require re-modeling of certification pathway timelines and compliance cost structures. Practitioners should keep alternative scenarios live as mass timber code expansions and state-level embodied carbon disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market