
 Steel Wire Rope Products Market | 2026-2036
Steel Wire Rope Products Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Wire Rope Products Market Insights
Offshore energy infrastructure is broadening the addressable base for steel wire rope suppliers as floating wind platforms require specialized mooring and lifting assemblies. WireCo WorldGroup leverages its deepwater product portfolio to anchor long-term supply relationships with marine contractors across the Gulf of Mexico and North Sea basins. Bekaert sustains R&D intensity in corrosion-resistant alloy coatings that extend service intervals in saltwater environments. Kiswire Ltd. competes on manufacturing scale, operating some of Asia's largest continuous rope-making lines to serve port authorities and crane OEMs.
Steel wire rope consists of multiple strands of metal wires laid helically around a central core, typically manufactured from high-carbon steel with tensile strengths exceeding 1,770 MPa to withstand heavy dynamic loads in lifting, hauling, and suspension duties. Its primary commercial purpose centers on transmitting tensile forces reliably across mining hoists, crane systems, elevator suspensions, and marine anchoring where synthetic alternatives lack sufficient abrasion resistance or temperature tolerance. Steel core configurations command premium positioning in deep-shaft mining and offshore crane applications where crush resistance and structural stability under shock loading justify higher unit economics. Fiber core alternatives occupy economy-tier segments in general construction and logging skidding where moderate loads and shorter service cycles reduce total cost sensitivity. Double braid constructions are gaining traction in marine towing and mooring lines where torque balance and fatigue life extension matter most.
OSHA crane and derrick standards in the United States mandate periodic inspection intervals and retirement criteria for running ropes, directly shaping replacement demand cycles and aftermarket service revenue pools. EU machinery directives under CE marking require manufacturers to document compliance with EN 12385 wire rope standards before placing lifting equipment into service, creating compliance barriers for non-certified suppliers. China's GB/T 20118 national standards govern general-purpose wire ropes while SAMR market surveillance intensifies quality enforcement across domestic distribution channels. Stakeholders must monitor how divergent inspection regimes and material certification requirements across these jurisdictions influence sourcing strategies and regional manufacturing footprints.
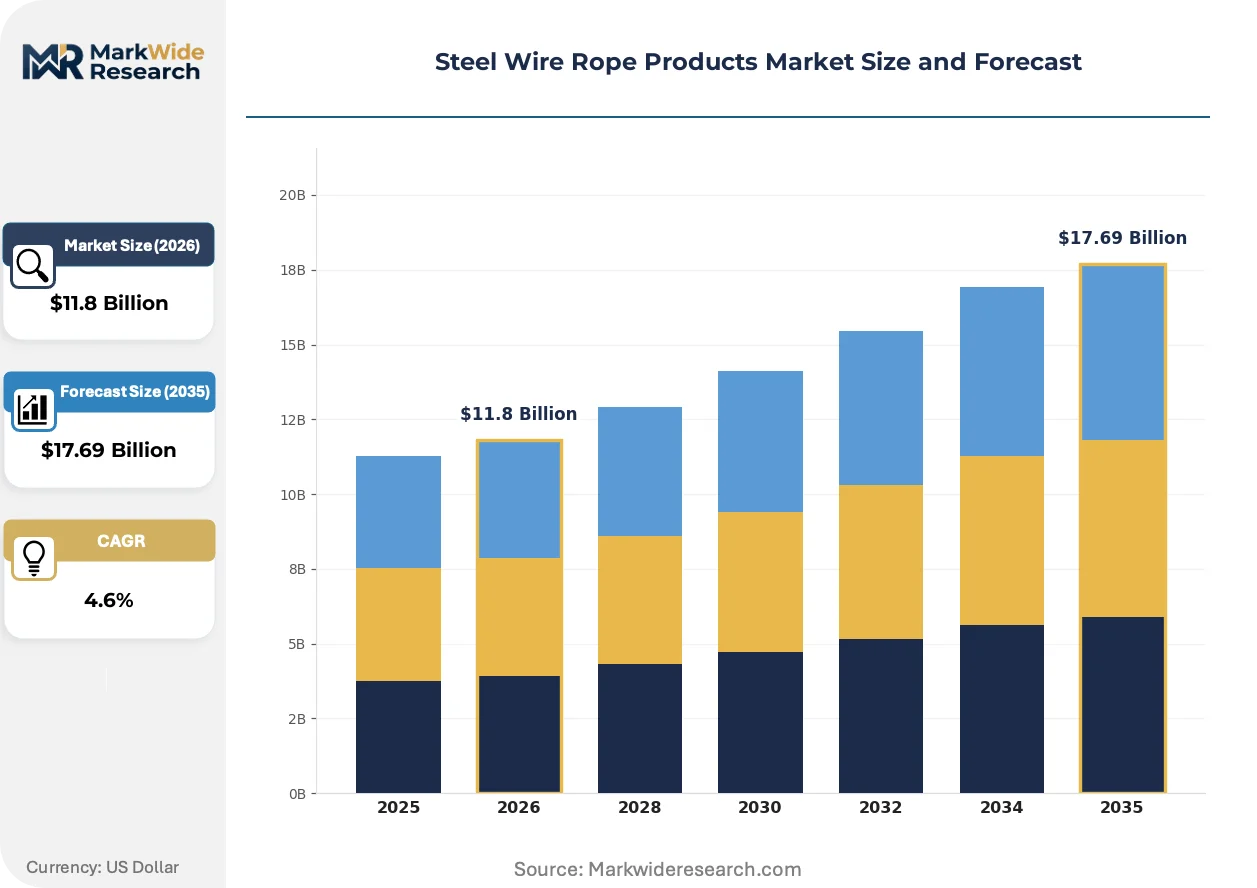
Market Dynamics
Floating offshore wind platforms are forcing steel wire rope manufacturers to engineer mooring systems rated for 60-year service lives in corrosive North Sea and Gulf of Mexico conditions. This structural pull toward extreme-environment performance is compressing supplier qualification timelines and concentrating procurement among certified marine contractors.
Growth Catalysts
- EU machinery safety directives:CE marking fatigue-testing protocols for lifting equipment are accelerating replacement cycles across European ports and shipyards.
- China's coastal provinces:Port modernization and shipbuilding activity in Jiangsu and Shandong are sustaining elevated demand for heavy-lift crane ropes.
- High-performance synthetic-steel hybrid cores:Torque-balanced constructions for floating wind mooring are opening new specification tiers above conventional wire rope.
Market Restraints
- High-carbon steel wire rod volatility:Scrap metal and alloy input costs fluctuate with Chinese export quotas and energy-intensive production curbs.
- Specialized marine rope concentration:Deepwater mooring qualification requires testing facilities concentrated in Norway, the Netherlands, and Singapore.
- Synthetic fiber substitution in logging:Ultra-high molecular weight polyethylene ropes displace steel in skidding applications where weight reduction outweighs abrasion concerns.
Strategic Opportunities
- Floating offshore wind installation fleets:Specialized mooring and lifting assemblies for pre-commercial projects in UK and French waters represent uncaptured specification value.
- Corrosion-resistant alloy coatings:Extended saltwater service intervals create aftermarket service contracts beyond initial equipment sales.
- Digital inspection integration:Magnetic flux leakage and ultrasonic testing embedded in port maintenance contracts reshape channel economics.
Industry Challenges
- Deepwater rope engineering talent:Fatigue modeling and polymer-core interface design require scarce specialists crossing materials science and marine engineering.
- Multi-jurisdictional certification timelines:Simultaneous OSHA, CE marking, and GB/T compliance for global crane OEMs extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Wire Rope Products Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Braid, Double Braid, Steel Core, Fiber Core Application: Mining, Marine, Construction, Logging End User: OEMs, Contractors, Wholesalers, Distributors Diameter: 1mm, 5mm, 8mm, 12mm |
| Companies Covered | WireCo WorldGroup, Bekaert, Kiswire Ltd., Bridon-Bekaert Ropes Group, Usha Martin Limited, Teufelberger, Pfeifer Group, Samson Rope Technologies, Tokyo Rope Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Wire Rope Products Market Trends and Innovations
Material science advances and inspection digitization are compressing the gap between raw wire production and predictive maintenance services. Manufacturers now compete on total lifecycle cost rather than unit price alone.
Plasma-transferred arc welding of corrosion-resistant alloy coatings onto high-carbon steel wires is rewriting durability benchmarks for subsea mooring applications. Offshore wind developers in the North Sea basin are specifying these surfaces for 25-year unmanned service intervals. The technology is compressing maintenance vessel schedules and reshaping supplier contract structures toward performance guarantees.
REACH substance restrictions on hexavalent chromium in surface treatments are forcing European wire rope manufacturers to accelerate trivalent chromium and zinc-aluminum-magnesium coating conversions. The industrial consequence is elevated R&D spend and temporary capacity constraints during line conversions. Marine and offshore segments in EU waters are absorbing premium pricing for compliant products while non-EU suppliers face market access barriers.
Buyer concentration among integrated marine contractors is compressing distributor layers in offshore wind supply chains. Direct specification relationships between rope manufacturers and EPC firms are displacing traditional maritime equipment distributors in UK and German project procurement. This channel consolidation is most visible in floating wind pre-assembly yards where single-source accountability for mooring system performance dominates sourcing criteria.
Steel Wire Rope Products Market Segmentation
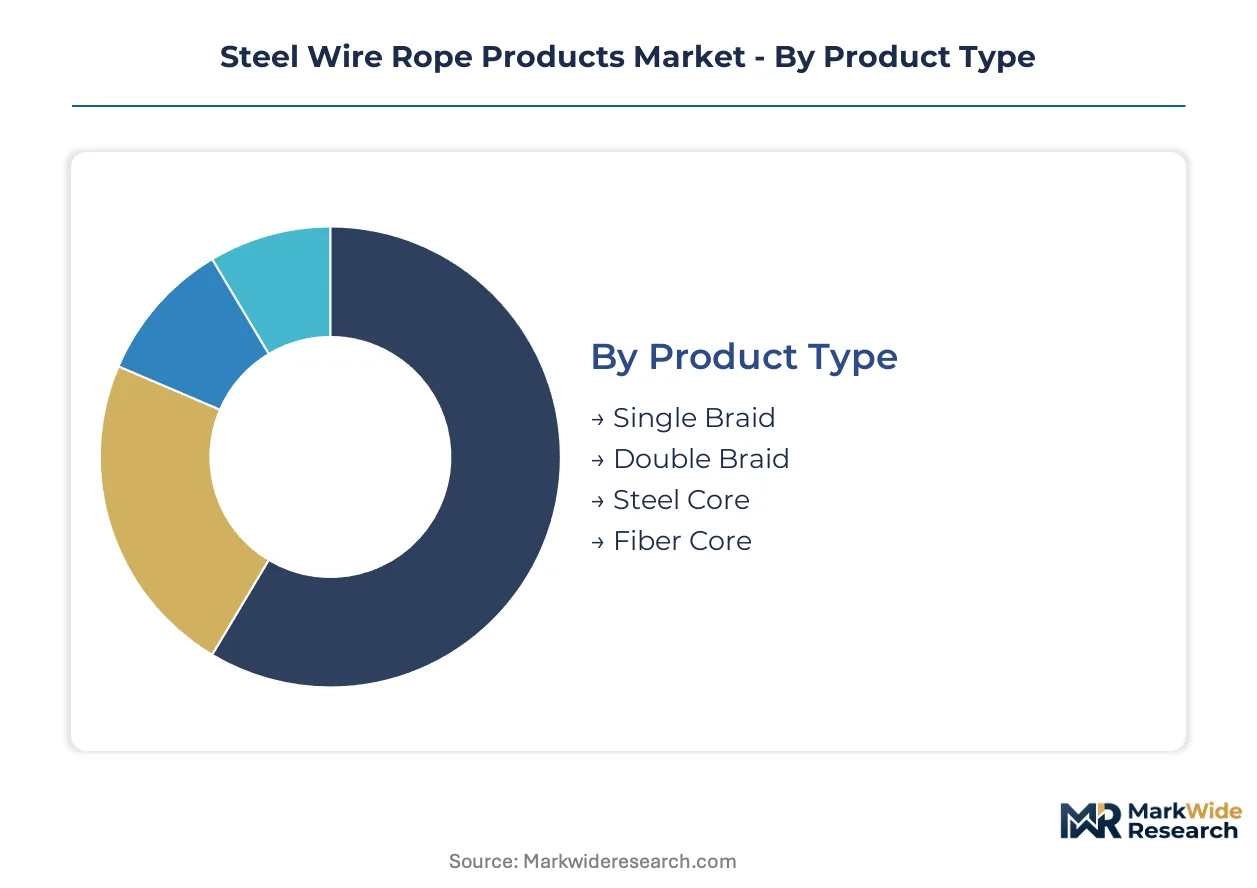
Steel wire rope segmentation reflects divergent certification burdens across product architectures and end-use environments. Regulatory complexity concentrates procurement decisions among qualified suppliers capable of multi-jurisdictional compliance documentation.
Product Type:
CE marking under EN 12385 governs lifting applications for all configurations, while offshore mooring ropes face supplementary DNV-ST-N001 qualification for deepwater service. OSHA 1910.179 mandates inspection protocols that vary by core construction in US crane installations.
- Steel Core:High-carbon steel strands wound around a central steel wire core deliver crush resistance exceeding 1,770 MPa tensile strength. Mining hoists in South Africa and Australia specify these configurations for shaft depths beyond 1,500 meters where structural stability under shock loading prevents catastrophic failure.
- Fiber Core:Synthetic or natural fiber centers provide flexibility and reduced weight for moderate-load applications. General construction crews in Brazil and Indonesia favor these ropes for tower crane rigging where shorter service cycles limit total cost sensitivity.
- Single Braid:One layer of helically laid strands around a central core. Standard lifting equipment in European ports deploys these constructions for routine cargo handling under predictable load profiles.
- Double Braid:Two concentric braided layers with opposing twist directions that neutralize torque under tension. Floating wind mooring systems in UK and French waters require these torque-balanced specifications for 60-year service intervals.
Steel Core sits at the top of the volume ranking, with Double Braid climbing the fastest.
Application:
End-use segmentation maps directly to duty cycle intensity and replacement frequency, with mining and marine commanding premium pricing against shorter-life construction and logging segments.
- Mining:Deep-shaft hoisting ropes face EN 12385-4 fatigue testing and mandatory retirement criteria after defined bending cycles. Underground operations in Chile and Kazakhstan drive specification toward 216mm diameter ropes rated for 2,000-meter vertical lifts.
- Marine:Offshore mooring and crane ropes must survive saltwater immersion and dynamic vessel motion. North Sea floating wind developers specify plasma-coated surfaces for 25-year unmanned service intervals, compressing maintenance vessel schedules.
- Construction:Tower cranes and material hoists utilize standard-duty ropes with periodic inspection regimes. China's coastal provinces absorb volume for port modernization projects in Jiangsu and Shandong.
- Logging:Skidding and yarding applications face synthetic fiber substitution as ultra-high molecular weight polyethylene ropes displace steel where weight reduction outweighs abrasion resistance.
Mining commands the highest unit economics, though marine applications are expanding most quickly.
End User:
Channel structure determines margin capture, with direct OEM relationships sustaining price premiums against price-sensitive wholesale distribution.
- OEMs:Crane manufacturers and mining equipment builders specify ropes during original equipment design, locking in multi-year supply agreements with performance guarantees.
- Contractors:Marine EPC firms and construction operators procure directly for project-specific requirements, displacing traditional distributors in offshore wind supply chains.
- Wholesalers:Inventory-heavy intermediaries serve fragmented construction and logging customers with standard specifications and rapid fulfillment.
- Distributors:Technical specialists provide inspection and splicing services alongside product sales, capturing aftermarket revenue in port maintenance contracts.
OEMs dominate value capture, while contractors are gaining share fastest through direct specification authority.
Diameter:
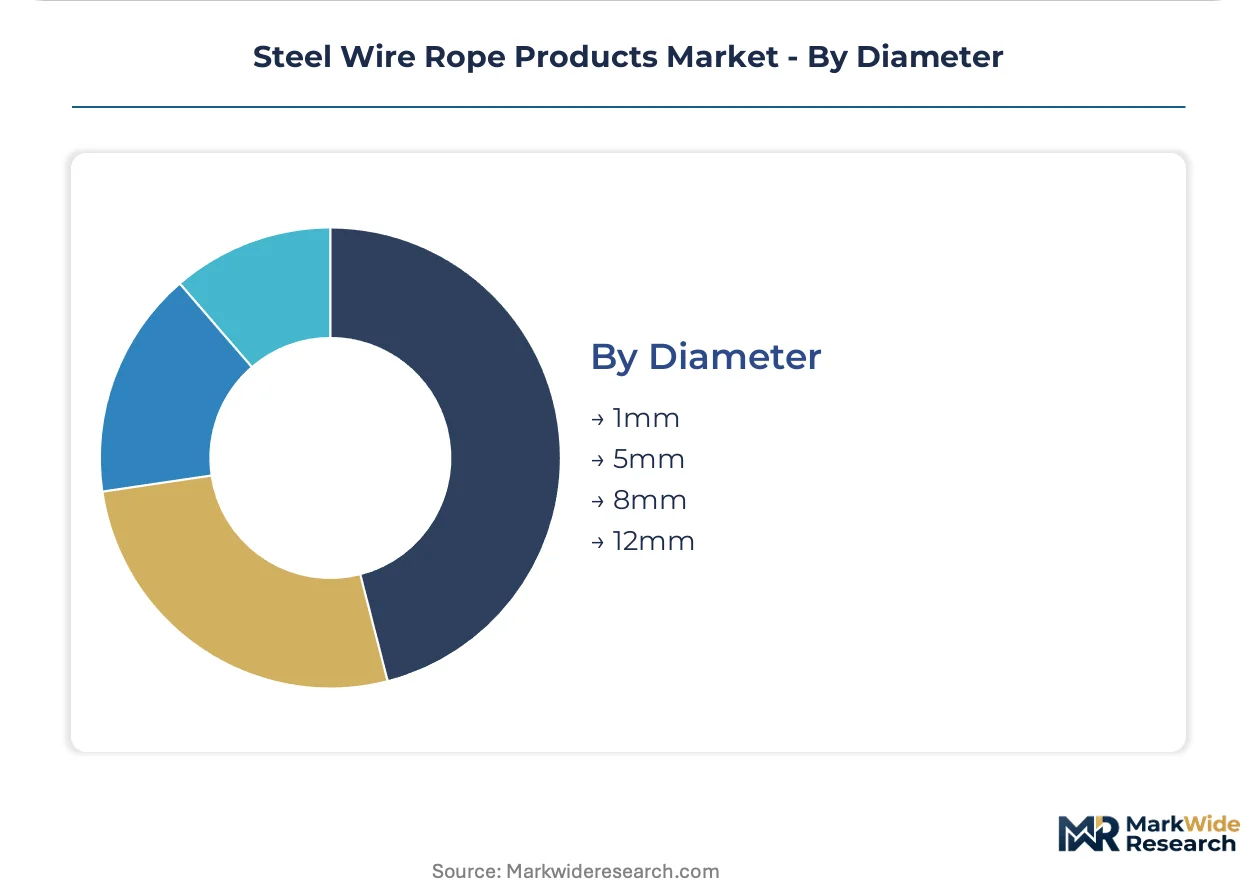
Dimensional segmentation correlates with load capacity and regulatory scrutiny, with larger diameters facing intensified testing documentation.
- 12mm:Heavy-lift marine and mining ropes require DNV or ABS certification for rated loads exceeding 50 tonnes. Offshore crane systems in Norway and Singapore specify these dimensions for subsea installation vessels.
- 8mm:Mid-range construction and general port handling applications balance strength with handling convenience. European shipyards standardize on this diameter for deck cranes under CE marking compliance.
- 5mm:Light-duty rigging and secondary lifting tasks in manufacturing facilities. Japanese automotive plants utilize these ropes for assembly line conveyance systems.
- 1mm:Specialized instrumentation and control cable applications with minimal load-bearing function. Precision equipment manufacturers in Germany integrate these into medical and aerospace systems.
8mm diameter holds the volume leadership position, with 12mm specifications showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing footprints as producers seek jurisdictions with streamlined certification pathways and lower compliance costs. CE marking fatigue-testing mandates in Europe and OSHA inspection regimes in North America create divergent cost structures that influence sourcing decisions.
China
Jiangsu and Shandong coastal provinces sustain heavy-lift crane rope demand through port modernization and shipbuilding expansion. SAMR intensifies GB/T 20118 quality enforcement across domestic distribution channels, compressing non-compliant supplier margins. Qingdao and Nantong industrial clusters anchor steel wire rope fabrication for export-oriented marine equipment.
United States
Offshore wind installation fleets in the Gulf of Mexico drive specification for deepwater mooring systems with extended service intervals. OSHA 1910.179 crane and derrick standards mandate periodic inspection protocols that accelerate replacement cycles. Houston marine service bases concentrate aftermarket inspection and splicing operations.
Germany
North Sea floating wind developers specify plasma-coated rope surfaces for 25-year unmanned service intervals. REACH substance restrictions on hexavalent chromium force coating conversions that elevate R&D spend and compress capacity during line transitions. Hamburg and Bremerhaven port authorities absorb premium pricing for compliant lifting equipment.
Norway
Subsea installation vessels operating North Sea oil and gas fields demand 12mm diameter ropes with DNV certification for rated loads exceeding 50 tonnes. DNV-ST-N001 qualification requirements for deepwater service concentrate testing infrastructure in Stavanger and Bergen. Stavanger marine engineering clusters anchor fatigue modeling expertise for extreme-environment mooring design.
Singapore
Marine EPC firms serving Southeast Asian offshore projects procure directly from qualified rope manufacturers, displacing traditional distributor layers. The city-state's testing facilities serve as qualification hubs for Asia-Pacific deepwater mooring contracts. Jurong shipyard complexes concentrate demand for corrosion-resistant alloy coatings in tropical saltwater conditions.
Steel Wire Rope Products Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale continuous rope-making lines to capture floating wind mooring contracts. The vendor base stratifies across three tiers: integrated steel-to-rope producers with captive wire rod supply; specialized marine rope fabricators with DNV/ABS qualification authority; and regional construction-grade suppliers competing on fulfillment speed. Tier consolidation accelerates through backward integration into high-carbon steel wire rod production and geographic expansion into coastal wind development zones.
Within the integrated producer tier, WireCo WorldGroup and Bekaert occupy positions defined by deepwater product portfolios and corrosion-resistant coating capabilities. Kiswire Ltd. exemplifies scale-driven manufacturing archetypes operating continuous production lines. These three entities anchor competitive positioning across marine contractor direct procurement channels and OEM specification relationships.
| Leading Market Players |
|---|
| WireCo WorldGroup |
| Bekaert |
| Kiswire Ltd. |
| Bridon-Bekaert Ropes Group |
| Usha Martin Limited |
| Teufelberger |
| Pfeifer Group |
| Samson Rope Technologies |
| Tokyo Rope Manufacturing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Integrated marine contractors and floating wind EPC firms command direct procurement relationships that compress traditional distributor markups and anchor contract-based long-term offtake pricing. This buyer concentration rewards certified suppliers with multi-year performance guarantees while squeezing margins for non-qualified competitors.
Pricing Analysis
Distributor margins in standard construction-grade ropes face compression as direct-to-OEM channels capture premium marine and mining specifications. Three-tier pricing structure across DNV-certified premium, CE-marked standard, and GB/T economy levels reflects certification burden and testing documentation intensity. Cost compression in fiber core segments intensifies because ultra-high molecular weight polyethylene substitutes erode steel rope volumes in logging applications. Construction contractors in Brazil and Indonesia exhibit highest price sensitivity, while North Sea floating wind developers absorb premiums for 60-year service life guarantees.
Supply Chain Analysis
High-carbon steel wire rod supply rests on Chinese, Japanese, and South Korean producers subject to export quota volatility and energy-intensive production curbs. Zinc-aluminum-magnesium alloy coatings, synthetic fiber cores, and plasma-transferred arc welding equipment constitute critical input dependencies. Single-source vulnerability concentrates in Norwegian and Dutch testing facilities for DNV-ST-N001 deepwater qualification. Distribution runs through direct manufacturer-to-EPC relationships in offshore wind, bypassing traditional maritime equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as floating offshore wind specifications displace commodity-grade volume with corrosion-resistant, torque-balanced premium products.
For Market Incumbents: Cement DNV and ABS certification authority through exclusive testing facility partnerships in Norway and Singapore. Lock in backward integration into high-carbon steel wire rod production to insulate against Chinese export quota volatility. Synthetic fiber substitution in logging and construction segments threatens volume tiers; defend through captive supply of alloy-coated premium specifications for marine contractors. For New Entrants and Emerging Players: The mid-tier price gap between DNV-certified premium ropes and GB/T economy grades offers white-space entry through CE-marked standard products for European port modernization. Target Jiangsu and Shandong coastal provinces where SAMR enforcement compresses non-compliant domestic suppliers. Partner with regional crane OEMs for specification-in-design relationships that bypass established marine distributor networks. For Investors and Strategic Acquirers: Integrated steel-to-rope producers with captive wire rod supply are the most active acquirer in this space, consolidating regional construction-grade competitors for scale. Five-to-ten year viability hinges on floating wind installation fleet expansion and qualification timeline compression. Watch DNV-ST-N001 certification backlog as inflection indicator for supplier pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod | Captive high-carbon steel supply insulates against Chinese export quota volatility and stabilizes input costs. |
| DNV Certification Investment | Testing facility partnerships in Norway and Singapore unlock floating wind mooring contract access. |
| Corrosion-Resistant Coating Scale-Up | Plasma-transferred arc welding capacity captures 25-year unmanned service interval specifications. |
| Direct EPC Channel Development | Manufacturer-to-contractor relationships displace distributor layers in UK and German offshore wind. |
| Digital Inspection Service Bundling | Magnetic flux leakage testing embedded in port maintenance contracts reshapes aftermarket economics. |
Research Methodology
Bottom-up mining and marine modeling reconciled against top-down steel wire rod production tracking forms the analytical core of this study. Primary interviews with crane OEM procurement teams, marine EPC contractors, port maintenance directors, and aftermarket service technicians combined with secondary validation from customs trade data, SEC filings of listed wire rod producers, OSHA enforcement records, and DNV certification registries. Triangulation across these sources ensures volume estimates align with actual qualification timelines and replacement cycle documentation.
Historical trendline analysis of rope diameter specifications, core construction mix shifts, and coating technology adoption informs the projection framework. Segmentation dimensions span product architecture, end-use intensity, channel structure, and regional regulatory clusters. CAGRs derive from fitted growth curves applied to qualified supplier capacity expansion and floating wind project development pipelines. Forecast inputs include SAMR enforcement intensity in China, REACH coating conversion completion in Europe, and offshore wind installation fleet deployment schedules.
Caveats apply where Chinese steel export policy shifts, DNV testing facility capacity constraints, or synthetic fiber substitution acceleration could materially shift the outlook. Forecasts reflect assumptions regarding certification timeline stability and alloy coating technology diffusion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
France Ceramic Tiles Market