
 Roof Window Market | 2026-2036
Roof Window Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Window Market Analysis
European timber-frame fabricators is broadening output capacity for high-performance roof windows as housing retrofit targets tighten. Velux leverages its integrated supply chain to control distribution across Nordic markets. Fakro competes through specialized PVC and wood-composite lines engineered for cold-climate performance. Roto anchors its position in Central Europe with tilt-turn hardware systems that extend product functionality.
A roof window is an operable or fixed fenestration unit installed on sloped roof surfaces, typically incorporating double or triple glazing with warm-edge spacers and condensation-resistant frames to manage thermal bridging while delivering daylight and ventilation to attic or upper-floor spaces. Ventilated roof windows command structural priority in residential retrofits where moisture management and passive cooling drive specification, while fixed units dominate new construction segments where cost control outweighs operability needs. Aluminum-clad wood frames capture margin concentration in premium residential and commercial applications across Germany and Austria.
CE marking under the EU Construction Products Regulation governs structural load, thermal transmittance, and air permeability compliance for roof windows sold across member states, with national building codes in Denmark and Sweden layering stricter U-value thresholds that filter lower-efficiency imports. The EU Green Deal and national renovation wave programs directly shape demand by tying public subsidy eligibility to window replacement schedules and energy performance certificates. Stakeholders must monitor how evolving Ecodesign requirements and embodied carbon disclosure rules under the CSRD reshape material selection and supplier qualification criteria.
Market Dynamics
The EU Green Deal's renovation wave mandates are compressing replacement cycles across Northern European housing stock, forcing fabricators to triple-glaze production lines faster than installer capacity can absorb.
Growth Catalysts
- CE marking under EU Construction Products Regulation:Harmonized standards for thermal transmittance and air permeability enable cross-border sales, reducing certification duplication for Polish and Czech manufacturers exporting into Germany.
- Attic conversion activity:Remote work permanence in Denmark and Sweden drives residential retrofits requiring ventilated roof windows for code-compliant daylighting and moisture management.
- Triple-pane glazing:Warm-edge spacer technology and low-emissivity coatings deliver U-values below 0.8 W/m²K, satisfying Denmark's 2025 building code thresholds that filter single-glazed imports.
Market Restraints
- Aluminum and timber input volatility:Baltic birch plywood and extruded aluminum frame cladding face price swings from Swedish sawmill capacity constraints and energy-intensive smelter operations.
- Installer bottleneck concentration:Certified roof window installation in Germany relies on a fragmented guild system where training pipelines lag retrofit subsidy deadlines.
- Flat-roof substitution:Modular skylight systems for low-slope commercial buildings capture daylighting specifications that pitched-roof windows cannot serve.
Strategic Opportunities
- Polish housing stock penetration:Underrenovated single-family homes in Silesia and Greater Poland present volume potential as national energy performance certificates tighten resale requirements.
- Smart home integration:Rain sensors and automated ventilation controls converge with building management systems, commanding premium positioning in Austrian passive house developments.
- CSRD-aligned embodied carbon disclosure:Early compliance with corporate sustainability reporting rules positions timber-frame suppliers for public procurement preference in France and the Netherlands.
Industry Challenges
- Passive house certifier scarcity:The pool of accredited auditors for PHIUS and PHI certification in Central Europe cannot match the velocity of retrofit project filings.
- Legacy roof pitch standardization:Non-standard angles in 1970s French and Belgian housing stock force custom flashing fabrication, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Window Market |
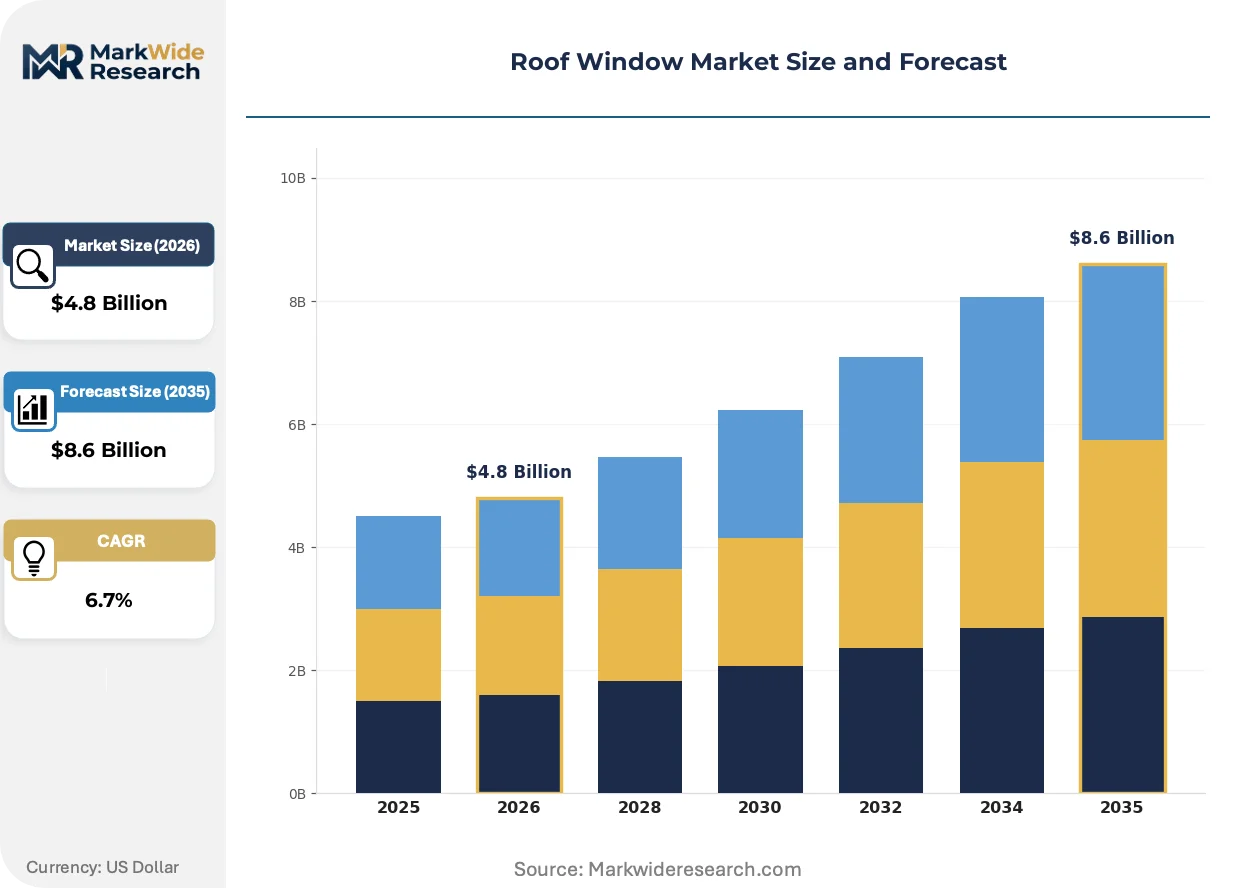
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Roof Windows, Ventilated Roof Windows, Skylights, Roof Lanterns Material: Wood, PVC, Aluminum, Fiberglass End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Educational Institutions Installation Type: New Construction, Retrofit, Replacement, DIY |
| Companies Covered | Keylite, OKPOL, Velux, Sunsquare, Dakea, Fakro, Lamilux, Faelux, Roto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Window Market Emerging Trajectories
Product intelligence and material science are converging to redefine performance benchmarks, with connectivity and thermal engineering now table stakes rather than differentiators.
Electrochromic glazing with user-adjustable tint levels is rewriting how daylight control integrates into energy management. German multi-family developers specify these units to eliminate external shading hardware. The technology compresses HVAC load calculations and reduces mechanical system sizing in net-zero projects.
Denmark's 2025 building code revision layers stricter U-value thresholds on roof windows, filtering lower-efficiency imports from non-EU suppliers. Polish fabricators are retooling extrusion lines to meet these specifications ahead of enforcement. The regulation accelerates consolidation among mid-tier suppliers unable to absorb R&D costs.
Homeowner specification behavior is fragmenting across digital and traditional channels. Online configurators with photorealistic placement visualization capture early-stage research in Sweden and Norway. Installer networks respond by unbundling measurement services from product markup, compressing traditional distributor margins in urban markets.
Roof Window Market Segmentation
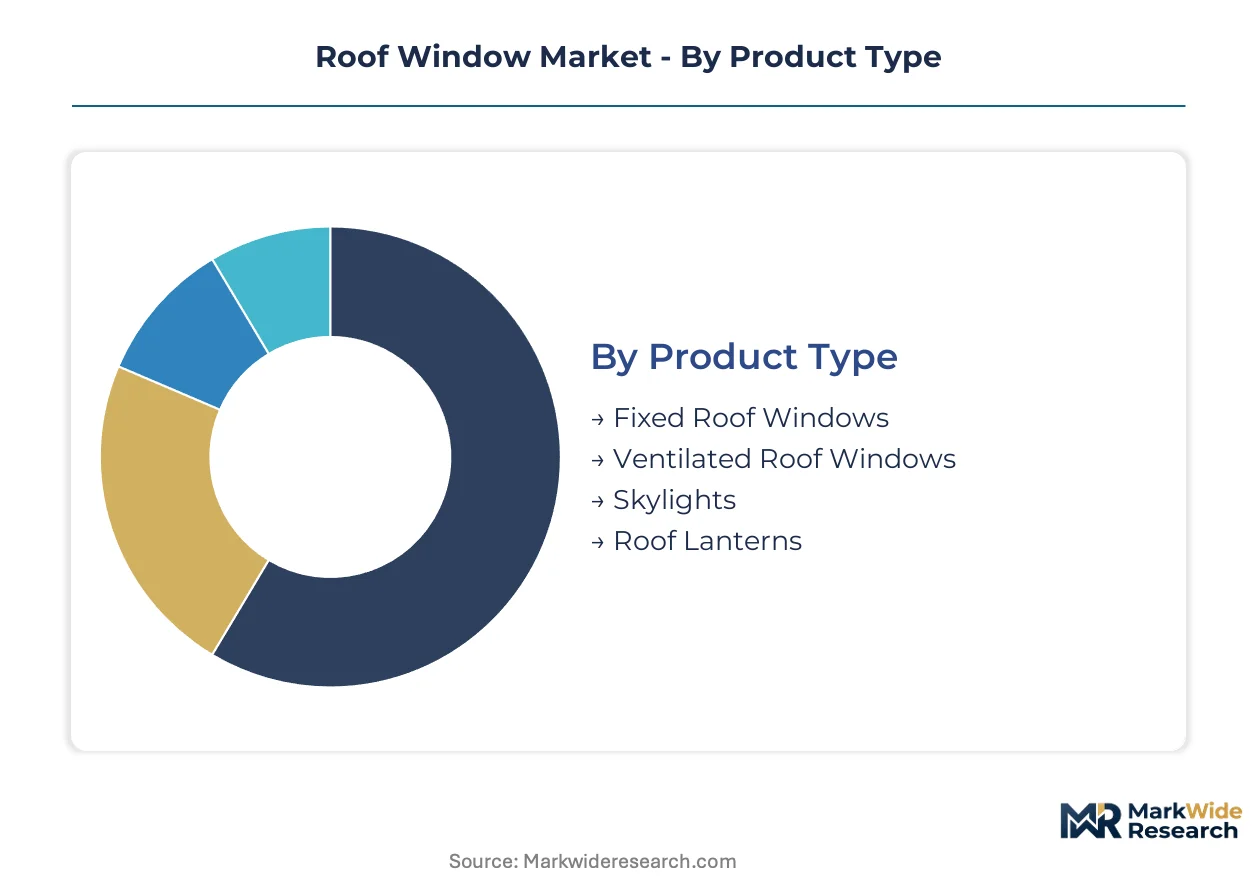
Roof window procurement patterns diverge sharply between new construction and renovation channels, with thermal performance thresholds and installation complexity dicting specification behavior across Northern European housing markets. Material selection and operability features further stratify demand between premium passive-house developments and cost-sensitive retrofit segments.
Product Type:
Fixed units dominate standalone daylighting applications where thermal efficiency outweighs ventilation needs, while operable designs embed into broader building management systems for moisture control.
- Fixed Roof Windows:Sealed glazing units with warm-edge spacers and low-emissivity coatings deliver U-values below 0.8 W/m²K. German multi-family developers specify these for attic conversions where code-compliant daylighting must coexist with strict air-tightness requirements.
- Ventilated Roof Windows:Top-hung or center-pivot designs integrate rain sensors and automated actuators for passive cooling. Denmark and Sweden drive demand through remote-work attic conversions requiring moisture management and natural ventilation compliance.
- Skylights:Curb-mounted or deck-sealed configurations serve flat-roof commercial buildings where pitched-roof windows cannot install.
- Roof Lanterns:Multi-pane glazed structures for heritage residential extensions and hospitality atriums seeking architectural statement daylighting.
Fixed roof windows lead volumes today; ventilated roof windows are gaining share fastest.
Material:
Cost tiers separate premium timber-composite frames from commodity PVC extrusions, with aluminum cladding commanding position in high-performance segments where thermal bridging resistance justifies material investment.
- Wood:Laminated pine or spruce cores with aluminum exterior cladding dominate German and Austrian passive-house specifications. Baltic birch plywood supply constraints from Swedish sawmill capacity limits are compressing availability for mid-tier fabricators.
- PVC:Multi-chamber extrusions with steel reinforcement deliver cost-efficient thermal performance for Polish and Czech mass-housing retrofits. Fakro specializes in cold-climate PVC lines engineered for condensation resistance.
- Aluminum:Thermally broken profiles for commercial skylight systems where structural load requirements exceed timber capacity.
- Fiberglass:Pultruded composite frames for coastal and high-humidity installations requiring dimensional stability.
PVC frames capture the largest installed base; wood-aluminum composites show the steepest expansion trajectory in premium residential.
End User:
Application context determines glazing specification intensity, with residential retrofits prioritizing U-value performance while commercial projects balance daylight autonomy against HVAC load reduction.
- Residential Buildings:Single-family and multi-family attic conversions across Germany, France, and Poland constitute the core volume driver. EU Green Deal renovation wave subsidies tie eligibility to window replacement schedules and energy performance certificates.
- Commercial Buildings:Office and retail daylighting specifications favor electrochromic glazing with automated tint control to eliminate external shading hardware and compress mechanical system sizing.
- Industrial Facilities:Warehousing and manufacturing roof openings for natural illumination with minimal thermal performance requirements.
- Educational Institutions:Schools and universities in Denmark and Sweden specifying ventilated units for classroom air quality compliance.
Residential buildings anchor current demand; commercial buildings are expanding most quickly through net-zero development mandates.
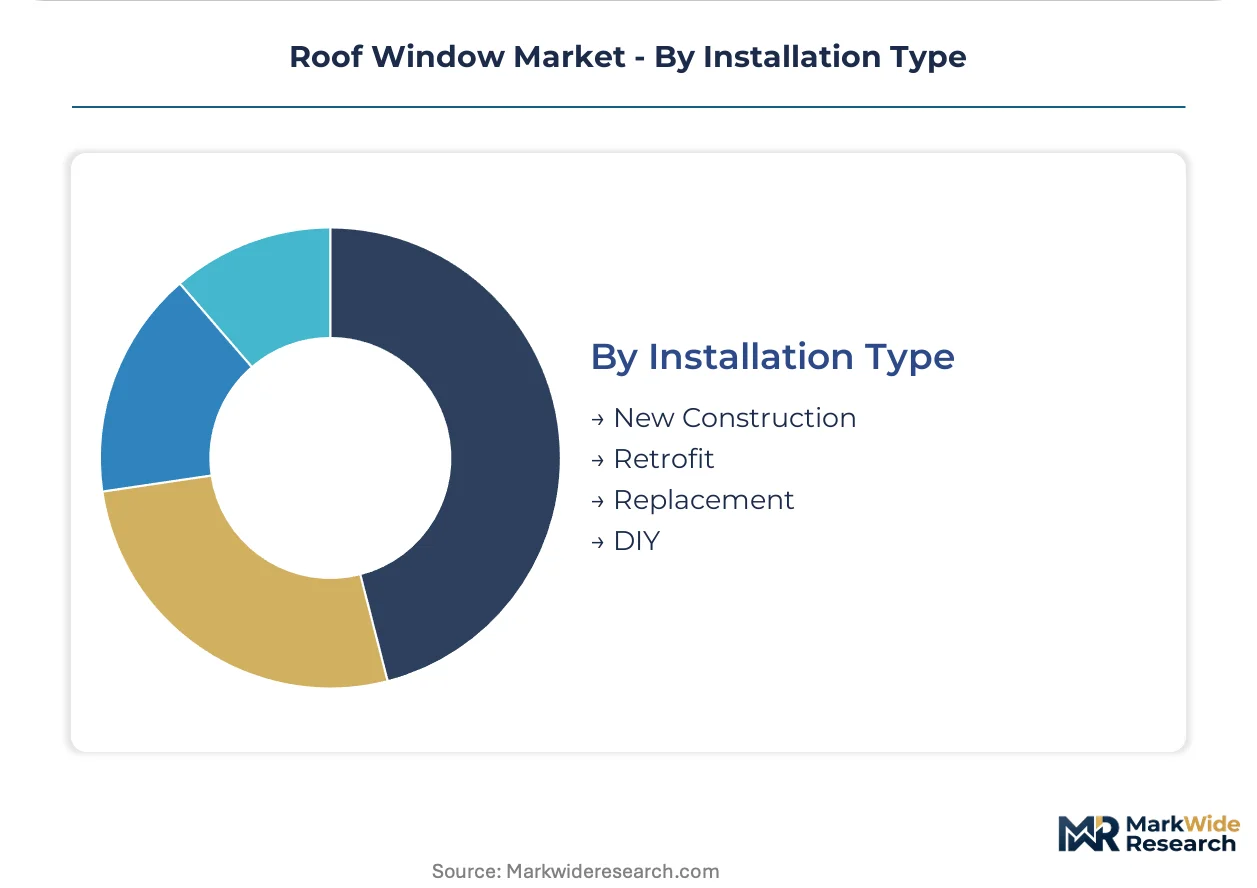
Installation Type:
Customer capability and project timeline urgency fragment procurement channels, with certified installer dependency creating bottlenecks in subsidy-driven retrofit waves.
- New Construction:Builder-direct specifications integrated during framing stage allow standard flashing kits and predictable labor sequencing. CE marking under EU Construction Products Regulation governs structural load and thermal transmittance compliance.
- Retrofit:Attic conversion projects in underrenovated Silesia and Greater Poland housing stock require custom flashing for non-standard 1970s roof pitches, extending timelines.
- Replacement:Single-unit swap-outs driven by failure or energy code upgrades, constrained by Germany's fragmented guild-certified installer network.
- DIY:Online configurators with photorealistic visualization capture research-phase homeowners in Sweden and Norway, compressing traditional distributor margins.
New construction maintains volume leadership; retrofit channels are climbing the fastest as renovation wave deadlines concentrate project filings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting production capacity toward Poland and Czechia as German energy codes tighten, creating a compliance-cost gap that favors cross-border manufacturing while preserving CE-marked access to high-value Northern European markets.
Germany
Attic conversion permits in Bavaria and North Rhine-Westphalia surged following remote-work permanence, with multi-family developers specifying triple-glazed units for code-compliant daylighting. The country's national building energy code (GEG) mandates U-values below 0.8 W/m²K for roof windows in new construction, filtering imports from non-EU suppliers. Stuttgart and Munich housing clusters are driving demand for aluminum-clad wood frames in passive-house developments.
Denmark
Renovation wave subsidies compressed replacement cycles across Copenhagen and Aarhus housing stock, with homeowners prioritizing ventilated units for moisture management. The 2025 building code revision layers stricter thermal transmittance thresholds that accelerate淘汰 of single-glazed legacy units. Odense fabricators are retooling extrusion lines to meet these specifications ahead of enforcement deadlines.
Poland
Underrenovated single-family homes in Silesia and Greater Poland present volume potential as national energy performance certificates tighten resale requirements. EU Green Deal renovation subsidies tie eligibility to window replacement schedules, concentrating project filings in Warsaw and Kraków metropolitan areas. Poznań-based fabricators are expanding triple-glaze production lines to capture cross-border demand from Germany.
Sweden
Remote-work attic conversions in Stockholm and Gothenburg drive specification of automated ventilated roof windows with rain sensors and building management integration. The country's national building code (BBR) mandates daylighting compliance for residential retrofits, creating installer bottlenecks in subsidy-driven project waves. Malmö housing clusters are pioneering smart-home integration with electrochromic glazing for HVAC load reduction.
France
Heritage residential extensions in Île-de-France and Provence-Alpes-Côte d'Azur favor roof lanterns for architectural statement daylighting, while mass-housing retrofits concentrate in Hauts-de-France. The EU Green Deal's national renovation wave program ties public subsidy eligibility to energy performance certificates, accelerating replacement of 1970s-era single-glazed units. Lyon fabricators are developing custom flashing systems for non-standard roof pitches prevalent in post-war housing stock.
Roof Window Market Vendor Landscape
Nordic producers anchor the premium tier with integrated supply chains controlling distribution across Northern European markets; Central European specialists hold cost-competitive positions through PVC and wood-composite lines engineered for cold-climate performance. The vendor base stratifies across three archetypes: timber-frame fabricators with captive forestry assets, extrusion specialists leveraging polymer chemistry, and hardware-integrated system providers extending product functionality. Consolidation pressure is accelerating as mid-tier suppliers absorb R&D costs for triple-glaze compliance, while strategic partnerships between fabricators and certified installer networks defend channel access.
Among Denmark-based manufacturers, Velux occupies a position exemplifying integrated supply chain control across Nordic distribution. Polish fabricator Fakro represents the cold-climate specialization archetype through PVC and wood-composite engineering. German hardware provider Roto anchors the system-integration tier with tilt-turn mechanisms that extend roof window functionality. These three entities illustrate how geographic origin and structural positioning map to distinct competitive vectors in a market where regulatory compliance and installer certification create defensive moats.
| Leading Market Players |
|---|
| Keylite |
| OKPOL |
| Velux |
| Sunsquare |
| Dakea |
| Fakro |
| Lamilux |
| Faelux |
| Roto |
| Others |
Supply Flow & Price Mechanics
Certified roof window installers in Germany's fragmented guild system anchor labor-cost differentials that widen pricing-tier spreads between premium aluminum-clad timber frames and commodity PVC extrusions. Baltic birch plywood supply constraints from Swedish sawmill capacity limits and energy-intensive aluminum smelter operations compress margins for mid-tier fabricators unable to pass input volatility through to subsidy-sensitive retrofit buyers.
Pricing Analysis
Distributor margin layers separate factory gate from installed price, with installer markup capturing 35-40 percent of final project cost in Denmark and Sweden where certified labor scarcity concentrates channel power. Three-tier pricing structure across premium, standard, and economy levels stratifies by glazing specification and frame material, with triple-pane warm-edge units commanding position in German passive-house developments while Polish mass-housing retrofits gravitate toward steel-reinforced PVC. Cost compression in the economy tier is intensifying because Poznań-based fabricators are expanding triple-glaze capacity ahead of installer absorption rates. Residential retrofit buyers in Silesia and Greater Poland exhibit highest price sensitivity, while Austrian commercial developers specifying electrochromic glazing show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Swedish sawmill capacity for Baltic birch plywood core material, where environmental permitting constraints limit expansion response to demand spikes. Manufacturing concentrates in Poland, Czechia, and Denmark, with Polish extrusion specialists feeding cross-border demand into Germany under CE marking harmonization. Raw material draws from Norwegian aluminum smelters, German glass coaters, and Finnish timber suppliers. Tariff exposure on extruded aluminum frame cladding from energy-intensive EU smelters presents structural risk as carbon border adjustments phase in. Distribution runs through builder-direct channels for new construction and fragmented certified installer networks for retrofit, with online configurators compressing traditional distributor margins in Nordic urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roof window market margins are expanding through premium-tier shift toward smart-integrated ventilated units with automated controls and building management system compatibility, while triple-glaze standardization in economy tiers captures volume from compressed replacement cycles under EU Green Deal renovation mandates.
For Market Incumbents: Acquire certified installer network capacity in Germany and Denmark to lock channel access against emerging PVC specialists from Poland. Backward integration into captive Baltic birch plywood supply from Swedish forestry assets defends margin position against sawmill capacity constraints. Invest in automated actuator and rain sensor R&D to extend functionality differentiation as electrochromic glazing commoditizes daylight control features. For New Entrants and Emerging Players: Capture underrenovated single-family housing stock in Silesia and Greater Poland where national energy performance certificate tightening concentrates retrofit filings ahead of subsidy deadlines. Flat-roof commercial segments in France and the Netherlands present white-space opportunity as modular skylight systems displace pitched-roof windows in low-slope daylighting specifications. Partner with smart home platform providers for building management system integration rather than competing on hardware alone. For Investors and Strategic Acquirers: Timber-frame fabricators with captive forestry assets are the most active acquirer in this space, consolidating mid-tier extrusion specialists unable to absorb triple-glaze R&D costs. Target acquisition archetype: Polish or Czech fabricators with CE-marked production capacity and underutilized extrusion lines. Watch installer certification pipeline velocity in Germany as inflection indicator for demand absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Glaze Production Line Expansion | Polish fabricators retool to meet Denmark's 2025 U-value thresholds ahead of enforcement. |
| Certified Installer Network Acquisition | Channel control in Germany's fragmented guild system locks retrofit subsidy flow access. |
| Smart Home Platform Integration | Austrian passive-house developers specify automated ventilation controls for HVAC load reduction. |
| Backward Integration into Timber Supply | Swedish sawmill capacity constraints favor captive Baltic birch plywood sourcing. |
| Electrochromic Glazing Partnership | German multi-family developers eliminate external shading hardware through tint-adjustable units. |
Methodological Framework
Bottom-up residential and commercial construction modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with roof window fabricators, certified installer guild representatives, building energy code officials in Denmark and Germany, and multi-family development procurement managers combined with secondary validation from EU Construction Products Regulation filings, national building code revision documents, and forestry industry capacity reports. Trade flow data from Eurostat and customs records triangulate production location against destination market demand.
Input-output matrices map glazing specification intensity, frame material selection, and installation channel penetration across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-use application, and installation context. CAGRs derive from replacement cycle compression analysis under EU Green Deal renovation wave deadlines and attic conversion permit velocity in remote-work housing clusters. Industry-specific forecast inputs incorporate CE marking compliance cost trajectories and installer certification pipeline capacity constraints.
Regulatory enforcement delays, aluminum and timber input price volatility, and installer training pipeline bottlenecks are the dominant revision risks that could compress or extend projected replacement cycle timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Roofing Shingles Market