
 Construction Safety Net Market | 2026-2036
Construction Safety Net Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Safety Net Market Analytics
OSHA's updated fall-protection standards for construction sites is expanding the cost-of-entry calculus for safety-net suppliers across North America. Guardian Fall Protection leverages its vertical integration into raw material sourcing to sustain margin stability amid polyester price swings. Carl Stahl GmbH anchors its competitive position through specialized steel-wire mesh systems for heavy industrial applications. MSA Safety differentiates via R&D intensity in flame-resistant netting formulations for energy-sector worksites.
Construction safety nets are engineered textile barriers, typically fabricated from high-density polyethylene or knotted nylon cord with mesh apertures ranging from 2 to 4.5 inches, designed to arrest personnel falls and contain debris at elevated worksites. The primary industrial purpose centers on protecting workers and pedestrians from fall hazards and falling objects during building erection, demolition, and facade maintenance operations. Fall protection nets command the largest share of product-type revenue, while debris nets represent the fastest-expanding category as urban density intensifies and zero-debris policies proliferate. Polyethylene dominates material volumes due to its UV resistance and cost efficiency, though polyester gains ground in premium segments requiring higher tensile strength and chemical resistance.
OSHA regulations in the United States, the EU's Construction Products Regulation with CE marking requirements, and China's GB standards administered by SAMR collectively shape product certification pathways and market access conditions for manufacturers. Compliance with these frameworks determines which suppliers can bid on government-funded infrastructure projects and commercial developments. Stakeholders must monitor evolving municipal ordinances in high-growth construction corridors and align certification portfolios accordingly.
Market Dynamics
OSHA enforcement intensity around fall-protection compliance is compressing the operational latitude of construction contractors across high-rise developments, forcing systematic adoption of certified barrier systems and reshaping supplier qualification criteria.
Growth Catalysts
- Polyethylene UV-stabilization advances:Enhanced polymer formulations extend service life in sun-exposed scaffolding applications, reducing replacement frequency and total cost of ownership for contractors managing multi-year infrastructure builds.
- China's GB standard mandates:Municipal governments in urban infrastructure corridors require barrier netting for all high-rise scaffolding, creating volume pull through state-funded residential and commercial tower construction.
- Zero-debris policy proliferation:Dense urban districts in Singapore, Dubai, and London impose strict falling-object containment rules, accelerating specification of debris-rated mesh systems for facade maintenance and demolition work.
Market Restraints
- Polyester feedstock volatility:Crude oil price swings transmit directly to high-tenacity fiber costs, squeezing margin stability for manufacturers lacking backward integration into polymer production.
- Regional supply concentration:Knotted nylon cord production clusters in Zhejiang Province, creating single-source vulnerability for European and North American distributors seeking just-in-time delivery.
- Steel-wire mesh weight penalty:Heavy industrial applications face logistical constraints from transport costs and crane capacity limits, restricting deployment flexibility compared to synthetic alternatives.
Strategic Opportunities
- India's urban corridor buildout:Smart city initiatives in Mumbai, Bangalore, and Hyderabad generate demand for certified fall-protection systems as high-rise residential construction accelerates.
- Flame-resistant energy-sector formulations:Offshore platform maintenance and petrochemical facility turnarounds require specialized netting meeting NFPA 701 standards, commanding premium pricing.
- Digital procurement platforms:Construction material marketplaces enable direct manufacturer-to-contractor relationships, disintermediating traditional distributor networks and capturing margin.
Industry Challenges
- Certification timeline compression:CE marking under the EU Construction Products Regulation requires extensive testing documentation, delaying market entry for new product variants by six to eighteen months.
- Installation technician scarcity:Qualified riggers capable of proper tensioning and anchor-point verification command wage premiums, constraining deployment velocity during peak construction seasons.
- Legacy system interoperability:Modular netting systems must interface with existing scaffolding from multiple manufacturers, complicating specification and increasing engineering review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Safety Net Market |
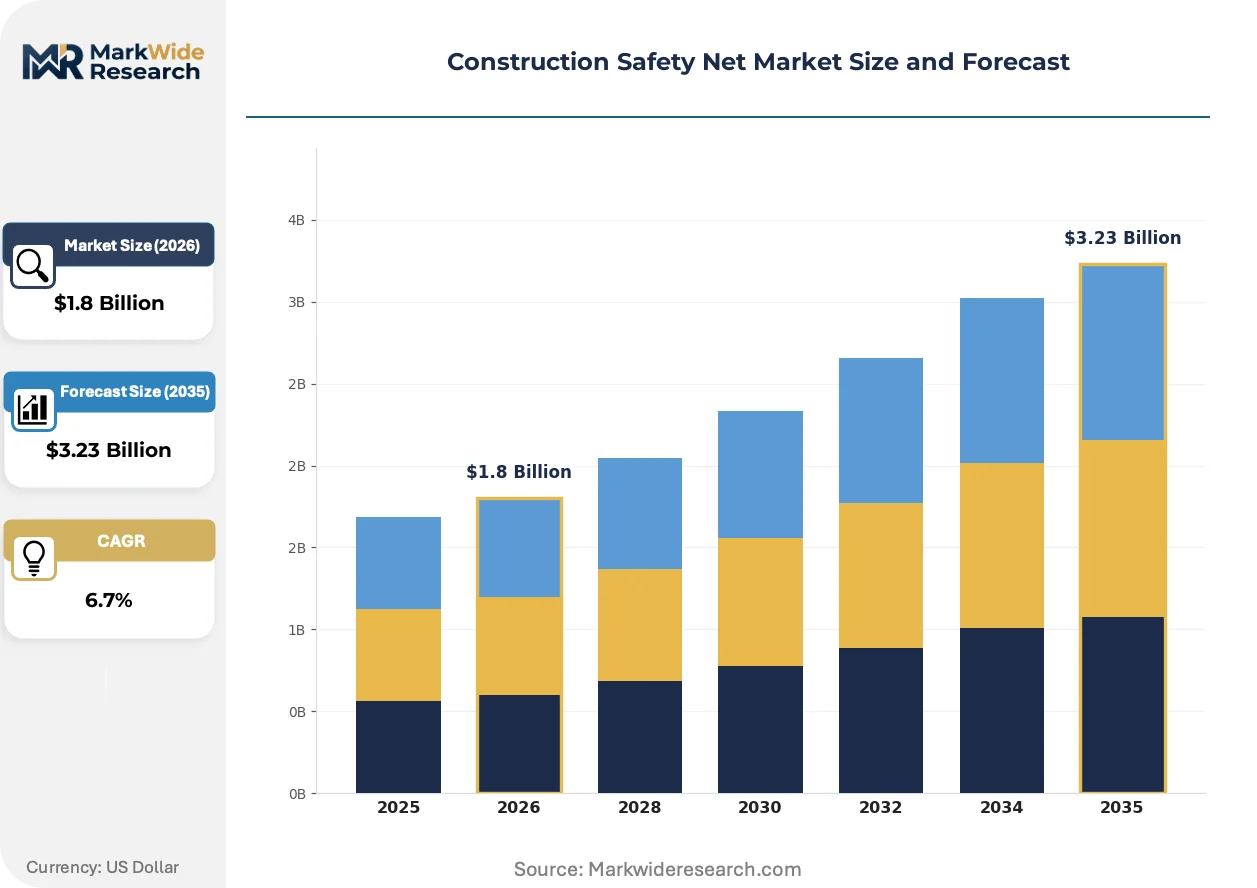
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Debris Nets, Safety Mesh, Fall Protection Nets, Barrier Nets Material: Polyethylene, Nylon, Polyester, PVC Application: Commercial Construction, Residential Projects, Industrial Worksites, Infrastructure Development End User: Contractors, Government Agencies, Real Estate Developers, Construction Firms |
| Companies Covered | Guardian Fall Protection, Pure Safety Group, 3M, Carl Stahl GmbH, Protecta Screen Limited, MSA Safety, FallTech, Diamond Nets, Honeywell Miller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Safety Net Market Evolving Landscape
Material science breakthroughs and regulatory digitization are converging to redefine performance benchmarks and compliance workflows across the construction safety net value chain.
High-modulus polyethylene (HMPE) fiber is absorbing load-bearing functions previously reserved for steel-wire mesh in heavy industrial applications. Offshore energy contractors in the North Sea and Gulf of Mexico specify HMPE debris barriers for platform maintenance, drawn by weight reductions exceeding sixty percent versus traditional metal systems. The technology is absorbing market share in corrosive marine environments where synthetic longevity outweighs upfront cost premiums.
REACH chemical registration requirements in the European Union now mandate full substance disclosure for polymer additives and UV stabilizers used in construction textiles. Manufacturers must requalify legacy formulations or reformulate to meet SVHC screening protocols, elevating R&D overhead for suppliers serving EU infrastructure projects. Fall-protection netting with full material passports commands preferential treatment in public procurement tenders across Germany, France, and the Netherlands.
Specification decisions increasingly migrate from procurement departments to site safety officers with direct liability exposure. Large general contractors in Australia and Canada empower project-level safety managers to select certified netting systems based on documented incident-prevention performance rather than headline price. This behavioral shift concentrates volume with suppliers maintaining searchable digital certification libraries and rapid technical response capabilities.
Construction Safety Net Market Segmentation
Construction safety net procurement decisions fragment across multiple technical and commercial dimensions. Specification requirements diverge sharply between high-rise commercial towers and heavy industrial sites, while material selection hinges on UV exposure, load-bearing demands, and regulatory compliance costs.
Product Type:
Supply concentration for knotted cord systems clusters in Zhejiang Province, while woven mesh manufacturing disperses across Southeast Asian textile hubs.
- Debris Nets:Woven high-density polyethylene barriers with 2-4.5 inch mesh apertures designed to arrest falling tools and construction materials. Demand concentrates in Singapore, Dubai, and London where municipal zero-debris ordinances mandate facade containment during high-rise maintenance and demolition operations.
- Fall Protection Nets:Knotted nylon or HMPE cord systems engineered to arrest personnel falls per OSHA and EN 1263-1 energy absorption standards. Contractors on US commercial high-rises and Chinese state-funded residential towers specify these systems under tightening enforcement regimes.
- Safety Mesh:Lightweight woven barriers for pedestrian protection and boundary demarcation at ground level. Urban infrastructure corridors in India and Brazil deploy these for sidewalk shielding during metro construction.
- Barrier Nets:General-purpose containment systems for material storage zones and perimeter security. Standard specifications dominate procurement for temporary site enclosures across mid-market construction segments.
Fall protection nets absorb the bulk of installed capacity; debris nets are expanding most quickly.
Material:
Cost tier differentiation separates commodity polyethylene volumes from premium synthetic fibers serving specialized industrial applications.
- Polyethylene:UV-stabilized high-density formulations dominate volume due to cost efficiency and weather resistance. Multi-year infrastructure builds in sun-exposed climates favor this material for reduced replacement frequency and lower total cost of ownership.
- Polyester:High-tenacity fiber with superior tensile strength and chemical resistance for premium segments. European energy-sector worksites and offshore platforms specify polyester where synthetic longevity outweighs upfront cost premiums.
- Nylon:Knotted cord systems with high elasticity for personnel fall arrest. Zhejiang Province production clusters serve global demand for traditional construction netting applications.
- PVC:Coated formulations for flame-resistant and chemical-resistant barriers. NFPA 701-compliant specifications command premium pricing in petrochemical facility maintenance and offshore platform turnarounds.
Polyethylene commands the widest deployment base; polyester is climbing the fastest on energy-sector specification growth.
Application:
Customer type segmentation reveals divergent procurement authority between project-level safety officers and centralized purchasing departments.
- Commercial Construction:High-rise office and retail developments requiring certified fall-protection and debris containment systems. OSHA enforcement intensity in the United States and GB standard mandates in China drive systematic adoption of barrier netting across urban tower construction.
- Infrastructure Development:State-funded transportation, energy, and utility projects with extended construction timelines. Bridge maintenance and highway expansion works in Germany, France, and the Netherlands specify REACH-compliant netting with full material passports.
- Industrial Worksites:Heavy manufacturing, petrochemical, and offshore energy facilities requiring specialized load-bearing and flame-resistant barriers. HMPE fiber is displacing steel-wire mesh in North Sea and Gulf of Mexico platform maintenance for weight reduction exceeding sixty percent.
- Residential Projects:Mid-rise and high-rise housing construction with standardized safety requirements. Municipal mandates in China's urban corridors and India's smart city initiatives generate volume pull through state-funded residential tower builds.
Commercial construction absorbs the bulk of installed capacity; infrastructure development is gaining share fastest on public procurement tender growth.
End User:
Maturity gradients separate established specification relationships in developed markets from emerging procurement digitization in high-growth construction corridors.
- Contractors:General and specialty contractors with direct liability exposure for site safety compliance. Australian and Canadian project-level safety managers increasingly select certified netting based on documented incident-prevention performance rather than headline price.
- Construction Firms:Large integrated builders with centralized procurement and standardized safety protocols. Digital certification libraries and rapid technical response capabilities concentrate volume with preferred supplier relationships.
- Government Agencies:Public infrastructure authorities with mandatory compliance frameworks and transparent tender processes. EU Construction Products Regulation CE marking and China's SAMR-administered GB standards determine qualified bidder pools.
- Real Estate Developers:Private sector project sponsors specifying safety systems through design-build contracts. Risk transfer mechanisms place net procurement authority with contractor partners in most developed markets.
Contractors absorb the bulk of installed capacity; government agencies are expanding most quickly on infrastructure stimulus program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's urban infrastructure corridors concentrate demand volume through state-mandated barrier netting requirements, while the United States and Germany anchor premium specification markets driven by tightening enforcement regimes.
China
High-rise residential tower construction in Shanghai, Shenzhen, and Chengdu drives polyethylene debris net procurement under SAMR-administered GB standards. Municipal governments mandate barrier netting for all scaffolding above six stories, creating volume pull through state-funded smart city initiatives. Production clusters in Zhejiang Province supply knotted nylon cord systems to domestic contractors and export markets.
United States
Commercial high-rise developments in New York, Chicago, and Los Angeles expand fall-protection net deployment as OSHA enforcement intensifies. Updated fall-protection standards compress contractor operational latitude, forcing systematic adoption of certified barrier systems. Guardian Fall Protection anchors its position through captive supply of raw materials amid polyester price volatility.
Germany
Infrastructure maintenance contracts across the Rhine-Ruhr and Bavarian industrial corridors specify REACH-compliant netting with full material passports. The EU Construction Products Regulation CE marking requirement determines qualified bidder pools for public procurement tenders. Carl Stahl GmbH holds position through specialized steel-wire mesh systems for heavy industrial applications.
India
Smart city initiatives in Mumbai, Bangalore, and Hyderabad accelerate certified fall-protection system demand as high-rise residential construction expands. Central government infrastructure stimulus programs channel funding toward metro construction and highway expansion works. MSA Safety differentiates through R&D intensity in flame-resistant formulations targeting energy-sector worksites.
United Arab Emirates
Zero-debris policies in Dubai and Abu Dhabi mandate facade containment netting for high-rise maintenance and demolition operations. Mega-project developments including NEOM generate specification pull for premium debris-rated mesh systems. Regional distributors face logistics constraints from knotted nylon cord supply concentration in East Asian production hubs.
Construction Safety Net Market Competitive Landscape
Chinese producers anchor volume-tier supply through Zhejiang Province manufacturing clusters; German and US specialists hold premium positions via certification intensity and material science capabilities. The vendor base splits between scale-driven synthetic fiber fabricators and precision-engineered metal-mesh specialists. Three archetypes dominate: vertically integrated polymer producers, R&D-intensive formulation houses, and project-specific system integrators. Competitive moves concentrate on backward integration into raw material sourcing and rapid certification library expansion for public procurement eligibility.
Within the premium-tier vector, Carl Stahl GmbH and MSA Safety exemplify specialized engineering positions, while Guardian Fall Protection occupies a scale-driven archetype with upstream control over supply chains. These three anchors represent distinct strategic postures: German precision manufacturing, diversified safety equipment portfolios, and North American vertical integration.
| Leading Market Players |
|---|
| Guardian Fall Protection |
| Pure Safety Group |
| 3M |
| Carl Stahl GmbH |
| Protecta Screen Limited |
| MSA Safety |
| FallTech |
| Diamond Nets |
| Honeywell Miller |
| Others |
Value Network & Pricing Analysis
Qualified riggers capable of proper tensioning and anchor-point verification cluster in Zhejiang Province and the US Gulf Coast, where labor-cost differentials of forty to sixty percent separate premium-certified installation crews from standard-tier contractors. This workforce concentration compresses margins at the economy tier while sustaining pricing power for suppliers bundling certified installation with product sales.
Pricing Analysis
Volume-mass polyethylene debris nets trade on thin margins in Chinese state-funded residential towers, while margin-rich HMPE formulations for offshore energy command premiums exceeding threefold on synthetic longevity and weight reduction. Price differentiation centers on certification grade—CE marking under the EU Construction Products Regulation and OSHA compliance tiers—and geographic delivery cost to remote industrial sites. Pricing pressure stems from polyester feedstock volatility transmitting directly to high-tenacity fiber costs. Government agencies exhibit lowest price sensitivity due to mandatory compliance frameworks; mid-market residential contractors in India and Brazil show highest sensitivity, prioritizing headline cost over total cost of ownership.
Supply Chain Analysis
Domestic-content mandates in India's smart city initiatives and China's GB standard enforcement are reshaping sourcing patterns, favoring local manufacturers with in-house polymer production over import-dependent distributors. Raw material flows draw from Saudi Arabian petrochemical feedstocks for polyethylene, Zhejiang Province for knotted nylon cord, and German specialty chemical houses for flame-resistant coatings. Single-source vulnerability concentrates in East Asian cord production clusters, exposing European and North American distributors to logistics chokepoints. Distribution runs through construction material marketplaces disintermediating traditional distributor networks, alongside direct manufacturer-to-contractor relationships for large infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
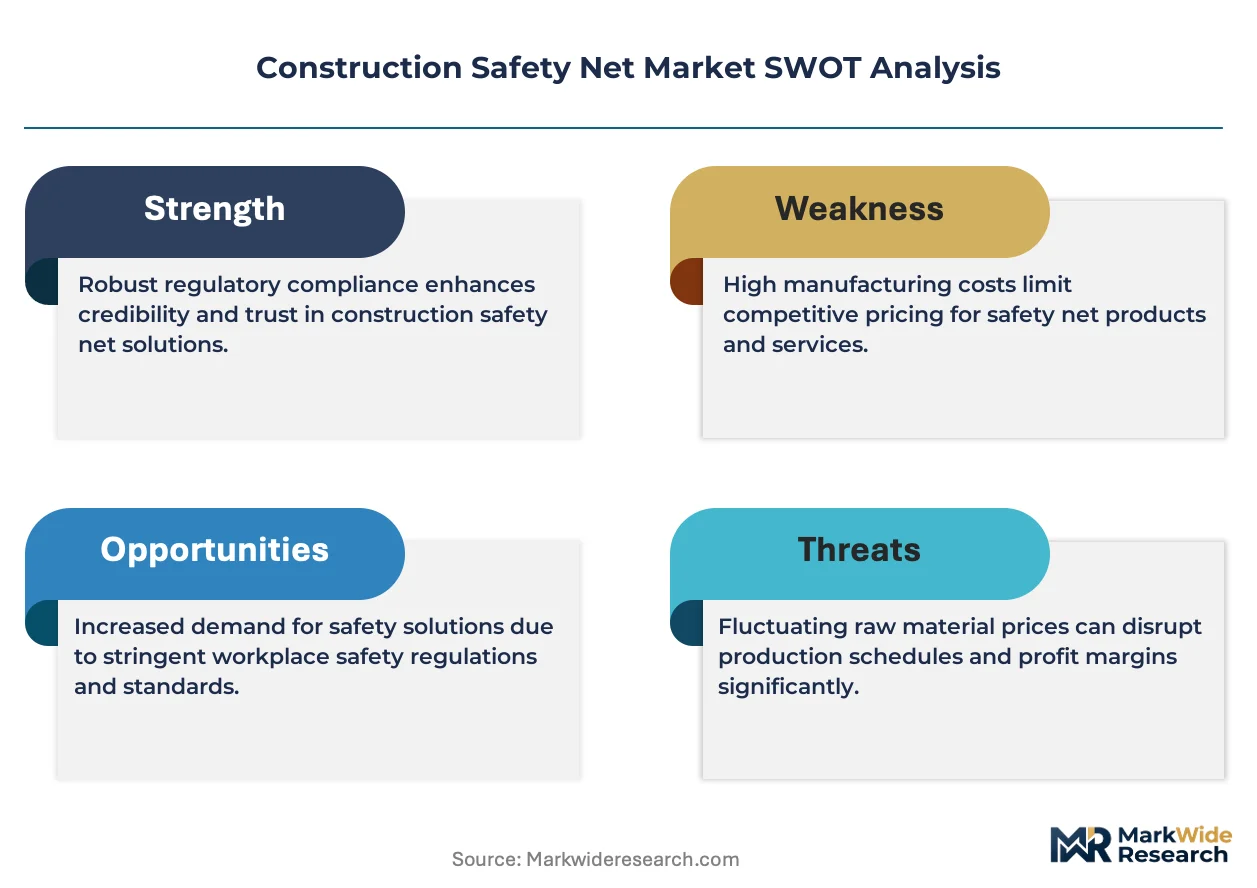
This market functions as a cost-of-compliance arena where OSHA's updated fall-protection standards and the EU Construction Products Regulation CE marking requirements erect barrier-to-entry moats. Suppliers lacking certification investment or rapid technical response capabilities face systematic exclusion from government-funded infrastructure tenders.
For Market Incumbents: To counter polyester feedstock volatility squeezing margin stability, secure backward integration into polymer production or captive supply agreements with Saudi Arabian petrochemical producers. Expand digital certification libraries to meet specification decisions migrating from procurement departments to project-level safety officers in Australia and Canada.
For New Entrants and Emerging Players: Enter via India's urban corridor buildout where smart city initiatives in Mumbai, Bangalore, and Hyderabad generate demand outpacing certified supplier capacity. Target flame-resistant energy-sector formulations for offshore platform maintenance, where NFPA 701 compliance gaps create specification white space. Pursue direct manufacturer-to-contractor relationships through construction material marketplaces to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive formulation houses given REACH chemical registration requirements elevating overhead for legacy formulation requalification. Long-term viability favors suppliers with demonstrated certification velocity and material science capabilities spanning HMPE fiber development. Watch for inflection signals in municipal zero-debris ordinance adoption across dense urban districts, accelerating debris-rated mesh system specification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive supply of polyethylene raw materials insulates margin stability from crude oil price transmission. |
| Digital Certification Library Expansion | Searchable compliance documentation meets specification authority shifts toward project-level safety managers. |
| HMPE Fiber R&D Investment | High-modulus polyethylene formulations displace steel-wire mesh in North Sea and Gulf of Mexico platform maintenance. |
| Direct Marketplace Distribution | Manufacturer-to-contractor relationships through construction material platforms capture margin from traditional distributors. |
| REACH-Compliant Formulation Requalification | Full material passports command preferential treatment in German, French, and Dutch public procurement tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with rigging contractors, site safety officers, scaffolding system integrators, and municipal procurement directors. OSHA enforcement databases, EU Construction Products Regulation CE marking registries, SAMR GB standard filings, and import-export statistics from Zhejiang Province textile hubs provided demand-side validation. Bottom-up project pipeline analysis across commercial high-rise developments and top-down infrastructure stimulus tracking were triangulated for volume estimation.
Reconciliation of customs shipment records, polymer producer output disclosures, and contractor purchase order data informed the analytical framework. Segmentation dimensions spanned product type, material grade, application vertical, and end-user procurement authority across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory enforcement intensity and urban construction density metrics. Industry-specific inputs included knotted cord capacity utilization rates in Zhejiang Province and REACH chemical registration timelines for UV stabilizer formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt OSHA enforcement shifts or polyester feedstock price spikes. Assumptions include sustained municipal mandate proliferation in China's urban corridors and stable CE marking processing timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Tool Storage Market
Construction and Engineering
Entrenching Tool Market
Construction and Engineering
North America Welding Equipment Market
Construction and Engineering
Rapid Strength Concrete Market
Construction and Engineering
Gas Cutting Machine Market
Construction and Engineering
Construction Engineering Services Outsourcing Market
Construction and Engineering
Qatar Facade Market
Construction and Engineering
Global Metal Forming Machine Tools Market
Construction and Engineering
North America Luxury Vinyl Tile (LVT) Market
Construction and Engineering
Drill Set Market
Construction and Engineering
North America Air to Water Heat Pump Market
Construction and Engineering
Europe HVAC Equipment Market
Construction and Engineering
Underground Mining Market
Construction and Engineering
Cut-To-Length Line Systems Market
Construction and Engineering
Turkey Commercial Construction Market
Construction and Engineering
Porter Cable Air Compressor Market