
 Modular Process Skid Systems Market | 2026-2036
Modular Process Skid Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Process Skid Systems Market Insights
Gulf Coast fabricators is broadening output of modular process skid systems to serve surging petrochemical and water treatment demand. Fluor Corporation leverages its engineering-procurement-construction heritage to anchor large-scale integrated projects across North America. Sulzer competes through specialized pumping and separation skids for corrosive process environments. Praj Industries dominates biofuel and ethanol processing skids, particularly in emerging markets where distributed plant architecture reduces capital intensity.
Modular process skid systems are self-contained process units mounted on structural steel frames, pre-piped, pre-wired, and factory-tested to pressure ratings typically ranging from 150 to 600 psi before site delivery. These systems compress field construction schedules, reduce labor risk, and enable parallel workstreams between civil infrastructure and process equipment readiness. Process skids command the largest share of fabrication hours due to their complexity in integrating pumps, vessels, heat exchangers, and instrumentation into transportable footprints. Water treatment end users represent the fastest-expanding demand pool as municipalities and industrial operators confront aging infrastructure and stricter discharge mandates. Permanent installations absorb the majority of capital allocation, though temporary configurations gain traction in pilot plants and emergency response scenarios.
EPA effluent limitations under the Clean Water Act shape design specifications for water treatment skids, while ASME Boiler and Pressure Vessel codes govern fabrication standards across North American supply chains. OSHA process safety management requirements influence hazard analysis protocols during factory acceptance testing and site commissioning. Stakeholders must monitor evolving PFAS treatment regulations and carbon intensity accounting rules, as these will redirect R&D spending toward advanced separation technologies and low-emission fabrication methods.
Market Dynamics
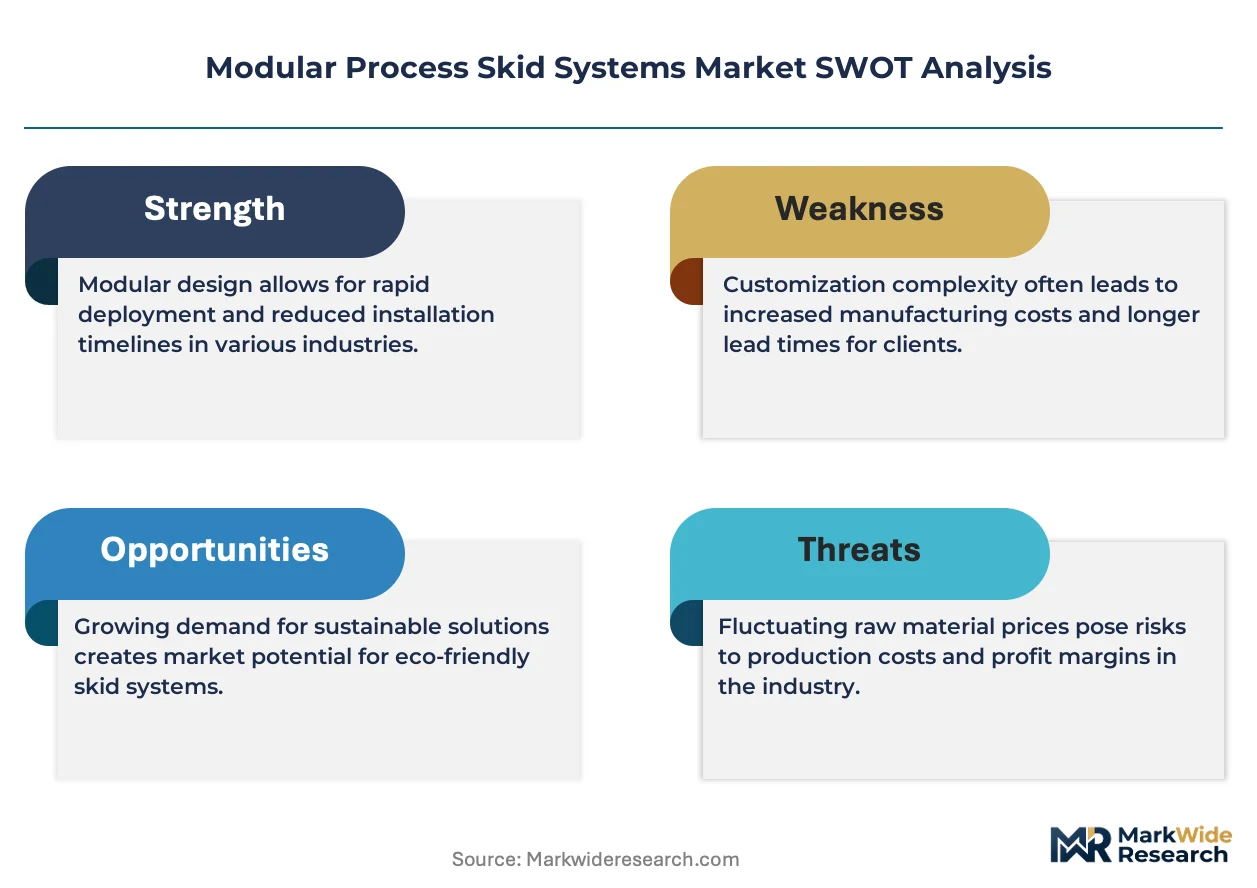
Pre-assembly requirements are compressing project delivery schedules across water treatment and petrochemical infrastructure, forcing fabricators to absorb more engineering risk upfront while municipalities demand plug-and-play architectures that minimize field construction exposure.
Growth Catalysts
- EPA effluent standards:Tightening discharge mandates under the Clean Water Act are compelling municipal operators to accelerate procurement of pre-tested treatment skids that guarantee compliance before site installation.
- Petrochemical cluster concentration:Gulf Coast processing facilities are standardizing on modular architectures to enable parallel civil and mechanical workstreams, reducing capital deployment timelines.
- Plug-and-play plant architecture:Distributed processing models in biofuel and specialty chemical production are displacing stick-built construction with transportable, factory-integrated process units.
Market Restraints
- Specialized alloy input volatility:Duplex stainless steel and superalloy pricing fluctuations directly compress fabrication margins, particularly for corrosive-service separation skids.
- Fabricator geographic concentration:Heavy reliance on Gulf Coast and Midwest US production bases creates hurricane and logistics disruption exposure for time-sensitive project schedules.
- ASME certification bottlenecks:Limited third-party inspection capacity for pressure vessel code compliance extends factory acceptance testing queues, delaying revenue recognition.
Strategic Opportunities
- PFAS treatment regulatory tailwind:Emerging federal and state mandates for per- and polyfluoroalkyl substance removal are opening specification windows for advanced separation skids with membrane and adsorption technologies.
- Carbon intensity accounting integration:Factory-controlled fabrication environments offer measurable emissions advantages over field construction, positioning modular systems for low-carbon procurement preferences.
- Emergency response deployment:Temporary skid configurations for disaster recovery and seasonal capacity augmentation represent underdeveloped demand pools outside permanent infrastructure replacement cycles.
Industry Challenges
- Welding and instrumentation technician scarcity:Factory fabrication of complex process skids requires ASME-certified welders and controls specialists in tight labor markets, constraining output expansion.
- Legacy system integration complexity:Brownfield installations demand custom interface engineering between pre-engineered skids and aging distributed control systems, eroding standardization benefits.
- Factory acceptance testing coordination:Multi-stakeholder witness testing protocols involving end users, EPC contractors, and insurers create scheduling friction and scope creep risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Process Skid Systems Market |
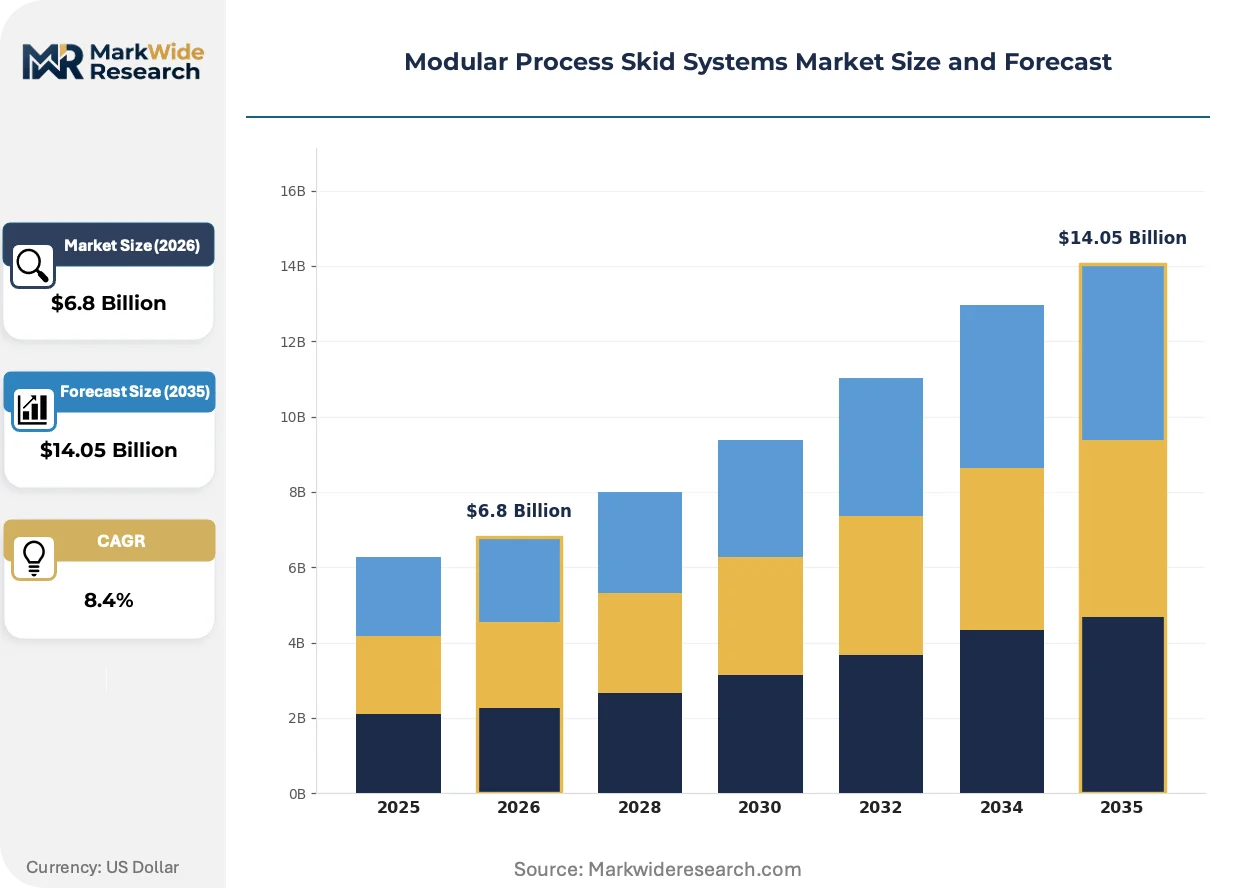
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabrication Skids, Utility Skids, Process Skids, Chemical Skids End User: Oil & Gas, Chemical Processing, Water Treatment, Pharmaceuticals Installation: Onshore, Offshore, Temporary, Permanent Service Type: Design, Manufacturing, Maintenance, Installation |
| Companies Covered | Robinson, H+M Industrial, Donaldson, EPIC Systems, Sulzer, Aquatech, Integrated Flow Solutions, Fluor Corporation, Praj Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Process Skid Systems Market Trends and Innovations
Digital engineering workflows and advanced fabrication techniques are compressing design-to-delivery cycles while regulatory pressure on emissions and effluent quality redefines performance specifications across process industries.
Digital twin integration is expanding into modular skid engineering, enabling virtual commissioning and predictive maintenance protocols before physical delivery. Water treatment operators in the United States are deploying these models to reduce startup risk and accelerate operator training. The technology is expanding into contract structures that tie vendor payments to operational performance milestones rather than mechanical completion.
EPA effluent limitation guidelines under the Clean Water Act are tightening total dissolved solids and nutrient discharge thresholds for industrial facilities. These mandates are forcing retrofit demand across aging municipal infrastructure and driving specification of advanced membrane bioreactor skids. Petrochemical processors on the US Gulf Coast are responding with bundled procurement of treatment and process skids from single-source fabricators to streamline compliance accountability.
Performance-based contracting is displacing traditional equipment purchase models in municipal water treatment procurement. Operators are transferring operational risk to skid vendors through multi-year service agreements tied to effluent quality guarantees. This shift is most visible in California and Texas, where strained technical staffing at public agencies makes outsourced operations attractive despite higher upfront capital commitments.
Modular Process Skid Systems Market Segmentation
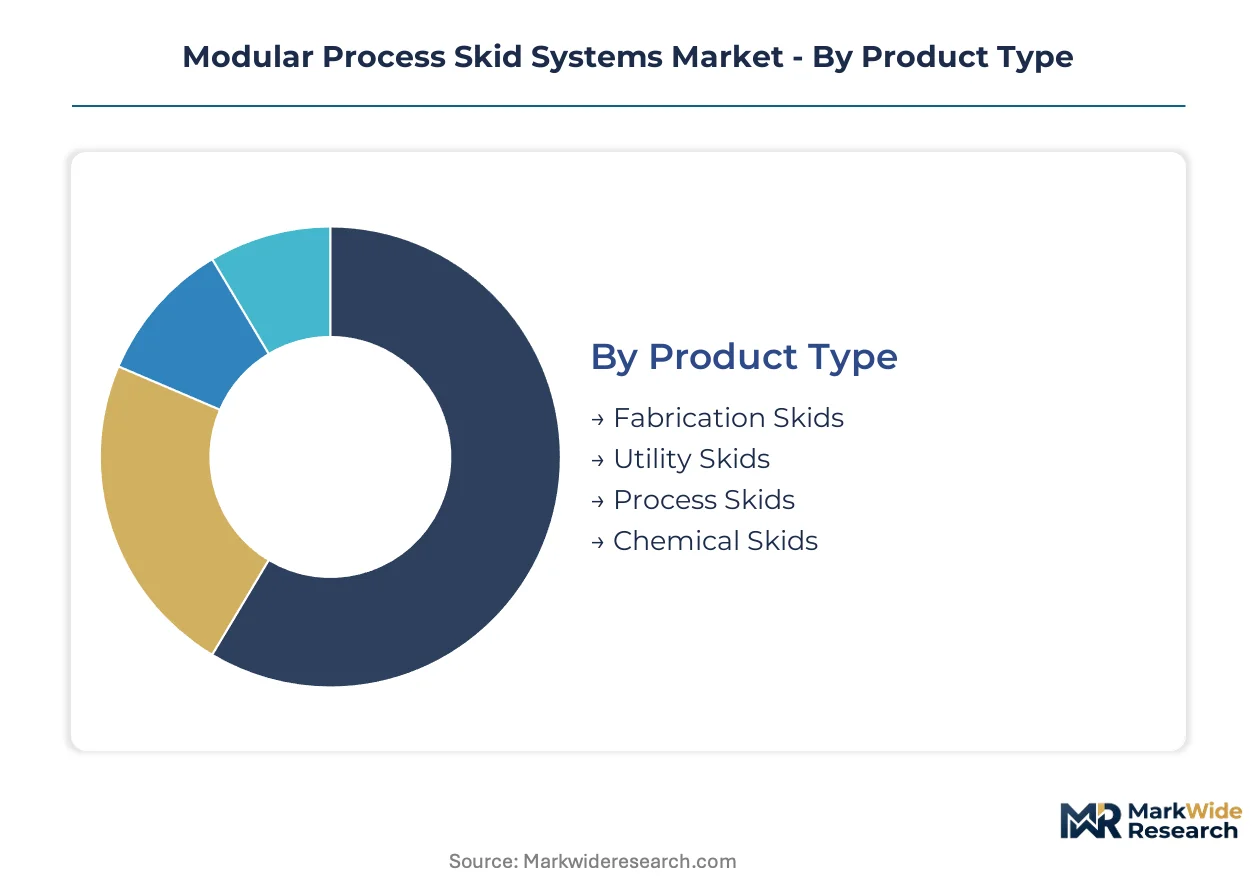
Modular process skid systems fragment across four critical dimensions that dictate engineering complexity, certification burden, and procurement economics. Each segmentation axis reveals distinct margin profiles and competitive dynamics that shape vendor positioning.
Product Type:
ASME BPVC Section VIII certification governs pressure-retaining fabrication skids and process skids, while utility skids face lighter structural code requirements. Chemical skids trigger additional EPA risk management plan obligations for toxic substance containment.
- Process Skids:Complex integration of pumps, vessels, heat exchangers, and instrumentation into transportable footprints. These units command the largest fabrication hour allocations and require full ASME pressure vessel stamping. Gulf Coast petrochemical clusters drive concentrated demand as operators compress field construction schedules.
- Fabrication Skids:Structural steel frames with pre-mounted equipment bases and piping supports, forming the foundational layer of modular architecture. Municipal water treatment facilities in Texas and California are standardizing on these units to accelerate aging infrastructure replacement timelines.
- Utility Skids:Compressed air, nitrogen, and steam generation modules with lower pressure ratings. These units serve as supporting infrastructure across multiple process industries.
- Chemical Skids:Specialized containment systems for corrosive and hazardous substance handling. Duplex stainless steel specifications dominate this segment due to chloride resistance requirements.
Leading the category by volume: Process Skids. Growing fastest: Fabrication Skids.
End User:
Regulatory stringency varies sharply across end-use verticals, with EPA effluent mandates tightening fastest for water treatment while OSHA process safety management dominates chemical processing procurement.
- Water Treatment:Municipal and industrial operators confronting Clean Water Act discharge mandates. EPA effluent limitation guidelines are forcing retrofit demand across aging infrastructure. California and Texas municipalities are transferring operational risk to vendors through performance-based service agreements.
- Oil & Gas:Upstream and midstream operators standardizing on modular architectures for remote field deployment. Permian Basin producers are bundling process and utility skids to reduce capital deployment timelines.
- Chemical Processing:Specialty and commodity chemical manufacturers requiring corrosion-resistant separation systems. Gulf Coast clusters dominate procurement concentration.
- Pharmaceuticals:FDA-validated systems for active pharmaceutical ingredient manufacturing. These skids require 21 CFR Part 11 compliance for electronic records and signatures.
Water Treatment claims the steepest expansion trajectory. Oil & Gas retains the largest installed base.
Installation:
Capital allocation patterns split sharply between permanent infrastructure replacement and temporary capacity augmentation, with distinct logistics and commissioning protocols governing each mode.
- Permanent:Fixed installations absorbing majority capital allocation across water treatment and petrochemical infrastructure. These configurations require full civil foundation integration and extended commissioning protocols.
- Temporary:Deployable units for pilot plants, emergency response, and seasonal capacity augmentation. Hurricane recovery operations on the US Gulf Coast are creating underdeveloped demand pools outside standard replacement cycles.
- Onshore:Land-based installations with standard transportation logistics and crane accessibility.
- Offshore:Platform-mounted systems requiring marine-grade coatings and compact footprints for weight-constrained environments.
Permanent installations dominate capital deployment. Temporary configurations are gaining share fastest in disaster recovery applications.
Service Type:
Vendor business models are shifting from equipment-only transactions toward integrated lifecycle contracts, with performance guarantees reshaping revenue recognition timing.
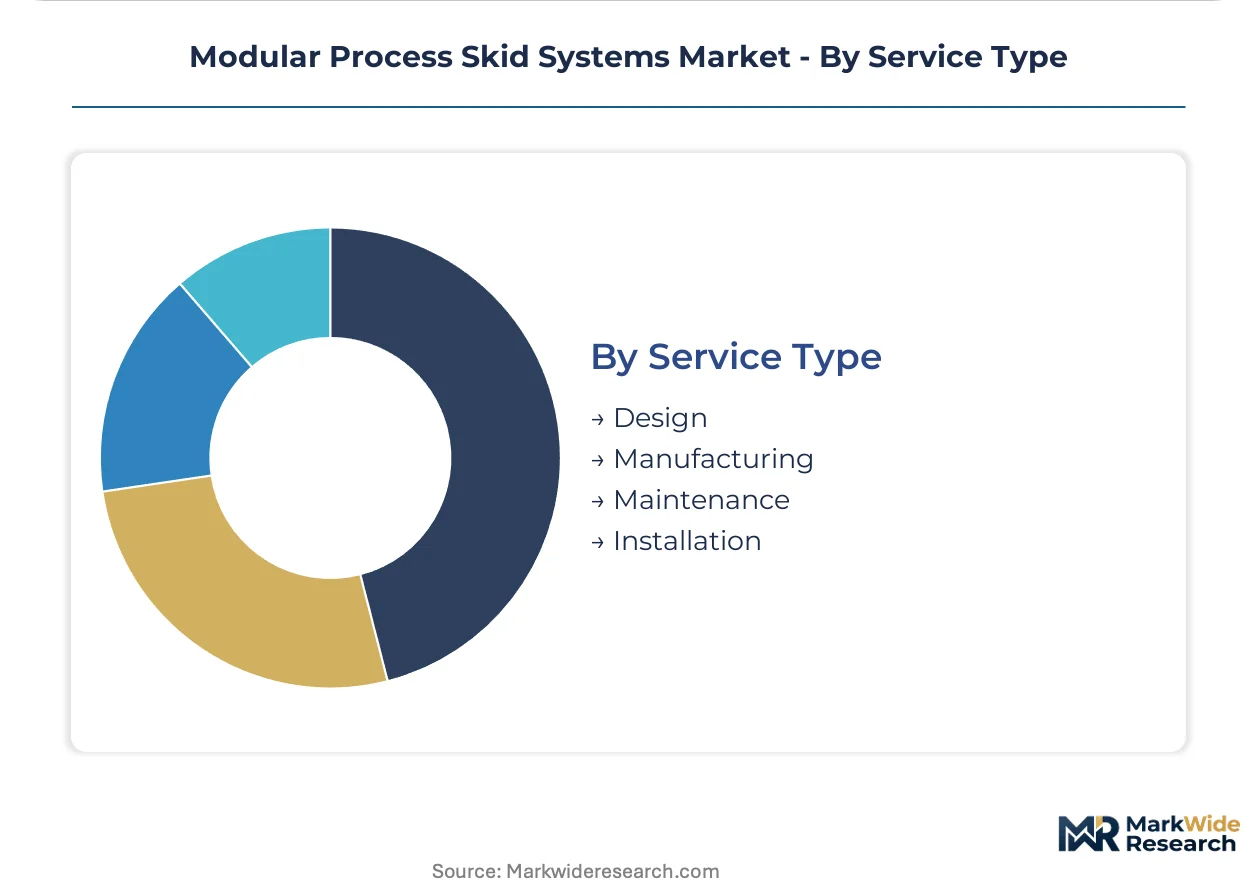
- Manufacturing:Factory-controlled fabrication delivering pre-tested, transportable units. ASME-certified welders and controls specialists constrain output expansion in tight labor markets.
- Design:Front-end engineering for custom skid specifications. Digital twin integration is compressing design-to-delivery cycles across water treatment applications.
- Installation:Site assembly, commissioning, and integration with legacy distributed control systems. Brownfield complexity erodes standardization benefits.
- Maintenance:Multi-year service agreements tied to effluent quality guarantees. California municipalities are outsourcing operations due to strained technical staffing.
Manufacturing captures the largest revenue share. Maintenance contracts are climbing the fastest as performance-based procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy supply chains and petrochemical feedstock corridors anchor demand geography across multiple industrial basins. Fabrication capacity clusters near Gulf Coast petrochemical complexes, Midwest manufacturing belts, and select European process industry hubs. Regulatory stringency and infrastructure replacement cycles create divergent procurement timelines across national markets.
United States
Gulf Coast petrochemical operators are accelerating procurement of pre-assembled process skids to compress capital deployment timelines. EPA effluent limitations under the Clean Water Act are forcing municipal water treatment retrofits across Texas and California municipalities. Houston-Galveston fabricators are expanding output to serve Permian Basin upstream operators bundling process and utility skids.
Germany
REACH compliance obligations and the EU Green Deal are redirecting specification requirements toward low-carbon fabrication methods for chemical processing skids. The country's national pharmaceutical regulator validates systems for active pharmaceutical ingredient manufacturing under stringent electronic records requirements. Bavarian and North Rhine-Westphalian industrial clusters are standardizing on modular architectures for specialty chemical production.
China
Dual carbon goals and GB standards for pressure vessel fabrication are reshaping procurement preferences toward factory-controlled, emissions-measurable skid systems. The Ministry of Ecology and Environment is tightening discharge mandates for industrial water treatment. Yangtze River Delta petrochemical complexes are adopting plug-and-play architectures to accelerate project timelines.
India
BIS certification requirements and the PLI scheme for manufacturing are incentivizing domestic fabrication capacity for biofuel and ethanol processing skids. State-level pollution control boards are enforcing stricter effluent standards for industrial clusters. Gujarat and Maharashtra process industries are deploying distributed plant architectures to reduce capital intensity in specialty chemical production.
Saudi Arabia
Downstream petrochemical expansion under Vision 2030 is creating concentrated demand for corrosion-resistant separation skids. The national environmental regulator is aligning discharge standards with international benchmarks for industrial facilities. Eastern Province integrated refining and petrochemical complexes are procuring bundled treatment and process systems from single-source fabricators.
Modular Process Skid Systems Market Competitive Landscape
Global majors compete with regional champions across fabrication capacity and engineering-procurement-construction integration depth. Market structure tilts toward consolidated leadership among full-service EPC-anchored players and specialized skid fabricators, with mid-tier engineering houses occupying project-specific niches. Strategic archetypes span integrated EPC-skid providers, pump and separation equipment specialists, and biofuel process technology licensors. Dominant competitive moves include geographic expansion into Gulf Coast petrochemical corridors and portfolio diversification into PFAS treatment and carbon-accounting-compliant fabrication methods.
Among US-based fabricators, Robinson and H+M Industrial occupy positions within the regional specialist tier serving Gulf Coast petrochemical and water treatment demand. EPIC Systems exemplifies the engineering-procurement-construction integrated model anchoring large-scale projects across North American industrial infrastructure. Sulzer, with its Swiss corporate origins, represents the pump and separation equipment specialist archetype competing through corrosive-service technical capabilities. Praj Industries anchors the biofuel process technology licensor position, particularly in distributed plant architectures reducing capital intensity for ethanol processing.
| Leading Market Players |
|---|
| Robinson |
| H+M Industrial |
| Donaldson |
| EPIC Systems |
| Sulzer |
| Aquatech |
| Integrated Flow Solutions |
| Fluor Corporation |
| Praj Industries |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast petrochemical operators concentrate procurement volume through bundled EPC contracts, anchoring project-based pricing that bundles factory acceptance testing and commissioning services into lump-sum deliverables. This buyer concentration compresses margin negotiation leverage for fabricators while amplifying price sensitivity among municipal water treatment agencies operating under fixed capital budgets.
Pricing Analysis
Factory warranty and multi-year service bundling separate premium-tier vendors from economy competitors in municipal procurement. Pricing stratifies across ASME-certified premium fabricators, mid-tier regional specialists, and economy imports lacking code stamping. Cost compression in the mid-tier intensifies because duplex stainless steel input volatility erodes fixed-price contract margins. Municipal water treatment agencies exhibit highest price sensitivity due to constrained tax-funded budgets, while Gulf Coast petrochemical operators prioritize schedule certainty over unit cost.
Supply Chain Analysis
Direct-to-EPC contractor channels handle hyperscale petrochemical demand, while municipal procurement flows through specified-bid processes involving engineering consultants. Fabrication capacity concentrates in the United States, Germany, and China, with Gulf Coast and Midwest US plants serving North American demand. Duplex stainless steel, superalloy castings, and specialized instrumentation draw from limited qualified supplier pools. Single-source vulnerability in ASME-certified welding consumables creates disruption exposure during surge demand periods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified welder scarcity constrains output expansion, propping pricing power for qualified fabricators and extending backlog visibility. This supply bottleneck justifies selective capacity investments by incumbents with certified labor pipelines.
For Market Incumbents: Cement market position through captive ASME certification programs and backward integration into specialized alloy machining. Fluor Corporation and EPIC Systems anchor integrated EPC-skid models that emerging engineering houses threaten through niche PFAS treatment specialization. Capacity addition in hurricane-resilient Midwest fabrication bases reduces geographic concentration risk. For New Entrants and Emerging Players: Digital twin-enabled virtual commissioning offers a technology-first wedge against legacy fabricators burdened by conventional factory acceptance protocols. Temporary emergency response skid configurations represent the most penetrable white-space, particularly for Gulf Coast hurricane recovery demand. Go-to-market execution should target performance-based contracting structures that transfer operational risk from municipal agencies. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with certified fabrication capacity and existing EPA compliance track records. Long-term viability hinges on positioning for PFAS treatment and carbon-accounting-compliant fabrication methods as procurement preferences shift. Monitor state-level PFAS mandate acceleration and ASME third-party inspector capacity expansion as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Capacity Expansion | Captures backlog from fabricators constrained by welder scarcity in tight labor markets. |
| Backward Integration into Alloy Machining | Reduces margin compression from duplex stainless steel price volatility in corrosive-service skids. |
| PFAS Treatment Technology Licensing | Positions vendors for emerging EPA and state discharge mandates driving retrofit demand. |
| Performance-Based Service Contracting | Aligns revenue recognition with California and Texas municipal operational risk transfer preferences. |
| Midwest Fabrication Footprint Addition | Diversifies hurricane exposure from concentrated Gulf Coast production bases. |
Research Methodology
Independent corroboration across plant managers at Gulf Coast petrochemical facilities, procurement leads at municipal water treatment agencies, and EPC contractor project directors underwrites the qualitative findings. Primary interviews with ASME-certified fabricators, aftermarket service heads, and engineering consultants combined with secondary validation from EPA effluent limitation guidelines, ASME Boiler and Pressure Vessel Code documentation, and SEC 10-K filings of listed EPC contractors. Bottom-up fabrication capacity estimates and top-down capital expenditure projections were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline, supply disruption peak, and normalization phases anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, end user vertical, installation mode, and service type dimensions. CAGRs were derived from regression analysis against industrial capital expenditure cycles and regulatory mandate implementation timelines. Forecast inputs included ASME inspector capacity expansion rates and state-level PFAS treatment mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA effluent standard tightening or prolonged alloy price volatility. Practitioners should monitor ASME third-party inspector queue lengths and state pollution control board PFAS rulemaking calendars for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Conventional Overhead Conductor Market
Construction and Engineering
Industrial Electric Boiler Market
Construction and Engineering
Wall Hung Boilers Market
Construction and Engineering
India UPVC Doors and Windows Market
Construction and Engineering
Pozzolana Cement Market
Construction and Engineering
Autonomous Material Handling Equipment Market
Construction and Engineering
Centrifugal Blower Market
Construction and Engineering
Thin Wall Mould Market
Construction and Engineering
Italy Cement Market
Construction and Engineering
Asia-Pacific Drill Pipe Market
Construction and Engineering
Drywall and Gypsum Board Market
Construction and Engineering
Linear Slides Market
Construction and Engineering
Steel Utility Poles Market
Construction and Engineering
Africa Pipeline Construction Market
Construction and Engineering
Mini Cranes Market
Construction and Engineering
Global FRP Rebar Market