
 Moisture Resistant Plaster Boards Market | 2026-2036
Moisture Resistant Plaster Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Resistant Plaster Boards Market Intelligence
Glass-fiber reinforced gypsum core formulations is narrowing the performance gap between standard drywall and cement-based alternatives in wet-zone applications. Saint-Gobain leverages captive gypsum sourcing and integrated glass-mat supply to sustain margin stability across volatile raw-material cycles. Knauf Group anchors European specification channels through EN 520-certified production lines, while Georgia-Pacific competes on scale in North American distribution through mill-direct relationships with national homebuilders.
Moisture resistant plaster boards are gypsum-core or cement-core panels treated with silicone additives, glass-fiber mat facings, or wax emulsions to achieve water absorption rates below 5% per ASTM C1396, engineered for interior surfaces exposed to intermittent humidity or liquid contact. Gypsum boards dominate volume due to lower installed cost and familiar trade handling, though magnesium oxide boards represent the fastest-growing product category where mold resistance and fire ratings must coexist. Application demand tilts toward bathroom walls and basement interiors in residential renovation, while commercial partitions command premium pricing through extended warranty terms and contractor-specified performance tiers.
EPA regulations on formaldehyde emissions from composite wood products, REACH restrictions on hazardous additives in European construction materials, and ASTM C1178 testing protocols collectively elevate compliance costs for market entry while favoring incumbent producers with certified laboratory infrastructure. Building code adoption of moisture-performance categories in humid climate zones creates specification inertia that rewards early certification investments. Stakeholders must track evolving regional standards for circularity and recycled content, as these will determine which core formulations retain specification access in premium construction segments.
Market Dynamics
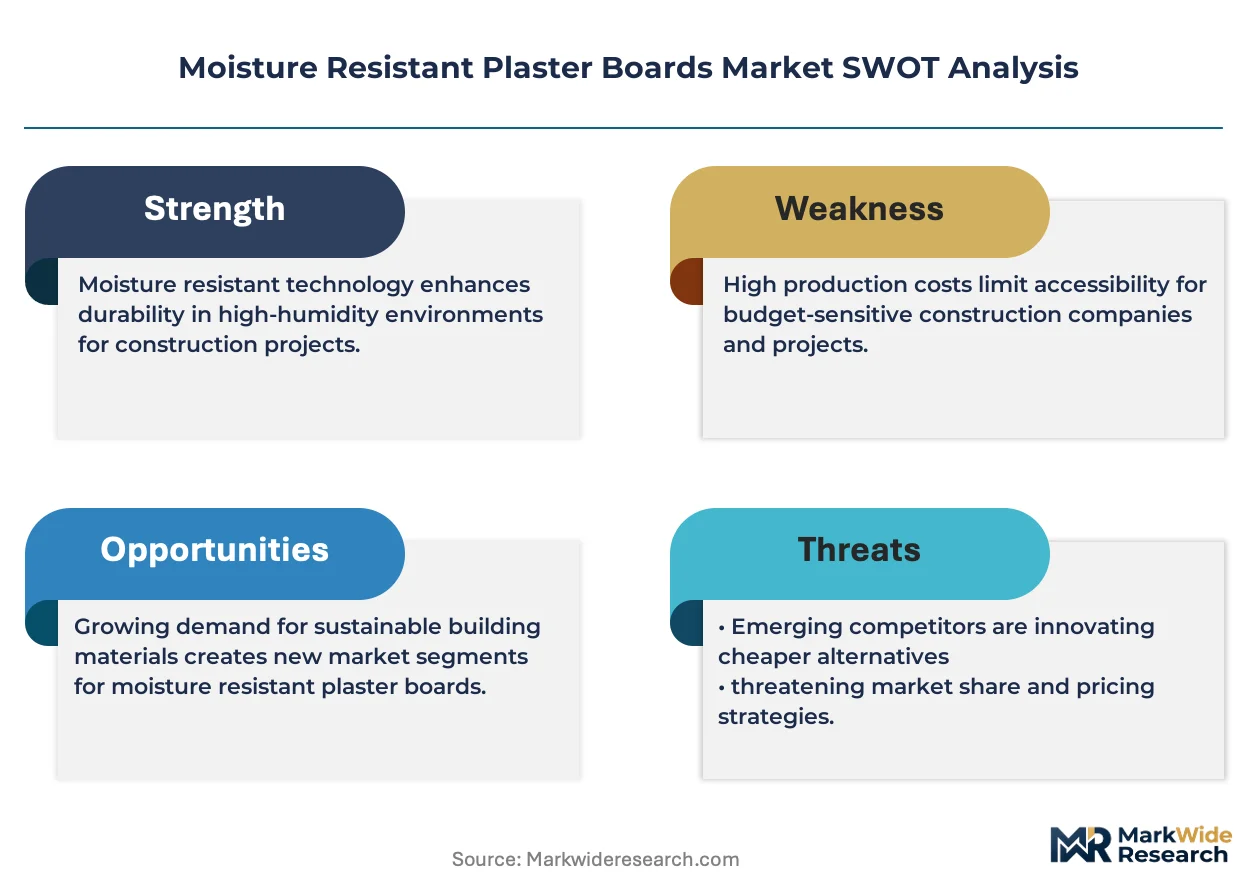
Reformulated core materials and glass-fiber mat facings are compressing the performance gap between gypsum and cement-based boards, forcing incumbents to defend specification access through certified laboratory infrastructure rather than scale alone.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Germany, France, and Italy now enforce lower-carbon interior finishes in public procurement, pulling manufacturers toward bio-based core binders and recycled gypsum feedstocks.
- Healthcare facility construction corridors:Southeast Asian hospital buildouts in Vietnam and Indonesia specify ASTM C1396-compliant boards for cleanroom humidity control, creating specification-grade demand clusters.
- Glass-mat facing technology:Silicone-impregnated facings reduce water absorption below 5%, enabling gypsum boards to penetrate wet-zone applications previously reserved for magnesium oxide panels.
Market Restraints
- Raw material volatility:Synthetic gypsum supply from flue-gas desulfurization fluctuates with coal-fired power generation trends, compressing margin stability for non-integrated producers.
- REACH additive restrictions:ECHA scrutiny on formaldehyde-releasing agents and flame retardants elevates reformulation costs and extends product recertification timelines.
- Cement-board substitution in fire-rated assemblies:Magnesium oxide panels command premium specification where mold resistance and non-combustibility must coexist, capping gypsum volume in high-performance segments.
Strategic Opportunities
- Indonesian hospitality construction:Humidity-resistant specifications are becoming standard in resort and institutional projects, opening specification channels for EN 520-certified imports.
- Circular content mandates:EU construction product regulations advancing recycled gypsum quotas create first-mover advantage for producers with post-consumer feedstock partnerships.
- Digital specification platforms:Building information modeling integration allows manufacturers to embed performance data directly into architect workflows, bypassing traditional distributor influence.
Industry Challenges
- Multi-jurisdiction certification complexity:ASTM C1178, EN 520, and GB/T 9775 testing protocols require parallel laboratory investments, straining mid-cap R&D budgets.
- Installer skill gaps:Glass-mat board handling demands modified cutting and fastening techniques, creating field performance risk where contractor training lags product introduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Resistant Plaster Boards Market |
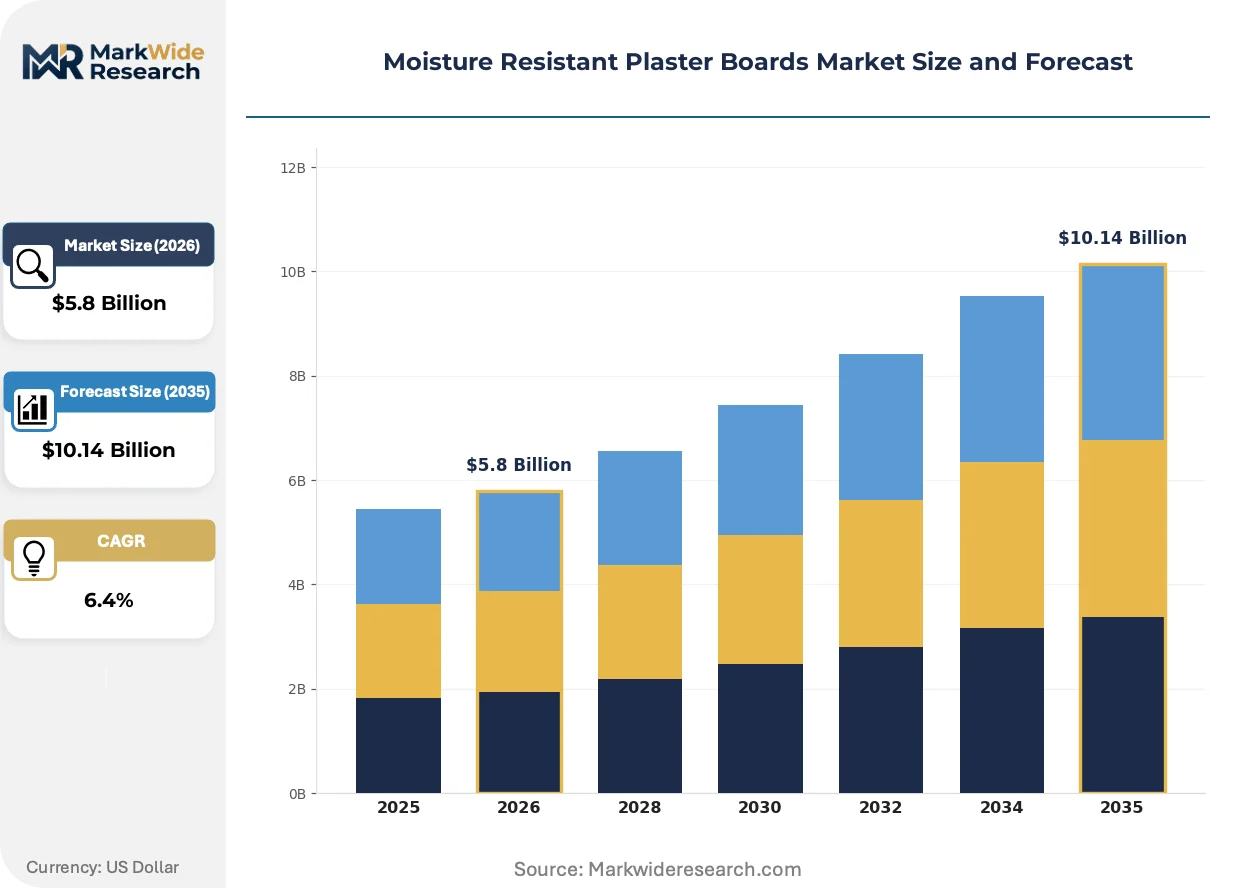
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum Boards, Cement Boards, Fiber Cement Boards, Magnesium Oxide Boards, Wooden Boards Application: Bathroom Walls, Kitchen Walls, Basement Interiors, Commercial Partitions, Institutional Buildings Installation Type: Wall Mounting, Ceiling Installation, Partitioning, External Cladding, Decorative Paneling End User: Contractors, Interior Designers, Real Estate Developers, Renovation Firms, Property Managers |
| Companies Covered | Saint-Gobain, Etex Group, Gold Bond, PABCO Gypsum, Georgia-Pacific, National Gypsum, Knauf Group, USG ME, USG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Resistant Plaster Boards Market Strategic Shifts & Innovations
Material science advances and procurement digitization are compressing traditional specification cycles, while regulatory pressure on embodied carbon forces core formulation reinvention across manufacturing bases.
Glass-fiber reinforced gypsum cores with silicone additive treatments are rendering obsolete the historical trade-off between installed cost and moisture performance. Hospital and cleanroom contractors in humid climate zones specify these boards for intermittent liquid exposure zones. The technology is compressing cement-board penetration in commercial renovation by 15-20 percentage points in wet-zone applications.
REACH restrictions on hazardous additives and the EU Green Deal's embodied carbon thresholds are forcing reformulation of core binders and facings. Manufacturers with captive gypsum sourcing and integrated glass-mat supply chains absorb compliance costs more efficiently than import-dependent competitors. German and French specification channels now prioritize Environmental Product Declarations alongside mechanical performance data.
Specification decisions increasingly flow through centralized procurement platforms rather than traditional distributor relationships. National homebuilders and healthcare facility developers consolidate supplier panels around certified performance tiers, compressing vendor counts. This concentration is most visible in North American multi-family residential and Southeast Asian institutional construction, where warranty terms and contractor-specified tiers determine allocation.
Moisture Resistant Plaster Boards Market Segmentation
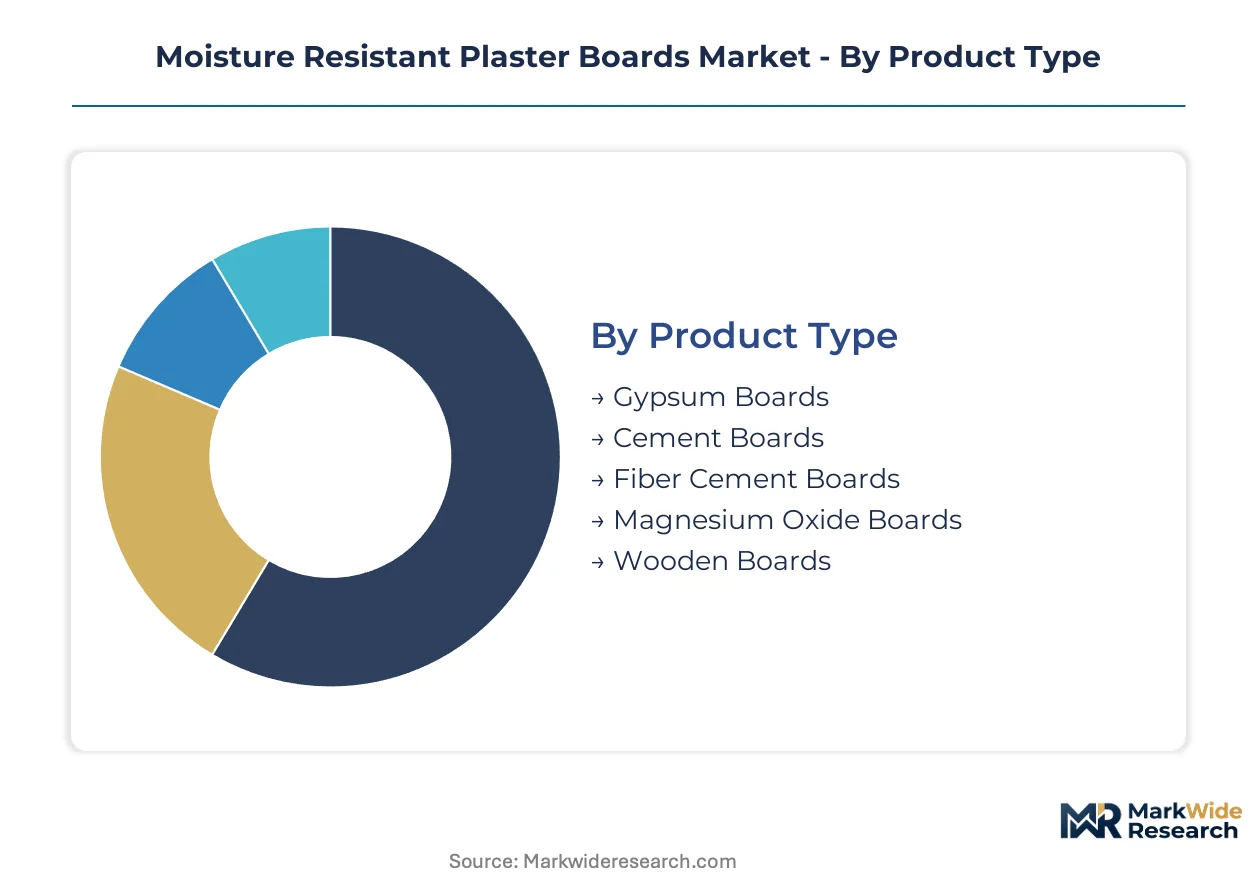
Segmentation in moisture resistant plaster boards determines specification pathways, warranty tiers, and contractor training requirements. Each dimension—product chemistry, application environment, installation method, and buyer type—creates distinct margin profiles and technical support demands that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply by core chemistry, with cementitious and magnesium oxide formulations demanding specialized field support for crack remediation and fastener corrosion issues.
- Gypsum Boards:Silicone-impregnated cores with glass-fiber mat facings achieve water absorption below 5% per ASTM C1396. Residential renovation in Germany and France concentrates demand where installed cost familiarity drives contractor preference over cement alternatives.
- Cement Boards:Portland cement cores with polymer-modified facings deliver superior compressive strength for wet-zone tile backing. Commercial partitions in Vietnamese hospital construction specify these for extended warranty coverage where liquid exposure is continuous.
- Fiber Cement Boards:Cellulose-reinforced cement formulations balance density and workability for exterior-grade humidity resistance.
- Magnesium Oxide Boards:Chloride-free MgO cores achieve mold resistance and non-combustibility ratings simultaneously for cleanroom specifications.
- Wooden Boards:Pressure-treated timber panels with wax emulsion barriers serve heritage restoration projects requiring aesthetic warmth alongside moisture protection.
By volume, Gypsum Boards leads. By growth pace, Magnesium Oxide Boards is ahead.
Application:
Cost tier stratification separates specification-grade commercial installations from economy residential retrofits, with warranty duration and performance certification driving price differentiation.
- Bathroom Walls:Intermittent humidity exposure zones favor glass-mat gypsum for residential renovation speed. Italian building codes now mandate moisture-performance categories in humid climate zones, pulling specification toward certified products.
- Commercial Partitions:Extended warranty terms and contractor-specified performance tiers command premium pricing. Indonesian hospitality construction corridors standardize humidity-resistant specifications for resort developments.
- Kitchen Walls:Grease-resistant facings combined with moisture barriers address residential cooking vapor exposure.
- Basement Interiors:Below-grade hydrostatic pressure demands cement-board substitution in flood-prone geographies.
- Institutional Buildings:Cleanroom humidity control specifications in Southeast Asian hospital buildouts create demand clusters for ASTM C1396-compliant boards.
Residential renovation concentrates volume in Bathroom Walls. Institutional construction offers the steepest expansion trajectory through healthcare facility mandates.
Installation Type:
Volume concentration tilts toward wall-mounted systems where trade labor familiarity minimizes field performance risk and accelerates project timelines.
- Wall Mounting:Direct-screw attachment to metal or wood studs dominates residential and light commercial construction. REACH restrictions on formaldehyde-releasing agents in European construction materials elevate reformulation costs for adhesive-dependent alternatives.
- Ceiling Installation:Sag-resistant cores with enhanced tensile strength address gravity load concerns in humid environments. German specification channels prioritize Environmental Product Declarations alongside mechanical performance data for suspended systems.
- Partitioning:Demountable systems for commercial fit-outs require edge-hardness durability.
- External Cladding:Rainscreen assemblies demand freeze-thaw cycling resistance.
- Decorative Paneling:Pre-finished surfaces reduce on-site labor for hospitality interiors.
Wall Mounting captures the largest installed base. Ceiling Installation is gaining share fastest through healthcare cleanroom specifications.
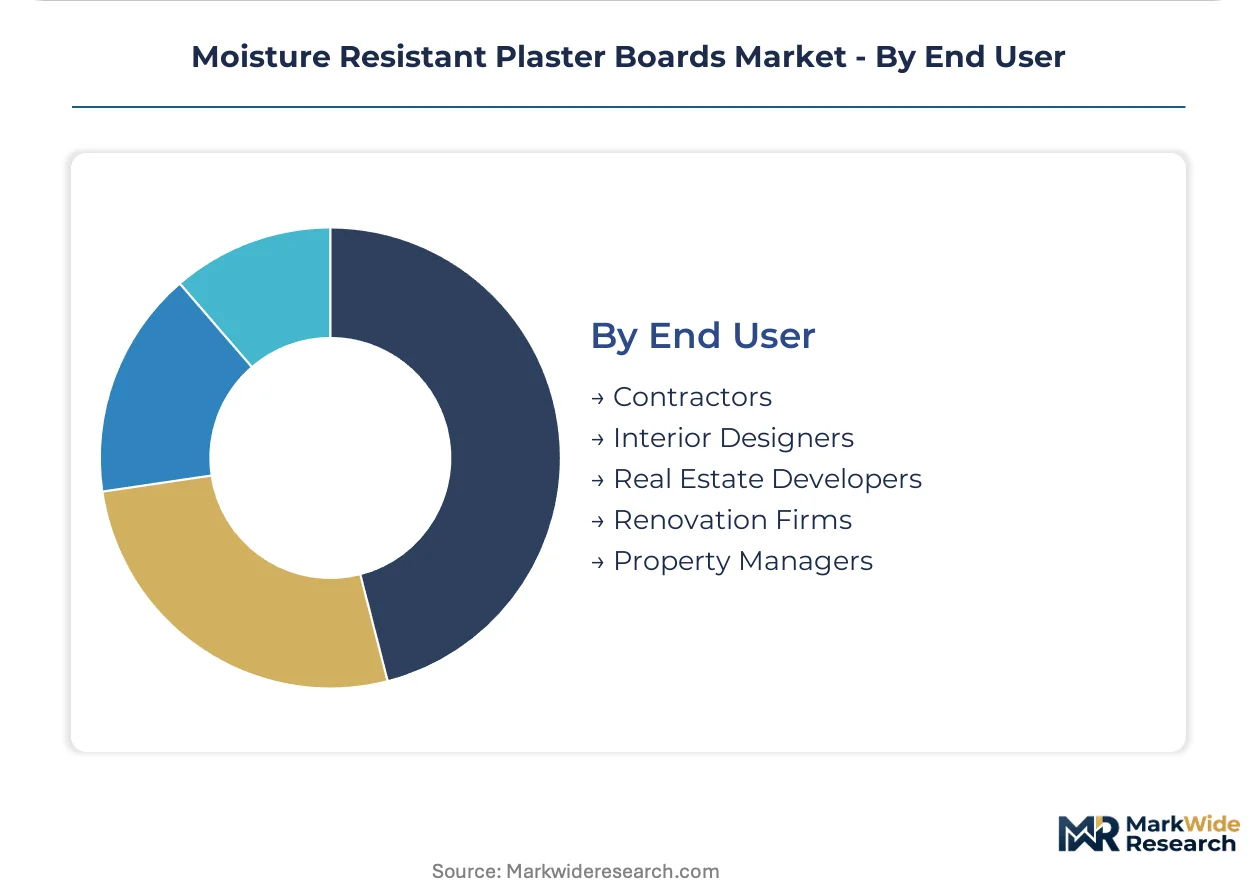
End User:
Customer type determines procurement channel—national homebuilders consolidate supplier panels while renovation firms fragment across distributor relationships.
- Contractors:Field crews require modified cutting and fastening techniques for glass-mat boards, creating training gaps where product introduction outpaces contractor education. EPA regulations on formaldehyde emissions from composite wood products elevate compliance costs for market entry.
- Real Estate Developers:Centralized procurement platforms consolidate supplier panels around certified performance tiers, compressing vendor counts in North American multi-family residential construction.
- Interior Designers:Aesthetic integration with moisture performance drives specification for premium hospitality projects.
- Renovation Firms:Time-sensitive residential retrofits prioritize familiar gypsum handling over cement-board learning curves.
- Property Managers:Warranty terms and lifecycle cost calculations dominate replacement decisions in institutional portfolios.
Contractors represent the deepest volume channel. Real Estate Developers are consolidating procurement fastest through digital specification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French manufacturers export EN 520-certified boards to Southeast Asian hospital construction corridors, while Chinese producers supply magnesium oxide panels to Middle Eastern hospitality developments.
Germany
Healthcare facility retrofits and cleanroom construction drive specification-grade demand in Bavaria and North Rhine-Westphalia. The EU Green Deal mandates lower embodied carbon in public procurement, forcing reformulation toward recycled gypsum feedstocks. Stuttgart's industrial cluster hosts integrated glass-mat production facilities serving Central European distribution networks.
United States
Multi-family residential construction and basement renovation concentrate volume demand in Texas and the Southeast. EPA regulations on formaldehyde emissions from composite wood products elevate compliance costs for imported alternatives. Atlanta's distribution hub anchors mill-direct relationships with national homebuilders consolidating supplier panels.
Vietnam
Hospital buildouts and hospitality construction corridors in Ho Chi Minh City and Hanoi specify ASTM C1396-compliant boards for humidity control. National building codes adopt moisture-performance categories for institutional projects. Da Nang's resort developments standardize glass-mat gypsum specifications for wet-zone applications.
Indonesia
Jakarta's commercial construction and Bali's hospitality infrastructure drive humidity-resistant specification adoption. Local regulations align with ASEAN harmonized standards for interior finishes. Surabaya's institutional projects increasingly require EN 520-certified imports for extended warranty coverage.
Italy
Residential renovation in Lombardy and Emilia-Romagna favors familiar gypsum handling over cement-board alternatives. National building codes now mandate moisture-performance categories in humid climate zones. Milan's specification channels prioritize Environmental Product Declarations alongside mechanical performance data.
Moisture Resistant Plaster Boards Market Key Industry Players
Channel-controlling players compete with product-specialist players across specification tiers. The market structure tilts toward consolidated supply relationships in North America and fragmented specialist competition in Europe. Three archetypes dominate: vertically integrated gypsum producers with captive mineral sourcing, regional fabricators with certified laboratory infrastructure, and magnesium oxide specialists serving fire-rated segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers defend specification access.
Among European-based producers, Saint-Gobain, Knauf Group, and Etex Group exemplify the integrated archetype. Saint-Gobain occupies a position anchored by captive gypsum sourcing. Knauf Group represents the certification-focused specialist model through EN 520-certified production lines. Etex Group sits within the regional scale tier serving specification channels across multiple jurisdictions.
| Leading Market Players |
|---|
| Saint-Gobain |
| Etex Group |
| Gold Bond |
| PABCO Gypsum |
| Georgia-Pacific |
| National Gypsum |
| Knauf Group |
| USG ME |
| USG Corporation |
| Others |
Cost & Logistics Intelligence
Chinese synthetic gypsum capacity from flue-gas desulfurization operations anchors upstream supply, concentrating margin capture among manufacturers with captive mineral sourcing and integrated glass-mat production. This upstream consolidation forces import-dependent competitors into price-taker positions across European and Southeast Asian specification channels.
Pricing Analysis
Glass-mat facing technology commands premium positioning against standard silicone-treated gypsum cores, while wax-emulsion boards occupy economy tiers in residential renovation. Three-tier pricing structure across premium, standard, and economy levels separates EN 520-certified imports with extended warranty terms from domestic commodity production. Cost compression in standard-grade segments is intensifying because synthetic gypsum supply fluctuates with coal-fired power generation trends. Real estate developers consolidating supplier panels exhibit lowest price sensitivity, while renovation firms prioritize familiar handling over specification-grade premiums.
Supply Chain Analysis
REACH restrictions on hazardous additives limit cross-border flows of formaldehyde-releasing agents and flame-retardant formulations, fragmenting raw material procurement across regulatory jurisdictions. Manufacturing concentrates in Germany, China, and the United States, with glass-fiber mat supply drawing from integrated chemical complexes in Stuttgart and Atlanta. Synthetic gypsum, silicone additives, and glass-mat facings constitute critical input dependencies. Single-source vulnerability in glass-mat supply creates chokepoint exposure for non-integrated producers. Distribution runs through mill-direct relationships with national homebuilders and specification channels serving healthcare facility developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesium oxide board substitution threatens gypsum incumbents in fire-rated assemblies where mold resistance and non-combustibility must coexist. Incumbents must navigate this technology displacement while defending specification access through certification infrastructure.
For Market Incumbents: Build certification moats around EN 520 and ASTM C1178 laboratory infrastructure to defend specification access against cement-board substitution. Deepen backward integration into synthetic gypsum sourcing to absorb raw material volatility. Channel control through digital specification platforms embedded in architect workflows counters distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Indonesian hospitality construction corridors where humidity-resistant specifications are becoming standard and EN 520-certified imports command premium positioning. Target Surabaya institutional projects requiring extended warranty coverage. Partner with regional distributors possessing certified handling capabilities for glass-mat board logistics. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated producers with captive gypsum sourcing and glass-mat supply chains that absorb compliance cost inflation more efficiently than import-dependent competitors. Long-term viability hinges on circular content mandates advancing recycled gypsum quotas. Watch for first-mover advantage signals in post-consumer feedstock partnerships as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Gypsum Sourcing | Saint-Gobain's captive mineral supply stabilizes margin exposure across volatile coal-power generation cycles. |
| EN 520 Certification Investment | Knauf Group anchors European specification channels through certified production lines in Germany. |
| Digital Specification Platform Integration | Embedding performance data into architect workflows bypasses traditional distributor influence in North America. |
| Post-Consumer Gypsum Feedstock Partnerships | EU circular content mandates create first-mover advantage for producers with recycled material pipelines. |
| Healthcare Facility Direct Procurement Relationships | Mill-direct ties with national homebuilders consolidate supplier panels around certified performance tiers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory submissions to establish baseline market sizing. Primary interviews engaged plant managers at gypsum manufacturing facilities, procurement leads at national homebuilders, specification directors at healthcare facility developers, and distribution channel partners across Germany, Vietnam, and the United States. Secondary validation drew from EPA formaldehyde emission databases, ECHA REACH restriction notices, ASTM certification registries, and ASEAN harmonized standard documentation. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates.
Forecast inputs include product chemistry segmentation across gypsum, cement, and magnesium oxide formulations; application environment stratification by residential renovation versus institutional construction; and installation method differentiation between wall-mounted and ceiling systems. CAGRs were derived through regression analysis of historical specification adoption rates and forward projection of regulatory mandate implementation timelines. Core formulation innovation cycles and circular content quota phase-ins served as industry-specific demand shapers across the modeling period.
Stress conditions across synthetic gypsum supply disruption, REACH additive restriction expansion, and cement-board substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and construction sector capital allocation priorities. Cross-checking against national building code adoption timelines and healthcare facility procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market