
 EPS Sandwich Panels Market | 2026-2036
EPS Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
EPS Sandwich Panels Market Insights
The EU Green Deal is broadening demand for low-embodied-carbon building envelopes across European construction markets. Kingspan Group leverages its vertically integrated insulation and panel manufacturing network to serve this regulatory shift. ArcelorMittal sustains competitive pressure through its steel supply chain control and pre-coated metal offerings for panel facings. Metecno Group anchors its position in cold storage applications with specialized refrigeration-compatible panel systems.
EPS sandwich panels consist of an expanded polystyrene core bonded between two metal facing sheets, typically steel or aluminum, delivering thermal conductivity values near 0.036 W/m·K for temperature-controlled environments. Wall panels dominate volume shipments across residential and commercial building construction, while cold storage panels command premium positioning due to stringent thermal bridging requirements and specialized joint detailing. Agricultural end users represent an expanding segment as controlled-atmosphere livestock facilities and food processing plants adopt modular envelope solutions.
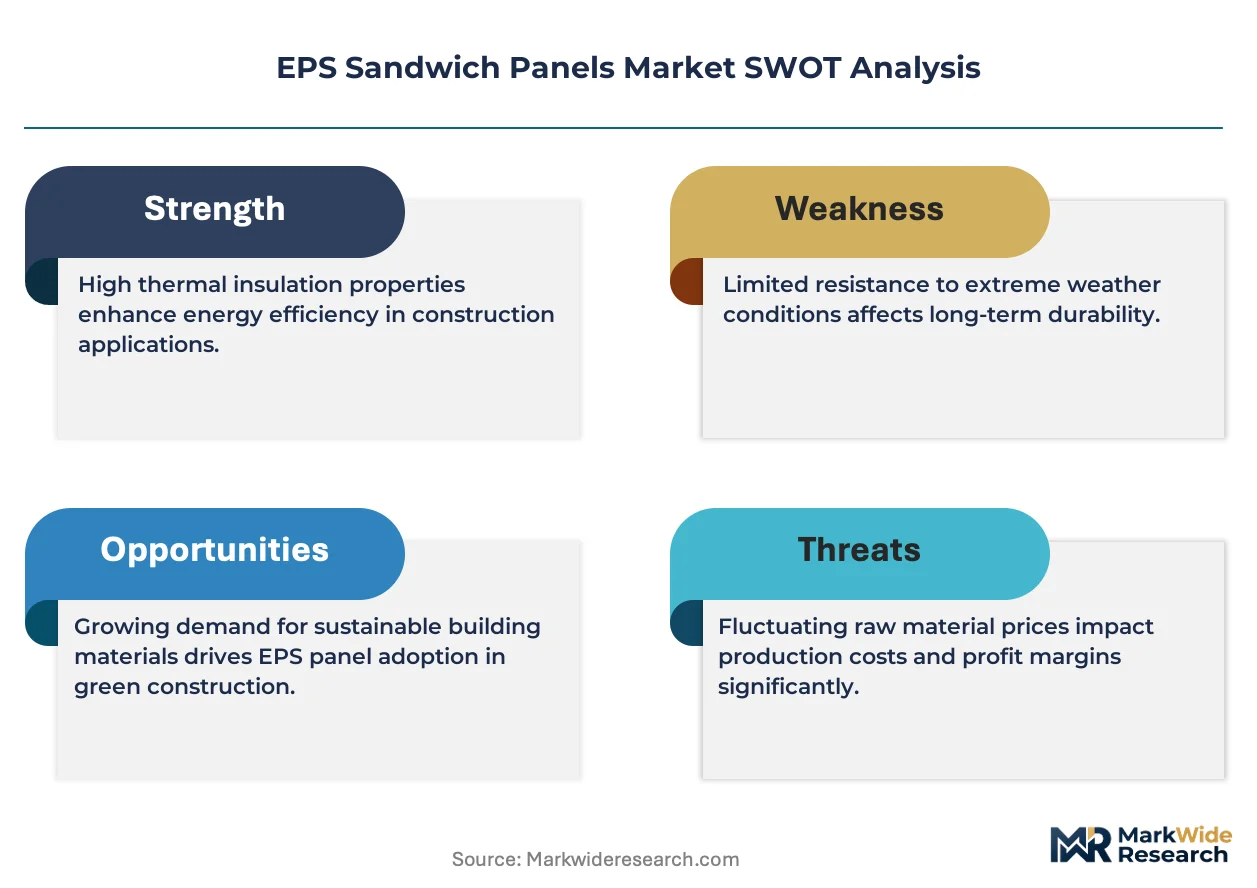
EMA and ECHA frameworks in Europe govern fire performance and chemical safety standards for EPS core materials, while India's BIS certification mandates thermal and structural testing for panel assemblies used in commercial buildings. The EU F-Gas Regulation is additionally reshaping cold storage panel specifications as operators transition to lower-global-warming-potential refrigeration systems that demand tighter envelope performance. Stakeholders must weigh regulatory compliance investments against the margin compression risk from commoditized standard wall panel segments.
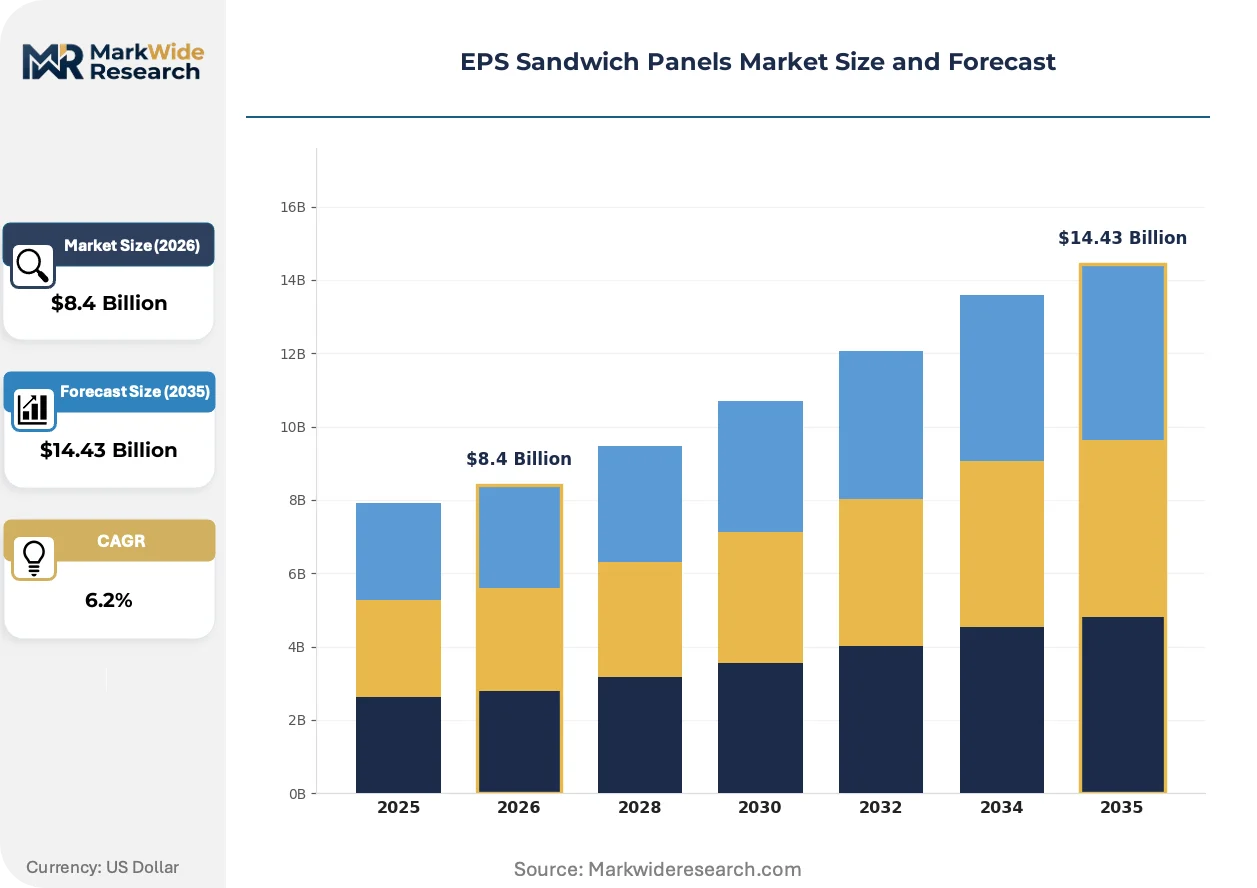
Market Dynamics
The EU Green Deal's building renovation mandates are compressing embodied carbon thresholds across European construction supply chains. Cold storage operators in Germany, China, and Brazil are simultaneously expanding warehouse footprints with thermally efficient envelope systems, creating dual demand vectors for high-performance insulated paneling.
Growth Catalysts
- EU Green Deal building renovation targets:Tightening embodied carbon thresholds for construction materials are accelerating specification of low-carbon insulated envelope systems across European commercial and industrial building stock.
- India pharmaceutical cold chain infrastructure:Temperature-controlled facilities for vaccine and biologics distribution require high-performance insulated paneling with stringent thermal bridging control.
- EU F-Gas Regulation transition:Cold storage operators migrating to lower-global-warming-potential refrigeration systems demand tighter envelope performance specifications for panel assemblies.
Market Restraints
- Polystyrene feedstock volatility:Expanded polystyrene core production remains exposed to benzene and styrene monomer price swings, compressing margin stability for panel fabricators.
- Steel supply concentration:Pre-coated metal facing sheet availability clusters with integrated steel producers, creating procurement leverage asymmetry for independent panel assemblers.
- Fire performance limitations:EPS core materials face inherent combustibility constraints under ECHA and EMA framework classifications, restricting application in high-rise residential envelopes.
Strategic Opportunities
- Controlled-atmosphere agricultural facilities:Livestock housing and food processing plants in Brazil and India are adopting modular envelope solutions for temperature and humidity management.
- CE marking harmonization:Streamlined conformity assessment procedures across EU member states reduce certification duplication costs for panel manufacturers expanding cross-border.
- Refrigeration-compatible joint detailing:Specialized gasket and cam-lock systems for ultra-low-temperature cold storage represent premium positioning white space distinct from commoditized wall panels.
Industry Challenges
- Thermal bridging engineering expertise:Cold storage panel specification requires specialized joint detailing knowledge that sits outside standard architectural engineering curricula, constraining qualified installer availability.
- BIS certification timeline compression:India's thermal and structural testing mandates for commercial building panel assemblies create extended product approval cycles that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPS Sandwich Panels Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Roof Panels, Door Panels, Cold Storage Panels End User: Residential, Commercial, Industrial, Agricultural Insulation Type: Polyurethane, Polystyrene, Metal, Fiberglass Application: Cold Storage, Building Construction, Clean Rooms, Prefabricated Structures |
| Companies Covered | Kingspan Group, ArcelorMittal, Metecno Group, Tata Steel, Assan Panel A.S., Nucor Corporation, Cornerstone Building Brands, Rautaruukki Corporation, DANA Group of Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPS Sandwich Panels Market Trends and Innovations
Modular prefabrication methods are compressing on-site construction timelines for temperature-controlled facilities. Three distinct forces are reshaping how insulated envelope systems are specified, fabricated, and deployed across end-use verticals.
Prefabricated panel-to-structure connection systems are decentralizing traditional stick-built construction workflows for cold storage warehouses. Third-party logistics operators in Germany and Brazil are specifying factory-assembled envelope modules to compress commissioning schedules. Site labor requirements drop substantially while thermal bridge control improves through precision-manufactured joint interfaces.
REACH chemical safety frameworks are tightening additive disclosure requirements for flame-retardant formulations in EPS core materials. Panel manufacturers face reformulation costs to maintain CE marking compliance across EU member states. Cold storage applications with stringent fire performance specifications are experiencing the most acute specification friction as legacy formulations phase out.
Integrated envelope-performance contracting is displacing component-based procurement for pharmaceutical cold chain facilities in India. Owner-operators now specify guaranteed thermal performance outcomes rather than individual panel R-values. This shifts risk allocation toward fabricators with in-house thermal modeling and installation capabilities, compressing margins for pure component suppliers.
EPS Sandwich Panels Market Segmentation
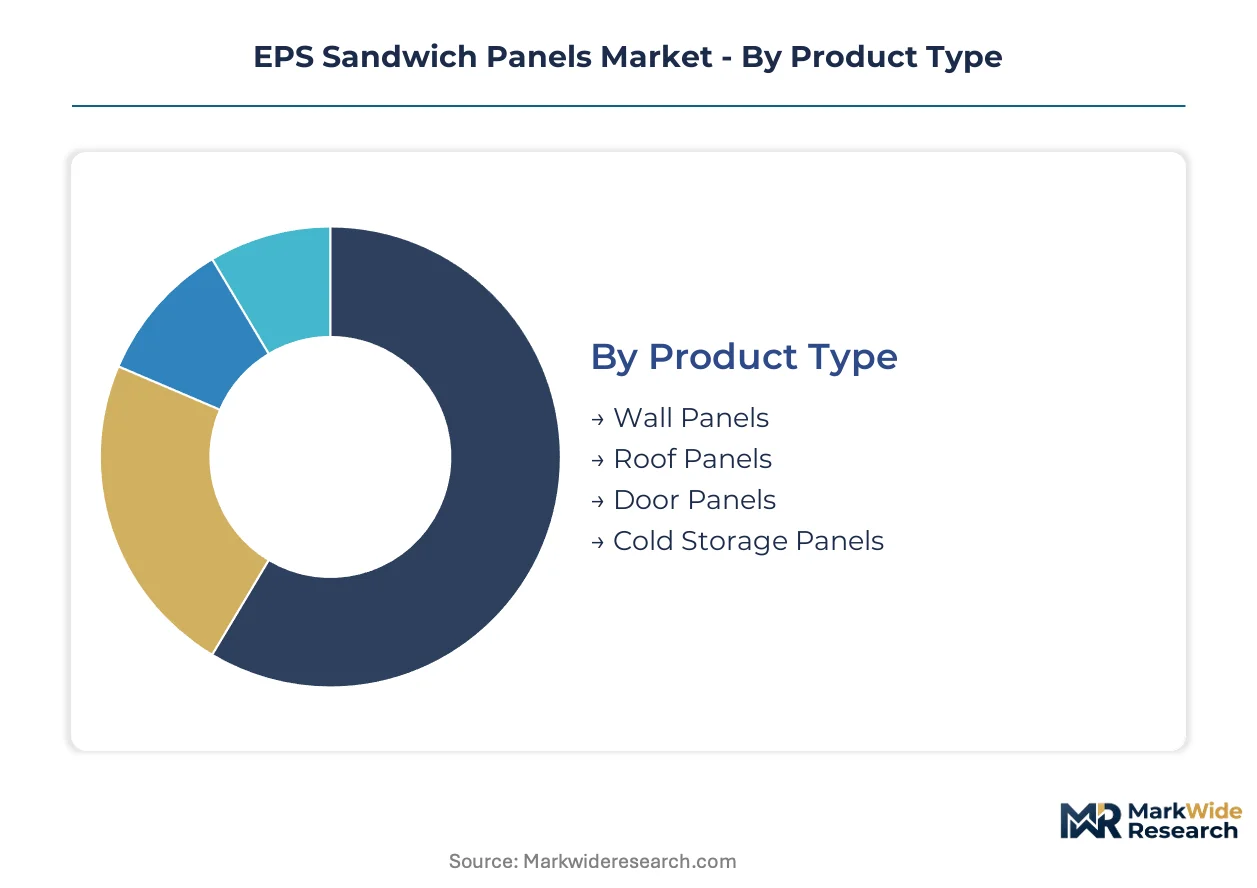
Segmentation in EPS sandwich panels reveals how capital requirements, thermal performance thresholds, and installation complexity fragment demand across construction verticals. Specification patterns diverge sharply between commodity wall envelope projects and precision-engineered cold storage facilities.
Product Type:
Capital intensity escalates dramatically from standard wall systems to ultra-low-temperature cold storage panels with specialized joint engineering.
- Cold Storage Panels:Engineered with precision cam-lock joints and thermal break gaskets to maintain envelope integrity at -40°C. German and Brazilian third-party logistics operators specify these for automated warehouse expansions where thermal bridging control determines refrigeration energy loads.
- Wall Panels:Standardized steel-faced EPS core systems dominate residential and commercial construction volume. India's commercial building stock renovation under BIS certification mandates is absorbing significant wall panel capacity for thermally compliant envelope retrofits.
- Roof Panels:Structural load-bearing profiles with integrated drainage channels for industrial sheds and agricultural facilities.
- Door Panels:Insulated access systems with reinforced framing for cold storage airlocks and controlled-atmosphere entries.
Most installed capacity flows through Wall Panels. Expansion is steepest in Cold Storage Panels.
End User:
Margin profiles diverge across customer categories, with industrial cold chain operators paying premiums for performance guarantees unavailable in residential procurement.
- Industrial:Cold storage warehouses and food processing plants demand certified thermal performance with installation warranties. The EU F-Gas Regulation is compressing envelope specifications as operators migrate to lower-global-warming-potential refrigeration systems requiring tighter building envelopes.
- Agricultural:Controlled-atmosphere livestock housing and food processing facilities in Brazil and India are adopting modular envelope systems for humidity and temperature management in tropical climates.
- Residential:Single-family and multi-family construction specifies standard wall and roof panels with baseline thermal compliance.
- Commercial:Retail and office construction balances thermal performance against facade aesthetics with pre-coated metal facing options.
Industrial buyers command premium pricing through outcome-based procurement. Agricultural adoption is climbing fastest in tropical belt countries.
Insulation Type:
Core material selection determines fire performance classification, thermal conductivity, and regulatory compliance cost across EU and Indian markets.
- Polystyrene:Expanded polystyrene cores deliver thermal conductivity near 0.036 W/m·K at the lowest material cost point. ECHA and EMA frameworks govern fire performance classifications that restrict EPS deployment in high-rise residential envelopes across European markets.
- Polyurethane:Higher-density closed-cell cores achieve superior thermal resistance for ultra-low-temperature applications. REACH chemical safety disclosure requirements are elevating formulation costs for flame-retardant additives in EU-manufactured panels.
- Metal:Mineral wool or perforated steel cores for fire-rated wall assemblies in commercial and industrial separation barriers.
- Fiberglass:Glass fiber reinforced cores for clean room and pharmaceutical manufacturing environments requiring particulate control.
Polystyrene retains volume leadership on cost position. Polyurethane is gaining share fastest in sub-zero cold storage specifications.
Application:
Application scope stretches from standardized building envelopes to precision-controlled environments with particulate and thermal contamination protocols.
- Cold Storage:Automated warehouses and distribution centers for pharmaceuticals, fresh produce, and frozen foods require continuous envelope thermal modeling. India's vaccine and biologics distribution infrastructure is specifying guaranteed thermal performance outcomes rather than component R-values.
- Building Construction:Commercial and industrial envelope systems for offices, retail, and manufacturing facilities under EU Green Deal renovation mandates.
- Clean Rooms:Pharmaceutical and electronics manufacturing environments with ISO 14644 air cleanliness classifications and sealed panel joints.
- Prefabricated Structures:Modular building systems for remote site accommodation and rapid-deployment facilities.
Building Construction absorbs the greatest panel volume. Cold Storage is expanding most quickly on pharmaceutical infrastructure investment.
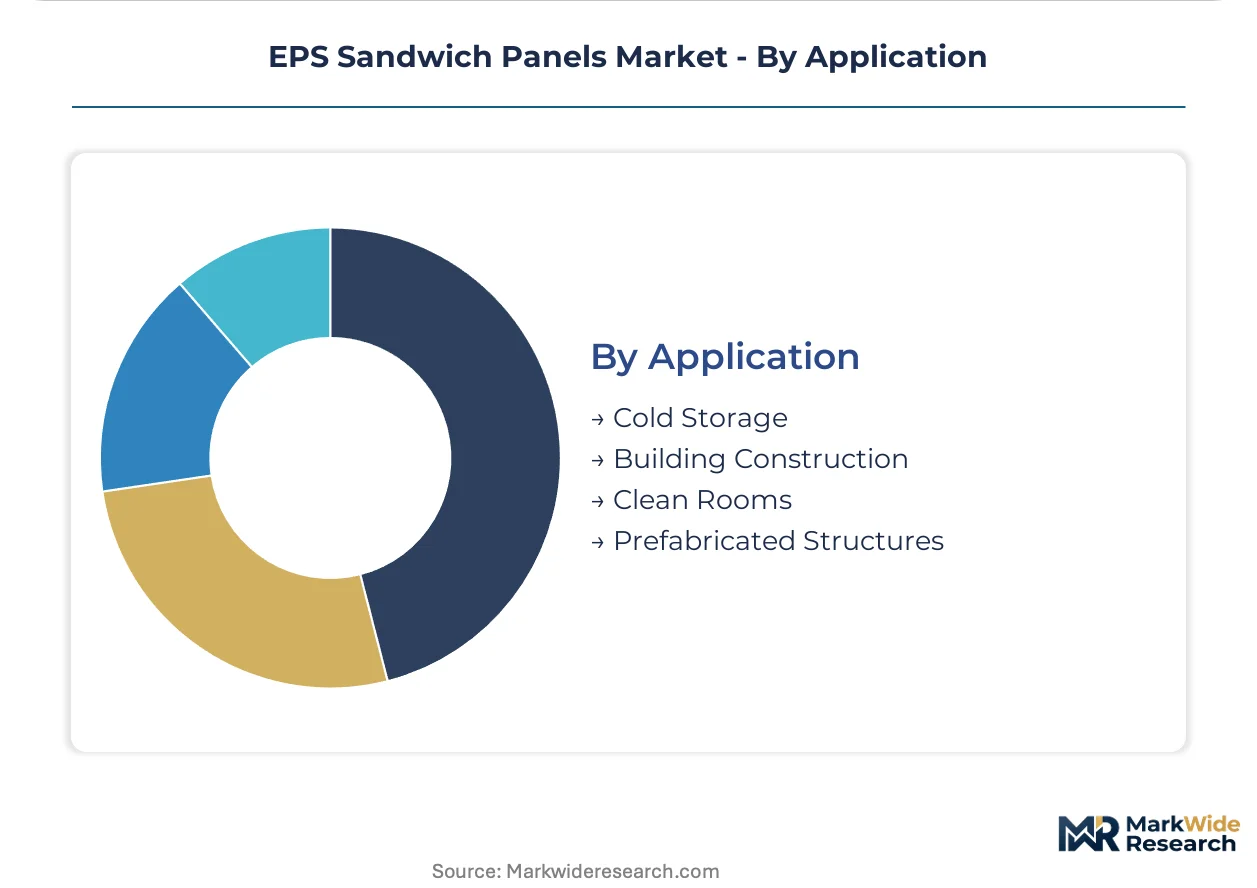
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale sandwich panel fabrication during post-war reconstruction, establishing technical standards that shaped European envelope engineering. Cold storage infrastructure investment now concentrates across four distinct national markets with divergent regulatory drivers.
Germany
Third-party logistics operators in Leipzig and Hamburg are commissioning automated cold storage warehouses with precision-engineered envelope systems. The EU F-Gas Regulation is compressing thermal performance specifications as operators migrate refrigeration infrastructure. Bavarian industrial zones host fabricators supplying cam-lock panel assemblies for sub-zero pharmaceutical distribution.
China
Fresh produce e-commerce fulfillment networks in Shanghai and Shenzhen are absorbing prefabricated cold storage modules. MIIT energy efficiency mandates for commercial buildings are tightening envelope thermal conductivity thresholds. Yangtze River Delta manufacturing clusters produce steel-facing laminates for domestic panel assembly and regional export.
India
Vaccine and biologics cold chain infrastructure in Maharashtra and Gujarat requires certified thermal bridge control for temperature-sensitive distribution. BIS thermal and structural testing mandates create extended product approval cycles that shape procurement timelines. Telangana's pharmaceutical manufacturing corridor is specifying guaranteed envelope performance outcomes rather than component specifications.
Brazil
Controlled-atmosphere livestock facilities in São Paulo state and Minas Gerais are adopting modular envelope systems for tropical climate management. ANVISA pharmaceutical storage regulations are elevating thermal performance requirements for vaccine distribution infrastructure. Paraná's food processing belt is integrating prefabricated panel systems into expansion projects.
United States
Automated grocery fulfillment centers in Texas and California are specifying high-performance insulated envelopes for energy-intensive refrigeration loads. EPA commercial building energy codes are tightening thermal envelope compliance thresholds across climate zones. Southeast industrial construction corridors are absorbing wall panel capacity for manufacturing facility expansion.
EPS Sandwich Panels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent competitive vectors in the EPS sandwich panel market. Integrated steel producers maintain supply chain leverage through captive pre-coated metal facing production, while independent panel fabricators concentrate on specialized joint engineering and installation services. Three archetypes dominate: steel-backed conglomerates with upstream metallurgical control, dedicated envelope specialists with thermal modeling capabilities, and regional assemblers serving localized construction markets. Capacity expansion and portfolio diversification toward refrigeration-compatible systems represent the dominant competitive moves.
Among steel-integrated conglomerates, ArcelorMittal and Tata Steel occupy positions anchored by metallurgical supply chain control, while Kingspan Group exemplifies the dedicated envelope specialist archetype with in-house insulation and panel manufacturing integration. These three entities represent distinct strategic postures: metallurgical supply dominance, vertical manufacturing integration, and thermal performance contracting capability.
| Leading Market Players |
|---|
| Kingspan Group |
| ArcelorMittal |
| Metecno Group |
| Tata Steel |
| Assan Panel A.S. |
| Nucor Corporation |
| Cornerstone Building Brands |
| Rautaruukki Corporation |
| DANA Group of Companies |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Italy and Spain anchor European panel production, transmitting feedstock volatility directly into contract negotiations without the pricing discipline of listed conglomerates. Their concentrated ownership concentrates supply response speed but fragments pricing coordination across national markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and thermal performance tier. Premium cold storage panels with cam-lock joint engineering command substantial markups over commodity wall systems due to BIS and CE marking compliance costs. Cost compression in standard wall panels is intensifying because Indian and Chinese producers are expanding export capacity. Agricultural buyers in Brazil exhibit the highest price sensitivity, while German pharmaceutical cold chain operators prioritize guaranteed thermal outcomes over unit cost.
Supply Chain Analysis
Steel-facing laminates rest on integrated producers in Germany, China, and India, with Yangtze River Delta clusters supplying both domestic assembly and regional export markets. Expanded polystyrene beads, pre-coated metal coils, and thermal break gasket systems constitute the critical input trinity. Single-source vulnerability concentrates in benzene-derived styrene monomer supply from petrochemical complexes. Distribution runs through regional fabricator networks that perform on-site panel assembly and joint sealing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPS sandwich panels market functions as a stable compounder, with EU Green Deal renovation mandates providing durable demand visibility across multi-year building stock upgrade cycles.
For Market Incumbents: Hedge margin exposure to polystyrene feedstock volatility through backward integration into insulation core production or long-term benzene supply agreements. Capacity addition in Maharashtra and Telangana secures positioning in India's pharmaceutical cold chain expansion. CE marking harmonization investments defend against emerging Turkish and Southeast Asian competitors. For New Entrants and Emerging Players: Capture the controlled-atmosphere agricultural facilities segment in Brazil's Minas Gerais and São Paulo states, where modular envelope adoption is accelerating fastest among livestock operators. Refrigeration-compatible joint detailing for ultra-low-temperature applications offers premium positioning distinct from commoditized wall panels. Partner with Brazilian ANVISA-certified installation contractors to bypass thermal bridging engineering expertise constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking in-house steel-facing production, presenting consolidation targets with installation network assets. The five-to-ten-year viability window favors envelope specialists with thermal modeling capabilities over pure component suppliers. Watch BIS certification timeline compression in India as the inflection signal for procurement pattern shifts toward guaranteed performance contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Production | Captive polystyrene supply shields Kingspan and ArcelorMittal from benzene price volatility. |
| Refrigeration-Compatible Joint System Development | Specialized cam-lock engineering captures premium positioning in German pharmaceutical cold storage. |
| BIS Certification Fast-Track Investment | Accelerated thermal testing approval compresses commissioning timelines for Indian commercial projects. |
| Controlled-Atmosphere Agricultural Partnership | Modular envelope alliances with Brazilian livestock operators open tropical climate management demand. |
| EU F-Gas Regulation Compliance Portfolio | Tighter envelope specifications align panel offerings with lower-GWP refrigeration system transitions. |
Research Methodology
Coverage spans Germany, China, India, Brazil, and the United States, with primary inputs from each market's construction and cold storage operator base. Plant managers at panel fabrication facilities, procurement leads at third-party logistics operators, thermal engineering consultants, and regulatory compliance officers provided structured interviews. Secondary validation drew from EU ECHA additive disclosure databases, Indian BIS certification registries, Brazilian ANVISA pharmaceutical storage guidelines, and customs trade flows for steel-facing laminates. Bottom-up capacity estimates and top-down demand projections were triangulated against disclosed expansion announcements.
Granularity-level modeling distinguished cold storage panels from standard wall and roof systems, with separate thermal performance tiering for sub-zero pharmaceutical applications versus controlled-atmosphere agriculture. End-user segmentation captured industrial, agricultural, residential, and commercial procurement patterns. CAGRs were derived from installed base replacement cycles and new construction absorption rates. Feedstock cost indices for benzene and styrene monomer, plus steel coil pricing from Yangtze River Delta exchanges, informed margin sensitivity scenarios.
Feedstock price spikes, regulatory certification delays, and refrigeration technology transitions are the dominant revision risks to demand assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Liquid Applied Roofing Market