
 Detox Drinks Market | 2026-2036
Detox Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Detox Drinks Market Analytics
A capital-intensity divergence between cold-pressed infrastructure and ambient-ready bottling is reorganizing competitive tiers in the detox drinks sector. GT's Living Foods leverages captive fermentation capacity to sustain margin control across its kombucha portfolio. Suja Life LLC anchors West Coast distribution density through refrigerated supply chain dominance. Hain Celestial Group competes via shelf-stable formulation expertise that extends retail reach beyond premium cold-chain outlets.
Detox drinks comprise formulated beverages containing botanical extracts, cold-pressed juices, or fermented substrates designed to support hepatic function and eliminate metabolic byproducts through diuresis or antioxidant pathways. Manufacturing spans high-pressure processing at sub-100°F to preserve enzymatic activity, or thermal pasteurization for ambient distribution. The herbal product type dominates volume through turmeric, dandelion, and milk thistle formulations with established efficacy signaling. Online retailers represent the fastest-expanding distribution channel as direct-to-consumer subscription models capture repeat purchase economics. Organic labeling commands price premiums that concentrate margin pools among certified supply chains.
The FDA governs health claim substantiation under 21 CFR 101.93 while USDA Organic certification dictates ingredient sourcing and processing standards for label-bearing products. EFSA's health claims regulation in Europe restricts liver detoxification assertions, shaping formulation marketing and forcing repositioning around general wellness framing. Stakeholders must monitor evolving clean-label enforcement intensity and decide between premium refrigerated positioning or ambient scale economics before channel commitments harden.
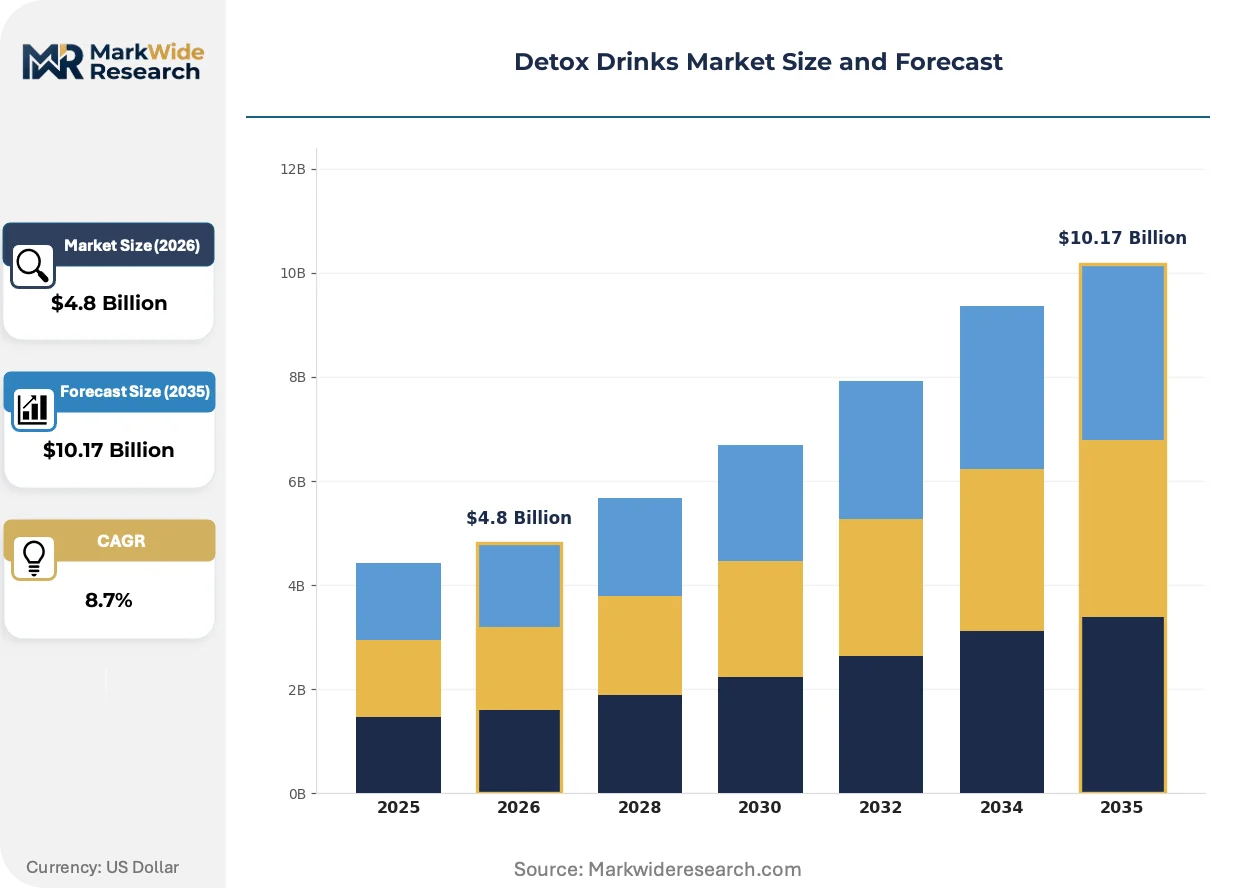
Market Dynamics
The EU Green Deal's packaging sustainability mandates are forcing material transitions across the detox drinks sector, while refrigerated supply chain economics and ambient-ready formulation paths diverge competitive positioning between premium and mass-market tiers.
Growth Catalysts
- Fitness protocol normalization:Athletic recovery regimens now embed functional beverages as standard post-workout consumption, expanding repeat purchase frequency among gym-affiliated consumers.
- USDA Organic certification premiums:Certified supply chains command sustained price advantages in North American retail, concentrating margin pools among compliant producers.
- Direct-to-consumer subscription models:Online retailers capture recurring revenue economics through automated replenishment platforms, reducing customer acquisition costs over repeat cycles.
Market Restraints
- Cold-chain infrastructure capex:High-pressure processing equipment and refrigerated distribution networks require substantial capital deployment, limiting entrant scale.
- EFSA health claims restriction:European liver detoxification assertions face regulatory prohibition, forcing costly repositioning around general wellness framing.
- Thermal pasteurization trade-offs:Ambient-stable formulations sacrifice enzymatic activity claims, compressing differentiation in shelf-stable segments.
Strategic Opportunities
- German premium consumption anchoring:Kombucha and fermented detox traditions in Germany support higher willingness-to-pay for functional positioning.
- High-pressure processing convergence with aseptic bottling:Hybrid manufacturing technologies bridge quality preservation with extended distribution reach.
- Clean-label enforcement intensity escalation:Stricter FDA 21 CFR 101.93 interpretation creates first-mover advantage for substantiated claim holders.
Industry Challenges
- Fermentation microbiology talent scarcity:Captive kombucha production requires specialized biochemists, constraining capacity expansion timelines.
- Dual certification compliance burden:Organic plus non-GMO verification processes extend product launch cycles and raise administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detox Drinks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Fruit Blend, Vegetable Blend, Infused Water Target Audience: Health Conscious Consumers, Fitness Enthusiasts, Millennials, Detox Regulars Distribution Channel: Online Retailers, Supermarkets, Health Stores, Direct Sales Labeling Type: Organic, Non-GMO, Sugar-Free, Gluten-Free |
| Companies Covered | Pukka Herbs, Project Juice, Suja Life LLC, GT's Living Foods, Jus By Julie, Pressed Juicery, Hain Celestial Group, Health-Ade Kombucha, Raw Generation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detox Drinks Market Evolving Landscape
Refrigerated supply chain dominance is fragmenting as ambient-stable technologies mature, while regulatory enforcement tightens around health claim substantiation and clean-label verification protocols.
High-pressure processing at sub-100°F preserves enzymatic activity in cold-pressed formulations. Fitness enthusiasts and premium retailers adopt this technology for functional integrity signaling. Thermal pasteurization is displacing HPP in mid-market SKUs as brands prioritize distribution density over nutrient retention claims.
EFSA's health claims regulation restricts liver detoxification assertions across European marketing. Formulators must reposition around antioxidant or general wellness framing without specific organ-targeted language. Kombucha and herbal segments in Germany, France, and Netherlands face the steepest compliance recalibration.
Subscription-based replenishment models now dominate direct-to-consumer acquisition strategies. Traditional retail slotting fees and distributor markups face compression as brands build proprietary digital channels. This pattern concentrates in North American urban markets with established cold-chain delivery infrastructure.
Detox Drinks Market Segmentation
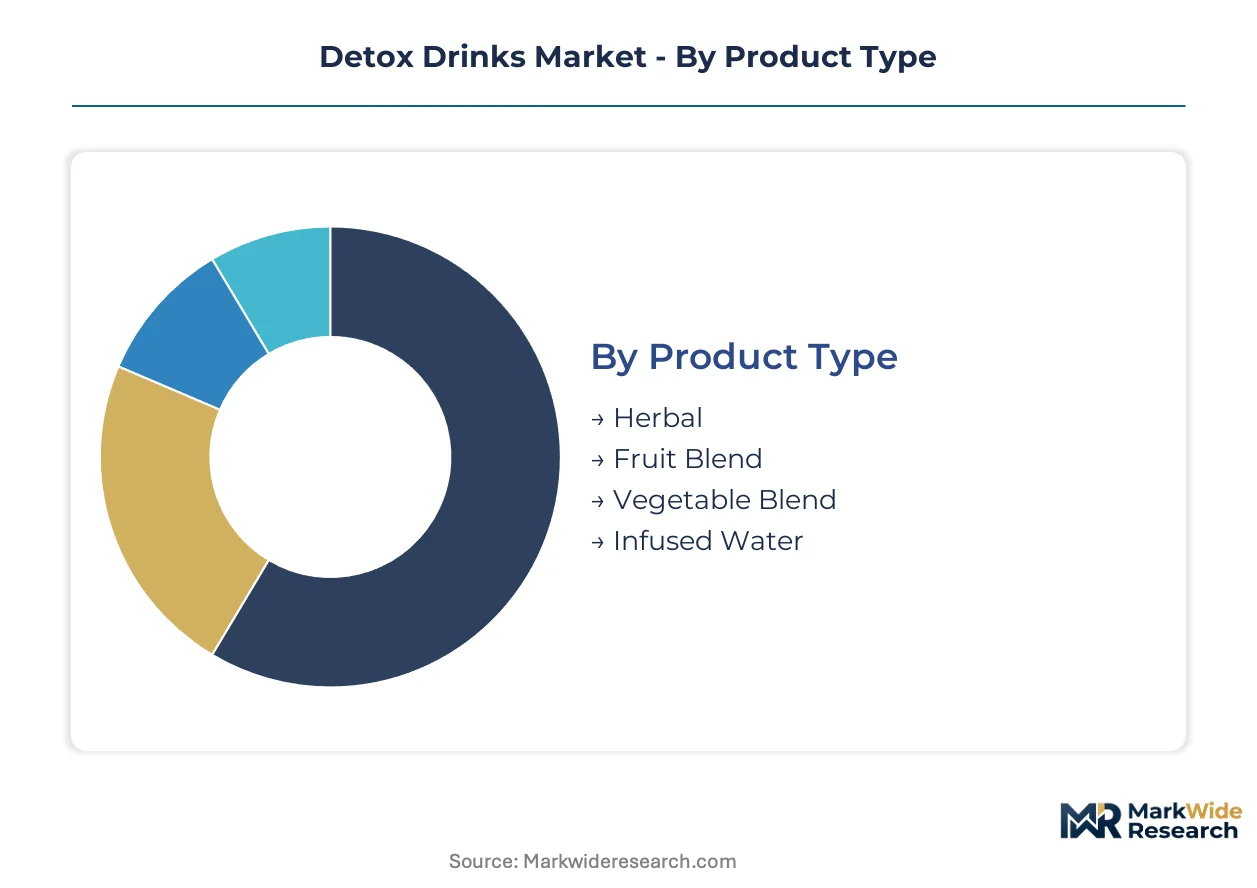
Segmentation in detox drinks determines channel economics and margin capture. Cold-chain requirements, certification premiums, and consumption occasion specificity create divergent profit pools across product and audience dimensions.
Product Type:
Herbal formulations flow through health stores and premium online channels. Fruit blends dominate supermarket velocity. Vegetable concentrates and infused waters split between fitness channels and mass retail.
- Herbal:Turmeric, dandelion, and milk thistle extracts form the functional core. EFSA restrictions on liver detox claims in Germany and France force antioxidant repositioning. Kombucha fermentation capacity concentrates margin among captive producers.
- Fruit Blend:Cold-pressed combinations of citrus, berry, and tropical fruits preserve enzymatic activity through high-pressure processing. Fitness enthusiasts in urban US markets drive repeat subscription economics through direct-to-consumer platforms.
- Vegetable Blend:Green juice formulations featuring kale, spinach, and celery target nutrient density positioning.
- Infused Water:Low-calorie botanical extracts in still or sparkling formats compete with conventional bottled water.
By volume, Fruit Blend leads. By growth pace, Herbal is climbing the fastest.
Target Audience:
Audience segmentation determines pricing architecture and channel investment. Premium positioning targets biochemically engaged consumers. Volume scaling requires mass-market accessibility.
- Health Conscious Consumers:Broad demographic seeking general wellness benefits through routine functional beverage integration. Supermarket and online retailers capture this demand through subscription replenishment models.
- Fitness Enthusiasts:Gym-affiliated consumers embed detox drinks in post-workout recovery protocols. Athletic recovery regimens in Germany and the United States normalize repeat purchase frequency through specialized health stores and direct sales.
- Millennials:Digital-native cohort purchasing through mobile-optimized platforms with clean-label verification requirements.
- Detox Regulars:Habitual consumers pursuing periodic cleansing protocols with high willingness-to-pay for organic certification.
Health Conscious Consumers anchor volume baselines. Fitness Enthusiasts generate the steepest expansion trajectory.
Distribution Channel:
Channel selection locks in margin structure through cold-chain requirements and slotting fee exposure. Digital infrastructure investment separates scaling strategies.
- Online Retailers:Direct-to-consumer platforms with automated replenishment reduce customer acquisition costs over repeat cycles. Subscription models in North American urban markets with established cold-chain delivery infrastructure concentrate recurring revenue.
- Supermarkets:Mass retail placement requires ambient-stable formulation or refrigerated section negotiation. Thermal pasteurization trade-offs compress differentiation but extend geographic reach beyond premium outlets.
- Health Stores:Specialty retail with trained staff enables premium pricing for certified organic and high-pressure processed SKUs.
- Direct Sales:Brand-controlled channels bypass distributor markups through proprietary digital infrastructure and fitness affiliate networks.
Supermarkets maintain volume leadership. Online Retailers are gaining share fastest.
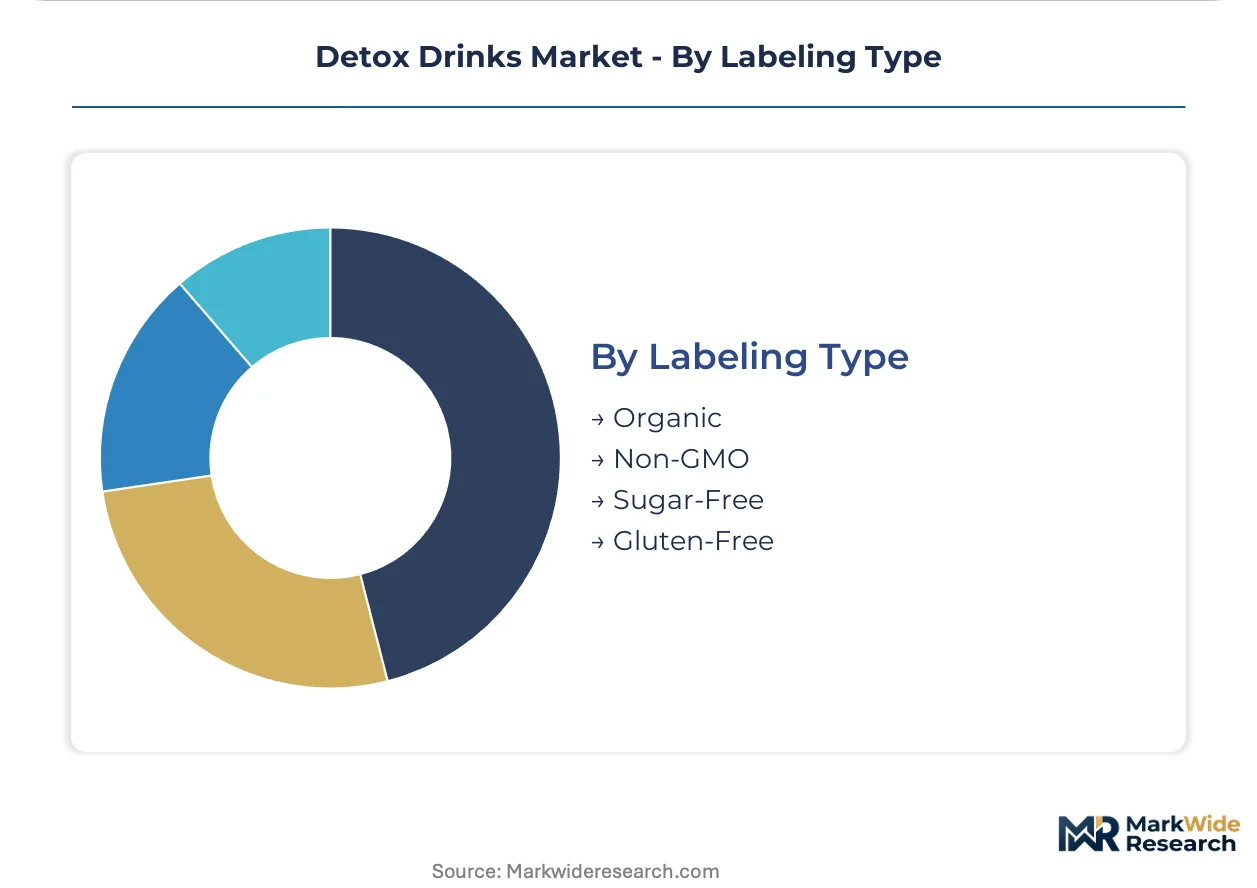
Labeling Type:
Certification tiering creates price stratification and supply chain compliance burdens. Dual verification extends launch timelines but captures premium positioning.
- Organic:USDA certification dictates ingredient sourcing and processing standards. Certified supply chains command sustained price advantages in North American retail, concentrating margin pools among compliant producers with audited farm relationships.
- Non-GMO:Verification through third-party testing protocols addresses consumer skepticism toward biotechnology. European demand in Germany and Netherlands supports non-GMO premiums alongside organic claims.
- Sugar-Free:Natural and artificial sweetener alternatives target metabolic health positioning and diabetic-friendly formulations.
- Gluten-Free:Certification relevant for celiac and sensitivity positioning in grain-conscious consumer segments.
Organic labeling leads by revenue concentration. Non-GMO is expanding most quickly as European clean-label enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in detox beverages favor producing nations with established fermentation infrastructure and cold-chain logistics. Germany and the United States generate trade surpluses in premium kombucha and cold-pressed formulations. Import dependency concentrates in markets lacking domestic HPP capacity or organic certification ecosystems.
United States
Fitness enthusiasts in Los Angeles and New York Metro drive subscription economics through direct-to-consumer platforms. FDA 21 CFR 101.93 enforcement on health claims shapes formulation marketing around antioxidant rather than detoxification language. California's captive kombucha production capacity anchors West Coast supply chains for national distribution.
Germany
Kombucha and fermented detox traditions support premium willingness-to-pay in Berlin and Munich health stores. EU Green Deal packaging mandates force material transitions toward recyclable substrates. Bavaria's organic juice processing clusters concentrate high-pressure processing equipment for export-grade formulations.
United Kingdom
London's wellness-oriented consumers normalize functional beverage consumption in post-workout protocols. EFSA health claims restrictions prohibit liver detoxification assertions, compelling general wellness repositioning. Southeast England's refrigerated distribution networks enable same-day delivery economics for subscription models.
France
Parisian retail channels embed organic-certified juices in premium supermarket assortments. ANSM oversight of botanical extract safety influences herbal formulation standards. Île-de-France's cold-pressed bottling facilities serve cross-border demand in Benelux markets.
Japan
Tokyo's health-conscious demographic integrates detox drinks into traditional fermentation-influenced diets. METI guidelines on functional food labeling constrain explicit organ-targeted claims. Kanto region's aseptic bottling technology bridges quality preservation with ambient distribution reach.
Detox Drinks Market Competitive Landscape
Concentration sits with fermentation-captive specialists and refrigerated supply chain dominators. The market structures around three tiers: premium cold-pressed players with HPP infrastructure, ambient-stable formulators with mass retail penetration, and direct-to-consumer platforms with proprietary subscription technology. Strategic moves center on hybrid manufacturing adoption and clean-label certification stacking.
Within the fermentation-specialist tier, GT's Living Foods and Health-Ade Kombucha exemplify captive production models. Suja Life LLC occupies a position among West Coast cold-pressed formulators with refrigerated distribution density. Hain Celestial Group anchors the shelf-stable segment through ambient-ready formulation expertise. These three archetypes represent the competitive vectors separating premium positioning from scale economics.
| Leading Market Players |
|---|
| Pukka Herbs |
| Project Juice |
| Suja Life LLC |
| GT's Living Foods |
| Jus By Julie |
| Pressed Juicery |
| Hain Celestial Group |
| Health-Ade Kombucha |
| Raw Generation |
| Others |
Value Network & Pricing Analysis
USDA Organic certification gates both supply qualification and price differentiation in the detox drinks sector, concentrating margin pools among producers with audited farm relationships while forcing non-certified competitors into commodity positioning. Fitness enthusiasts and detox regulars pay sustained premiums for certified supply chains, compressing margins for ambient-stable formulators lacking organic credentials.
Pricing Analysis
Health conscious consumers anchor a three-tier pricing structure across premium, standard, and economy levels in the detox drinks market. Price differentiation stems from certification grade—USDA Organic and Non-GMO Project Verified command 20-40% shelf price premiums—and cold-chain infrastructure investment, with refrigerated HPP products pricing above ambient-stable alternatives. Cost compression in mid-market SKUs is intensifying because thermal pasteurization sacrifices enzymatic activity claims, eroding differentiation. Fitness enthusiasts show least price sensitivity due to protocol-driven repeat purchase habits, while supermarket mass-market buyers exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for kombucha SCOBY cultures and cold-pressed botanical extracts extend production planning cycles beyond conventional beverage categories. Supply concentrates in the United States, Germany, and Japan, with California and Bavaria anchoring high-pressure processing equipment clusters and captive fermentation capacity. Raw material dependencies include organic turmeric root, milk thistle extract, and live kombucha cultures sourced from certified cultivators. Single-source vulnerability in specialized biochemist talent for fermentation microbiology constrains capacity expansion. Distribution runs through refrigerated networks for premium tiers and ambient-ready mass retail for shelf-stable formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detox drinks represent an early-cycle expansion story as fitness protocol normalization embeds functional beverages in post-workout regimens, accelerating repeat purchase frequency beyond traditional wellness categories.
For Market Incumbents: Fortify margin control through captive kombucha fermentation capacity and backward integration into organic ingredient sourcing. Cold-chain infrastructure capex requirements create defensive moats against ambient-stable entrants, while dual certification compliance investments raise barriers for smaller competitors lacking administrative scale. For New Entrants and Emerging Players: USDA Organic certification fast-tracks premium positioning in German health stores and North American direct-to-consumer channels where willingness-to-pay concentrates. White-space targets include sugar-free diabetic-friendly formulations and hybrid HPP-aseptic bottling technologies bridging quality preservation with extended distribution reach. A mobile-optimized subscription platform with automated replenishment captures recurring revenue economics in urban fitness corridors. For Investors and Strategic Acquirers: EFSA health claims restriction reshapes the acquisition landscape toward general wellness repositioning capabilities rather than organ-targeted formulation expertise. Long-term viability favors fermentation-captive specialists with proprietary SCOBY libraries and refrigerated supply chain density. The signal to watch is clean-label enforcement intensity escalation under FDA 21 CFR 101.93 interpretation, creating first-mover advantage for substantiated claim holders.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Buildout | GT's Living Foods model demonstrates margin control through proprietary SCOBY cultures and in-house biochemistry talent. |
| Hybrid HPP-Aseptic Bottling Investment | Japanese Kanto region technology bridges enzymatic preservation with ambient distribution reach beyond cold-chain constraints. |
| Direct-to-Consumer Subscription Platform | Suja Life LLC's West Coast density proves recurring revenue economics reduce customer acquisition costs over repeat cycles. |
| Dual Certification Compliance Stacking | Organic plus Non-GMO verification captures European clean-label premiums in Germany and Netherlands retail channels. |
| Sustainability Repositioning Under EU Green Deal | Packaging material transitions toward recyclable substrates align with Bavaria's organic juice processing cluster mandates. |
Research Methodology
Desk research of FDA 21 CFR 101.93 guidance documents, EFSA health claims registers, and USDA Organic certification databases preceded structured interviews with kombucha production biochemists, health store category buyers, cold-chain logistics coordinators, and direct-to-consumer platform operators. Secondary validation drew from Nielsen retail audit data, customs import records for botanical extracts, and SEC filings of publicly traded beverage companies. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Variance decomposition across product type, target audience, distribution channel, and labeling certification dimensions drove analytical framework construction. Modeled inputs included gym affiliation penetration rates, organic certification compliance costs, and refrigerated delivery infrastructure density by metropolitan area. CAGRs derived from segment-level trajectory blending rather than single-point extrapolation, with cross-validation against historical functional beverage adoption curves.
Decision-makers should treat outputs as directional under sustained fitness protocol normalization and stable clean-label enforcement intensity; material deviation in regulatory interpretation or consumer wellness framing would warrant model refresh. Specific risk factors include EFSA health claims restriction expansion, cold-chain energy cost volatility, and fermentation microbiology talent scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hot Cocoa Mix Market
Beverages
Sparkling Bottled Water Market
Beverages
Spring Water Market
Beverages
Ginger Beer Market
Beverages
GCC Juice Market
Beverages
Sarsaparilla Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Global Electrolyte Drinks Market
Beverages
Relaxation Beverages Market
Beverages
North America Energy Drink Market
Beverages
China Orange Juice Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Caffeine Mint Market
Beverages
Middle East and Africa Ready to Drink Beverages Market