
 Out-Of-Home Coffee Market | 2026-2036
Out-Of-Home Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Out-Of-Home Coffee Market Outlook
Multi-source bean procurement is recalibrating how major chains manage supply risk and origin transparency. Starbucks Corporation leverages direct-trade relationships with cooperatives across Latin America and East Africa to secure arabica volumes. Nestlé SA anchors its out-of-home portfolio through licensed Nespresso systems in hotels and offices across Europe. JAB Holding Company Sàrl competes via a portfolio of branded chains including Peet's and Caribou, concentrating on drive-through density in suburban United States markets.
Out-of-home coffee comprises beverages prepared and served for immediate consumption outside residential settings, typically brewed at 195–205°F with 9-bar pressure for espresso extraction, then dispensed through commercial equipment designed for high-throughput service environments. The primary commercial purpose is delivering standardized, repeatable sensory experiences to time-constrained consumers in transit or workplace adjacencies. Espresso-based formats dominate revenue contribution in European cafés, while cold brew and specialty offerings represent the fastest-expanding margin pool in United States coastal markets. Instant out-of-home solutions, primarily through automated vending and workplace machines, occupy a mature, price-sensitive segment with thinner profitability.
The United States Food and Drug Administration enforces food-contact substance regulations for paper cups and plastic liners, while the European Union's Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that increase operational compliance costs for cross-border chains. China's State Administration for Market Regulation monitors food safety in commercial beverage preparation through GB standards for water quality and equipment sanitation. Stakeholders must monitor how diverging packaging compliance timelines across Washington, Brussels, and Beijing reshape capital allocation for cup-to-cup standardization.
Market Dynamics
Single-use packaging bans across the European Union and California are forcing capital reallocation toward compostable cup and lid R&D, while digital ordering integration in Chinese urban centers is compressing service times and reshaping real estate requirements for café operators.
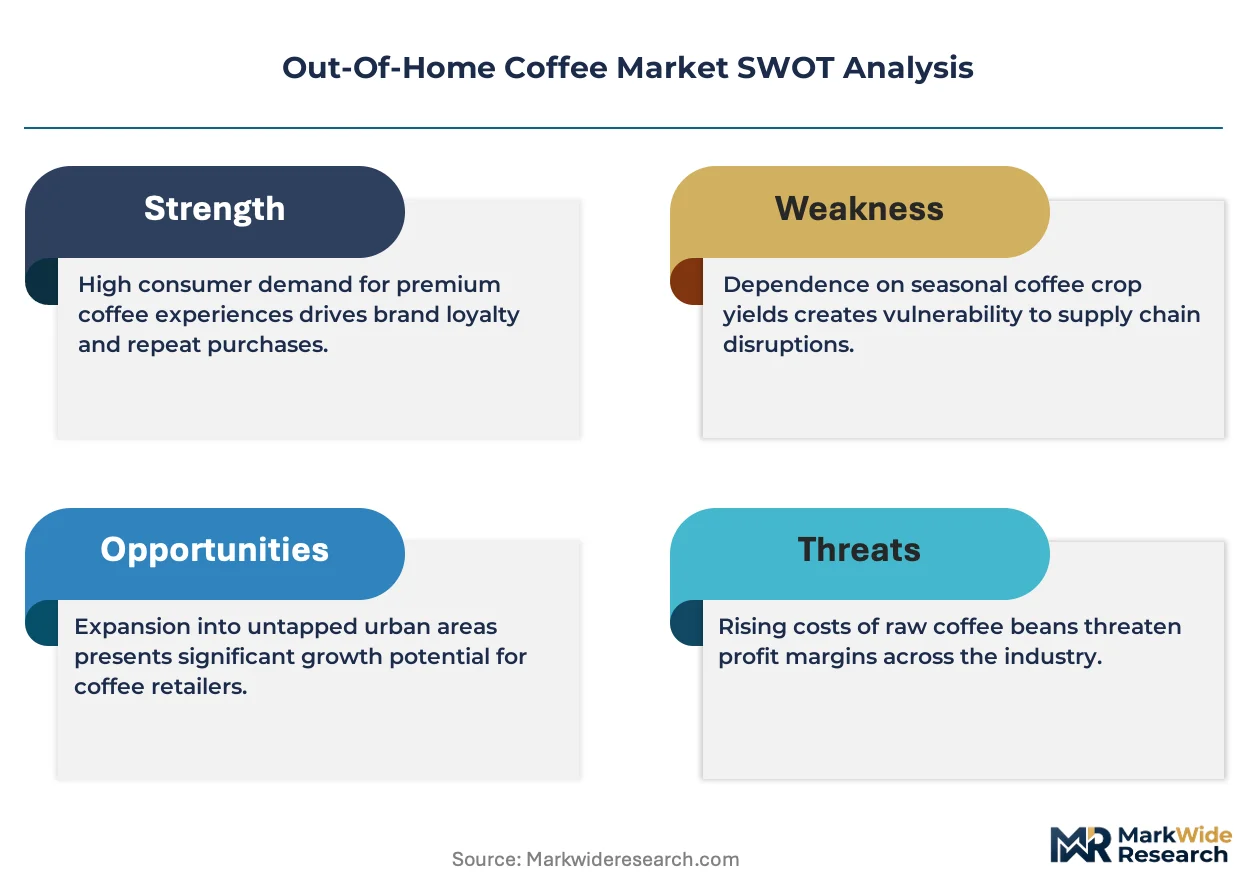
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Extended producer responsibility schemes accelerate investment in circular packaging infrastructure across licensed café networks and automated vending estates.
- Specialty cold brew extraction:Nitrogen-infused formats and extended steeping protocols command margin premiums in United States coastal commuter corridors.
- Urban middle-class concentration:Shanghai and Beijing office districts sustain chain expansion through mobile-first ordering platforms integrated with commercial real estate lobbies.
Market Restraints
- Arabica price volatility:Weather-driven yield fluctuations in Brazilian highlands and Colombian Andes compress roasting margins for standardized espresso programs.
- Equipment import dependency:Commercial espresso machine manufacturing concentrates in Italian and Swiss engineering clusters, exposing operators to currency and shipping cost swings.
- Energy input cost spikes:Commercial brewing at 195–205°F with 9-bar pressure demands sustained electrical load, making European café operators vulnerable to grid price reforms.
Strategic Opportunities
- Workplace automated systems:Licensed capsule and bean-to-cup formats in corporate campuses and hotel lobbies capture recurring revenue with lower labor intensity than full-service formats.
- Compostable mandate alignment:California's phased single-use plastic restrictions create first-mover advantage for chains with certified fiber-based cup and lid supply chains.
- Rural Chinese penetration:Tier-two and tier-three city expansion beyond Shanghai and Beijing accesses underpenetrated white-collar density with lower rent per square meter.
Industry Challenges
- Barista skill scarcity:Latte art and manual espresso calibration expertise concentrates in coastal United States and Western European labor pools, constraining format consistency in expansion markets.
- Cross-border compliance fragmentation:Divergent FDA food-contact substance rules, EU extended producer responsibility timelines, and China's GB sanitation standards force multi-jurisdictional quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out-Of-Home Coffee Market |
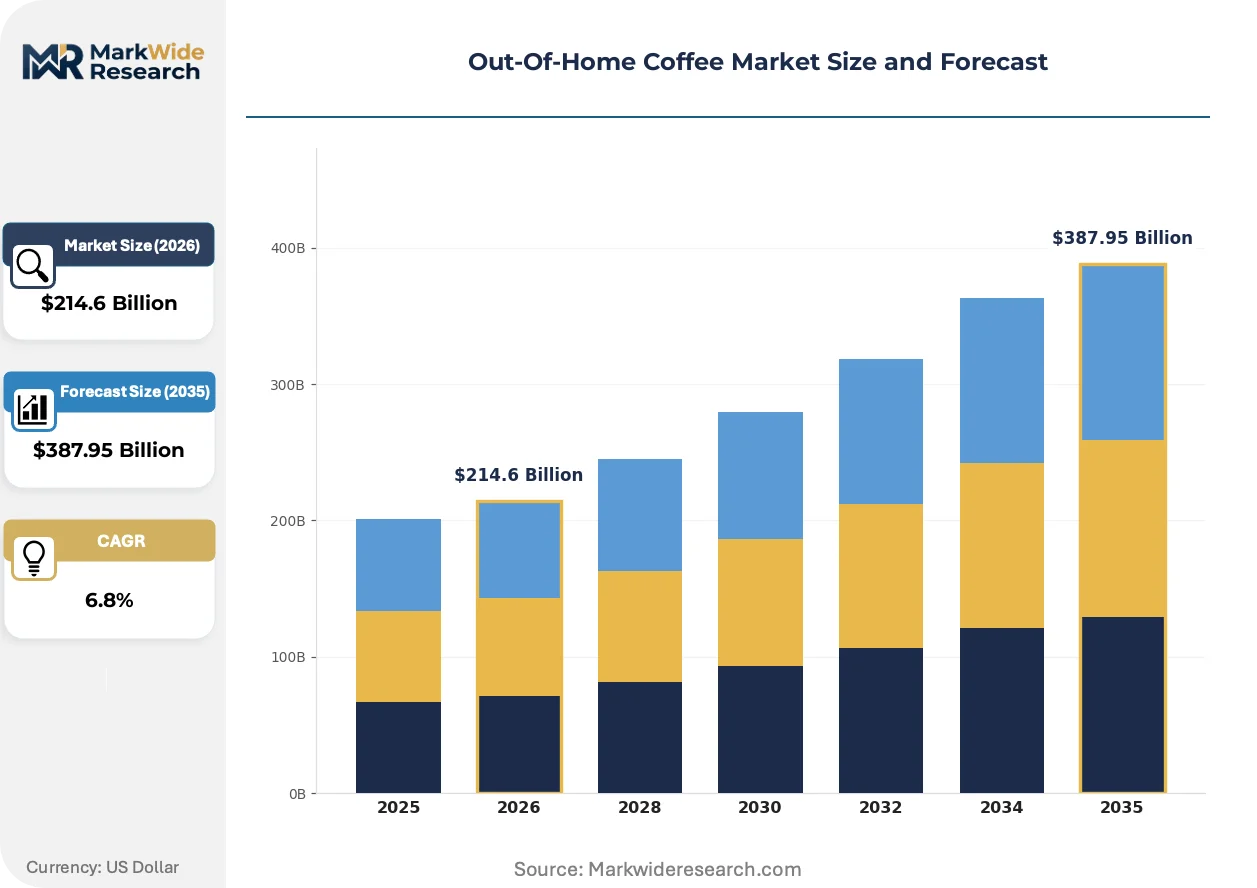
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso, Cold Brew, Specialty, Instant Service Type: Cafés, Food Trucks, Coffee Kiosks, Chains Customer Type: Office Workers, Students, Tourists, Commuters Distribution Channel: Online Delivery, Retail Outlets, Events, Partnerships |
| Companies Covered | Starbucks Corporation, Nestlé SA, JAB Holding Company Sàrl, The Coca-Cola Company, Luigi Lavazza SpA, The J.M. Smucker Company, Dunkin' Brands, Tchibo GmbH, Tim Hortons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out-Of-Home Coffee Market Strategic Shifts
Automation is compressing labor models while regulatory packaging mandates and shifting commuter consumption patterns are redefining format economics and service location strategies.
Nitrogen-infused cold brew systems are absorbing front-of-house labor roles in high-throughput United States suburban drive-through locations. Chains deploy automated dispensing with integrated flavor dosing to reduce order-to-handoff intervals. This technology is absorbing the traditional barista station, enabling smaller physical footprints and 24-hour service windows without overnight staffing.
California's single-use plastic ban and the EU's Packaging and Packaging Waste Directive are mandating fiber-based cup and lid specifications with defined compostability windows. Cross-border chains face capital duplication as FDA food-contact rules diverge from Brussels-mandated migration testing protocols. European licensed operators and United States coastal independents are responding with dual-sourcing strategies and regional packaging SKUs.
Mobile pre-ordering with designated pickup points is displacing queue-based service in Chinese urban commercial districts. Office workers in Beijing and Shanghai now expect sub-two-minute retrieval from lobby-installed smart lockers. This behavioral shift concentrates demand in high-rise-adjacent locations and compresses tolerance for traditional sidewalk café waiting environments.
Out-Of-Home Coffee Market Segmentation
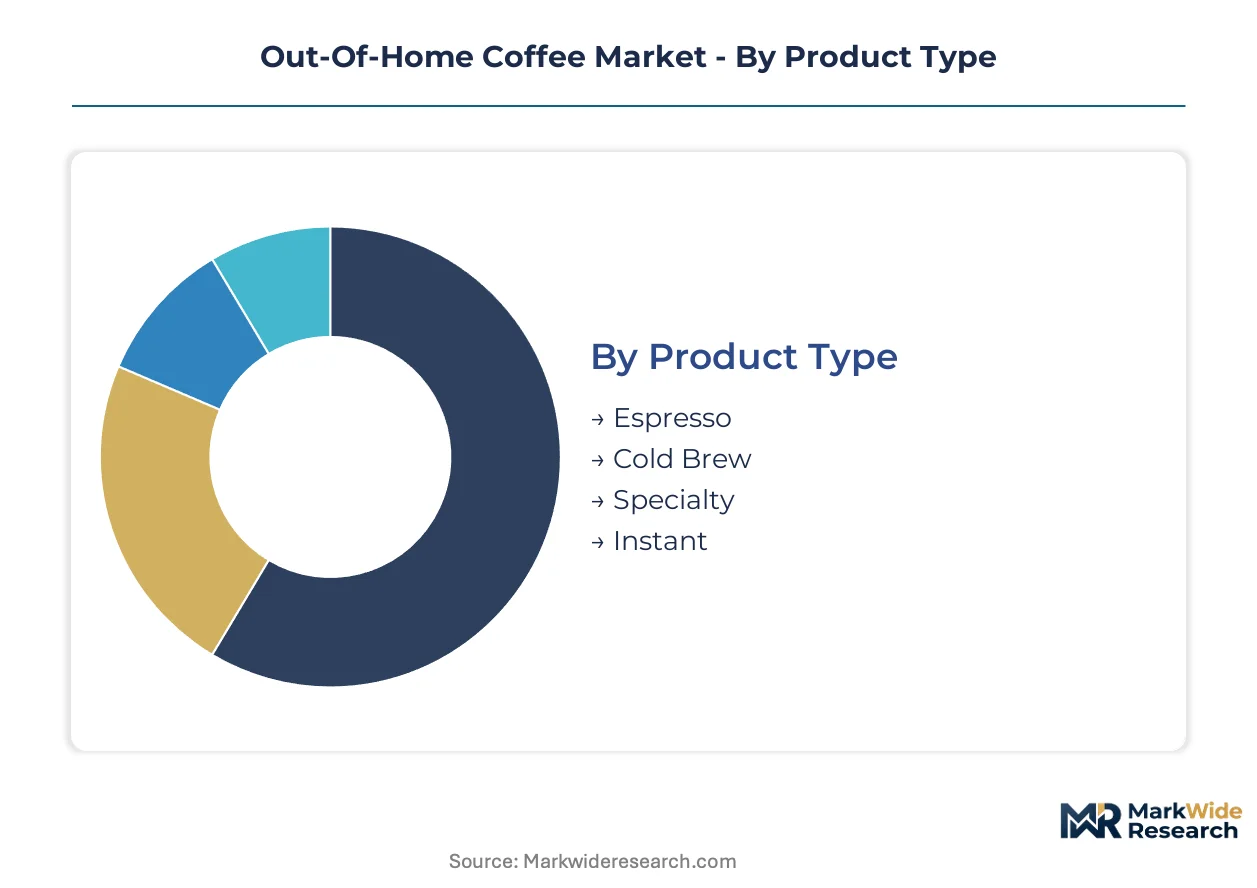
Segmentation in out-of-home coffee reveals how brewing format, service infrastructure, and consumer occasion intersect to determine margin structure and capital intensity. Each category carries distinct certification burdens from FDA food-contact rules to EU compostability mandates that reshape equipment and packaging procurement.
Product Type:
FDA food-contact substance regulations govern paper cup liners for hot formats, while EU Packaging and Packaging Waste Directive compliance burdens concentrate in single-use cold brew packaging with shorter compostability windows.
- Espresso:Extracted at 195–205°F with 9-bar pressure through commercial machines, this format demands Italian and Swiss equipment imports. United States office districts sustain demand through workplace lobby installations where speed competes with quality consistency.
- Cold Brew:Extended steeping protocols and nitrogen infusion systems command margin premiums in coastal commuter corridors. California's single-use plastic bans force fiber-based cup and lid R&D investment that compresses near-term profitability despite volume growth.
- Specialty:Latte art and manual calibration requirements concentrate barista expertise in Western labor pools, constraining format standardization in expansion markets.
- Instant:Automated vending and workplace capsule systems occupy mature price-sensitive segments with thinner margins and lower labor intensity.
Leading the category by volume: Espresso. Growing fastest: Cold Brew.
Service Type:
Capital deployment varies dramatically across physical footprints, from high-rent café buildouts to mobile units with minimal fixed infrastructure.
- Cafés:Full-service formats with espresso bars and seating require substantial lease commitments in urban commercial districts. Shanghai and Beijing office lobbies sustain premium locations through mobile-integrated pre-ordering platforms.
- Food Trucks:Mobile permits and commissary kitchen requirements vary by municipal jurisdiction, creating operational complexity for cross-regional operators.
- Coffee Kiosks:Compact smart-locker formats in Chinese high-rise adjacencies capture sub-two-minute retrieval expectations without seating overhead.
- Chains:Standardized equipment and supply contracts enable rapid suburban drive-through density in United States markets where nitrogen-infused automation reduces front-of-house labor.
Chains dominate capital deployment. Kiosks expand most quickly in urban China.
Customer Type:
Occasion-based demand patterns determine daypart concentration and pricing power across commuter, workplace, and leisure consumption.
- Office Workers:Morning peak demand in commercial districts drives loyalty program adoption and subscription models for recurring revenue capture.
- Students:Price-sensitive volume concentrates near campus locations with extended hours and study-conducive seating configurations.
- Tourists:Destination cafés in historic European centers and Asian gateway cities command experience premiums through origin storytelling and brewing theater.
- Commuters:Drive-through and transit-adjacent formats in United States suburban corridors prioritize order-to-handoff speed over customization depth.
Office workers generate highest frequency. Commuters show steepest expansion trajectory in automated formats.
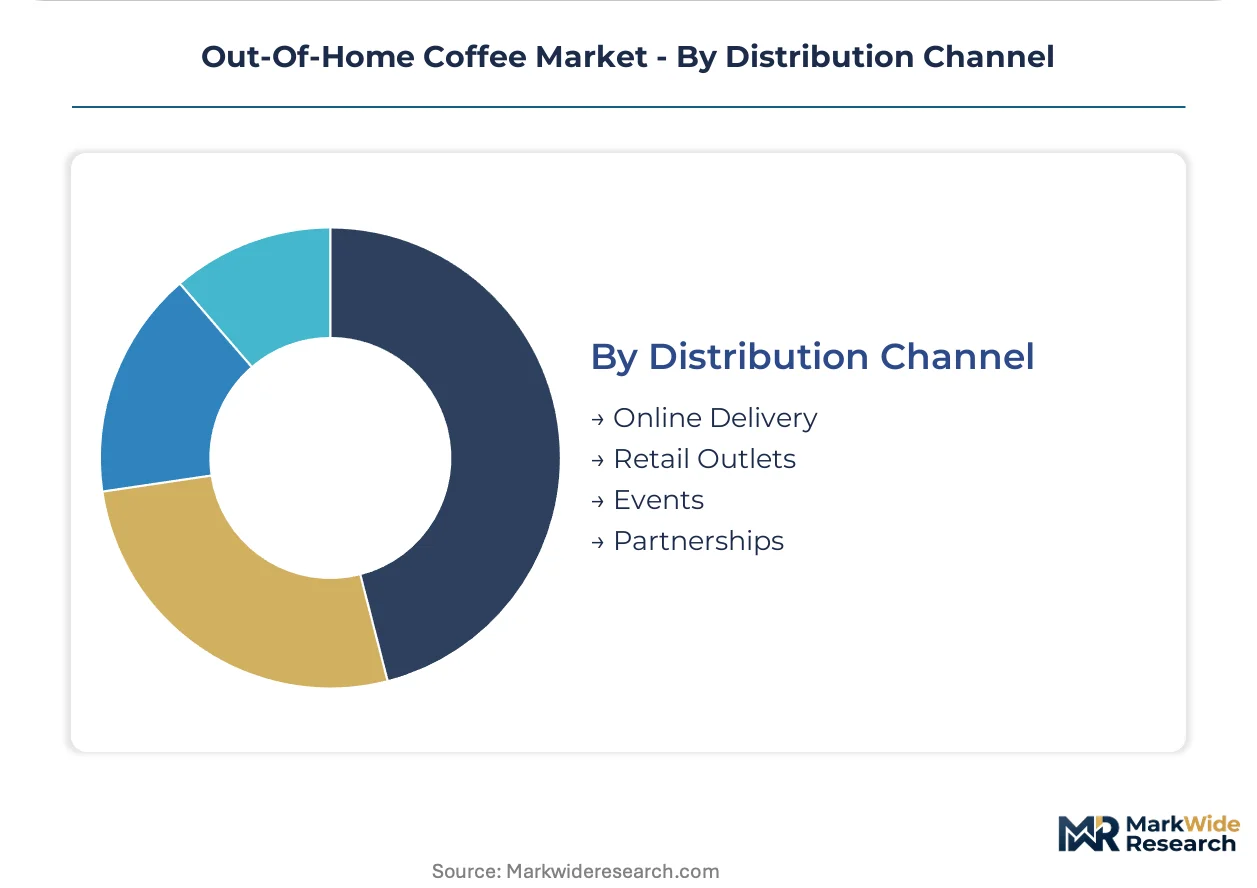
Distribution Channel:
Channel selection determines last-mile cost structure and customer data capture capabilities for retention marketing.
- Online Delivery:Platform commission structures and temperature-maintenance packaging requirements erode margins despite volume accessibility in dense urban markets.
- Retail Outlets:Supermarket and convenience store licensed formats extend reach with lower per-unit labor but reduced brand experience control.
- Events:Festival and conference catering demands mobile equipment resilience and permits that vary by local health authority jurisdiction.
- Partnerships:Corporate campus and hotel lobby licensed systems generate recurring revenue with captive audience concentration and lower customer acquisition cost.
Retail outlets anchor volume. Partnerships gain share fastest through workplace automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class concentration in Shanghai and Beijing office districts sustains chain expansion and digital ordering integration, while suburban United States drive-through density and European packaging compliance timelines reshape capital allocation across major markets.
United States
Coastal commuter corridors in California and New York sustain nitrogen-infused cold brew volume, with office workers driving morning peak demand through mobile loyalty platforms. FDA food-contact substance regulations govern paper cup liners for hot formats, forcing R&D coordination with California's phased single-use plastic restrictions. Chicago and Dallas suburban markets concentrate drive-through automation deployment where nitrogen-infused systems absorb front-of-house labor roles.
China
Shanghai and Beijing office districts generate sub-two-minute retrieval expectations through lobby-installed smart lockers, compressing tolerance for traditional sidewalk café queues. SAMR monitors food safety through GB standards for water quality and equipment sanitation, extending compliance burdens to tier-two city expansions. Shenzhen and Hangzhou technology corridors anchor digital platform integration with commercial real estate developers.
Germany
Munich and Frankfurt workplace lobbies sustain licensed capsule and bean-to-cup system penetration, capturing recurring revenue with lower labor intensity than full-service formats. EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that increase operational compliance costs for cross-border chains. Berlin independent café clusters concentrate compostable packaging R&D investment ahead of Brussels-mandated timelines.
Italy
Milan and Rome historic centers command experience premiums through origin storytelling and brewing theater, anchoring tourist-driven demand concentration. REACH compliance for food-contact materials shapes equipment import specifications from domestic espresso machine manufacturers. Turin engineering clusters concentrate commercial equipment production that supplies global café chains.
Brazil
São Paulo and Rio de Janeiro urban districts sustain arabica sourcing relationships with cooperatives across Minas Gerais highlands, though weather-driven yield fluctuations compress roasting margins. ANVISA food safety regulations govern commercial beverage preparation equipment import and sanitation protocols. Campinas industrial corridor concentrates roasting capacity expansion serving licensed café networks across Latin America.
Out-Of-Home Coffee Market Competitive Environment
Portfolio diversification dominates the current landscape as holding companies consolidate branded chains and licensed systems across multiple service formats. The market structure concentrates around three tiers: multinational beverage conglomerates with out-of-home licensing arms, specialized coffee-focused holding companies with drive-through density strategies, and regional roasting specialists with origin-direct procurement relationships. Strategic archetypes include workplace automation licensors, suburban drive-through consolidators, and premium café experience operators. M&A activity and geographic licensing expansion constitute the dominant competitive moves, with chains acquiring regional players to secure real estate positions in high-growth corridors.
Within the multinational beverage tier, Starbucks Corporation and Nestlé SA exemplify divergent strategic positions. Starbucks anchors premium café experience density with direct-trade procurement relationships across Latin America and East Africa, while Nestlé SA concentrates licensed system penetration in European hotel and office lobbies through automated formats. JAB Holding Company Sàrl occupies the specialized holding company tier, consolidating Peet's and Caribou branded chains with suburban United States drive-through concentration.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Nestlé SA |
| JAB Holding Company Sàrl |
| The Coca-Cola Company |
| Luigi Lavazza SpA |
| The J.M. Smucker Company |
| Dunkin' Brands |
| Tchibo GmbH |
| Tim Hortons |
| Others |
Value Chain & Pricing Dynamics
Barista skill concentration in Western European and United States coastal labor pools widens pricing-tier spreads between premium manual formats and automated economy offerings, as chains absorb certification and training costs into premium positioning while suburban drive-through automation compresses entry-level price points.
Pricing Analysis
Equipment warranty bundling separates premium café installations from unbundled kiosk deployments, with Italian and Swiss espresso machine suppliers including preventive maintenance in high-volume contracts. Pricing stratifies across premium, standard, and economy tiers based on labor intensity and origin certification depth. Cost compression in economy automated segments is intensifying because nitrogen-infusion hardware commoditizes. Students and price-sensitive commuters exhibit highest price elasticity, while office workers in Beijing and Shanghai lobby installations show lowest sensitivity due to employer-subsidized consumption.
Supply Chain Analysis
Reverse logistics for commercial espresso machine refurbishment flows from United States suburban locations back to Turin and Swiss engineering clusters, extending equipment lifecycle and secondary market circulation. Arabica sourcing concentrates in Brazil, Colombia, and Ethiopia, with roasting capacity clustering in Campinas, São Paulo state, and regional hubs serving licensed networks. Supply chains draw from single-origin cooperative relationships vulnerable to weather-driven yield fluctuations. Distribution runs through licensed café networks, automated vending estates, and direct-trade procurement channels serving premium roasting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arabica roasting capacity constraints in Brazilian highlands prop pricing power for origin-direct procurement relationships, sustaining margin premiums for chains with cooperative tie-ins.
For Market Incumbents: Acquire roasting facility assets in Minas Gerais and Campinas corridors to secure arabica supply ahead of weather-driven volatility. Consolidate suburban United States drive-through real estate positions against emerging automated format entrants. Certification investment in EU Packaging and Packaging Waste Directive compliance creates defensive moats as Brussels-mandated timelines accelerate. For New Entrants and Emerging Players: The price-point gap between premium manual espresso and economy automated formats opens white-space in tier-two Chinese cities beyond Shanghai and Beijing saturation. Target workplace lobby installations in Shenzhen and Hangzhou technology corridors with bean-to-cup licensing models. Go-to-market leverage rests on mobile-first pre-ordering platform integration with commercial real estate developers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized coffee-focused holding companies given portfolio diversification across drive-through density and licensed automation formats. Five-to-ten year viability favors operators with backward integration into roasting capacity and origin-direct procurement relationships. Monitor arabica futures volatility and EU compostable packaging certification adoption rates as inflection signals for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Roasting Capacity Expansion | Backward integration into Campinas and Minas Gerais facilities secures arabica supply against weather-driven yield fluctuations. |
| Compostable Packaging Certification | EU Packaging and Packaging Waste Directive compliance creates first-mover advantage in European licensed café networks. |
| Mobile Platform Integration | Pre-ordering platform partnerships with Shanghai and Beijing commercial real estate developers capture sub-two-minute retrieval demand. |
| Drive-Through Automation Deployment | Nitrogen-infused cold brew systems in United States suburban corridors absorb front-of-house labor and enable 24-hour service windows. |
| Origin-Direct Cooperative Partnerships | Latin American and East African cooperative relationships secure arabica volumes with transparency premiums for specialty positioning. |
Study Parameters
Document review covered SEC filings from multinational beverage conglomerates, EU regulatory submissions under Packaging and Packaging Waste Directive, and SAMR GB standard documentation, complemented by interviews with café chain procurement directors, commercial espresso equipment manufacturers, and cooperative export managers. Secondary validation drew from customs trade data, coffee futures exchange records, and commercial real estate leasing databases. Bottom-up volume modeling triangulated against top-down category spend estimates.
Cross-referencing historical volume trajectories against expert panel input anchored the analytical framework across the analysis window. Segmentation dimensions modeled include brewing format, service infrastructure type, customer occasion, and distribution channel. CAGRs were derived from slope analysis of annualized growth patterns. Forecast inputs incorporated arabica price volatility indices and EU regulatory compliance timeline acceleration.
Inputs from cooperative export managers and equipment manufacturer technical directors were available through the study window; gaps in tier-two Chinese city consumption data introduce uncertainty bands around rural penetration assumptions. Forecasts reflect documented assumptions about digital ordering adoption curves and compostable packaging cost trajectories. Practitioners should monitor SAMR enforcement patterns in tier-two cities and California single-use plastic ban implementation phases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
United States Coffee Market
Coffee
Latin America Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bags Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Global Cafe Market
Coffee
India Coffee Roaster Market
Coffee
Green Coffee Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Germany Coffee Market
Coffee
Coffee Capsules Market
Coffee
China Coffee Market
Coffee
North America Coffee Market
Coffee
Middle East Coffee Market
Coffee
Coffee Syrup Market
Coffee
Single-Serve Coffee Containers Market