
 Electrolyte Mixes Market | 2026-2036
Electrolyte Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyte Mixes Market Analysis
Medical patient applications is realigning demand within the electrolyte mixes landscape as clinical hydration protocols expand beyond traditional sports use. Abbott Laboratories leverages its pharmaceutical distribution network to sustain institutional contracts across hospital systems. Liquid I.V. competes through aggressive direct-to-consumer channel control, while Skratch Labs differentiates via clean-label positioning targeted at endurance athletes.
Electrolyte mixes are formulated solutions containing sodium, potassium, magnesium, and chloride ions designed to restore fluid balance and support nerve and muscle function, typically manufactured through spray-drying or liquid blending processes with controlled osmolality parameters. Powder formats dominate unit economics due to lower shipping weights and extended shelf stability, while liquid concentrates capture premium placement in convenience retail. Medical patient end users represent the fastest-growing consumption pool as post-acute care protocols integrate oral rehydration therapy.
The US FDA governs dietary supplement labeling and Good Manufacturing Practice compliance, while the EPA monitors water quality standards affecting production inputs. The EU EFSA sets novel food and health claims boundaries that constrain European formulation marketing. Stakeholders must monitor evolving sodium-reduction mandates across multiple jurisdictions and assess whether reformulation investments or geographic portfolio rebalancing delivers superior returns.
Market Dynamics
The US FDA's updated labeling requirements for dietary supplements are forcing electrolyte mix manufacturers to reformulate sodium content and revise packaging claims across their portfolios. This regulatory pressure compounds with weekend warrior adoption patterns to reshape competitive positioning between medical and sports nutrition applications.
Growth Catalysts
- Post-Acute Care Protocols:Hospital systems in the United States are integrating oral rehydration therapy into discharge planning, expanding institutional procurement of clinical-grade electrolyte formulations.
- Clean-Label Positioning:Endurance athletes now demand third-party certified ingredients, pulling manufacturers toward NSF Certified for Sport and Informed Choice verification standards.
- Spray-Drying Efficiency:Powder production technology improvements reduce moisture content variability, extending shelf stability and enabling lighter shipping weights for direct-to-consumer fulfillment.
Market Restraints
- Potassium Chloride Supply Concentration:Bulk mineral sourcing concentrates in Chilean and Israeli extraction operations, exposing formulators to geopolitical and climate-related disruption risk.
- Sodium-Reduction Mandates:The US FDA voluntary sodium targets and EU EFSA health claim restrictions constrain formulation flexibility for sports positioning.
- Functional Beverage Substitution:Ready-to-drink enhanced waters from Coca-Cola and PepsiCo capture convenience-oriented consumers who bypass powder preparation.
Strategic Opportunities
- Pediatric Medical Applications:Underpenetrated acute gastroenteritis protocols in India present expansion potential for WHO-compliant oral rehydration salts.
- Subscription Channel Development:Direct-to-consumer auto-replenishment models bypass retail slotting fees and capture lifetime value from endurance sports communities.
- Precision Fermentation Minerals:Convergence of synthetic biology with electrolyte production enables bio-identical mineral sourcing with reduced mining dependency.
Industry Challenges
- Electrolyte Stability Expertise:Formulation chemists with osmolality optimization experience command premium compensation, constraining mid-tier manufacturer R&D capacity.
- Dual-Use Certification Timelines:Medical device and dietary supplement pathway divergence at the US FDA extends time-to-market for clinical positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyte Mixes Market |
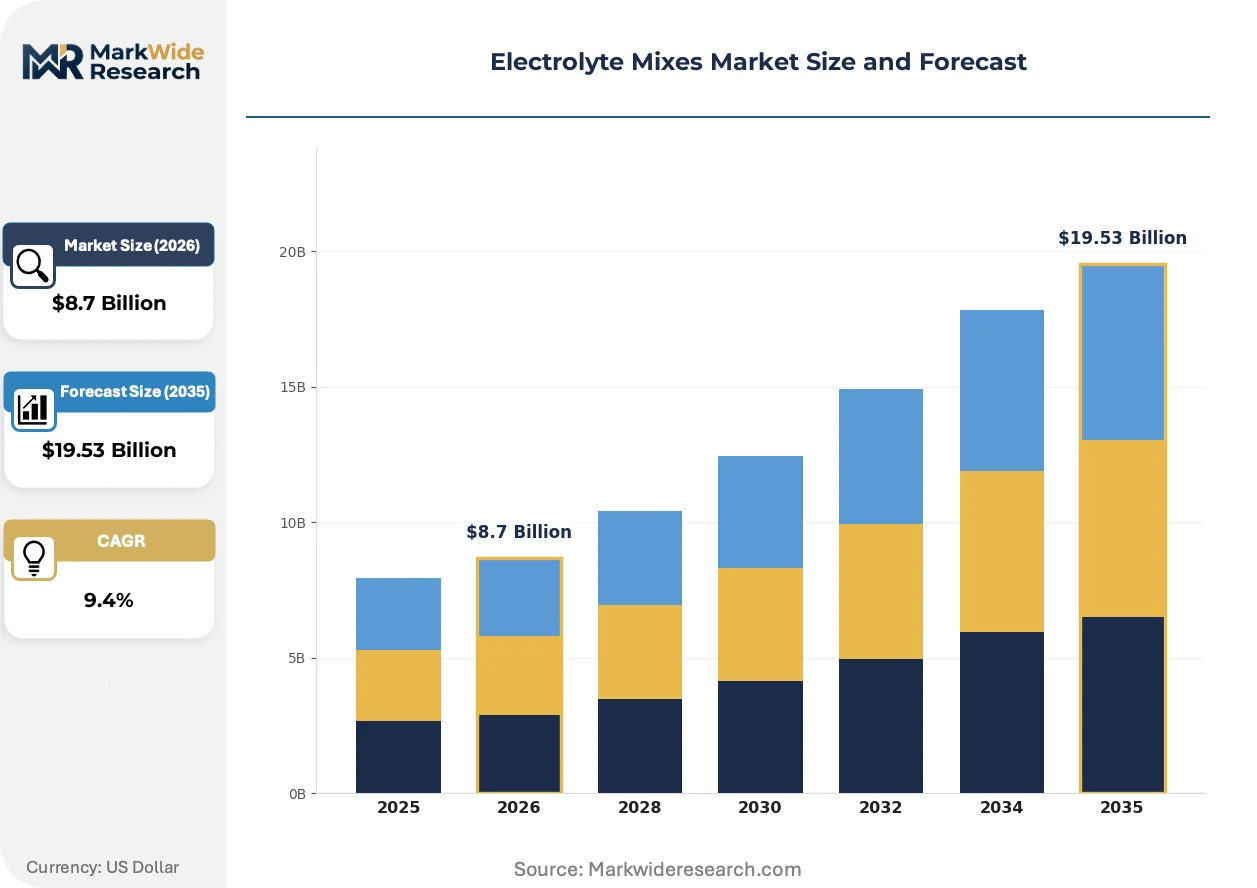
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablets, Gel End User: Athletes, Fitness Enthusiasts, Medical Patients, Weekend Warriors Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms Flavor: Citrus, Berry, Watermelon, Tropical |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, Nestlé SA, Unilever PLC, Abbott Laboratories, Liquid I.V., Skratch Labs, Ultima Health Products, DripDrop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyte Mixes Market Emerging Trajectories
Electrolyte mix innovation is concentrating on bioavailability enhancement and clean-label verification, with manufacturers racing to differentiate through mineral source transparency and delivery format convenience. These shifts are compressing legacy sports drink positioning while elevating clinical credibility.
Microencapsulation technology using lipid bilayer coatings is rewriting mineral absorption kinetics in the electrolyte category. Marathon and ultra-distance athletes are adopting these enhanced formulations at accelerating rates. The technology is compressing the performance gap between medical-grade rehydration and consumer sports products.
REACH registration requirements for novel mineral compounds are tightening entry barriers for European formulation innovation. Manufacturers now face extended toxicology study timelines before marketing new electrolyte complexes. Powder formats targeting endurance athletes bear the heaviest compliance burden, prompting some portfolios to pivot toward established mineral salts.
Subscription-based replenishment programs are displacing traditional sports specialty retail for core endurance consumers. Direct-to-consumer platforms capture recurring revenue from triathlon and cycling communities while eroding brick-and-margin positions. This channel rotation is most visible in United States coastal metropolitan markets where fitness app integration drives purchase automation.
Electrolyte Mixes Market Segmentation
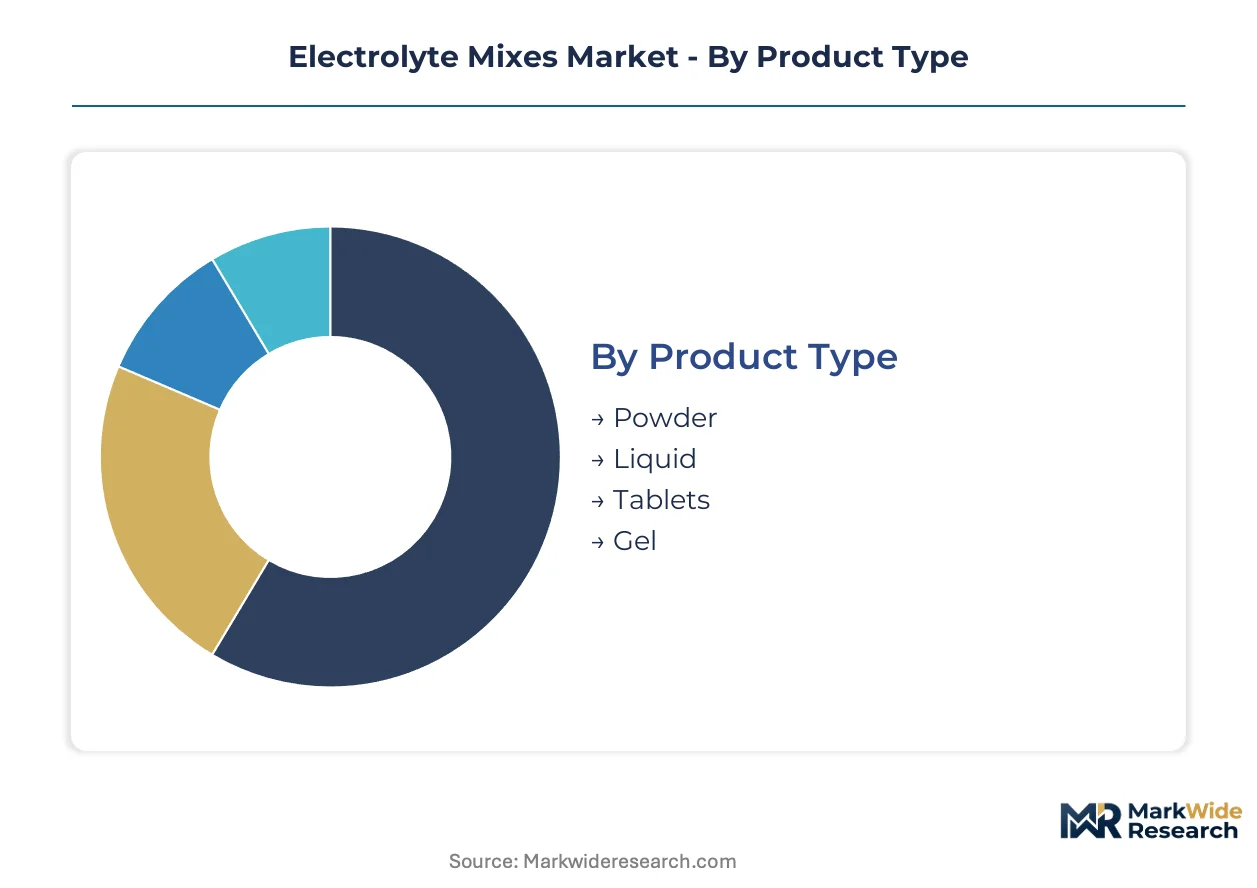
Electrolyte mix segmentation reveals divergent manufacturing economics and channel requirements across delivery formats. Powder and liquid variants demand distinct production assets, while end-user stratification between clinical and athletic applications reshapes formulation priorities and regulatory pathways.
Product Type:
Spray-drying and liquid blending technologies define cost structures and shelf stability profiles across format categories.
- Powder:Spray-dried formulations achieve controlled moisture content below 5%, enabling extended shelf stability and reduced shipping weights for direct-to-consumer fulfillment. Demand concentrates among endurance athletes in United States coastal metropolitan markets where subscription auto-replenishment dominates channel economics.
- Liquid:Ready-to-drink concentrates require sterile filling lines and aseptic packaging, elevating capital intensity but capturing premium placement in convenience retail. Weekend warriors in United States suburban markets drive volume through grab-and-go purchasing patterns.
- Tablets:Compression-molded effervescent formats suit travel-oriented consumers seeking portion control.
- Gel:Viscous semi-solid delivery targets ultra-distance athletes requiring rapid consumption without fluid mixing.
Powder leads on scale; liquid leads on momentum.
End User:
Application intensity varies sharply between performance optimization and clinical rehydration protocols.
- Medical Patients:Oral rehydration therapy integration into United States hospital discharge planning drives institutional procurement of clinical-grade formulations with precise osmolality parameters. Post-acute care protocols represent the steepest expansion trajectory as healthcare systems prioritize readmission reduction.
- Weekend Warriors:Recreational athletes with inconsistent training schedules purchase premium-positioned products through fitness app-integrated subscription platforms. United States functional beverage sector concentration shapes competitive intensity in this cohort.
- Athletes:Competitive endurance participants demand NSF Certified for Sport and Informed Choice verification standards.
- Fitness Enthusiasts:Regular gym attendees prioritize flavor variety and format convenience over clinical specifications.
Medical patients lead on growth rate; weekend warriors lead on volume contribution.
Distribution Channel:
Channel selection determines margin capture and customer lifetime value economics.
- Online Retail:Direct-to-consumer platforms bypass retail slotting fees and enable subscription-based replenishment with fitness app integration. United States endurance sports communities generate recurring revenue with minimal customer acquisition cost.
- Supermarkets:Mass-market placement requires trade promotion investment but captures impulse purchases from casual fitness participants.
- Health Stores:Specialty retail positions premium clean-label formulations with third-party certification visibility.
- Gyms:Point-of-exercise vending and pro-shop placement targets immediate consumption occasions.
Online retail leads on margin; supermarkets lead on reach.
Flavor:
Palatability engineering drives repeat purchase rates and formulation complexity.
- Citrus:Lemon-lime and orange profiles dominate medical applications due to masking efficacy for mineral bitterness. United States clinical-grade formulations standardize on citrus bases for pediatric and geriatric compliance.
- Berry:Antioxidant-associated positioning appeals to health-conscious consumers seeking functional ingredient narratives.
- Watermelon:Seasonal limited editions capture summer athletic event sponsorship visibility.
- Tropical:Mango and pineapple variants target hospitality and travel retail channels.
Citrus leads on clinical penetration; berry leads on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping electrolyte mix production geography as manufacturers relocate powder formulation to jurisdictions with streamlined dietary supplement pathways. Cost-of-compliance gaps between the United States and select export-oriented economies now exceed 15% on a fully-loaded basis.
United States
FDA labeling mandates and post-acute care protocol expansion drive institutional procurement of clinical-grade formulations. Weekend warrior adoption concentrates in California and New York metropolitan corridors where subscription auto-replenishment dominates channel economics. Abbott Laboratories leverages its pharmaceutical distribution network to sustain hospital system contracts across the Midwest and Southeast.
Germany
REACH registration requirements for novel mineral compounds tighten entry barriers for European formulation innovation. EFSA health claim restrictions constrain sports positioning flexibility, pushing manufacturers toward established mineral salt portfolios. Industrial concentration clusters around Frankfurt-Rhine-Main logistics corridors serving cross-border distribution into Benelux and Alpine markets.
China
SAMR dietary supplement registration timelines extend 18-24 months for novel electrolyte complexes, favoring domestic incumbents with established approvals. Precision fermentation mineral sourcing attracts venture investment in Yangtze River Delta biotech corridors. Export-oriented powder production concentrates in Shandong Peninsula spray-drying facilities serving Southeast Asian functional beverage markets.
India
FSSAI compliance costs for imported formulations exceed domestic manufacturing by 30%, incentivizing local production partnerships. Underpenetrated pediatric oral rehydration protocols present expansion potential for WHO-compliant salt formulations. Maharashtra and Gujarat host contract manufacturing clusters serving Middle East and African export demand.
Australia
TGA therapeutic goods classification distinguishes medical-grade electrolytes from sports nutrition, creating dual-pathway complexity. Clean-label positioning requirements exceed global baselines, elevating third-party certification costs. Sydney and Melbourne endurance sports communities drive premium powder demand through direct-to-consumer platforms with fitness app integration.
Electrolyte Mixes Market Vendor Landscape
Portfolio diversification dominates the current landscape as beverage conglomerates and pharmaceutical specialists converge on electrolyte positioning. Market structure bifurcates between scale-driven mass-market players and certification-heavy endurance specialists. Three archetypes define competitive positioning: diversified beverage conglomerates with functional beverage extensions, pharmaceutical-derived clinical-grade formulators, and clean-label specialists targeting subscription endurance communities. M&A activity and direct-to-consumer channel development represent the dominant competitive vectors.
Among diversified beverage conglomerates, PepsiCo Inc. and The Coca-Cola Company exemplify scale-driven mass-market positioning through established functional beverage distribution networks. Nestlé SA occupies a position bridging pharmaceutical credibility with consumer accessibility. Within the clean-label specialist tier, Skratch Labs and Liquid I.V. represent archetypes of subscription-optimized and certification-forward positioning respectively. Abbott Laboratories anchors the clinical-grade institutional segment through hospital system integration.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| Nestlé SA |
| Unilever PLC |
| Abbott Laboratories |
| Liquid I.V. |
| Skratch Labs |
| Ultima Health Products |
| DripDrop |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees concentrated in United States Midwest and Southeast health systems anchor institutional pricing through multi-year formulary contracts, compressing margin flexibility for clinical-grade electrolyte suppliers while elevating the importance of volume-based tiering and certification bundling in competitive positioning.
Pricing Analysis
Distributor margin compression in the direct-to-consumer channel is forcing powder-format suppliers toward subscription-based recurring revenue models with fitness app integration. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional sports positioning from private-label alternatives. Cost compression in premium tiers is intensifying because clean-label ingredient sourcing and third-party verification expenses are rising faster than end-user willingness to pay. Weekend warriors exhibit highest price sensitivity due to discretionary purchase patterns, while medical patients demonstrate lowest sensitivity given insurance reimbursement coverage for clinical-grade oral rehydration therapy.
Supply Chain Analysis
Freight cost volatility on trans-Pacific routes is elevating landed costs for Chilean-sourced potassium chloride and Israeli-processed magnesium compounds, pushing formulators toward regional mineral blending facilities. Bulk mineral extraction concentrates in Chile, Israel, and China, with spray-drying operations clustering in Shandong Peninsula and Frankfurt-Rhine-Main logistics corridors. Raw material dependencies rest on potassium chloride, magnesium oxide, and sodium bicarbonate as core inputs. Single-source vulnerability from Chilean caliche ore concentration exposes formulators to climate-related disruption risk. Distribution runs through pharmaceutical distribution networks for institutional segments and direct-to-consumer fulfillment centers for endurance sports communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrolyte mixes market functions as a regulatory compounder where FDA labeling mandates for dietary supplements are accelerating demand for reformulated, reduced-sodium clinical-grade formulations that satisfy both institutional procurement standards and emerging consumer health consciousness.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Abbott Laboratories should extend its pharmaceutical distribution network into post-acute care discharge planning protocols to preempt functional beverage substitution threats from Coca-Cola and PepsiCo. Nestlé SA must accelerate backward integration into precision fermentation mineral sourcing to reduce dependency on Chilean and Israeli bulk extraction operations. Channel control through hospital system integration represents the most durable margin defense against direct-to-consumer entrants. For New Entrants and Emerging Players: FDA sodium-reduction mandates in the United States open a window for clean-label specialists to capture weekend warrior migration from legacy sports drinks. Pediatric medical applications in India present the most penetrable white-space target given underpenetrated acute gastroenteritis protocols and FSSAI compliance cost barriers for imported formulations. A go-to-market angle anchored on WHO-compliant oral rehydration salts with local manufacturing partnerships bypasses import duty disadvantages. For Investors and Strategic Acquirers: Beverage conglomerates with functional beverage extensions are the most active acquirer in this space, seeking to bridge mass-market distribution with clinical credibility. Long-term viability hinges on dual-use certification capacity spanning medical device and dietary supplement pathways. Acquisition target archetype: clean-label specialists with established NSF Certified for Sport verification and subscription-based customer lifetime value economics. The signal to watch is integration of oral rehydration therapy into United States hospital value-based care contracts as a readmission reduction metric.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | NSF Certified for Sport verification unlocks institutional procurement access for endurance sports positioning. |
| Direct-to-Consumer Platform Launch | Fitness app integration enables subscription auto-replenishment with minimal customer acquisition cost in coastal metropolitan markets. |
| Precision Fermentation Mineral Sourcing | Synthetic biology convergence reduces mining dependency for potassium and magnesium inputs. |
| Pediatric Medical Application Expansion | WHO-compliant oral rehydration salts address underpenetrated acute gastroenteritis protocols in Indian subcontinent markets. |
| Hospital System Partnership Development | Post-acute care protocol integration captures institutional procurement volume through discharge planning mandates. |
Methodological Framework
Multiple input streams — formulation chemist interviews, hospital procurement manager discussions, dietary supplement regulatory filings, and endurance sports community surveys — were reconciled to construct demand and supply-side assessments. Primary engagement with R&D directors at powder manufacturing facilities, pharmaceutical distribution network managers, and clean-label brand founders was validated against secondary sources including FDA dietary supplement labeling guidance documents, EFSA health claim registers, and United States hospital discharge planning protocol databases. Bottom-up triangulation across product format economics and top-down validation through functional beverage sector revenue disclosures ensured cross-verification.
Historical consumption patterns were cross-referenced against panel input from electrolyte mix procurement specialists to establish baseline demand trajectories across the analysis window. Segmentation dimensions modeled include delivery format, end-user application intensity, distribution channel margin structure, and regional regulatory cluster. CAGRs were derived through regression analysis of adoption curve penetration rates and pricing elasticity estimates. Forecast inputs incorporated spray-drying capacity expansion timelines and precision fermentation mineral sourcing venture investment flows.
Revisions become necessary when sodium-reduction mandate enforcement intensifies, potassium chloride supply disruptions materialize, or functional beverage substitution accelerates beyond modeled substitution rates. Forecasts reflect documented assumptions regarding regulatory pathway timelines and channel migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Middle East Energy Drinks Market
Beverages
Aloe Vera Juice Market
Beverages
Fruit Juice Market
Beverages
Botanical Infused Beverages Market
Beverages
Coconut Water Market
Beverages
Japan Kombucha Market
Beverages
Flavored Powder Drinks Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Kvass Market
Beverages
United States Soy Beverages Market
Beverages
Apple Cider Vinegar Market
Beverages
Sparkling Water Machine Market
Beverages
Asia-Pacific Juices Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Ready to Drink Margarita Market