
 Europe Bottled Water Market | 2026-2036
Europe Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bottled Water Market Analysis
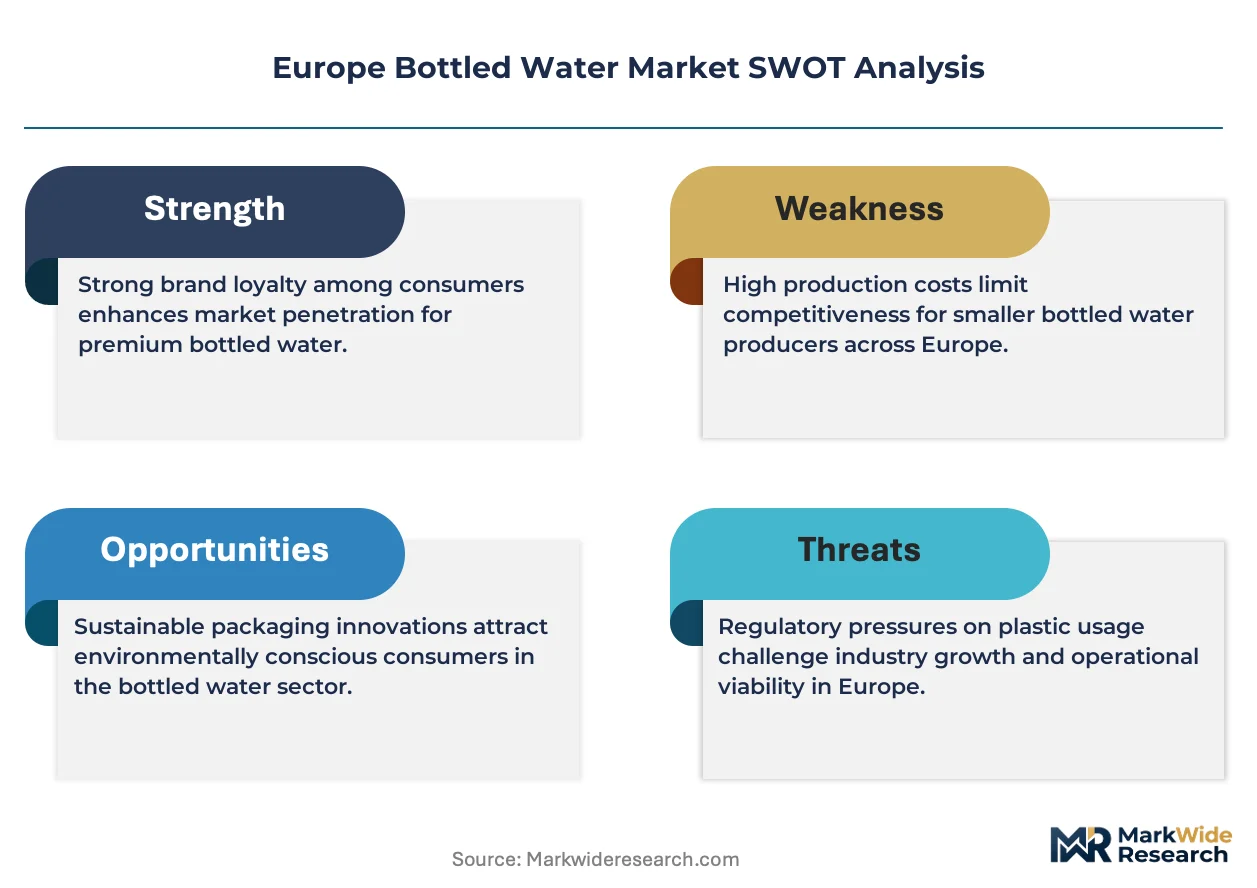
CE marking under the EU Drinking Water Directive is redrawing competitive boundaries for source protection and bottling hygiene. Danone SA leverages its Alpine and Vosges spring networks to sustain volume leadership across Western Europe. Gerolsteiner Brunnen GmbH & Co. KG anchors its position through volcanic rock filtration credentials that differentiate the brand in German retail. Highland Spring Group competes through Scottish source provenance and dominant placement in UK grocery multiples.
Europe bottled water comprises potable water sealed in containers for human consumption, sourced from natural springs, boreholes, or public supplies, with mineral content measured in milligrams per liter of calcium, magnesium, and bicarbonate. The product serves hydration, culinary pairing, and on-the-go convenience functions across hospitality, retail, and institutional channels. Still water dominates volume through supermarket and convenience store distribution, while sparkling mineral water captures disproportionate margin in food service and premium retail tiers. Plastic bottles remain the structural default across economy and mid-range price tiers, though glass and recycled PET alternatives are gaining shelf space in response to packaging regulations.
The EU Single-Use Plastics Directive and national implementations by France's ANSES and Germany's Federal Environment Agency are tightening recycled content mandates and extended producer responsibility frameworks. EFSA guidelines on mineral water purity and source labeling shape product claims and market access conditions. Stakeholders must monitor evolving packaging compliance thresholds and source certification renewals as the competitive landscape tilts toward circular supply chain credentials.
Market Dynamics
The EU Single-Use Plastics Directive is compressing packaging economics across Europe bottled water, forcing producers to absorb recycled PET premiums or cede shelf space to compliant rivals. This regulatory compression cascades through sourcing, bottling, and distribution decisions.
Growth Catalysts
- Alpine source concentration:Italy's protected designation of origin mineral waters command sustained price premiums in German and French hospitality channels as tourism rebounds.
- Extended producer responsibility frameworks:France's ANSES and Germany's Federal Environment Agency mandates accelerate investment in closed-loop rPET infrastructure.
- On-premise hospitality recovery:Premium glass-bottled mineral water volumes expand across Italian, French, and German food service as international visitor flows normalize.
Market Restraints
- Recycled PET input cost volatility:European rPET flake supply concentrates among limited chemical recyclers, exposing bottlers to feedstock price swings.
- Source protection geography:Viable natural spring sites cluster in Alpine and Vosges regions, constraining new market entry outside established catchment areas.
- CE marking compliance friction:The EU Drinking Water Directive's bottling hygiene standards extend certification timelines for new production facilities.
Strategic Opportunities
- Underpenetrated Eastern European markets:Polish and Romanian retail channels show widening gaps between local still water volumes and imported sparkling mineral water penetration.
- Regulatory tailwind from EU Green Deal:Circular packaging subsidies and carbon border adjustments favor producers with verified low-emission spring-to-shelf logistics.
- Direct-to-hospitality platform models:Digital ordering systems bypass traditional wholesale distributors for restaurant and hotel accounts in Madrid and Barcelona clusters.
Industry Challenges
- Source hydrologist talent scarcity:Qualified groundwater surveyors and catchment protection specialists command premium compensation across Alpine bottling operations.
- Legacy PET line conversion capex:Existing blow-molding equipment requires substantial modification to handle 100% recycled content without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bottled Water Market |
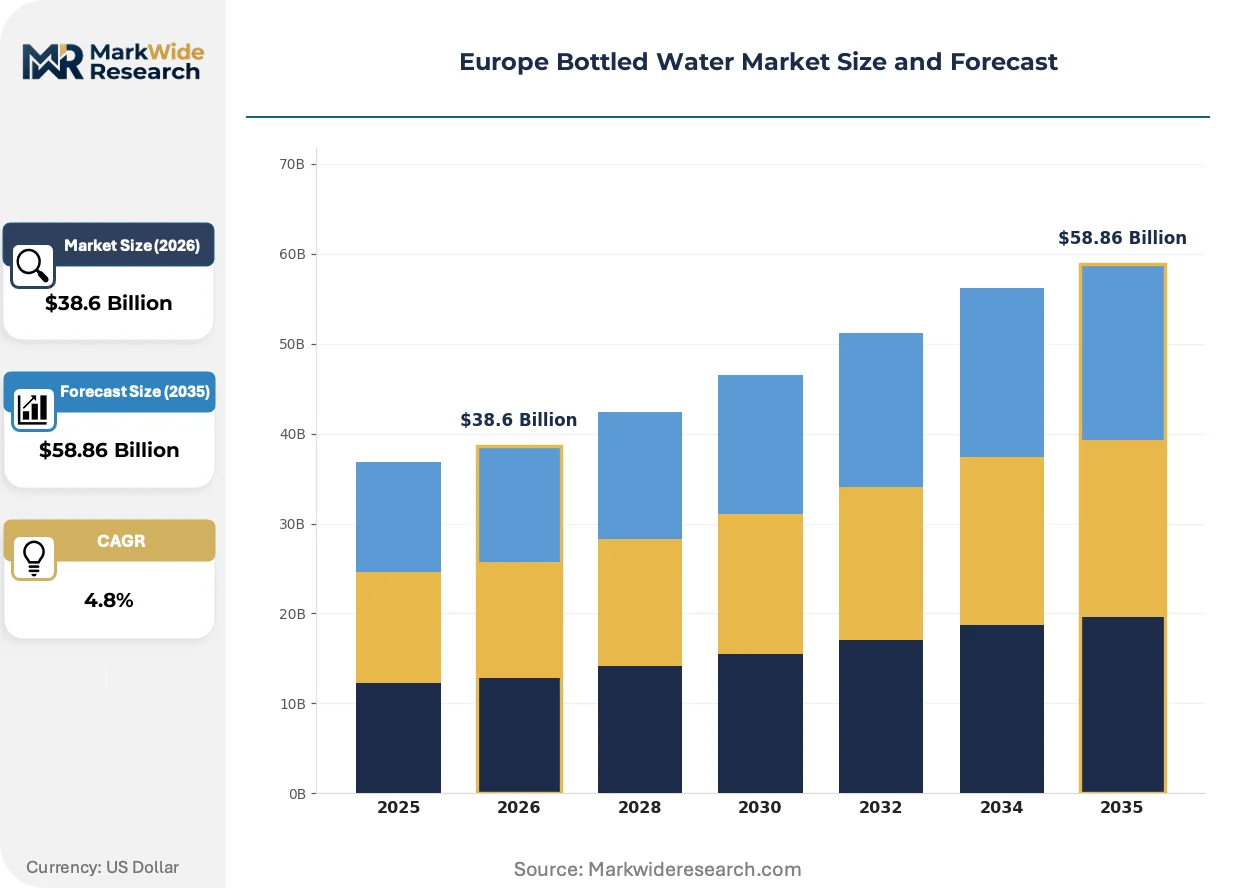
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | PepsiCo Inc., Ferrarelle SpA, Nestlé Waters, Highland Spring Group, Spadel SA, Danone SA, Gerolsteiner Brunnen GmbH & Co. KG, Acqua Minerale San Benedetto SpA, The Coca-Cola Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bottled Water Market Emerging Trajectories
Packaging substrate diversification and digital traceability systems are compressing traditional competitive moats in Europe bottled water. Producers now differentiate through verified circularity credentials rather than source mythology alone.
Lightweighting technology for glass bottle manufacturing is miniaturizing wall thickness while maintaining structural integrity for carbonated mineral water. Italian and French premium producers adopt these reduced-weight formats to offset glass's energy-intensive shipping profile. The technology is compressing the cost gap between glass and premium PET alternatives in supermarket channels.
EFSA guidelines on mineral water purity and source labeling are tightening permissible marketing claims across EU member states. Bottlers must now substantiate volcanic rock filtration or deep aquifer origin statements with certified laboratory documentation. Sparkling mineral water segments in Germany and France face the steepest compliance adjustment costs.
Hospitality procurement departments now unbundle water service from broader beverage supply contracts, negotiating direct relationships with single-source bottlers. This disintermediation bypasses traditional national distributors in Milan, Paris, and Berlin hotel clusters. Independent restaurants follow this pattern, though convenience store and supermarket retail retains consolidated wholesale structures.
Europe Bottled Water Market Segmentation
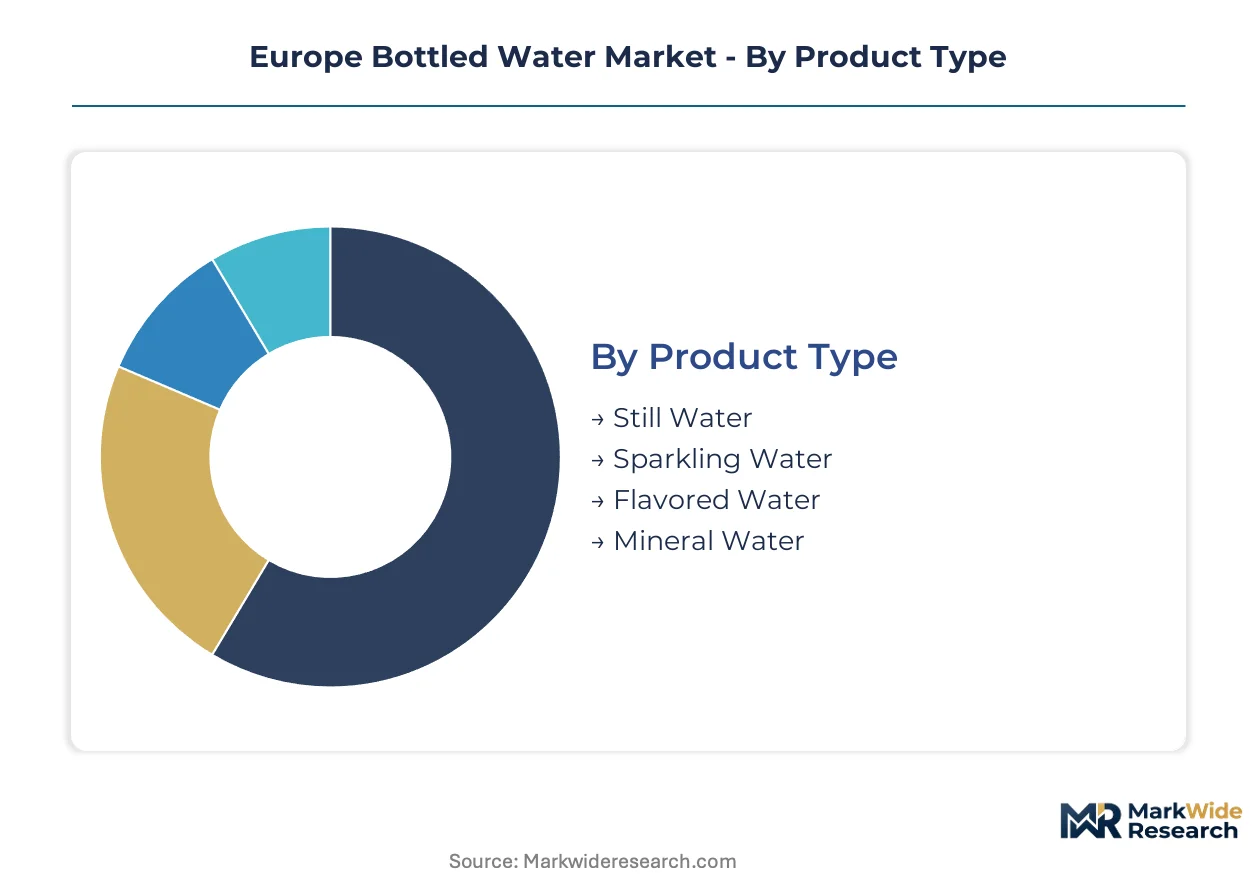
Segmentation in Europe bottled water reveals how regulatory pressure and channel economics split demand across incompatible production investments. Producers must choose between scale-driven still water for retail or margin-protected sparkling mineral water for hospitality, with packaging compliance costs determining viable entry points.
Product Type:
EFSA mineral water purity standards and CE marking under the EU Drinking Water Directive create divergent compliance burdens across product categories, separating natural source claims from treated municipal derivatives.
- Still Water:Non-carbonated potable water from springs, boreholes, or public supplies, bottled without added minerals or gas. German and French supermarkets move the highest volumes through private-label and branded formats, though margin compression from recycled PET mandates limits producer profitability in this tier.
- Mineral Water:Naturally sourced water with certified mineral content measured in milligrams per liter of calcium, magnesium, and bicarbonate, protected under EU protected designation of origin frameworks. Italian Alpine sources command sustained price premiums in on-premise hospitality across Germany and France as tourism normalizes.
- Sparkling Water:Carbonated variants achieving effervescence through natural source gas or added carbonation, regulated under stricter bottling hygiene protocols for sealed carbonation stability.
- Flavored Water:Water-based beverages with added natural or artificial flavoring, falling under general food law rather than mineral water directives, with sugar content thresholds monitored by national health agencies.
Still water handles the majority of throughput; mineral water is expanding most quickly on share as hospitality procurement disintermediates wholesale distributors.
Packaging Type:
Cost tier stratification separates premium glass formats from economy plastic, with regulatory thresholds forcing mid-range producers into recycled PET investments that alter break-even volumes.
- Plastic Bottles:Predominantly PET containers ranging from 0.33-liter on-the-go formats to 2-liter family sizes, with EU Single-Use Plastics Directive mandates requiring escalating recycled content percentages. German and French bottlers face acute feedstock cost volatility as European rPET flake supply concentrates among limited chemical recyclers.
- Glass Bottles:Returnable and single-use formats for premium mineral water, with lightweighting technology miniaturizing wall thickness while maintaining structural integrity for carbonated products. Italian and French producers adopt reduced-weight glass to offset energy-intensive shipping profiles in supermarket channels.
- Tetra Packs:Aseptic carton formats with laminated paperboard, aluminum, and plastic layers, occupying niche positions in institutional and family consumption segments where shelf stability outweighs source mythology.
- Cans:Aluminum formats gaining trial in sparkling water segments, constrained by consumer perception mismatches with still water consumption occasions and limited recycling infrastructure in Eastern European markets.
Plastic bottles handle the majority of throughput; glass bottles are gaining share fastest as hospitality procurement prioritizes premium presentation and circular packaging credentials.
Distribution Channel:
Application concentration splits between consolidated retail wholesale and disintermediated hospitality direct, with diverging working capital and relationship management requirements.
- Supermarkets:Dominant volume channel across Western Europe, with UK grocery multiples and German discounters driving private-label penetration and price transparency that compress branded still water margins.
- Food Service:Restaurants, hotels, and cafeterias unbundling water procurement from broader beverage contracts, negotiating direct relationships with single-source Italian and French bottlers in Milan, Paris, and Berlin clusters.
- Convenience Stores:Impulse-driven channel for single-serve formats, with location density determining competitive access in urban French and Spanish markets.
- Online Retail:Subscription and bulk delivery models for premium mineral water, constrained by last-mile logistics costs relative to product value in dispersed rural geographies.
Supermarkets handle the majority of throughput; food service is climbing the fastest on share as digital ordering platforms bypass traditional wholesale structures.
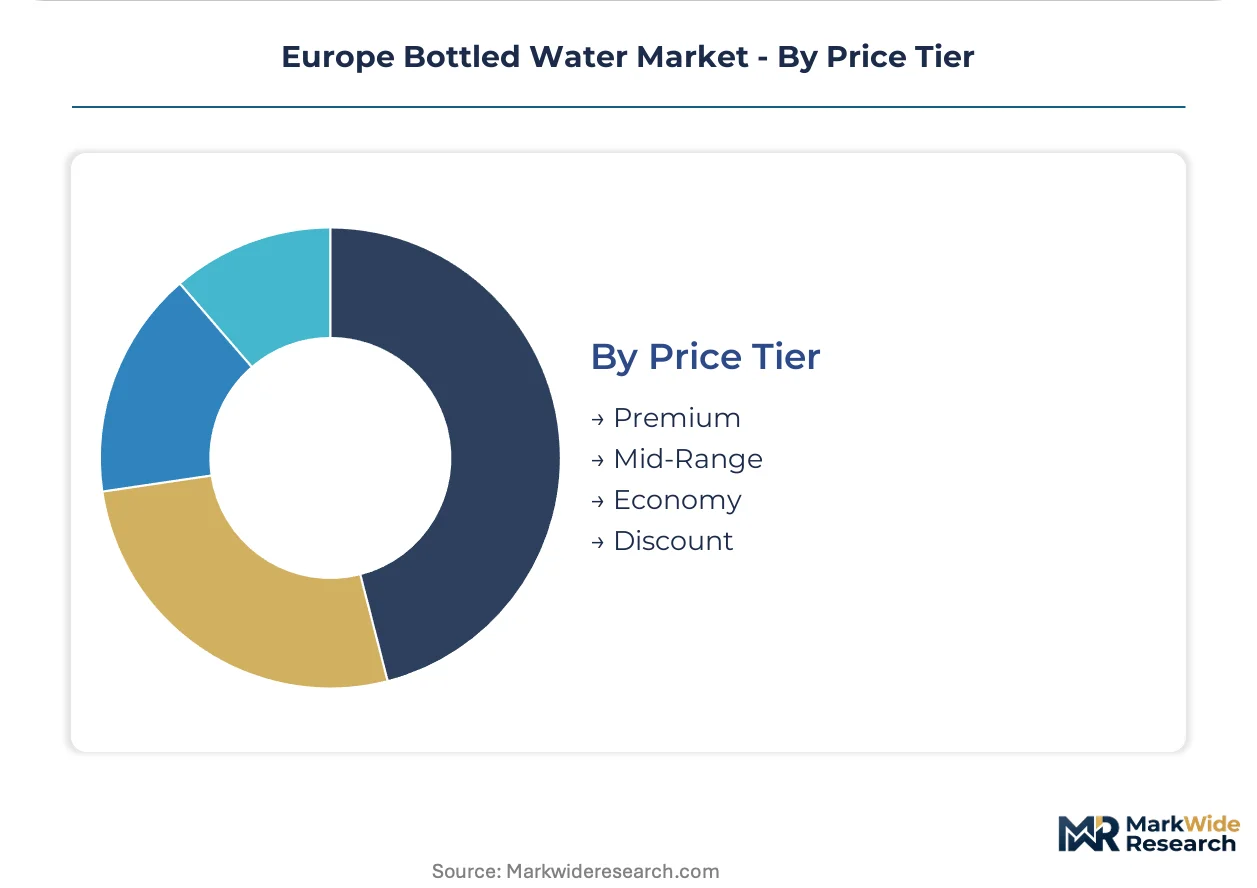
Price Tier:
Customer type stratification separates protected designation of origin seekers from price-sensitive hydration buyers, with certification grade and source mythology substituting for performance differentiation.
- Premium:Glass-bottled mineral water with certified Alpine or volcanic rock filtration provenance, commanding sustained price premiums in German and Italian hospitality channels.
- Mid-Range:Branded PET formats with recycled content compliance, occupying contested shelf space where private-label pressure and regulatory cost absorption squeeze producer economics.
- Economy:Private-label still water in lightweight PET, with German and UK discounters driving volume through aggressive price positioning that limits brand investment recovery.
- Discount:Unbranded or deep-private-label formats, concentrated in Eastern European retail channels where local sourcing minimizes logistics cost but constrains quality perception.
Economy handles the majority of throughput; premium is gaining share fastest as tourism recovery and sustainability signaling reshape hospitality procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in Alpine hospitality procurement clusters, German retail discounters, and Mediterranean tourism corridors. These demand centers drive divergent packaging investments and source certification priorities across national boundaries.
Germany
Retail discounters and mineral water connoisseurs split demand between private-label still formats and volcanic rock filtration brands. Germany's Federal Environment Agency enforces extended producer responsibility frameworks that accelerate rPET infrastructure investment. The Rhineland-Palatinate volcanic spring belt anchors premium mineral water production, with bottlers converting legacy PET lines to handle 100% recycled content.
France
ANSES mandates on recycled content and source labeling reshape competitive positioning for Vosges and Alpine spring networks. Hospitality procurement in Paris and Lyon hotel clusters unbundles water service from beverage contracts, favoring direct relationships with protected designation of origin bottlers. The Île-de-France retail corridor concentrates volume throughput for mid-range PET formats.
Italy
Alpine source protected designation of origin status commands sustained price premiums in German and French hospitality channels as tourism normalizes. EFSA guidelines on mineral water purity and bottling hygiene extend certification timelines for new production facilities. The Lombardy and Piedmont spring catchments concentrate premium glass-bottled volumes for export markets.
United Kingdom
Grocery multiples drive private-label penetration and price transparency that compress branded still water margins. CE marking under the EU Drinking Water Directive applies to Northern Ireland bottling operations, creating compliance friction relative to Great Britain facilities. Scottish source provenance anchors Highland Spring Group's placement in supermarket channels.
Spain
Digital ordering platforms bypass traditional wholesale distributors for restaurant and hotel accounts in Madrid and Barcelona clusters. Convenience store location density determines competitive access in urban markets. Local still water volumes dominate retail, though imported sparkling mineral water penetration lags Western European benchmarks.
Europe Bottled Water Market Vendor Landscape
Player mix skews toward multinational beverage conglomerates with diversified hydration portfolios alongside specialist mineral water houses with protected source networks. Structure concentrates volume leadership among three to four entities with cross-border spring networks, while mid-tier regional bottlers defend position through geographic source exclusivity. Strategic archetypes separate Alpine/Vosges source holders, volcanic filtration credential brands, and retail-private-label scale operators. Competitive moves center on rPET line conversion partnerships and direct-to-hospitality platform investments.
Within the multinational tier, Danone SA and Nestlé Waters occupy positions defined by spring network breadth across Alpine and Vosges catchments. Among specialist houses, Gerolsteiner Brunnen GmbH & Co. KG exemplifies volcanic rock filtration differentiation, while Highland Spring Group anchors Scottish source provenance in UK retail. These entities represent divergent strategic bets on source mythology versus scale logistics.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Ferrarelle SpA |
| Nestlé Waters |
| Highland Spring Group |
| Spadel SA |
| Danone SA |
| Gerolsteiner Brunnen GmbH & Co. KG |
| Acqua Minerale San Benedetto SpA |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Alpine and Vosges spring networks concentrates cost advantages among incumbent bottlers, compressing price floors for mid-range PET entrants while elevating premium glass-bottled margins through scarcity signaling. This scale asymmetry forces smaller producers into private-label contracts or regional niche positioning.
Pricing Analysis
Long-term offtake contracts with rPET suppliers index pricing to European flake market benchmarks, exposing mid-range producers to feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates protected designation of origin glass formats from compliant recycled-content PET and deep-private-label still water. Pricing pressure stems from German and UK discounters driving private-label penetration. Economy-tier buyers exhibit acute price sensitivity; hospitality procurement shows inelastic demand for certified Alpine provenance.
Supply Chain Analysis
Strategic stockpiling of rPET flake dominates inventory strategy as chemical recycler concentration creates single-source vulnerability. Spring water extraction concentrates in Italy, France, and Germany; rPET feedstock draws from limited European chemical recyclers. Legacy blow-molding equipment, virgin PET resin, and lightweight glass silica constitute critical input dependencies. Tariff exposure on aluminum can imports from Eastern European markets amplifies packaging substrate risk. Distribution runs through consolidated retail wholesale for volume tiers and direct-to-hospitality platforms for premium mineral water.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states on recycled content mandates and source certification timelines creates white-space opportunities for specialized entrants. Hospitality procurement disintermediation fragments demand into relationship-driven niches.
For Market Incumbents: Fortify Alpine and Vosges spring network control through catchment protection investments and exclusive sourcing agreements. Accelerate rPET line conversion partnerships to preempt compliance cost absorption. Channel control through direct-to-hospitality digital platforms defends margin position against wholesale disintermediation. For New Entrants and Emerging Players: Differentiate on Eastern European source provenance in Polish and Romanian retail channels where imported sparkling mineral water penetration lags. Target underpenetrated convenience store location density in Spanish urban markets. Launch through subscription-based online retail models to bypass consolidated wholesale structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist mineral water houses with protected designation of origin networks over diversified beverage conglomerates. Long-term viability rests on verified circularity credentials and source mythology defensibility. Acquisition focus: Alpine/Vosges source holders with dormant capacity expansion rights. Watch rPET flake price volatility as inflection indicator for mid-range producer distress.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Line Conversion Partnership | ANSES and Germany's Federal Environment Agency mandates require compliant infrastructure to maintain shelf access. |
| Direct-to-Hospitality Platform Launch | Paris and Milan hotel clusters now unbundle water procurement from beverage contracts. |
| Alpine Source Catchment Protection | EFSA guidelines on mineral water purity extend certification timelines for unprotected sites. |
| Lightweight Glass Manufacturing Investment | Reduced-weight formats compress cost gaps with premium PET in German supermarket channels. |
| Eastern European Distribution Expansion | Polish and Romanian retail channels show widening gaps between local still and imported sparkling volumes. |
Methodological Framework
A spread of perspectives from bottling plant managers, hospitality procurement directors, retail category buyers, and rPET supply specialists converged on the working assumptions around feedstock cost trajectories and source certification timelines. Primary interviews combined with secondary validation from EU Single-Use Plastics Directive implementation documents, ANSES technical guidance, EFSA purity standards, and national customs records on packaging material trade flows. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, packaging substrate, distribution channel, price tier, and regional regulatory cluster throughout the forecast period. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost absorption and tourism recovery patterns. Industry-specific forecast inputs encompass rPET flake supply elasticity and Alpine spring catchment hydrology assessments.
The analysis sits within stated boundaries; outcomes outside normalized tourism flows and stable rPET feedstock availability would require recalibration. Forecasts reflect assumptions on CE marking compliance timelines and EFSA guideline enforcement consistency. Revision becomes warranted when rPET price volatility crosses thresholds that trigger mid-range producer exit or when source protection geography constraints intensify beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Sparkling Soda Market
Beverages
US and Canada Tonic Water Market
Beverages
Double Valve Moka Pots Market
Beverages
Vegetable Juice Market
Beverages
Packaged Coconut Water Market
Beverages
Commercial Drink Mixers Market
Beverages
Probiotic Beverage Market
Beverages
Powdered Beverages Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Bottled Beverages Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Plant-Based Energy Drink Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
South America Mate Market
Beverages
Italy Probiotic Drinks Market