
 Brewing Chiller Market | 2026-2036
Brewing Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Chiller Market Outlook
Germany is tilting toward expanded chiller fabrication capacity to serve Central European brewery modernization. Alfa Laval leverages its plate heat exchanger expertise to anchor premium contracts with large-scale lager producers. GEA Group competes through integrated refrigeration skids that combine glycol distribution with fermentation tank controls.
A brewing chiller is a mechanical refrigeration system engineered to cool wort or maintain fermentation temperatures within ±0.5°C precision, typically employing glycol-water mixtures or direct-expansion refrigerants circulated through stainless steel heat exchangers. Glycol chillers dominate commercial installations due to their capacity for multi-tank zone control and frost-free operation below 4°C. Air-cooled technology leads outdoor and mobile deployments where water scarcity or plumbing constraints eliminate closed-loop tower options, while water-cooled systems retain efficiency advantages in high-capacity brewery environments with existing infrastructure.
EPA AIM Act refrigerant restrictions and EU F-Gas Regulation phase-down schedules are reshaping compressor and coolant specifications across North American and European supply chains. FDA food-contact material standards govern glycol formulation and piping alloys in production environments. Stakeholders must evaluate coolant transition timelines and regional service network density before committing to long-term chiller fleet investments.
Market Dynamics
EPA AIM Act refrigerant phase-down mandates are compressing equipment replacement cycles and forcing brewers toward low-GWP glycol formulations and thermoelectric alternatives ahead of regulatory deadlines.
Growth Catalysts
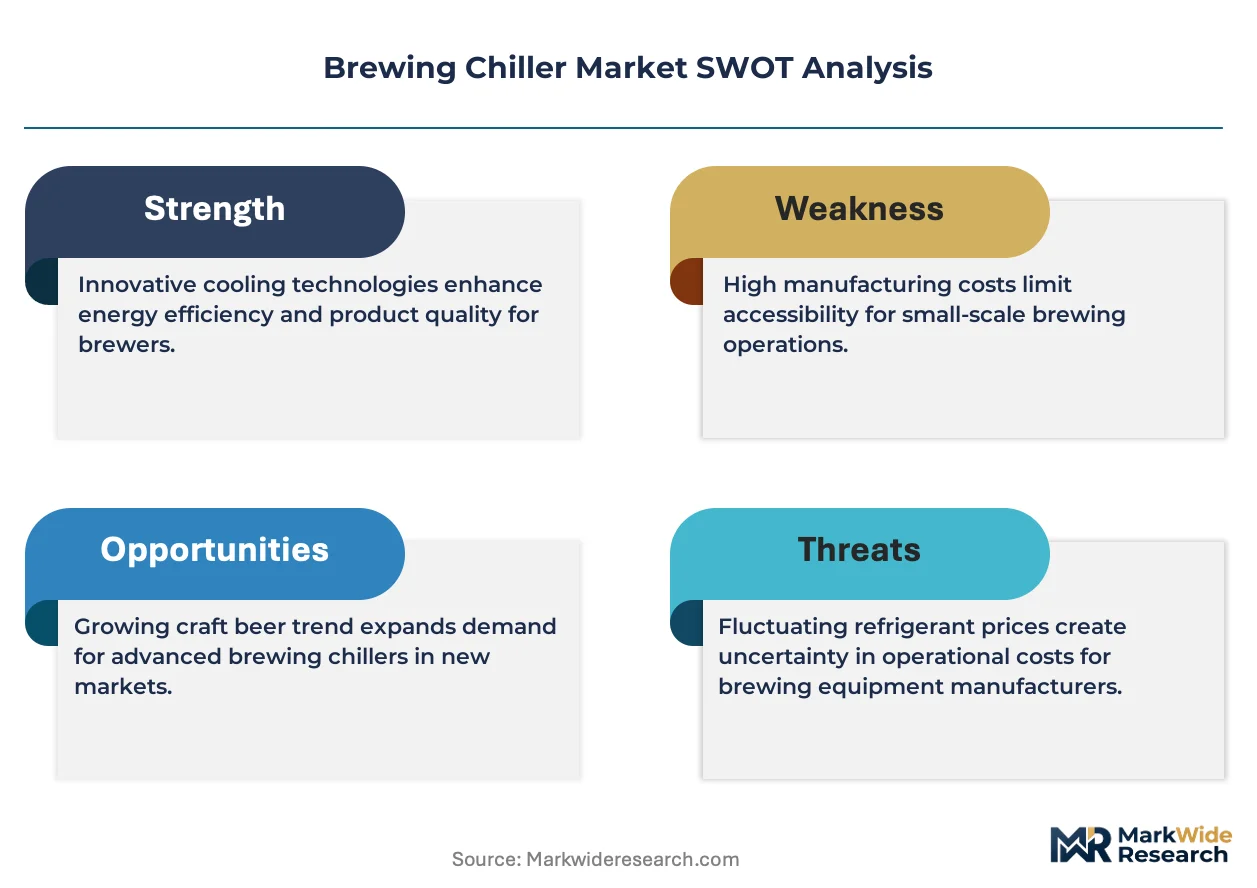
- EU F-Gas Regulation phase-down:Breweries across Germany and the Czech Republic are accelerating chiller fleet upgrades to comply with tightening GWP limits, creating replacement demand for compliant systems.
- Craft brewery expansion:Artisanal lager and ale producers in Seattle and Portland are installing multi-zone glycol chillers to support temperature-controlled fermentation capacity growth.
- Mobile brewing units:Air-cooled chiller technology is enabling outdoor and festival-based brewing operations where water infrastructure is unavailable.
Market Restraints
- Copper and stainless steel input volatility:Heat exchanger fabrication costs fluctuate with commodity markets, squeezing margins for chiller OEMs and fabricators.
- Specialized compressor supply concentration:Low-GWP compressor production concentrates among a limited supplier base in Germany and Japan, creating procurement bottlenecks.
- Direct-expansion refrigerant substitution limits:Ammonia systems face zoning restrictions in urban brewery locations, constraining technology choice in dense production clusters.
Strategic Opportunities
- India craft beer emergence:Mumbai and Bangalore brewery openings are creating first-mover advantage for glycol chiller suppliers establishing local service networks.
- CE marking and MDR convergence:Integrated refrigeration skids that combine fermentation controls qualify for streamlined certification, reducing time-to-market for European brewers.
- IoT-enabled predictive maintenance:Sensor-embedded chillers paired with cloud analytics are opening subscription revenue streams for equipment vendors serving distributed craft operations.
Industry Challenges
- Refrigeration technician scarcity:Low-GWP system servicing requires specialized certification that outpaces vocational training program output in North America and Europe.
- Legacy glycol piping integration:Retrofitting existing fermentation halls with new chiller headers demands custom fabrication and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Chiller Market |
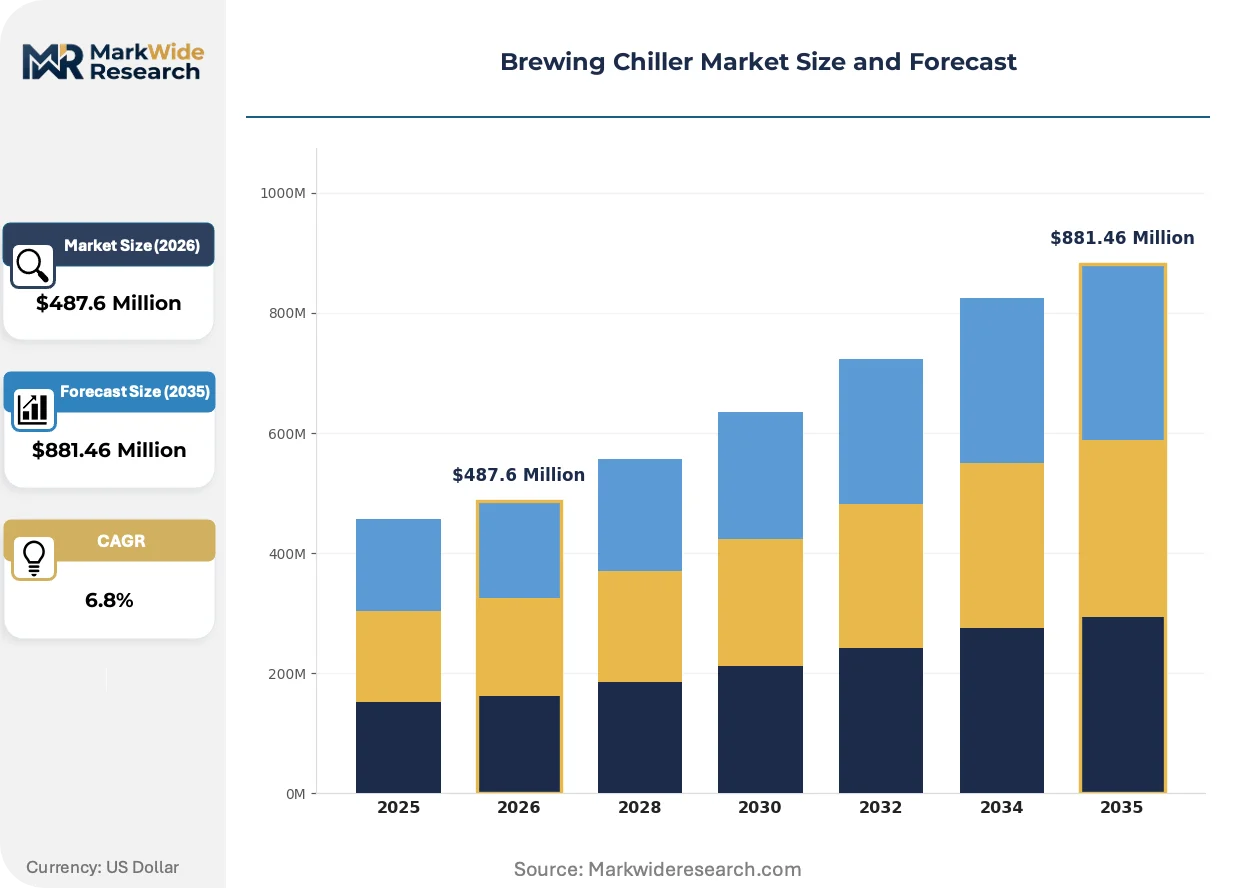
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterflow Chillers, Plate Chillers, Immersion Chillers, Glycol Chillers Technology: Air-Cooled, Water-Cooled, Refrigeration, Thermoelectric End User: Microbreweries, Craft Breweries, Large Breweries, Home Brewers Installation: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | HGMC, Alfa Laval, TopChiller, Paul Mueller Company, SS Brewtech, Cold Shot Chillers, GEA Group, Tecogen, J&M Fluidics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Chiller Market Strategic Shifts
Digital twin technology and refrigerant chemistry advances are converging to reshape how brewing chillers are specified, operated, and serviced across production scales.
Modular thermoelectric cooling arrays are virtualizing traditional compressor-based architectures for pilot and nanobrewery applications. Small-batch producers in Portland and Denver are deploying these solid-state systems for fermentation tanks under 500 liters. The technology is virtualizing maintenance schedules and footprint requirements that previously constrained urban microbrewery expansion.
REACH compliance deadlines for fluorinated gases are accelerating adoption of propane and CO2 transcritical systems in European installations. German lager producers face 2027 GWP reduction targets that render existing R-404A equipment noncompliant. Large-scale facilities are responding with centralized CO2 refrigeration plants that distribute cooling across multiple fermentation halls.
After-sales service unbundling is fragmenting traditional OEM revenue models. Craft brewers in the US Pacific Northwest are purchasing chillers through capital-light leasing arrangements while sourcing maintenance from independent refrigeration contractors. This pattern is most pronounced among breweries operating fewer than 10 fermentation vessels, where in-house technical staff are uneconomical.
Brewing Chiller Market Segmentation
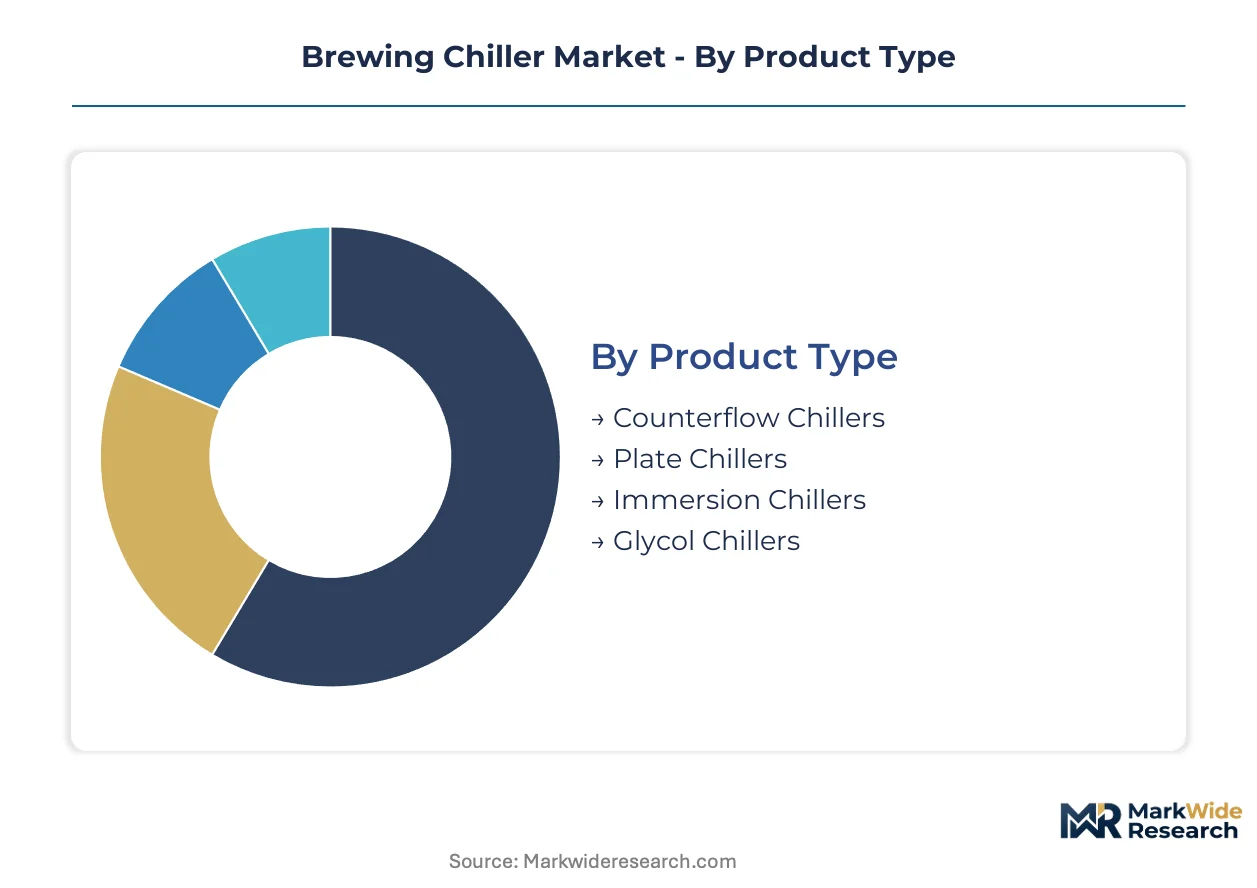
Brewing chiller procurement patterns diverge sharply across production scales and installation environments. Equipment specifications cascade from fermentation volume requirements through refrigerant chemistry constraints to service network availability.
Product Type:
After-sales service intensity varies dramatically by heat exchanger architecture, with plate-based systems demanding specialized gasket replacement protocols that reshape vendor economics.
- Glycol Chillers:Closed-loop systems circulate propylene glycol-water mixtures through jacketed fermentation tanks, enabling multi-zone temperature control across 50+ vessel arrays. German lager producers specify these for 24-month continuous fermentation cycles where ±0.5°C precision governs ester profile consistency.
- Plate Chillers:Stainless steel corrugated plates enable rapid wort cooling through turbulent flow patterns, slashing cooldown windows from 60 minutes to under 10 minutes for 10-hectoliter batches. Czech craft breweries favor compact footprints that slide between existing brewhouse vessels without structural modification.
- Counterflow Chillers:Tube-within-tube designs separate wort and coolant streams through concentric stainless channels, delivering thermal efficiency in mobile canning line deployments.
- Immersion Chillers:Submerged coil configurations dominate home brewing and pilot systems where capital constraints outweigh energy efficiency priorities.
By volume, Glycol Chillers lead. By growth pace, Plate Chillers are climbing the fastest as craft producers prioritize brewhouse density.
Technology:
Capital deployment thresholds stratify sharply by cooling architecture, with thermoelectric arrays commanding premium positioning against compressor-based alternatives.
- Air-Cooled:Finned-coil condensers eliminate cooling tower infrastructure, enabling outdoor installations where water scarcity or zoning restrictions block closed-loop systems. Pacific Northwest festival brewers deploy trailer-mounted units for temporary production at agricultural fairs.
- Water-Cooled: Shell-and-tube or plate heat exchangers leverage existing cooling tower capacity for efficiency advantages above 50 kW refrigeration loads. Large-scale facilities with on-site utilities favor these for compressor longevity in continuous-duty applications.
- Refrigeration: Vapor-compression systems using low-GWP refrigerants dominate commercial installations above 5 kW cooling capacity, with scroll and screw compressor architectures scaling from craft to industrial production.
- Thermoelectric: Solid-state Peltier arrays eliminate moving parts for nanobrewery pilot systems under 500 liters, where maintenance access constraints favor silent, vibration-free operation.
Water-Cooled systems capture the largest installed base. Thermoelectric configurations are gaining share fastest among urban microbreweries.
End User:
Technical staffing availability dictates equipment complexity tolerance, with owner-operator breweries favoring simplified architectures against engineered systems.
- Craft Breweries:Mid-scale producers operating 10-50 fermentation vessels require zone-controlled glycol distribution with remote monitoring capabilities. Seattle and Portland clusters drive specification toward IoT-embedded chillers with predictive maintenance dashboards.
- Large Breweries:Industrial lager producers specify centralized refrigeration plants serving multiple fermentation halls, with redundancy protocols ensuring zero downtime during peak summer production.
- Microbreweries:Small-batch operations with 2-10 vessels prioritize plug-and-play skids minimizing installation downtime and specialized commissioning.
- Home Brewers:Enthusiast-grade immersion and counterflow units dominate this price-sensitive segment through direct-to-consumer channels.
Craft Breweries represent the dominant revenue pool. Microbreweries are expanding most quickly as taproom legislation liberalizes across US states.
Installation:
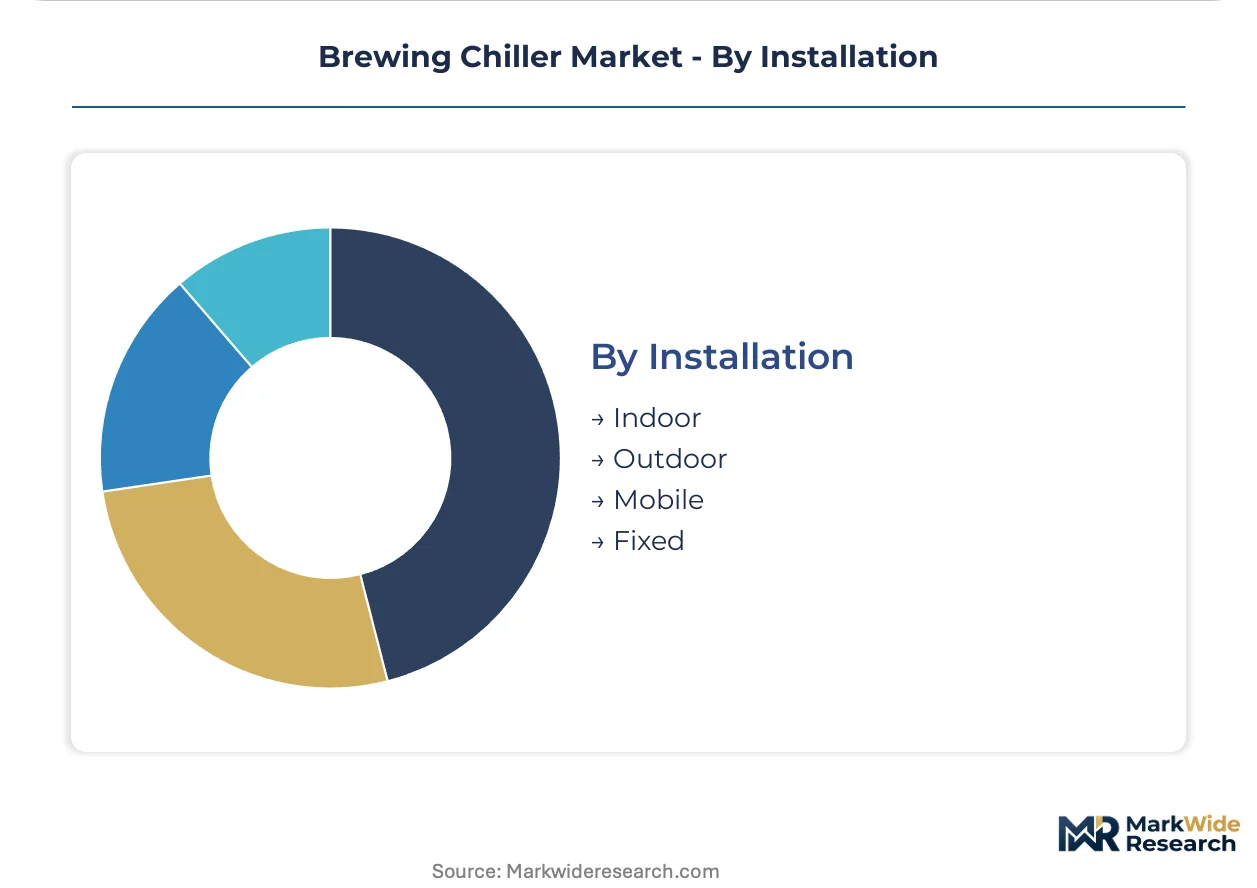
Environmental exposure ratings and mobility requirements cascade through enclosure specifications, refrigerant line routing, and power connection standards.
- Indoor:Climate-controlled mechanical rooms enable standard NEMA 1 enclosures and simplified glycol piping runs, dominating permanent production facilities with year-round operation.
- Outdoor:NEMA 3R or 4X rated enclosures with crankcase heaters protect compressors across freeze-thaw cycles, serving facilities where indoor floor space commands premium lease rates.
- Mobile:Trailer-mounted skids with quick-connect utilities enable seasonal and event-based production, requiring vibration isolation and DOT-compliant transport configurations.
- Fixed:Permanent pad-mounted installations with hard-piped utilities optimize efficiency for established production facilities with 10+ year lease commitments.
Fixed installations anchor the majority of capacity. Mobile configurations are expanding fastest among experiential hospitality operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA refrigerant phase-down mandates under the AIM Act anchor North American demand trajectories, while EU F-Gas Regulation timelines compress replacement cycles across Central European brewing clusters.
United States
Craft brewery proliferation in Seattle and Portland drives multi-zone glycol chiller specifications for temperature-controlled fermentation. EPA AIM Act refrigerant restrictions force equipment upgrades ahead of compliance deadlines. The Pacific Northwest corridor anchors dense supplier networks serving artisanal lager and ale producers.
Germany
Industrial lager producers face 2027 GWP reduction targets that obsolete existing R-404A installations. EU F-Gas Regulation enforcement accelerates centralized CO2 transcritical system adoption. Bavaria and North Rhine-Westphalia concentrate fabrication capacity expansion for Central European brewery modernization.
Czech Republic
Traditional pilsner breweries upgrade fermentation temperature precision to compete with craft segment entrants. REACH compliance deadlines for fluorinated gases reshape coolant procurement protocols. Prague and Plzeň anchor equipment specification clusters where brewhouse density constraints favor compact plate chiller architectures.
India
Mumbai and Bangalore brewery openings create first-mover positioning for glycol chiller suppliers establishing local service networks. Central Electricity Authority grid reliability standards influence backup cooling system specifications. Maharashtra and Karnataka sub-regions concentrate craft beer emergence with taproom legislation liberalization.
Australia
Independent brewing sector expansion in Melbourne and Sydney drives demand for outdoor-rated air-cooled systems. Therapeutic Goods Administration adjacent food-contact material standards govern glycol formulation compliance. Victoria and New South Wales anchor production facility clusters with water scarcity constraints eliminating water-cooled tower options.
Brewing Chiller Market Competitive Environment
Capability concentration sits with heat exchanger engineering specialists; scale advantage sits with integrated refrigeration skid providers. The vendor base stratifies across three tiers: multinational industrial refrigeration groups, regional fabrication specialists, and craft-focused equipment distributors. Strategic archetypes include premium plate heat exchanger designers, turnkey refrigeration skid integrators, and mobile air-cooled unit specialists. Competitive moves center on geographic service network expansion and predictive maintenance platform development.
Within the multinational tier, Alfa Laval and GEA Group exemplify divergent positioning strategies. Alfa Laval leverages Swedish engineering heritage in compact heat transfer architectures. GEA Group anchors German industrial refrigeration integration capabilities. Among North American craft specialists, Paul Mueller Company occupies a position bridging commercial-scale fabrication with craft brewery accessibility requirements.
| Leading Market Players |
|---|
| HGMC |
| Alfa Laval |
| TopChiller |
| Paul Mueller Company |
| SS Brewtech |
| Cold Shot Chillers |
| GEA Group |
| Tecogen |
| J&M Fluidics |
| Others |
Value Chain & Pricing Dynamics
Copper and stainless steel commodity volatility cascades through heat exchanger fabrication costs, compressing margin structures for chiller OEMs while forcing tiered pricing stratification across premium plate-based systems and economy glycol-loop alternatives. This input-cost uncertainty concentrates procurement leverage among fabricators with captive metalworking capacity in Germany and Japan, reshaping competitive positioning across the value chain.
Pricing Analysis
Price spreads between German-engineered plate chillers and Asian-fabricated glycol units span roughly 40-60% at equivalent cooling capacity, reflecting CE certification premiums and localized service network density. Three-tier pricing structure across premium, standard, and economy levels tracks heat exchanger alloy grade, compressor manufacturer origin, and predictive maintenance bundling. Pricing pressure stems from craft brewery capital constraints in emerging markets like India, where lease-to-own arrangements displace outright purchase. Microbreweries operating under 10 vessels exhibit highest price sensitivity, while industrial lager producers prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing for compressor assemblies concentrates among specialized facilities in Germany, Japan, and South Korea, with scroll and screw architectures feeding both European and North American chiller integrators. Heat exchanger plate stamping draws from stainless steel mills in Sweden, Italy, and China, while propylene glycol formulation sources from petrochemical complexes in the US Gulf Coast and Rotterdam. Single-source vulnerability sits with low-GWP refrigerant supply, where EU F-Gas Regulation phase-down schedules constrain R-454B and R-513A availability ahead of compliance deadlines. Distribution runs through three channels: direct OEM sales for large brewery projects, regional refrigeration distributors serving craft segments, and equipment leasing platforms targeting capital-constrained entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized refrigeration technician certification programs lag equipment complexity advances by roughly three training cycles, creating persistent service capacity constraints that advantage vendors with captive field engineering networks over pure-play fabricators.
For Market Incumbents: Pre-empt thermoelectric substitution threats in the sub-500-liter nanobrewery segment by acquiring solid-state cooling specialists or licensing Peltier array patents before cost curves intersect compressor economics. Defend margin position through backward integration into stainless steel heat exchanger fabrication, capturing commodity volatility spreads that currently erode OEM profitability. Prioritize predictive maintenance platform deployment to lock in recurring revenue streams as craft brewers shift toward capital-light operational models. For New Entrants and Emerging Players: Build out local service networks in Mumbai and Bangalore before established European vendors achieve density, leveraging India's craft beer legislative liberalization as first-mover territory. Target mobile air-cooled chiller deployments for festival and experiential hospitality operators, where water infrastructure constraints eliminate incumbent water-cooled solutions. Pursue OEM partnerships with Indian brewing equipment distributors rather than direct sales, accelerating market penetration through established channel relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors integrated refrigeration skid providers with CE marking convergence capabilities and established low-GWP compressor supply agreements. Long-term viability over the next decade hinges on IoT-enabled service revenue streams displacing transactional equipment sales. Acquisition targets should demonstrate predictive maintenance platform deployment or exclusive regional service network density. Watch EPA refrigerant phase-down enforcement velocity and EU F-Gas Regulation penalty implementation as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Fabrication | Captures stainless steel margin spreads and insulates against commodity volatility affecting Czech and German OEMs. |
| Predictive Maintenance Platform Launch | Converts transactional equipment sales into recurring SaaS revenue from Seattle and Portland craft brewery clusters. |
| Low-GWP Refrigerant Transition Certification | Secures EPA AIM Act compliance positioning ahead of R-404A obsolescence deadlines for North American installations. |
| Mobile Air-Cooled Unit Development | Addresses water-scarce Australian and festival brewing applications where fixed infrastructure is unavailable. |
| Regional Service Network Expansion | Builds defensible moats in India's emerging Maharashtra and Karnataka brewery corridors before incumbent arrival. |
Study Parameters
Initial hypotheses were tested against primary input from brewery operations managers, refrigeration service technicians, equipment procurement leads, and chiller OEM product directors, and refined through secondary validation across EPA refrigerant phase-down filings, EU F-Gas Regulation enforcement databases, SEC 10-K disclosures from listed industrial refrigeration groups, and customs trade data for stainless steel heat exchanger imports. Bottom-up triangulation aggregated fermentation vessel counts and chiller replacement cycles by brewery scale tier, while top-down analysis cross-checked against aggregate cooling capacity installations reported by regional brewing associations.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling capacity utilization at compressor foundries and heat exchanger fabrication facilities alongside craft brewery formation rates and industrial lager modernization cycles. Segmentation dimensions included product architecture, cooling technology, end-user scale tier, and installation environment, with CAGRs derived from regression analysis against historical replacement patterns and regulatory compliance deadlines. Industry-specific forecast inputs incorporated EPA AIM Act refrigerant phase-down schedules and EU REACH compliance timelines for fluorinated gas formulations.
Stress conditions across copper and stainless steel price bands, low-GWP refrigerant supply disruptions, and craft brewery formation rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and technician certification program expansion. Quarterly review of EPA refrigerant quota allocations, EU F-Gas Regulation penalty implementation, and Indian state-level taproom legislation progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Mill Mixer Market