
 North America Kombucha Market | 2026-2036
North America Kombucha Market Size, Share, and Industry Trends Forecast 2026-2036
North America Kombucha Market Outlook
Private-label contract manufacturing revenue is narrowing as established brands bring fermentation in-house. GT's Living Foods leverages captive brewing facilities across Southern California to control culture quality and batch consistency. Health-Ade Kombucha anchors its position through glass-bottle-only packaging that commands shelf-space premiums in Whole Foods and Sprouts locations. PepsiCo competes through Kevita's national retail distribution, extending refrigerated supply chain reach into conventional grocers previously underserved by live-culture beverages.
Kombucha denotes a fermented tea beverage produced through symbiotic culture of bacteria and yeast (SCOBY) activity, yielding organic acids, carbonation, and trace ethanol typically below 0.5% ABV. The primary commercial purpose centers on delivering probiotic-associated digestive wellness claims within ready-to-drink functional beverage portfolios. Flavored variants lead volume contribution, with ginger-turmeric and berry infusions capturing repeat purchase frequency in health-store channels. Cans represent the fastest-growing packaging format, displacing glass in convenience-store and outdoor-recreation use cases where weight and breakage risk deter selection. Supermarkets remain the dominant distribution channel, though online retailers are gaining traction in subscription-based replenishment models.
The FDA exercises jurisdiction over kombucha through its fermented foods guidance and alcohol-content thresholds that trigger TTAB excise-tax obligations when batches exceed 0.5% ABV. Health Canada enforces parallel labeling standards for probiotic content claims in cross-border Canadian commerce, while individual US states apply varying raw-food handling codes to small-batch producers. The USDA organic certification shapes ingredient sourcing requirements, particularly for tea and sugar inputs that constitute the bulk raw material cost stack. Stakeholders must monitor evolving state-level cottage-food exemptions and alcohol-testing protocols that determine whether products shelf in grocery refrigerators or regulated liquor channels.
Market Dynamics
Fermentation control technology is compressing batch-to-batch variability, allowing mid-scale producers to achieve consistency previously locked behind captive brewing infrastructure. This capability diffusion is eroding the quality gap between contract manufacturers and in-house operations.
Growth Catalysts
- California cottage-food exemptions:Streamlined licensing for home-based fermentation startups reduces regulatory entry barriers in the largest US state market.
- SCOBY cryopreservation:Advanced culture banking extends viable starter distribution timelines, enabling regional production without live-culture logistics.
- Fitness-center channel penetration:Post-workout functional beverage placement in boutique gyms and yoga studios captures recurring consumption rituals among wellness-focused demographics.
Market Restraints
- Organic tea input cost volatility:USDA-certified tea and cane sugar constitute the majority raw material stack, exposing margins to commodity price swings and certified-acreage constraints.
- Alcohol-testing protocol fragmentation:State-level ABV measurement requirements create compliance friction, with some jurisdictions mandating third-party laboratory verification that adds weeks to release cycles.
- Refrigerated supply chain concentration:Cold-chain dependency limits distribution to regions with adequate logistics infrastructure, excluding rural and ex-urban retail expansion.
Strategic Opportunities
- Canadian cross-border standardization:Health Canada probiotic labeling alignment with US FDA guidance creates unified North American product development pathways.
- Canned format outdoor-recreation channel:Lightweight, shatter-resistant packaging opens convenience-store and camping-supply retail previously inaccessible to glass-bottle formats.
- Subscription-based replenishment models:Direct-to-consumer recurring delivery bypasses slotting-fee barriers in conventional grocery while capturing lifetime value through predictable consumption patterns.
Industry Challenges
- Master brewer talent scarcity:SCOBY cultivation expertise and fermentation science specialization command premium compensation, constraining scale-up velocity for emerging brands.
- Multi-jurisdiction alcohol compliance:TTAB excise-tax triggering at 0.5% ABV requires real-time batch monitoring systems and legal contingency planning across state liquor control boards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Kombucha Market |
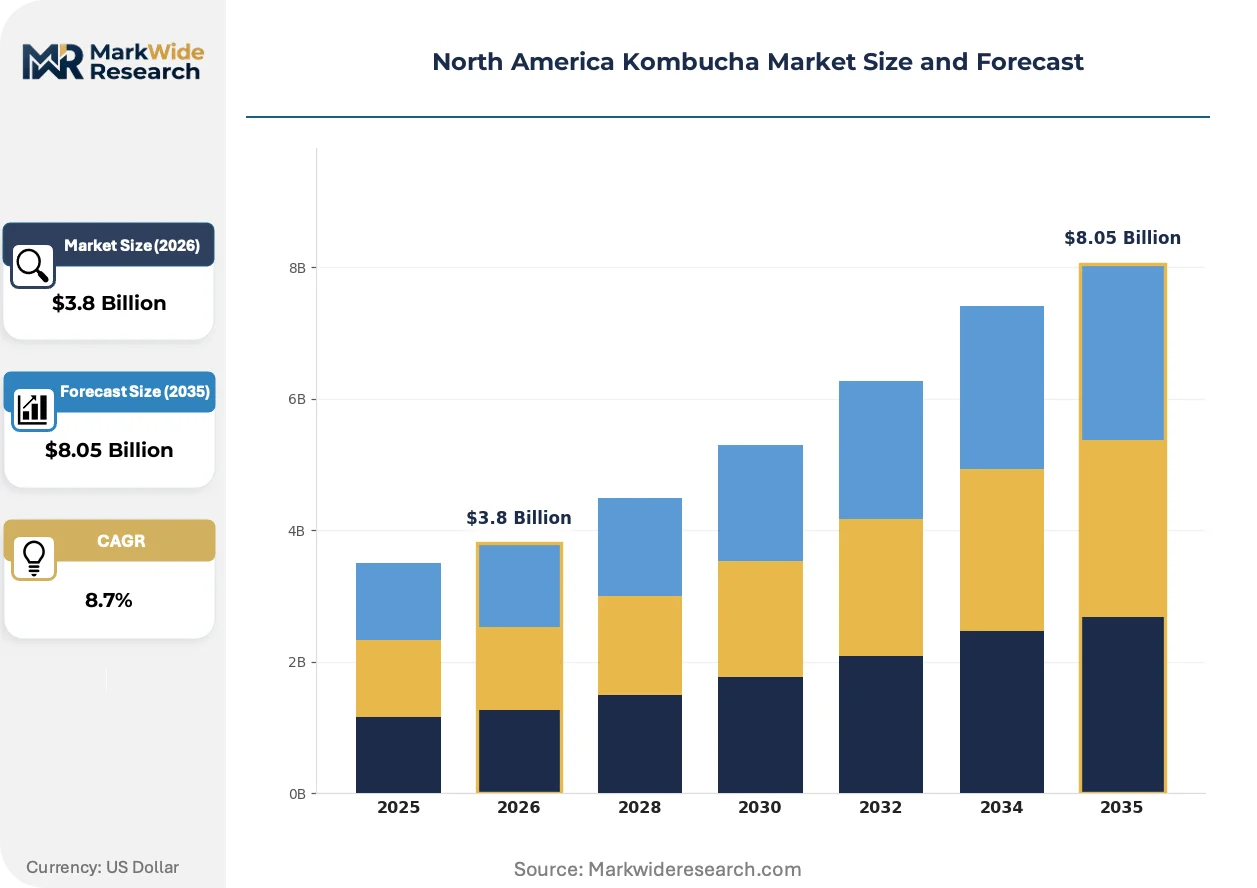
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original, Flavored, Organic, Raw Packaging Type: Bottles, Cans, Kegs, Pouches Distribution Channel: Supermarkets, Health Stores, Online Retailers, Restaurants End User: Health Enthusiasts, Regular Consumers, Fitness Centers, Cafes |
| Companies Covered | Revive Kombucha, NessAlla Kombucha, GT's Living Foods, Kevita, The Bu Kombucha, Health-Ade Kombucha, Humm Kombucha, PepsiCo, Brew Dr. Kombucha, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Kombucha Market Strategic Shifts
Packaging format diversification and precision fermentation analytics are compressing traditional quality-assurance timelines while expanding consumption occasions beyond health-food retail.
Continuous fermentation monitoring systems leveraging inline spectrometry are migrating from pharmaceutical bioprocessing to beverage applications. Mid-tier producers in Texas and the Pacific Northwest are adopting these sensors to replace manual pH and acidity testing. This technology is migrating from high-value biologics manufacturing to commodity fermented beverages, collapsing quality-control labor costs and enabling real-time batch intervention.
The FDA's evolving fermented foods guidance is tightening alcohol-content documentation requirements for products claiming non-alcoholic status. Producers must now maintain chain-of-custody records for ABV testing protocols. Small-batch operators in Oregon and Washington face particular adjustment burdens as state alcohol control boards harmonize with federal inspection standards.
Boutique fitness studios and specialty cafés are consolidating procurement authority previously dispersed across individual retail accounts. Multi-location wellness chains in California now negotiate direct supply agreements with regional kombucha breweries, displacing traditional distributor relationships. This concentration is most visible in Los Angeles and San Francisco metropolitan corridors where studio density supports dedicated delivery routes.
North America Kombucha Market Segmentation
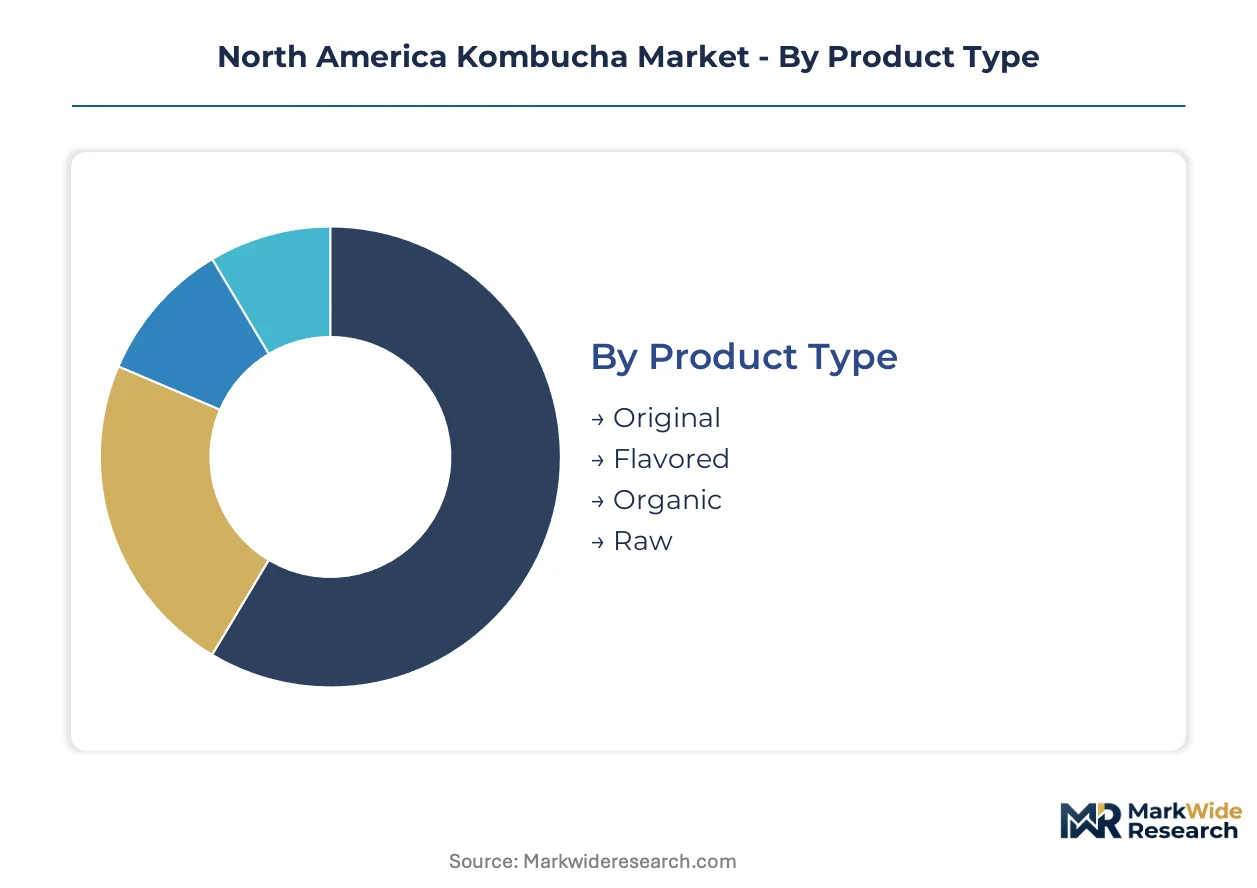
Segmentation in the North America kombucha market reveals how consumption occasions, packaging constraints, and channel economics fragment demand. Producers must align fermentation scale and cold-chain capabilities with specific buyer workflows rather than treating the category as monolithic.
Product Type:
The use-case spectrum spans ritual daily consumption to functional wellness targeting, with fermentation depth and ingredient purity driving price tier separation.
- Original:Unflavored kombucha maintains the highest SCOBY activity and lowest sugar residual, appealing to purists who prioritize digestive function over taste accessibility. Demand concentrates in Pacific Northwest metropolitan clusters where fermentation literacy runs deepest among consumers.
- Flavored:Ginger-turmeric and berry infusions mask acidity for entry-level drinkers while introducing adaptogenic positioning. California health-store channels and Texas fitness centers drive repeat purchase velocity for these variants.
- Organic:USDA-certified inputs command shelf-space premiums in Whole Foods and Sprouts locations where certification signals fermentation integrity.
- Raw:Unpasteurized live-culture claims require refrigerated custody throughout distribution, limiting reach to regions with adequate cold-chain infrastructure.
The dominant share belongs to Flavored, while Raw is closing the gap fastest through wellness-channel premiumization.
Packaging Type:
Cost tier separation between glass legacy formats and aluminum alternatives reshapes channel accessibility and logistics economics.
- Bottles:Glass containers preserve flavor stability and support premium positioning in specialty retail. Health-Ade's bottle-only strategy anchors this segment through visual differentiation and perceived quality signaling in high-end grocery.
- Cans:Aluminum formats reduce shipping weight and eliminate breakage risk, unlocking convenience-store and outdoor-recreation channels previously closed to kombucha. The Pacific Northwest and Colorado camping-supply retailers are adopting these SKUs fastest.
- Kegs:On-premise dispensing for cafes and fitness studios reduces per-ounce packaging cost while supporting fountain-style consumption rituals.
- Pouches:Flexible packaging targets single-serve portability for lunchbox and travel occasions, though cold-chain requirements constrain rollout velocity.
Bottles retain the dominant share, while Cans are expanding most quickly into mainstream retail previously served by sodas and seltzers.
Distribution Channel:
Customer type concentration determines margin structure, with direct relationships displacing traditional distributor economics in wellness-focused accounts.
- Supermarkets:Conventional grocery refrigerated sets reach the broadest consumer base but demand slotting fees and promotional support that strain emerging brand cash flows.
- Health Stores:Independent and chain natural retailers provide educated staff and fermentation-friendly shoppers willing to pay certification premiums.
- Online Retailers:Subscription replenishment models bypass retail gatekeepers while capturing predictable lifetime value through automated reordering.
- Restaurants:On-premise placement introduces kombucha to trial users through craft-cocktail mixology and non-alcoholic pairing menus.
Supermarkets command the dominant share, though Online Retailers are climbing the fastest as direct-to-consumer infrastructure matures.
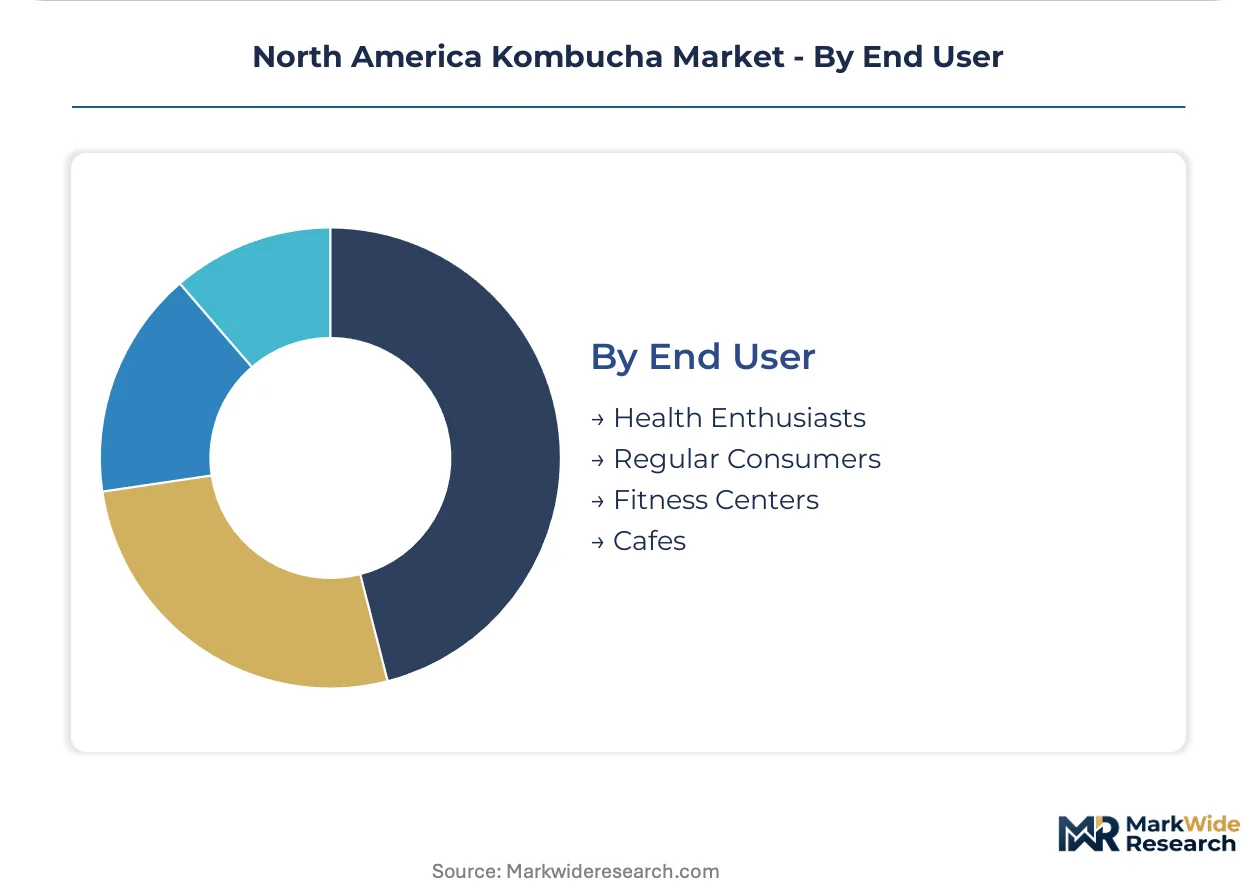
End User:
Volume concentration among institutional buyers is reshaping procurement patterns away from individual retail transactions.
- Health Enthusiasts:Core consumers with fermentation literacy drive category advocacy and premium tolerance, concentrating in California and Pacific Northwest urban centers.
- Regular Consumers:Mainstream adopters purchasing kombucha as soda replacement prioritize flavor accessibility and price parity over functional claims.
- Fitness Centers:Boutique gyms and yoga studios in Los Angeles and San Francisco metropolitan corridors now negotiate direct supply agreements, consolidating previously fragmented demand.
- Cafes:Specialty coffee chains use kombucha on tap to differentiate beverage programs and capture afternoon consumption occasions.
Health Enthusiasts hold the dominant share, while Fitness Centers are gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures sharply across North American markets, with Mexican buyers prioritizing affordability while Pacific Northwest consumers absorb certification premiums without volume attrition.
United States
FDA fermented-foods guidance and evolving ABV documentation requirements drive compliance investment among domestic producers. California cottage-food exemptions streamline licensing for home-based fermentation startups in Los Angeles and San Francisco metropolitan corridors. Pacific Northwest clusters in Oregon and Washington concentrate craft brewing infrastructure where wellness culture overlaps with fermentation literacy.
Canada
Health Canada probiotic labeling standards create cross-border alignment pressure for US exporters serving Ontario and Quebec markets. The country's national food regulator enforces parallel certification requirements that unified North American product development. British Columbia's Vancouver metro anchors West Coast demand concentration where organic certification commands shelf-space premiums.
Mexico
Price-conscious mainstream adoption prioritizes flavor accessibility over functional claims in Mexico City and Guadalajara metropolitan zones. The country's federal consumer protection agency applies beverage labeling standards that diverge from US FDA guidance on alcohol-content thresholds. Northern border states concentrate early craft fermentation infrastructure where cross-border supply chain integration reduces input cost volatility.
North America Kombucha Market Competitive Environment
Capability concentration sits with heritage fermentation specialists; scale advantage sits with diversified beverage conglomerates. The vendor base stratifies across three tiers: captive-brewing incumbents with multi-decade SCOBY cultivation expertise, contract-manufacturing private-label operators facing margin compression, and multinational entrants leveraging refrigerated distribution infrastructure. Dominant competitive moves include backward integration into culture banking and strategic partnerships with boutique fitness chains consolidating procurement authority.
Within the heritage specialist tier, GT's Living Foods and Health-Ade Kombucha occupy positions defined by fermentation infrastructure control and packaging differentiation. Kevita represents the scale-driven archetype, sitting within a diversified beverage portfolio that extends cold-chain reach into conventional grocery previously underserved by live-culture beverages. These three anchors exemplify how competitive positioning fragments between quality-signaling specialists and distribution-leveraged conglomerates.
| Leading Market Players |
|---|
| Revive Kombucha |
| NessAlla Kombucha |
| GT's Living Foods |
| Kevita |
| The Bu Kombucha |
| Health-Ade Kombucha |
| Humm Kombucha |
| PepsiCo |
| Brew Dr. Kombucha |
| Others |
Value Chain & Pricing Dynamics
Southern California's captive fermentation infrastructure anchors North American kombucha production capacity, with GT's Living Foods and Health-Ade Kombucha operating multi-facility brewing networks that translate culture-control advantages into shelf-space pricing power against contract-manufactured competitors.
Pricing Analysis
Subscription-based replenishment revenue streams now drive lifetime customer value as direct-to-consumer models bypass slotting-fee barriers. Three-tier pricing structure across premium glass-bottle, standard canned, and economy multi-serve formats separates Health-Ade's certification-premium positioning from Kevita's mass-market penetration. Price differentiation hinges on USDA organic certification and refrigerated custody requirements. Cost compression in the contract-manufacturing tier is intensifying because established brands are bringing fermentation in-house. Mainstream soda-replacement buyers exhibit highest price sensitivity; Pacific Northwest health enthusiasts absorb premium positioning without volume attrition.
Supply Chain Analysis
Extended payment terms from California-based organic tea suppliers and SCOBY culture banks are compressing working capital cycles for emerging producers. Raw material sourcing draws from India and China for USDA-certified tea inputs, with domestic cane sugar refining concentrated in Florida and Louisiana. Supply chain risk centers on single-source vulnerability for certified organic acreage constrained by climate volatility. Distribution runs through refrigerated third-party logistics networks that limit rural expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against functional seltzers and probiotic supplements that threaten kombucha's digestive wellness positioning. Incumbents must navigate hard seltzer incursions into the ready-to-drink functional beverage space.
For Market Incumbents: Pre-empt culture-quality arbitrage by investing in cryopreservation banking infrastructure that extends viable starter distribution timelines. Consolidate procurement relationships with boutique fitness chains in Los Angeles and San Francisco before regional competitors capture studio-channel volume. Hard seltzer substitution threats demand fermentation-integrity signaling through transparent ABV documentation protocols.
For New Entrants and Emerging Players: Pursue canned-format white space in convenience-store and outdoor-recreation channels where glass-bottle breakage risk has excluded legacy kombucha. Target Texas metropolitan corridors where craft brewing infrastructure overlaps with wellness-culture adoption gaps. Direct supply agreements with fitness-center procurement consolidators offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-control technology providers and regional brands with captive brewing infrastructure over contract-manufacturing private-label operators facing margin compression. Long-term viability across the projection horizon rests on culture-banking capabilities and multi-jurisdiction alcohol compliance systems. Watch for FDA fermented-foods guidance harmonization with state-level ABV protocols as the inflection signal for regulatory-compliance arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Culture Banking | SCOBY cryopreservation capabilities reduce starter logistics costs and batch variability for regional producers. |
| Canned Format Channel Expansion | Aluminum packaging unlocks convenience-store and camping-supply retail previously inaccessible to glass bottles. |
| Fitness Center Direct Supply Agreements | Multi-location wellness chains in California consolidate procurement authority away from traditional distributors. |
| Continuous Fermentation Monitoring Deployment | Inline spectrometry systems from pharmaceutical bioprocessing collapse quality-control labor costs for mid-tier producers. |
| Canadian Cross-Border Standardization | Health Canada probiotic labeling alignment creates unified North American product development pathways for US exporters. |
Study Parameters
A standing panel of master brewers, fermentation science specialists, health-store category buyers, and refrigerated logistics operators provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from FDA fermented-foods guidance documents, USDA organic certification databases, Health Canada labeling standards, and state-level cottage-food exemption records. Bottom-up volume triangulation across packaging formats, distribution channels, and regional consumption clusters was cross-checked against top-down value estimates derived from retail audit data and trade flow analysis.
Scenario-bracketing around organic input cost volatility and alcohol-testing protocol fragmentation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user procurement consolidation patterns. CAGRs were derived from trend extrapolation adjusted for regulatory harmonization timelines and cold-chain infrastructure expansion curves. Forecast inputs incorporated fitness-center channel penetration rates and subscription-model adoption velocity.
Sensitivities concentrate around FDA ABV documentation requirements, state-level cottage-food exemption revisions, and organic tea commodity price swings. Forecasts reflect documented assumptions regarding regulatory stability and cold-chain logistics availability. Macroeconomic contraction, federal-state regulatory divergence, or breakthroughs in ambient-stable live-culture preservation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Cold Pressed Juices Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Smoothies Market
Beverages
Double Valve Moka Pots Market
Beverages
India Soy Beverages Market
Beverages
Citrus Water Market
Beverages
Herb Infused Water Market
Beverages
Chocolate Powdered Drinks Market
Beverages
China Soy Beverages Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Japan Kombucha Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
North America Energy Drink Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Bottled Beverages Market
Beverages
Packaged Natural Mineral Water Market