
 Soft Serves Market | 2026-2036
Soft Serves Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Serves Market Analytics
Multi-source equipment procurement is pivoting toward vertically integrated supply partnerships as operators seek tighter quality control over refrigeration compressors and dispensing mechanics. Carpigiani Group leverages its Italian manufacturing heritage to sustain premium positioning in artisan gelato-soft serve hybrid machines. Taylor Company anchors North American commercial kitchen supply chains through extensive distributor networks and certified technician training programs.
Soft serve denotes a frozen dairy dessert extruded at approximately 18–22% overrun through continuous freezers, yielding a lighter, aerated texture than conventional hard-scoop ice cream. The product serves commercial foodservice operators seeking high-throughput dessert production with minimal labor and rapid customer turnaround. Specialty flavors command margin premiums in ice cream parlors and events, while vanilla and chocolate sustain volume throughput in supermarkets and convenience stores. Takeaway and dine-in service types dominate channel economics, though delivery logistics remain constrained by melt-time sensitivity and packaging insulation requirements.
The FDA enforces Grade A pasteurized milk standards for dairy-based soft serve, while NSF International certifies commercial food equipment sanitation protocols. Operators must navigate dual compliance frameworks governing both ingredient sourcing and machine hygiene cadence. Stakeholders should monitor evolving state-level sugar taxation proposals and plant-based dairy alternative labeling standards, as these regulatory shifts will reshape formulation strategies and equipment compatibility requirements.
Market Dynamics
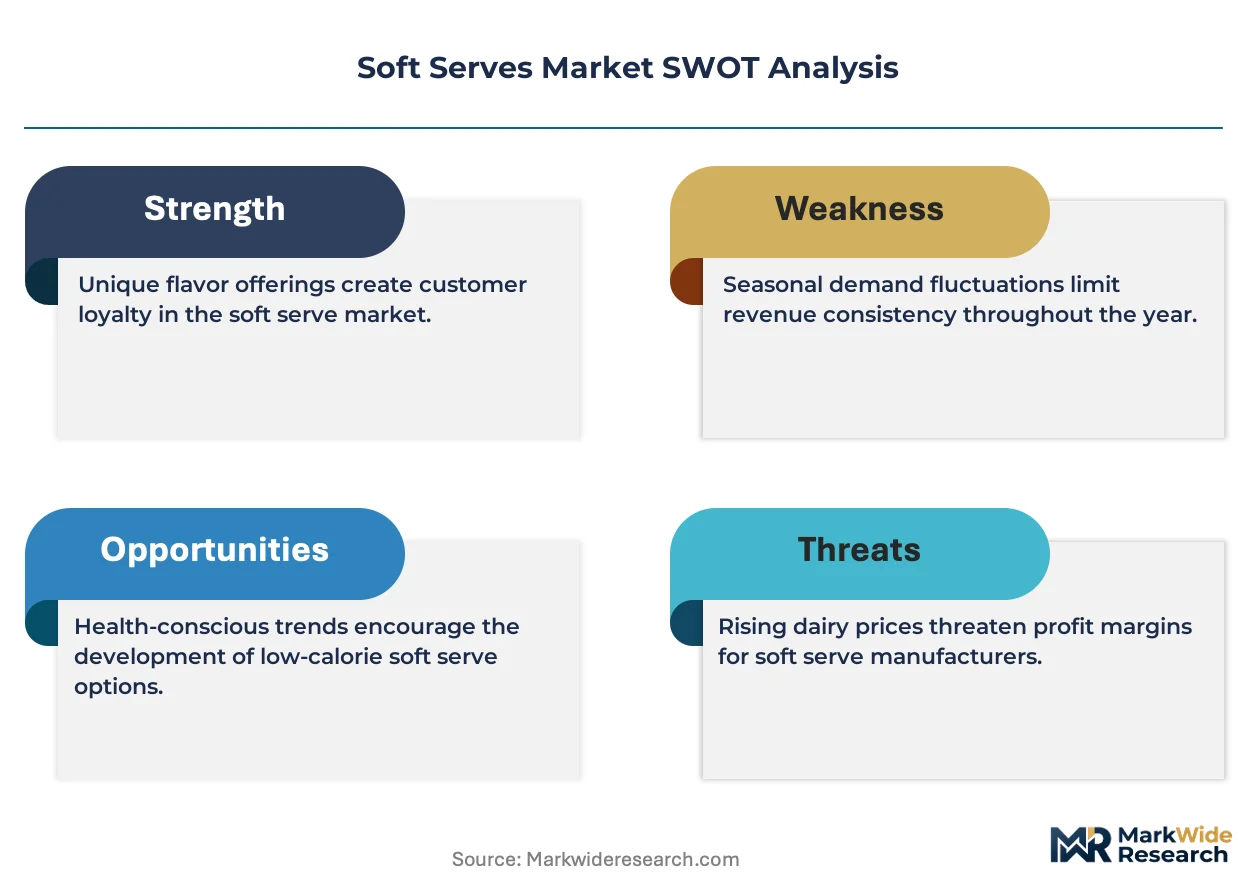
Quick-service restaurant chains are weaponizing soft serve as a high-margin attachment strategy, compressing equipment procurement cycles and forcing manufacturers to prioritize throughput reliability over feature differentiation.
Growth Catalysts
- Extended warm-weather seasons:Convenience store chains and seasonal boardwalk vendors in the United States are extending operating calendars, driving replacement demand for continuous freezer systems.
- NSF International certification protocols:Commercial food equipment sanitation mandates are accelerating upgrade cycles among legacy operators seeking compliance with current hygiene cadence standards.
- Plant-based dairy alternatives:Oat and coconut protein formulations are opening new flavor development pipelines for ice cream parlors targeting lactose-intolerant demographics.
Market Restraints
- Refrigeration compressor supply concentration:Italian and German component specialists control critical cooling system manufacturing, exposing operators to lead time volatility.
- Grade A Pasteurized Milk Ordinance friction:FDA equipment sanitation protocols impose dual compliance burdens on dairy-based soft serve operators navigating both ingredient sourcing and machine hygiene frameworks.
- Hard-scoop ice cream substitution:Premium artisan gelato and traditional ice cream retain texture advantages for dine-in dessert occasions, limiting soft serve penetration in full-service restaurants.
Strategic Opportunities
- India urban food courts:Organized retail expansion in Mumbai and Delhi is creating first-mover advantages for equipment vendors establishing service networks.
- Delivery logistics innovation:Insulated packaging and melt-time mitigation technologies are unlocking ghost kitchen and dark store channels previously excluded from soft serve economics.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon refrigerant restrictions are incentivizing retrofit demand for low-global-warming-potential compressor systems across European quick-service networks.
Industry Challenges
- Certified technician scarcity:Commercial dairy dispensing system maintenance requires specialized refrigeration and sanitation expertise that distributor training programs struggle to scale.
- Legacy equipment integration:Continuous freezer upgrades must interface with existing hopper and pump configurations, complicating retrofit timelines for multi-unit operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Serves Market |
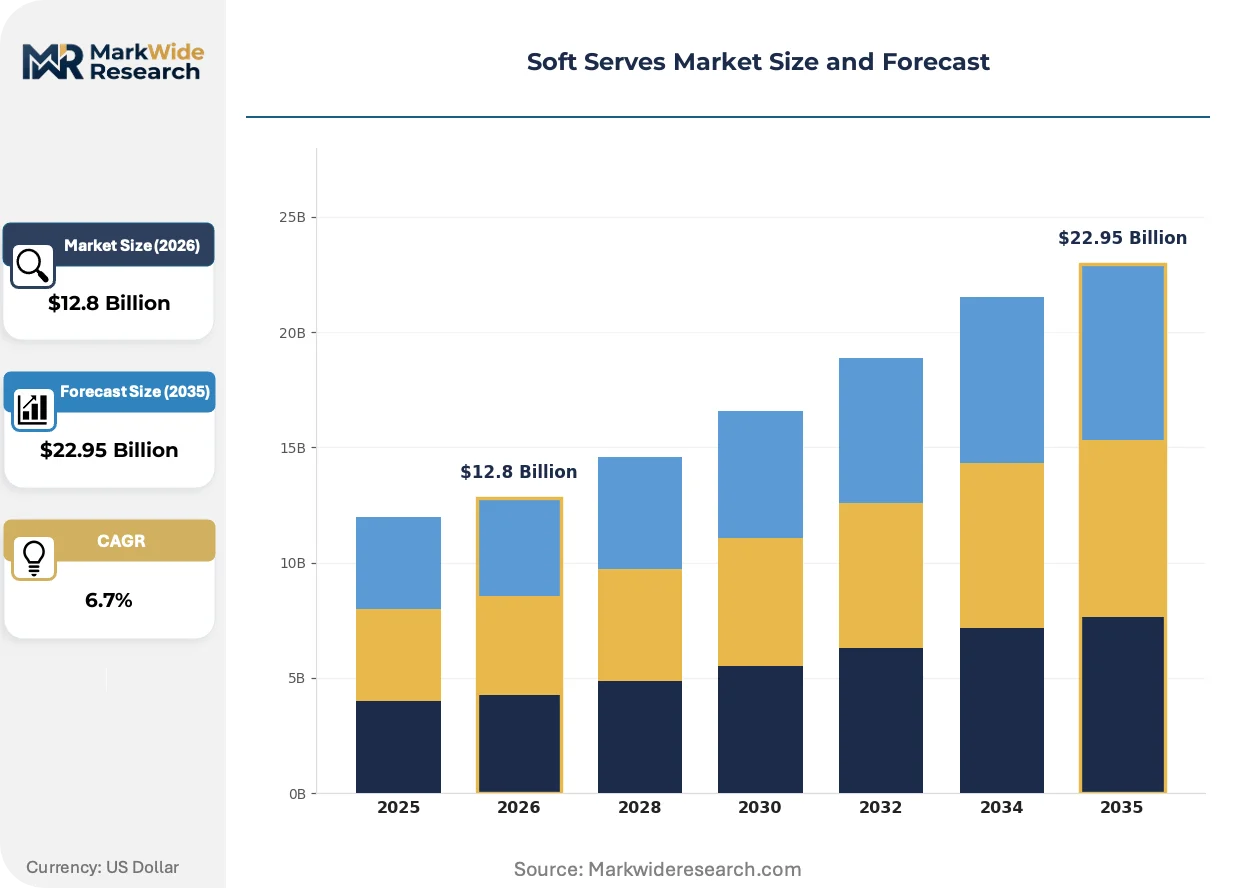
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanilla, Chocolate, Swirl, Specialty Flavors Distribution Channel: Supermarkets, Convenience Stores, Food Trucks, Ice Cream Parlors End User: Households, Restaurants, Cafes, Events Service Type: Takeaway, Dine-in, Delivery, Catering |
| Companies Covered | Carpigiani Group, Taylor Company, Electro Freeze, Stoelting, Spaceman Ice Systems, ICETRO America Inc., Donper USA, The Middleby Corporation, Gel Matic Italia Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Serves Market Evolving Landscape
Equipment architecture is fragmenting into interoperable subsystems, allowing operators to swap dispensing mechanics, flavor injection modules, and refrigeration compressors without full machine replacement.
Continuous freezer design is modularizing around standardized hopper interfaces and plug-and-play flavor injection systems. Mid-size ice cream parlor chains are adopting component-upgrade strategies rather than capital-intensive full replacements. This architecture is modularizing supplier relationships, enabling operators to source compressors from Italian specialists while retaining domestic dispensing mechanics.
REACH chemical substance restrictions are pressuring manufacturers to reformulate lubricants and seals used in dairy contact zones. Industrial consequence includes accelerated R&D cycles for food-safe synthetic alternatives. European quick-service operators are most affected, responding with supplier audit requirements that cascade to component vendors.
After-sales service unbundling is fragmenting traditional equipment-vendor relationships. Large convenience store chains are contracting directly with refrigeration specialists for compressor maintenance while sourcing dispensing mechanics from original manufacturers. This pattern is most visible in the United States, where multi-site operators prioritize uptime guarantees over single-source warranty coverage.
Soft Serves Market Segmentation
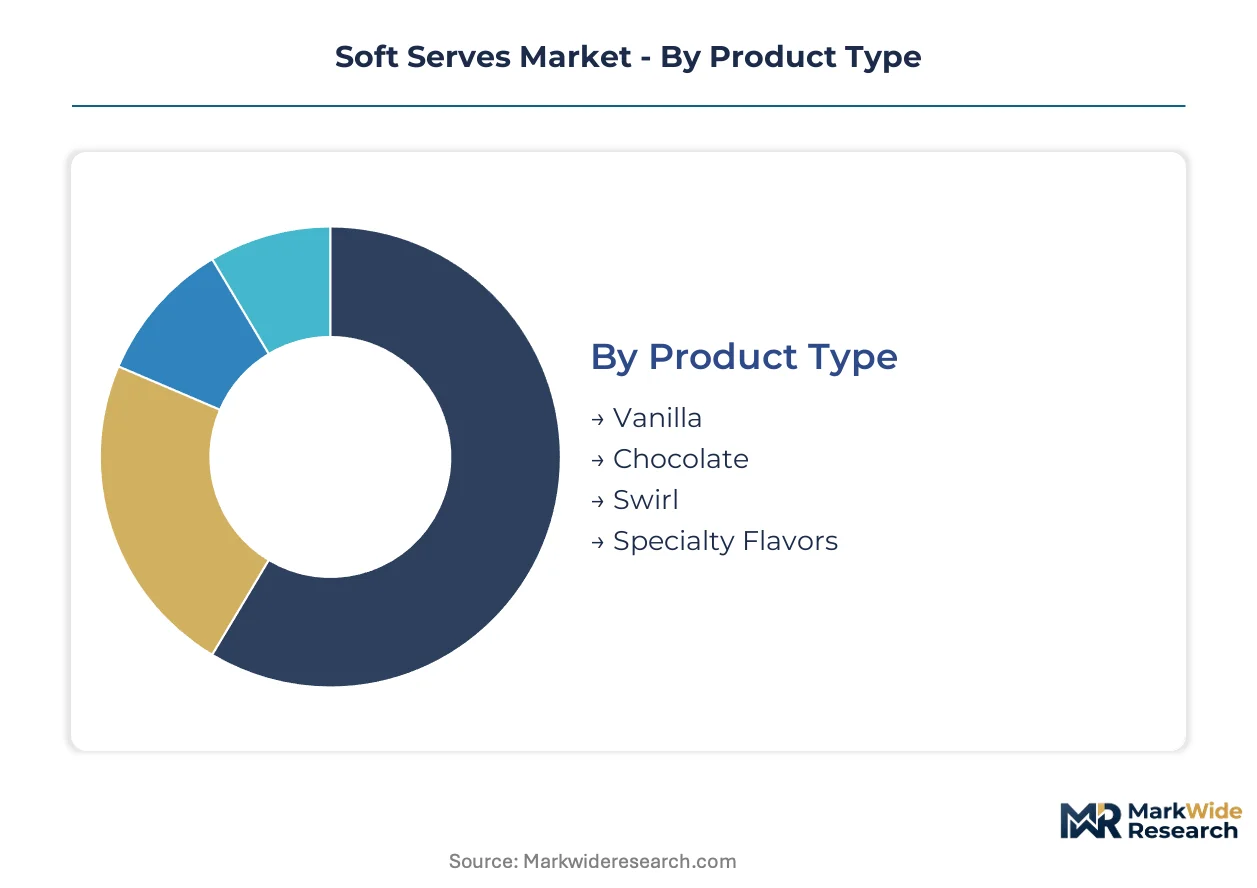
Soft serve segmentation reveals divergent equipment requirements and margin structures across flavor categories and service formats. Operators configure freezer systems differently for high-throughput convenience channels versus artisan parlor environments.
Product Type:
Customization intensity spans from standardized base flavors requiring minimal flavor-injection modules to complex specialty formulations demanding multi-hopper architectures.
- Vanilla:The foundational dairy base utilizes single-hopper continuous freezers with 18-22% overrun calibration. Demand concentrates in United States convenience store chains where vanilla sustains volume throughput during extended warm-weather operating calendars.
- Chocolate:Cocoa powder suspension requires enhanced agitation mechanics and dedicated sanitation protocols to prevent flavor cross-contamination. Quick-service restaurant chains deploy chocolate as a high-margin attachment alongside core food offerings.
- Swirl:Dual-extrusion systems combine vanilla and chocolate through synchronized dispensing mechanics. United States boardwalk vendors leverage swirl configurations for visual differentiation in seasonal high-traffic locations.
- Specialty Flavors:Modular flavor-injection modules enable rapid rotation of seasonal and limited-time offerings. Ice cream parlors command margin premiums through proprietary formulations targeting lactose-intolerant demographics with oat and coconut protein bases.
Leading the category by volume: Vanilla. Expanding most quickly: Specialty Flavors.
Distribution Channel:
Channel economics range from capital-intensive retail freezer installations to mobile equipment configurations with rapid deployment cycles.
- Supermarkets:Self-serve dispensing towers with automated portion control and integrated payment systems. Household demand in United States suburban locations drives replacement cycles for legacy continuous freezer systems.
- Convenience Stores:Compact countertop units with NSF International certification for 24-hour operation. United States chains extend operating calendars into shoulder seasons, accelerating equipment upgrade demand.
- Food Trucks:Mobile refrigeration compressors with vibration-resistant mounting and generator compatibility. Events and municipal permitting requirements shape procurement specifications across urban food court clusters.
- Ice Cream Parlors:Artisan gelato-soft serve hybrid machines with variable overrun adjustment and display case integration. Specialty flavor development pipelines differentiate positioning in competitive local markets.
Volume concentration: Supermarkets. Steepest expansion trajectory: Food Trucks.
End User:
User sophistication spans from residential occasional consumption to commercial high-throughput production with certified technician maintenance requirements.
- Households:Small-batch countertop appliances with domestic refrigeration compressors and simplified hopper cleaning protocols. United States residential demand peaks during summer months with limited year-round utilization.
- Restaurants:Back-of-house continuous freezers integrated with kitchen workflow and rapid customer turnaround objectives. Quick-service chains weaponize soft serve as high-margin dessert attachments to core food offerings.
- Cafes:Front-counter dispensing visibility with branded cup and cone presentation systems. Specialty coffee chains in India urban food courts deploy soft serve to extend daypart revenue capture.
- Events:Rental equipment fleets with rapid deployment logistics and temporary power infrastructure. Seasonal boardwalk vendors in United States coastal states drive concentrated demand spikes.
Dominant volume share: Restaurants. Gaining share fastest: Cafes.
Service Type:
Service format determines packaging insulation requirements and melt-time mitigation technology investments.
- Takeaway:Cone and cup configurations with immediate consumption assumptions and minimal packaging overhead. Convenience store chains in United States drive-through locations optimize for sub-60-second service intervals.
- Dine-in:Sundae assembly stations with topping bars and seated dessert occasion positioning. Full-service restaurants face substitution pressure from premium artisan gelato texture advantages.
- Delivery:Insulated packaging with phase-change materials and melt-time mitigation technologies. Ghost kitchen channels previously excluded from soft serve economics now unlock through logistics innovation.
- Catering:Batch-preparation systems with transport refrigeration and on-site dispensing setup. Events procurement emphasizes equipment reliability guarantees over feature differentiation.
Primary volume driver: Takeaway. Climbing the fastest: Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States convenience store chains and seasonal boardwalk vendors concentrate demand during extended warm-weather periods, driving replacement cycles for continuous freezer systems. Quick-service restaurant chains deploy soft serve as high-margin dessert attachments, compressing equipment procurement timelines across commercial foodservice networks.
United States
Convenience store chains extend operating calendars into shoulder seasons, accelerating demand for compact countertop units with NSF International certification. The FDA enforces Grade A Pasteurized Milk Ordinance protocols for dairy-based dispensing systems. Coastal boardwalk vendors in New Jersey and California drive concentrated seasonal spikes for dual-extrusion swirl configurations.
Germany
Quick-service networks prioritize retrofit demand for low-global-warming-potential compressor systems under EU F-Gas Regulation phase-down mandates. REACH chemical substance restrictions pressure manufacturers to reformulate lubricants and seals in dairy contact zones. Industrial equipment clusters in Bavaria and North Rhine-Westphalia anchor component manufacturing for European export markets.
China
Urban food court expansion in Shanghai and Beijing creates procurement volume for high-throughput continuous freezer systems. The national dairy regulator enforces pasteurization standards for commercial dispensing equipment. Manufacturing concentrations in Zhejiang and Guangdong provinces supply cost-optimized refrigeration compressors for domestic and Southeast Asian markets.
India
Organized retail expansion in Mumbai and Delhi generates first-mover opportunities for equipment vendors establishing certified technician training networks. FSSAI mandates govern dairy ingredient sourcing for commercial soft serve operations. Specialty coffee chains in Bangalore and Hyderabad deploy soft serve to extend daypart revenue capture beyond traditional beverage sales.
Italy
Artisan gelato-soft serve hybrid machines sustain premium positioning through heritage manufacturing expertise. ECHA oversees chemical compliance for food-contact materials under REACH frameworks. Equipment specialists in Emilia-Romagna maintain technical leadership in flavor-injection module architectures for European parlor chains.
Soft Serves Market Competitive Landscape
Backward integration into refrigeration compressor supply dominates the current landscape as operators seek tighter quality control over critical cooling subsystems. The vendor base separates into three strategic tiers: Italian heritage manufacturers commanding premium positioning, North American distributors anchoring extensive service networks, and Asian fabricators optimizing cost structures for volume procurement. Competitive intensity concentrates around M&A activity consolidating component suppliers and geographic expansion into underpenetrated urban food court clusters.
Within the heritage manufacturing tier, Carpigiani Group exemplifies Italian engineering positioning for artisan gelato-soft serve hybrid architectures. Taylor Company anchors North American commercial kitchen supply chains through certified technician training programs and distributor network density. Electro Freeze occupies the mid-market equipment segment, representing standardized continuous freezer configurations for convenience store and quick-service restaurant deployment.
| Leading Market Players |
|---|
| Carpigiani Group |
| Taylor Company |
| Electro Freeze |
| Stoelting |
| Spaceman Ice Systems |
| ICETRO America Inc. |
| Donper USA |
| The Middleby Corporation |
| Gel Matic Italia Srl |
| Others |
Value Network & Pricing Analysis
Backward integration into refrigeration compressor supply anchors both cost control and pricing power for soft serve equipment manufacturers, compressing margins for distributors who lack captive production of cooling subsystems. This upstream control dynamic intensifies as NSF International certification requirements and EU F-Gas Regulation phase-downs force rapid equipment refresh cycles across commercial foodservice networks.
Pricing Analysis
Warranty and service bundling separates premium Italian heritage manufacturers from unbundled North American distributors, with the former commanding 15-25% price premiums for integrated technician training and uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with NSF-certified units carrying sustained premiums over uncertified alternatives. Pricing pressure stems from Asian fabricators entering with cost-optimized compressor configurations, eroding mid-market positioning. Quick-service restaurant chains exhibit highest price sensitivity due to multi-unit procurement scale, while artisan ice cream parlors prioritize performance over unit economics.
Supply Chain Analysis
Certified refrigeration technician scarcity in Italy, Germany, and the United States constrains production scaling for precision cooling subsystems, extending lead times for continuous freezer manufacturers. Component sourcing draws from Italian and German compressor specialists, Chinese control system fabricators, and domestic stainless steel hopper suppliers. Single-source vulnerability concentrates in proprietary flavor-injection module architectures patented by Emilia-Romagna equipment specialists. Distribution runs through authorized dealer networks with mandatory technician certification, though large convenience store chains increasingly bypass intermediaries for direct compressor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft serves market functions as a vertical-integration race where compressor manufacturing capability determines margin capture, with players pursuing backward control over cooling subsystems to escape distributor margin stacking.
For Market Incumbents: Cement service network density through certified technician training programs that lock in multi-unit operator relationships and create switching costs. Defend against Asian cost-optimized entrants by accelerating modular equipment architectures that enable component-level upgrades rather than full replacement cycles. Prioritize captive compressor production or joint ventures with Italian specialists to secure supply continuity under EU F-Gas Regulation constraints. For New Entrants and Emerging Players: Ghost kitchen and dark store delivery channels offer the most penetrable entry vector, as melt-time mitigation technologies unlock previously excluded segments with lower incumbent saturation. Target India urban food court clusters in Mumbai and Delhi where organized retail expansion outpaces established service network coverage. Pursue direct-to-operator digital sales models that bypass traditional distributor markups and compress customer acquisition costs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by commercial kitchen equipment conglomerates seeking dessert category expansion. Long-term viability hinges on refrigerant transition readiness and modular architecture IP portfolios. Watch for FSSAI enforcement escalation in India as inflection indicator for regulatory-driven equipment replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Carpigiani Group's Italian heritage anchors premium positioning through captive cooling subsystem production. |
| Modular Equipment Architecture Development | Plug-and-play flavor injection modules enable operators to extend equipment life without full replacement. |
| Certified Technician Training Network Expansion | Taylor Company's North American distributor density locks in quick-service chain relationships through uptime guarantees. |
| Low-GWP Refrigerant System Retrofit | EU F-Gas Regulation phase-down mandates accelerate replacement demand across European quick-service networks. |
| Delivery Logistics Packaging Innovation | Phase-change material insulation unlocks ghost kitchen channels previously excluded from soft serve economics. |
Research Methodology
Trade association filings, customs import records, and NSF International certification databases formed the secondary backbone, supplemented by primary interviews with quick-service chain procurement directors, commercial equipment distributor principals, and certified refrigeration technicians. Bottom-up and top-down triangulation validated volume estimates across convenience store, supermarket, and food truck channels.
Bottom-up modeling anchored projections, with top-down macro validation from foodservice capital expenditure trends. Segmentation dimensions included product type, distribution channel, end user, and service format, with overrun calibration and flavor-injection complexity as industry-specific modifiers. CAGRs derived from historical replacement cycles, regulatory phase-in timelines, and warm-weather season extension patterns.
The model holds under stable refrigerant regulation transition schedules and continued quick-service attachment strategy adoption; deviation in FDA Grade A Pasteurized Milk Ordinance enforcement intensity or EU F-Gas Regulation acceleration would shift equipment procurement timelines. Material deviation in certified technician training program scaling or Asian compressor import tariff structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Powdered Soft Drinks Market
Beverages
Orange Juice Market
Beverages
Beverage Cooler Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
United States Soy Beverages Market
Beverages
Apple Juice Concentrate Market
Beverages
Botanical Infused Beverages Market
Beverages
Pineapple Juice Market
Beverages
Beverage Premix Market
Beverages
Water Flavor Market
Beverages
Sports and Energy Drinks Market
Beverages
India Cafes & Bars Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Caffeinated Beverage Market
Beverages
Fruit Vinegar Market
Beverages
Plant Based Beverages Market