
 Saudi Arabia Retail Bubble Tea Kits Market | 2026-2036
Saudi Arabia Retail Bubble Tea Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Retail Bubble Tea Kits Market Insights
Market Context
Multi-source ingredient procurement is recalibrating how Saudi bubble tea kit assemblers manage supply security and cost variability. ORBITEL INTERNATIONAL leverages its regional logistics network to secure tapioca pearl consistency across Gulf deliveries. Buddha Bubbles Boba differentiates through flavor R&D tailored to Middle Eastern palates. BOBA CHiC controls direct-to-consumer channels that bypass traditional retail markups in the Kingdom.
Technical Definition and Segment Structure
Saudi Arabia retail bubble tea kits are pre-packaged consumer assemblies containing tapioca pearls, flavored syrups, powdered bases, and optional toppings designed for at-home preparation of bubble tea beverages; kits typically specify brewing temperatures of 85-95°C for optimal pearl texture and shelf lives of 6-12 months under ambient storage. Complete kits capture the dominant revenue share as consumers prefer one-purchase solutions over component assembly. Online distribution channels register the fastest expansion, propelled by platform investments from Noon and Amazon.sa alongside dedicated beverage specialty portals. Premium price tiers sustain margin pools where packaging innovation and imported ingredient provenance justify elevated positioning.
Regulatory Framework and Outlook
SFDA governs food-contact materials and additive permissions for pearl formulations, while MOHAP enforces nutritional labeling and import documentation for products entering Saudi distribution. The General Authority for Food and Drug Administration's alignment with Gulf Standardization Organization (GSO) technical regulations harmonizes cross-border kit movements within GCC markets. Stakeholders must monitor evolving halal certification requirements for emerging topping categories including gelatin-based jellies and dairy derivatives.
Market Dynamics
Home-preparation convenience is compressing traditional café consumption in Saudi Arabia's Central Province, where young urban households now prioritize shelf-stable kit formats that replicate out-of-home beverage experiences without venue dependency.
Growth Catalysts
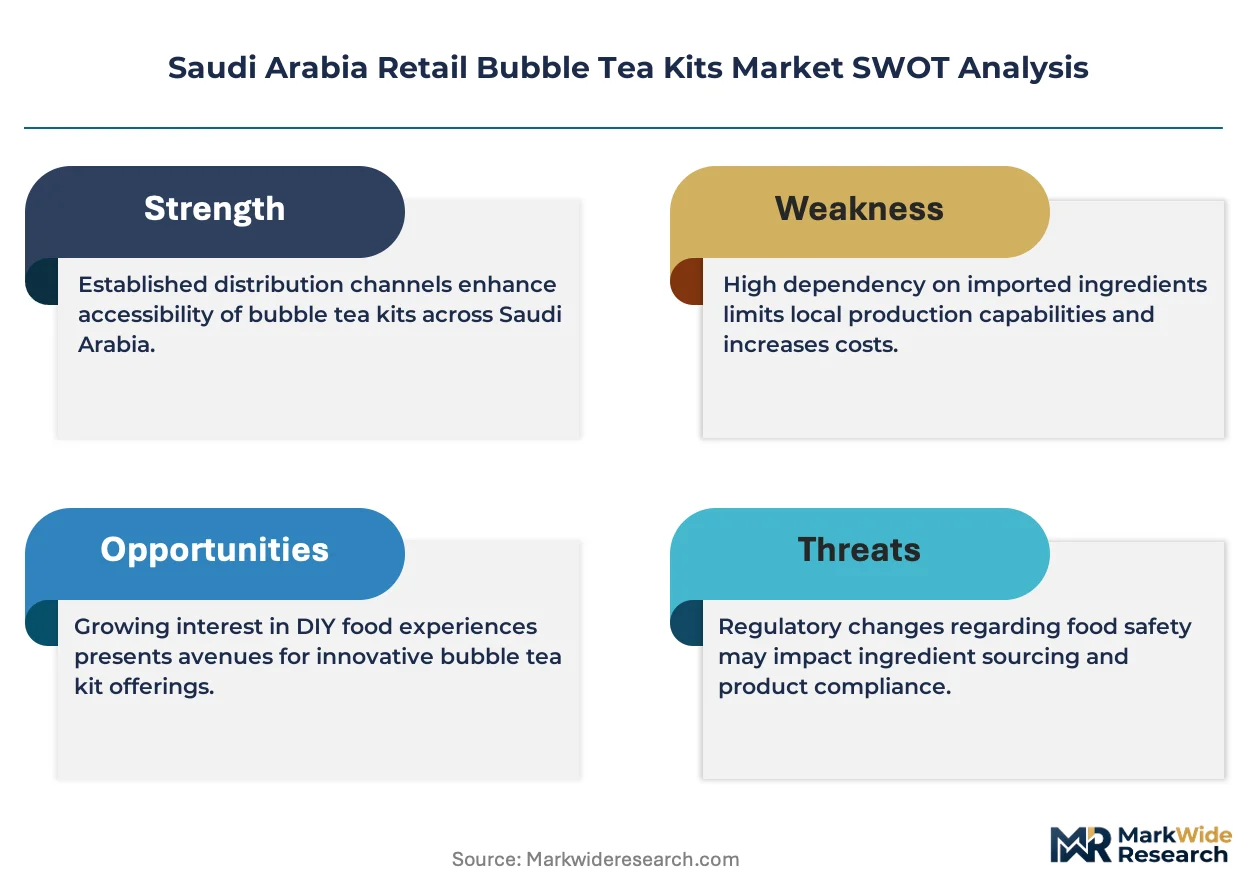
- SFDA food-contact material standards:Harmonized safety protocols for pearl packaging are reducing cross-border friction for GCC-sourced ingredients, accelerating kit assembler entry into Saudi distribution.
- E-commerce platform investments:Noon and Amazon.sa fulfillment infrastructure is collapsing delivery timelines for premium complete kits across Riyadh and Jeddah metropolitan zones.
- Halal certification alignment:Unified GSO technical regulations are streamlining topping ingredient approvals, expanding permissible formulation ranges for domestic kit producers.
Market Restraints
- Tapioca pearl import dependency:Southeast Asian supply concentration exposes assemblers to freight rate volatility and harvest-season quality inconsistency.
- MOHAP nutritional labeling friction:Bilingual Arabic-English packaging mandates extend product development cycles and elevate compliance costs for imported kit brands.
- Fresh-beverage substitution:Established café chains in Jeddah's Tahlia Street corridor retain experiential loyalty that shelf-stable kits cannot replicate.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar metropolitan areas lack dedicated bubble tea kit retail presence, creating first-mover whitespace for platform-anchored distribution.
- Subscription channel innovation:Recurring delivery models for flavor rotation kits are capturing household pantry-share from single-purchase formats in Riyadh's gated communities.
- SFDA additive approval expansion:Emerging clean-label stabilizers for extended ambient shelf life are opening formulation differentiation for premium positioning.
Industry Challenges
- Halal gelatin sourcing complexity:Certification timelines for bovine-derived jellies and dairy toppings are extending supplier qualification periods beyond standard procurement cycles.
- Temperature-controlled last-mile gaps:Ambient storage claims for pearls and syrups face validation pressure during Saudi summer logistics, requiring investment in heat-stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Retail Bubble Tea Kits Market |
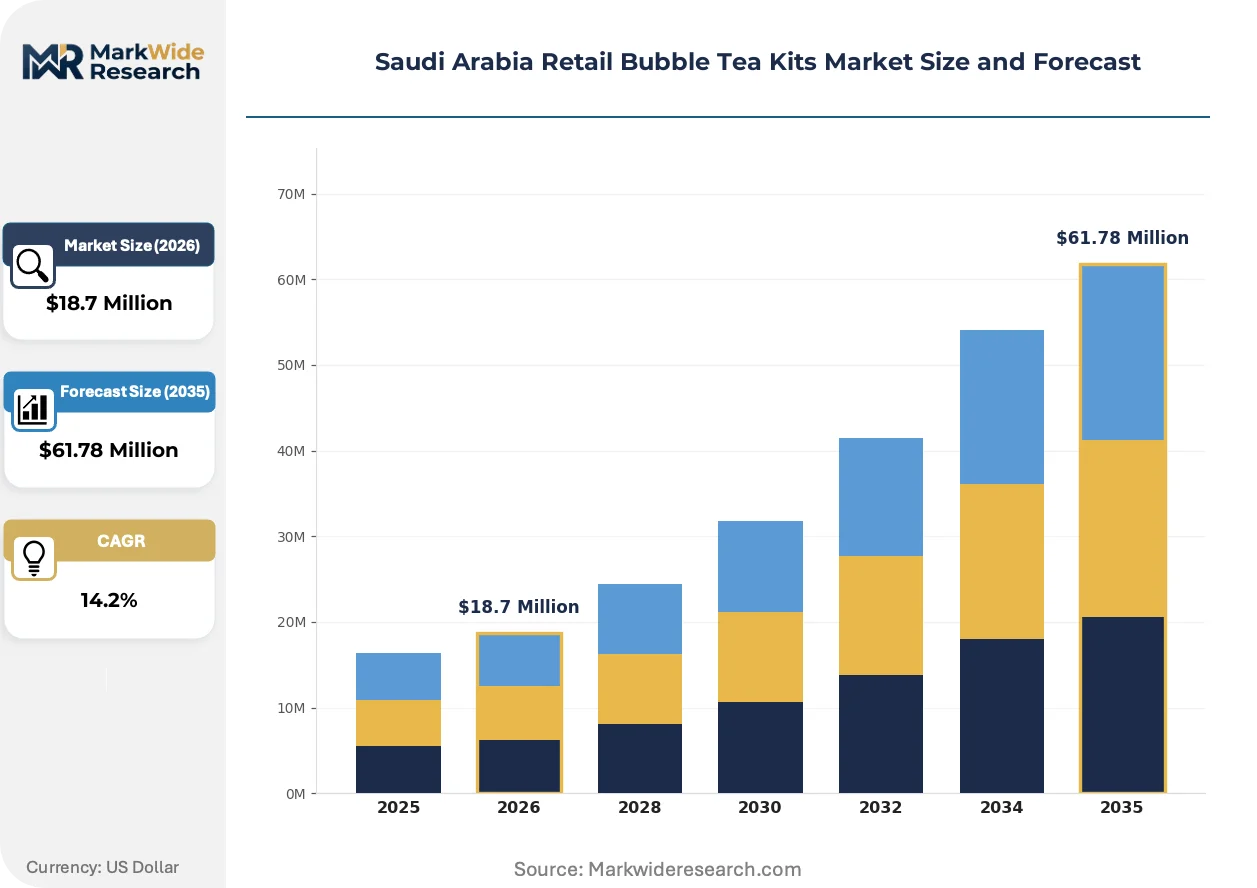
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pearl Kits, Flavor Kits, Topping Kits, Complete Kits Customer Type: Retailers, Online Consumers, Cafés, Restaurants Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | ORBITEL INTERNATIONAL, Locca Bubble Tea, The Bubble Tea Club, THE TEASHED, Buddha Bubbles Boba, BOBA CHiC, Boba Barista, BUBBLE TEA HOUSE COMPANY, Bubble Tea Supply, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Retail Bubble Tea Kits Market Trends and Innovations
Formulation science and channel infrastructure are converging to reshape how Saudi consumers access bubble tea preparation at home, with regulatory harmonization and platform economics accelerating format experimentation.
Modified starch technology is unifying texture stability across variable Saudi storage conditions, replacing traditional tapioca formulations that degrade in ambient Gulf heat. Kit assemblers serving Central Province households are adopting these pearl alternatives to reduce return rates and extend unopened shelf claims. The shift is compressing supplier qualification timelines while raising the technical barrier for new market entrants.
SFDA alignment with GSO cross-border technical regulations is standardizing additive permissions for bubble tea toppings across GCC member states. This regulatory convergence is enabling Saudi-based kit producers to source from UAE and Bahrain distributors without duplicate safety documentation. Smaller assemblers lacking in-house regulatory affairs capacity are outsourcing compliance verification to specialized Gulf consultancies.
Platform-native discovery is displacing traditional retail browsing for bubble tea kit acquisition in the Kingdom. Young Saudi households in Riyadh's northern districts now encounter new flavor formats through algorithmic recommendation rather than supermarket aisle exploration. This behavioral pivot is elevating content investment requirements for kit brands while compressing the window for organic product awareness.
Saudi Arabia Retail Bubble Tea Kits Market Segmentation
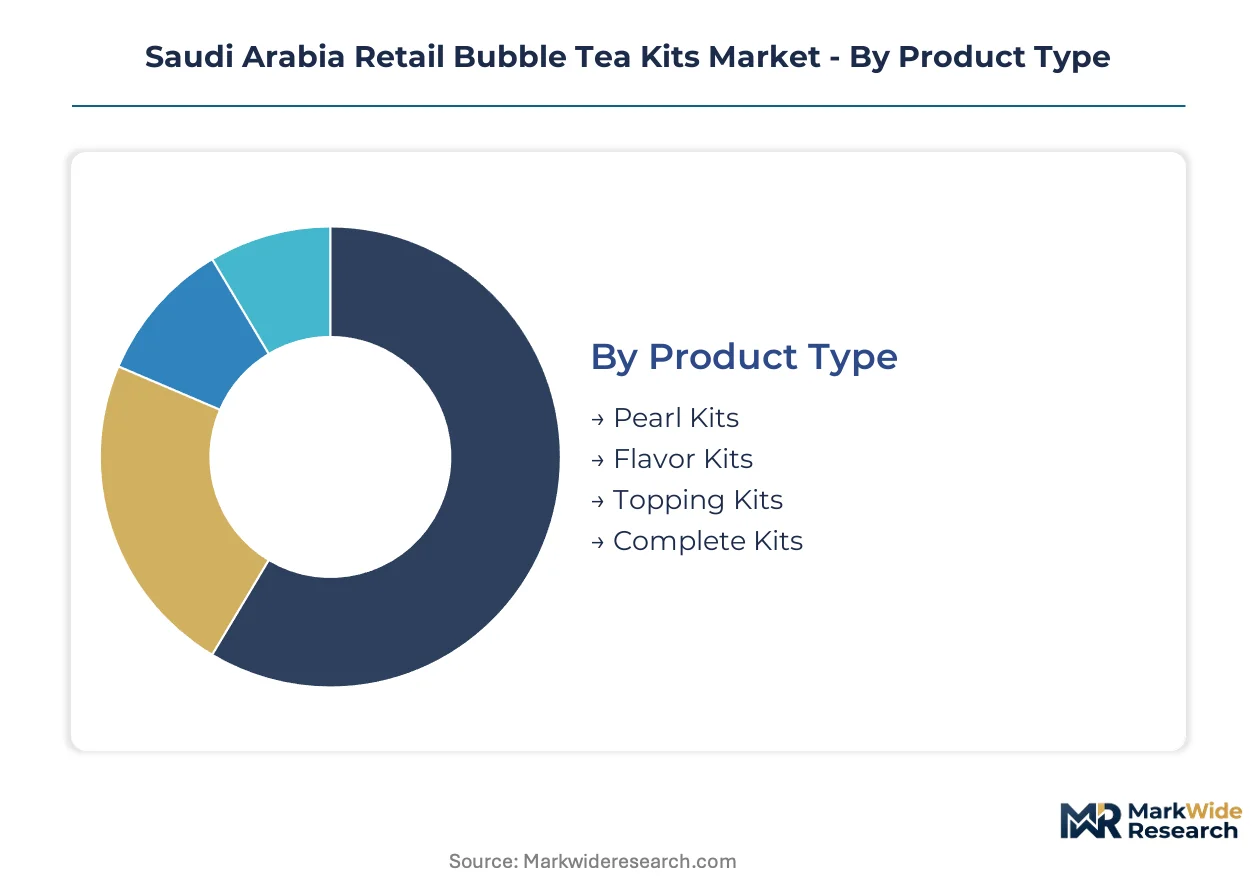
Segmentation in Saudi Arabia's retail bubble tea kits market reveals how kit configuration, procurement behavior, and channel economics fragment demand across Riyadh and Jeddah metropolitan zones. Each dimension exposes distinct margin pools and regulatory exposure profiles for assemblers navigating SFDA compliance and MOHAP labeling mandates.
Product Type:
Standalone pearl and flavor formats serve occasional home-preparers seeking component flexibility, while embedded complete kits target households prioritizing convenience over customization depth.
- Complete Kits:Pre-assembled packages containing pearls, syrups, powdered bases, and optional toppings in unified packaging with synchronized shelf-life claims. Riyadh's northern gated communities drive household penetration where pantry consolidation matters more than flavor experimentation.
- Pearl Kits:Standalone tapioca pearl sachets requiring separate syrup and base procurement. Jeddah's young urban renters favor this format for cost control and portion flexibility, though import dependency for Southeast Asian tapioca starch creates supply fragility.
- Flavor Kits:Concentrated syrup and powder combinations without pearl components. Home baristas in Dammam's emerging suburbs adopt these for beverage variety without pearl preparation complexity.
- Topping Kits:Specialized assemblies of jellies, popping boba, and dairy derivatives requiring halal certification verification. Extended SFDA approval timelines for gelatin-based inclusions constrain domestic formulation expansion.
Volume placements concentrate in Complete Kits; the faster expansion belongs to Pearl Kits.
Customer Type:
Procurement scale and repeat frequency separate institutional buyers from household purchasers, with channel access and certification requirements diverging sharply across the quartet.
- Online Consumers:Individual households purchasing through Noon, Amazon.sa, and specialty beverage portals for home pantry stocking. Riyadh's tech-native young families drive subscription adoption for flavor rotation kits.
- Retailers:Supermarket chains and convenience operators sourcing for shelf placement. Carrefour and Lulu Hypermarket procurement teams negotiate consolidated logistics contracts with kit assemblers serving Central Province distribution.
- Cafés:Small-format beverage operators purchasing kits for menu experimentation or supply contingency. Jeddah's independent café scene along Tahlia Street corridor uses kits to test seasonal flavors without bulk ingredient commitment.
- Restaurants:Full-service dining establishments adding bubble tea to beverage programs. Khobar's family dining clusters in Eastern Province represent underpenetrated whitespace for kit-based menu expansion.
Transaction volume concentrates in Online Consumers; steepest expansion trajectory sits with Retailers consolidating platform-anchored procurement.
Distribution Channel:
Channel selection determines margin capture, with direct and platform-native routes bypassing traditional retail markups while specialty stores sustain premium positioning through experiential discovery.
- Online:E-commerce platforms and brand-direct websites with algorithmic recommendation engines. Noon and Amazon.sa fulfillment infrastructure collapses delivery timelines across Riyadh and Jeddah metropolitan zones.
- Supermarkets:Mass retail chains with dedicated beverage aisles and promotional slotting fees. Lulu and Carrefour hypermarkets in Central Province anchor volume placement for mid-range complete kit formats.
- Specialty Stores:Dedicated tea and beverage retailers offering tasting demonstrations and staff guidance. Jeddah's boutique tea merchants sustain premium kit positioning through imported ingredient provenance storytelling.
- Direct Sales:Manufacturer-to-institution contracts bypassing distributor margins. Large café chains in Riyadh negotiate direct procurement for standardized kit specifications across multiple outlet locations.
Revenue share concentrates in Online; the channel gaining share fastest is Specialty Stores.
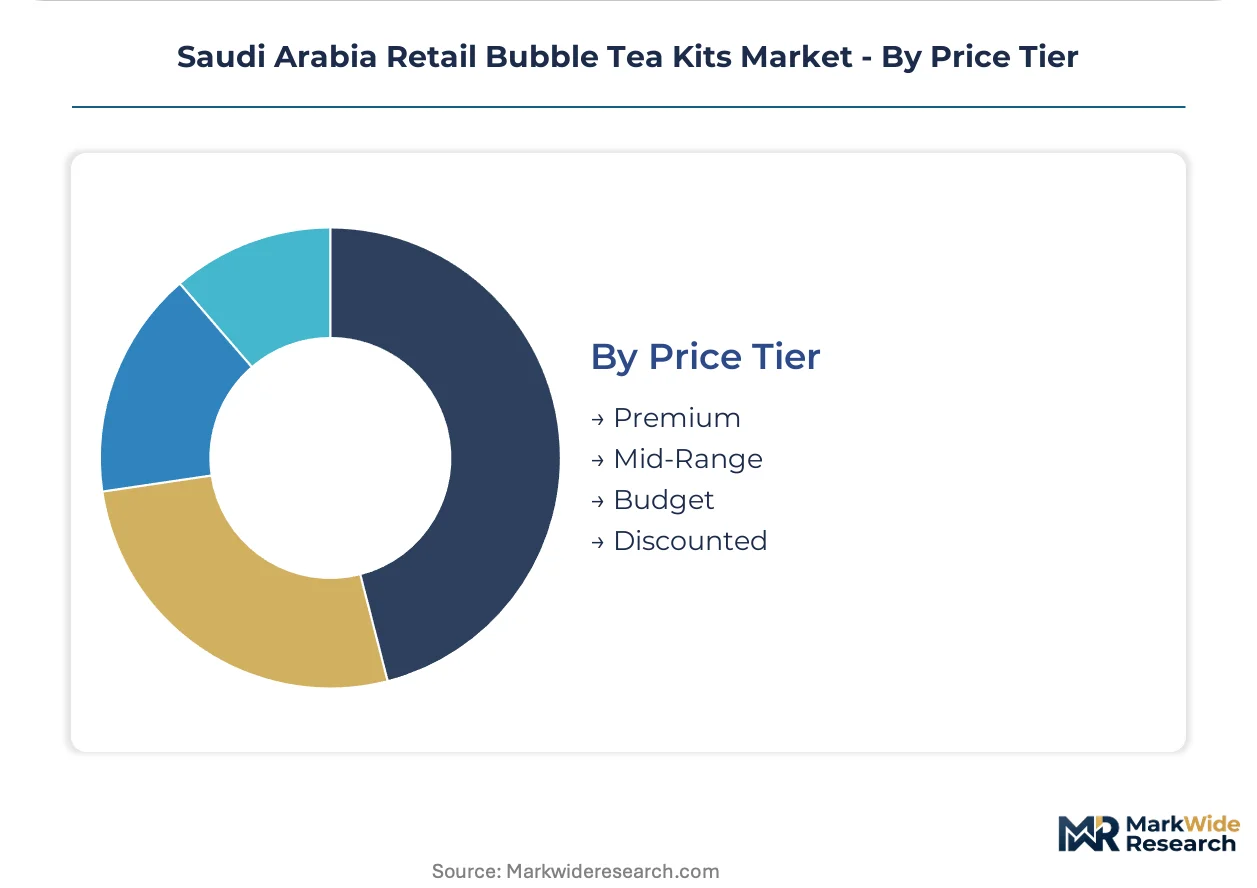
Price Tier:
Price stratification aligns with packaging innovation depth, import ingredient ratios, and shelf-life extension technology, creating four distinct margin bands with diverging customer loyalty profiles.
- Premium:Kits featuring imported Taiwanese tapioca pearls, natural flavor extracts, and extended ambient stability claims. Riyadh's affluent households in Diplomatic Quarter and King Abdullah Financial District sustain this tier through gift-oriented purchasing.
- Mid-Range:Balanced formulations with regional ingredient sourcing and standard packaging. Jeddah's middle-income young professionals drive repeat purchase frequency in this tier through platform subscription models.
- Budget:Cost-optimized kits with modified starch pearls and synthetic flavor profiles. Price-sensitive households in Eastern Province's emerging suburbs favor this format for entry-level home preparation experimentation.
- Discounted:Promotional and near-expiry inventory clearing through flash sales and outlet channels. Seasonal surplus from premium tier overproduction feeds this segment during Ramadan and summer clearance cycles.
Unit volume concentrates in Mid-Range; the tier climbing fastest is Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tapioca starch supply corridors from Southeast Asia anchor kit distribution across Saudi Arabia's metropolitan zones. Central Province logistics hubs consolidate pearl imports for re-export to Gulf neighbors under harmonized SFDA-GSO standards.
Central Province
Riyadh's northern gated communities drive household kit penetration through Noon and Amazon.sa subscription models. SFDA food-contact material standards govern pearl packaging for ambient shelf stability claims. King Abdullah Financial District office clusters sustain corporate gifting demand for premium complete kits during Ramadan cycles.
Western Region
Jeddah's Tahlia Street café corridor retains experiential beverage loyalty that challenges home-preparation substitution. MOHAP bilingual labeling mandates extend product development timelines for imported brands entering Red Sea port distribution. Young urban renters in Al-Hamra district favor pearl-only formats for cost-controlled experimentation.
Eastern Province
Dammam and Khobar metropolitan areas present underpenetrated whitespace for platform-anchored kit distribution. The General Authority for Food and Drug Administration's GCC alignment enables UAE-sourced kit transshipment without duplicate safety documentation. Family dining clusters in Dhahran seek menu expansion through kit-based bubble tea programs.
NEOM Northwest
Planned urban development zones anticipate imported kit demand from expatriate construction and hospitality workforces. GSO technical regulation harmonization facilitates cross-border movement from Jordanian and Egyptian distributors. Trojena and Sindalah project sites represent emerging institutional procurement channels for standardized kit specifications.
Saudi Arabia Retail Bubble Tea Kits Market Competitive Landscape
Global majors compete with regional champions across logistics infrastructure and flavor localization capabilities. The Saudi market exhibits tiered concentration where Gulf-based distributors leverage proximity advantages against Asian kit originators. Three archetypes dominate: regional logistics integrators controlling cross-border pearl consistency, direct-to-consumer platform natives collapsing retail markups, and flavor R&D specialists tailoring Middle Eastern palates. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as assemblers secure Southeast Asian tapioca supply commitments.
Within the regional logistics tier, ORBITEL INTERNATIONAL represents Gulf distribution anchoring through its network spanning Saudi Arabia and neighboring emirates. Buddha Bubbles Boba occupies a position exemplifying flavor localization specialization, with its naming convention suggesting Middle Eastern market orientation. BOBA CHiC sits within the platform-native archetype, its stylized branding indicating direct-to-consumer channel prioritization that bypasses traditional retail intermediaries in the Kingdom.
| Leading Market Players |
|---|
| ORBITEL INTERNATIONAL |
| Locca Bubble Tea |
| The Bubble Tea Club |
| THE TEASHED |
| Buddha Bubbles Boba |
| BOBA CHiC |
| Boba Barista |
| BUBBLE TEA HOUSE COMPANY |
| Bubble Tea Supply |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap kit assemblers dominate Saudi distribution, anchoring pricing discipline through long-standing relationships with Southeast Asian tapioca suppliers while absorbing freight volatility that erodes margin pools for newer entrants lacking volume leverage.
Pricing Analysis
Warranty-equivalent shelf-life guarantees differentiate premium kits from unbundled economy formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by import ingredient ratio and halal certification tier. Cost compression in budget tiers is intensifying because modified starch substitution erodes traditional tapioca pearl premiums. Online subscription households in Riyadh exhibit lowest price sensitivity; Eastern Province first-time buyers show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Jeddah Islamic Port and King Abdulaziz Port in Dammam consolidate inbound Southeast Asian pearl shipments for hub-and-spoke redistribution. Thailand, Vietnam, and Taiwan anchor global tapioca starch supply. Kit assemblers draw from modified starch alternatives, flavored syrup concentrates, and halal-certified gelatin derivatives. Single-source vulnerability in Thai harvest seasons exposes Q3 inventory gaps. Distribution runs through platform-anchored fulfillment networks bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA food-contact material standards create a cost-of-compliance moat where certification investment separates viable assemblers from margin-compressed opportunists seeking rapid market entry.
For Market Incumbents: Lock in multi-year tapioca supply commitments with Thai processors before harvest-season volatility accelerates. Extend backward integration into regional pearl repackaging facilities in Dammam to reduce import duty exposure. Emerging platform-native competitors threaten direct-to-consumer channel control; defend via exclusive flavor development partnerships with Noon and Amazon.sa. For New Entrants and Emerging Players: Launch via subscription-first models targeting Riyadh's northern gated communities where pantry-share rotation captures recurring revenue without retail slotting fees. Eastern Province family dining clusters represent the most penetrable whitespace for kit-based menu expansion. Position through halal-certified topping specialization to bypass SFDA approval bottlenecks slowing gelatin-based competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional logistics integrators with captive Gulf distribution networks during freight rate spikes. Long-term viability hinges on platform-native customer acquisition costs stabilizing below lifetime value thresholds. Watch for modified starch patent expirations as inflection signal for ingredient cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA-aligned GSO standards unlock GCC cross-border kit movement without duplicate documentation. |
| Subscription Channel Launch | Noon and Amazon.sa fulfillment infrastructure enables recurring revenue capture in Riyadh metropolitan zones. |
| Modified Starch Formulation Shift | Pearl alternatives reduce return rates during Saudi summer ambient storage conditions. |
| Eastern Province Distribution Buildout | Dammam and Khobar whitespace offers first-mover platform anchoring before competitor saturation. |
| Direct-to-Consumer Platform Pivot | BOBA CHiC-style channel control bypasses Carrefour and Lulu Hypermarket promotional slotting fees. |
Research Methodology
Multi-period observation of kit import volumes, platform sales rankings, and halal certification timelines anchored the trend analysis, supplemented by interviews with SFDA regulatory affairs consultants, Noon category managers, Thai tapioca processor export directors, and Jeddah café procurement leads. Secondary validation drew from Saudi Customs import records, GSO technical regulation updates, and e-commerce platform merchant disclosures. Bottom-up assembler revenue estimates triangulated against top-down household penetration models.
Input-output matrices mapped pearl kit, complete kit, and topping kit segments across online, supermarket, specialty store, and direct sales channels. CAGRs derived from logistic curve adoption modeling calibrated to Riyadh and Jeddah household panel data. Forecast inputs included SFDA additive approval pipelines, Noon fulfillment capacity expansion schedules, and Thai tapioca harvest yield projections.
Freight rate spikes, SFDA regulatory reinterpretations, and platform algorithm changes are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Canned Beverages Market
Beverages
South America Bottled Water Market
Beverages
Apple Juice Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Hot Cocoa Mix Market
Beverages
Packaged Milkshake Market
Beverages
Fruit Beverages Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Probiotic Beverage Market
Beverages
China Soy Beverages Market
Beverages
Powdered Beverages Market
Beverages
Hydrogen Water Bottle Market
Beverages
Hot Chocolate Market
Beverages
Water Flavor Market
Beverages
Dairy Based Beverages Market
Beverages
Africa Dairy Based Beverages Market