
 Mixers Market | 2026-2036
Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Mixers Market Foresight
Stainless steel is hardening its position as the dominant bowl and blade material across commercial-grade equipment, displacing lower-grade aluminum in high-shear applications. Alfa Laval AB leverages its heat transfer expertise to anchor premium positioning in hygienic processing environments. GEA Group AG sustains engineering intensity through dedicated test centers for customer-specific mixing protocols. SPX FLOW, Inc. competes on aftermarket service density across North American dairy processing corridors.
Mixers are electromechanical or pneumatic devices designed to blend, emulsify, homogenize, or disperse materials through controlled rotational energy, typically operating at speeds from 50 to 3,600 RPM with torque ratings calibrated to viscosity profiles. Their primary industrial purpose spans food processing, chemical compounding, pharmaceutical formulation, and construction material preparation. Commercial mixers command the deepest margin pools due to sanitation certification requirements and custom engineering cycles, while handheld mixers occupy high-volume, price-sensitive channels serving home bakers. Stainless steel construction dominates professional segments where 3A Sanitary Standards and EHEDG guidelines dictate surface finish specifications.
The EU F-Gas Regulation and REACH compliance frameworks elevate material traceability and energy efficiency requirements for equipment sold across Europe. The US FDA enforces 21 CFR Part 110 guidelines that shape mixer design for food contact surfaces and clean-in-place protocols. China's GB standards and SAMR certification procedures govern safety and electromagnetic compatibility for imported equipment. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon tracking will recalibrate supplier qualification criteria and equipment lifecycle assessments.
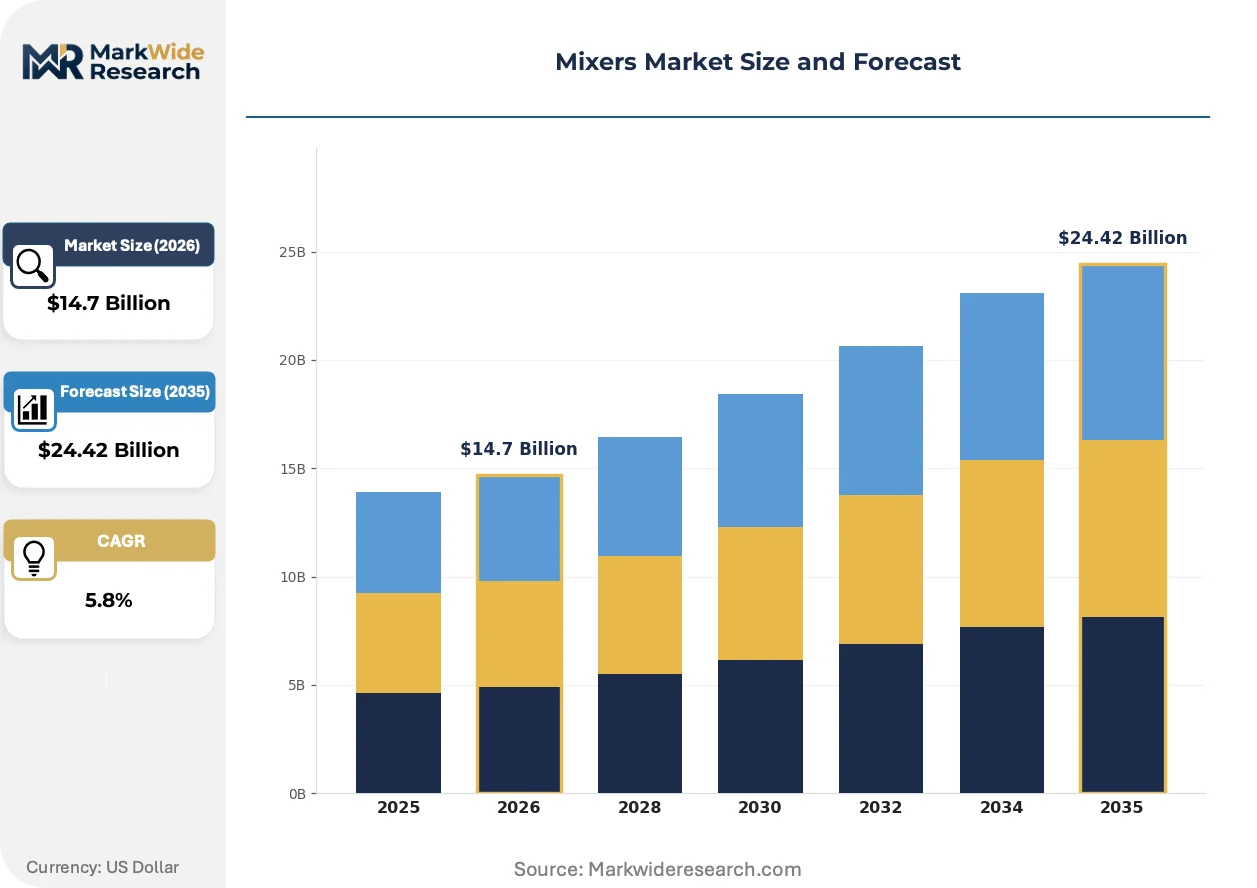
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles across European food processing facilities, forcing capital allocation toward low-global-warming-potential refrigerant architectures in mixing and cooling systems.
Growth Catalysts
- EU F-Gas phase-down mandates:Food manufacturers in Germany are retrofitting automated mixing lines to comply with fluorinated refrigerant restrictions, creating equipment refresh demand.
- Coastal China manufacturing expansion:Commercial bakery and dairy processing capacity is scaling fastest in Jiangsu, Zhejiang, and Guangdong provinces, pulling industrial mixer procurement.
- Stainless steel surface finish standards:3A Sanitary Standards and EHEDG guidelines are hardening specifications for high-shear applications, displacing aluminum in premium segments.
Market Restraints
- Nickel alloy input volatility:Austenitic stainless steel grades depend on nickel pricing, exposing bowl and blade fabricators to commodity swings.
- Precision gearbox supply concentration:High-torque planetary drives for viscous mixing concentrate among German and Japanese precision engineering suppliers.
- Clean-in-place protocol complexity:FDA 21 CFR Part 110 guidelines extend validation timelines for food-contact equipment, stretching commercialization cycles.
Strategic Opportunities
- India dairy cooperative modernization:State-level milk federation processing plants remain underpenetrated by automated batch mixing systems.
- EU Green Deal embodied carbon tracking:Equipment lifecycle assessment protocols will recalibrate supplier qualification criteria toward low-carbon steel sourcing.
- Digital twin convergence with predictive maintenance:Sensor-integrated mixers enabling torque signature analysis are opening service revenue streams.
Industry Challenges
- Hygienic welding certification scarcity:ASME BPE-qualified orbital welders for pharmaceutical-grade equipment remain concentrated in Western European and North American labor pools.
- Legacy control architecture integration:Retrofitting variable frequency drives into existing pneumatic mixing lines creates commissioning friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixers Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand Mixers, Handheld Mixers, Commercial Mixers, Blender Mixers End User: Home Bakers, Professional Chefs, Food Manufacturers, Beverage Corporations Power Rating: 500W, 1000W, 1500W, 2000W Material: Stainless Steel, Plastic, Aluminum, Glass |
| Companies Covered | SPX FLOW, Inc., GEA Group AG, Alfa Laval AB, EKATO Holding GmbH, Tetra Laval International S.A., Sulzer Ltd., Buhler Group, Charles Ross & Son Company, Hosokawa Micron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixers Market Shifts & Advancements
Active magnetic bearing technology is eliminating mechanical seals in high-speed dispersing applications, compressing maintenance intervals and enabling sterile processing architectures previously unreachable with conventional shaft seals.
Magnetic coupling systems are integrating into high-shear pharmaceutical mixers, transferring torque through containment shells without product contact. Biologics manufacturers are adopting these configurations fastest for monoclonal antibody production. The technology is integrating aseptic processing capabilities that were previously the domain of disposable single-use systems.
REACH compliance frameworks are elevating material traceability requirements for equipment sold across Europe. Substance of very high concern screening now extends to lubricants and elastomers in food-contact zones. Pharmaceutical formulation equipment faces the steepest documentation burdens, with suppliers building dedicated chemical dossier teams.
After-sales service contracts are unbundling from capital equipment sales, with processors preferring outcome-based uptime guarantees over traditional time-and-materials maintenance. North American dairy cooperatives are leading this shift, negotiating availability clauses tied to seasonal production peaks. The model compresses vendor switching costs while raising working capital intensity for equipment providers.
Mixers Market Segmentation
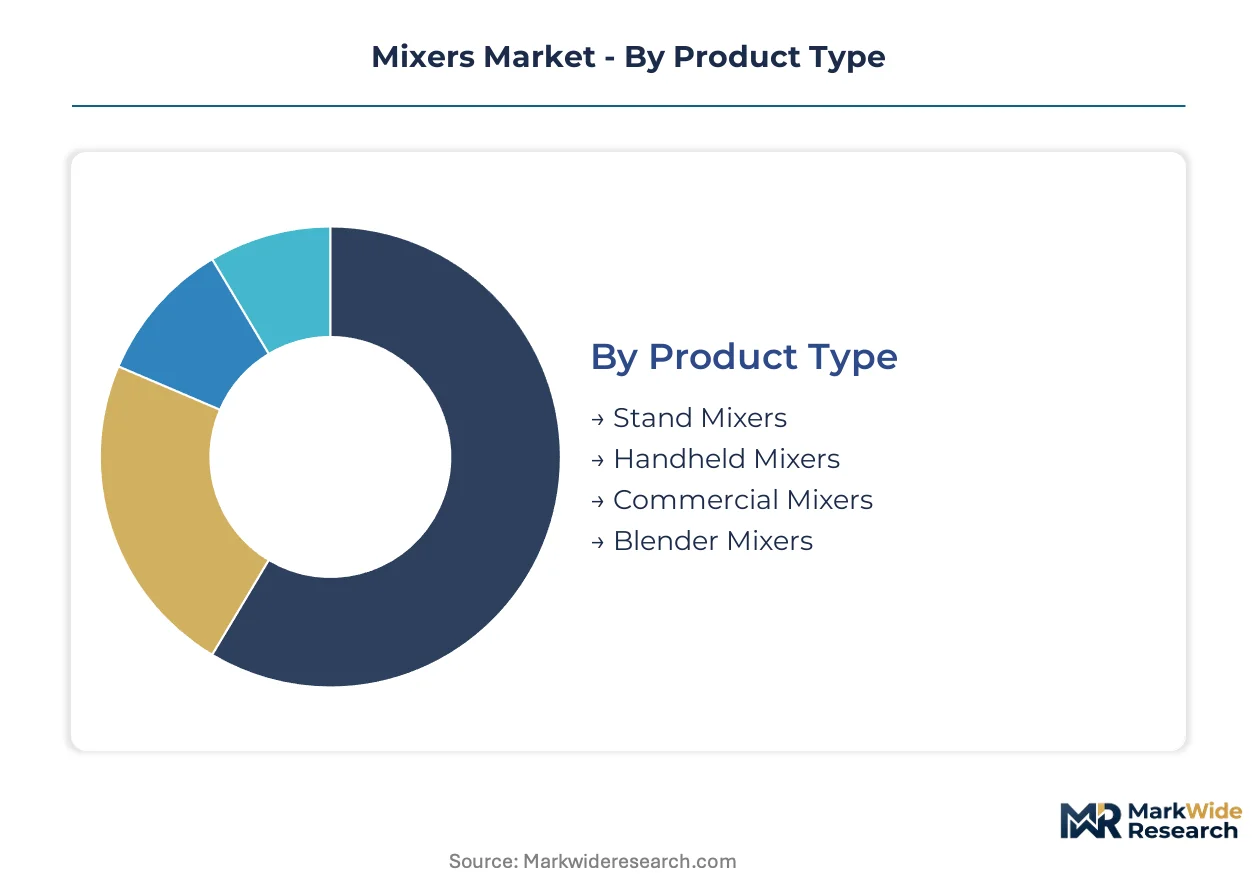
Mixer procurement patterns diverge sharply across end-use contexts, with sanitation certification requirements and torque specifications creating distinct margin pools. Equipment buyers segment first by operational scale, then by material compliance needs that gate access to regulated processing environments.
Product Type:
Commercial buyers prioritize torque calibration and clean-in-place compatibility over upfront capital cost.
- Stand Mixers:Countertop units with planetary mixing action dominate home and light commercial kitchens. Demand concentrates in North American and European retail channels where home baking participation remains elevated post-pandemic.
- Commercial Mixers:Floor-standing batch equipment with 20-140 quart bowl capacities serves high-volume food manufacturing. German and Chinese dairy processors are retrofitting automated lines to meet EU F-Gas refrigerant phase-down mandates, pulling capital equipment refresh cycles.
- Handheld Mixers:Portable units with detachable beaters occupy price-sensitive consumer segments. Asian manufacturing clusters in Guangdong province supply the majority of global volume through OEM arrangements.
- Blender Mixers:High-RPM units with vortex-generating blade geometries serve beverage preparation. Coffee shop chains and smoothie bars in US coastal metros drive specification requirements for noise dampening and programmable cycles.
Volume sits with handheld units through mass retail; growth tilts toward commercial mixers as food manufacturers automate batch consistency.
End User:
Regulatory exposure and production scale determine equipment specification intensity across buyer categories.
- Food Manufacturers:Industrial processors require 3A Sanitary Standards certification and EHEDG-compliant surface finishes for high-shear applications. Jiangsu and Zhejiang province bakery expansions are pulling automated mixing line procurement with integrated cooling systems.
- Beverage Corporations:Scale bottlers and dairy cooperatives demand torque-rated planetary drives for viscous product handling. North American dairy corridors are shifting toward outcome-based service contracts tied to seasonal uptime guarantees.
- Professional Chefs:Restaurant and hotel kitchens balance durability with footprint constraints. European procurement favors energy-efficient models as EU Green Deal embodied carbon tracking penetrates supplier qualification criteria.
- Home Bakers:Price-sensitive consumers prioritize aesthetic design and attachment versatility. E-commerce channels in China and the US dominate distribution with direct-to-consumer brands compressing traditional retail margins.
Margin concentration favors food manufacturers; specification intensity is climbing fastest among beverage corporations integrating predictive maintenance architectures.
Power Rating:
Torque requirements scale non-linearly with viscosity, creating discrete equipment tiers.
- 2000W:Heavy-duty planetary drives handle industrial dough and viscous chemical compounding. German precision gearbox suppliers concentrate supply for this tier, exposing buyers to extended lead times.
- 1500W:Mid-industrial units bridge commercial bakery and light manufacturing applications. China's coastal provinces are scaling capacity fastest in this range for dairy processing plant modernization.
- 1000W:Prosumer and small commercial kitchens favor this wattage for versatility. Attachment ecosystems and brand loyalty drive repeat purchase patterns in North American and European markets.
- 500W:Entry-level handheld and compact stand mixers serve occasional home use. Plastic housing dominance in this tier faces pressure from REACH substance-of-very-high-concern screening on polymer formulations.
Procurement volume clusters at 500W and 1000W; specification migration is pushing fastest toward 1500W as semi-automated food processing expands.
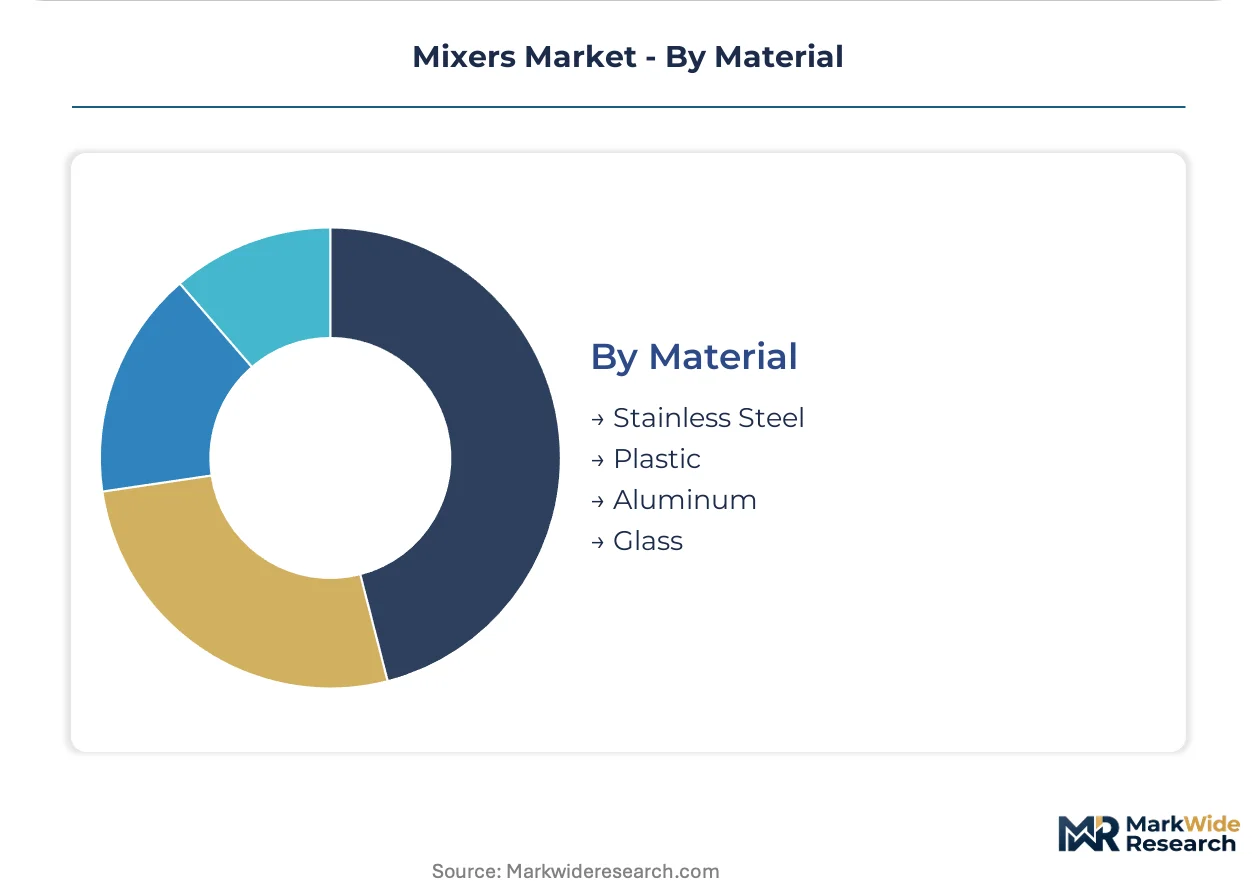
Material:
Surface finish standards and chemical compatibility govern material selection in regulated environments.
- Stainless Steel:Austenitic grades with 2B or mirror finishes dominate pharmaceutical and dairy processing where FDA 21 CFR Part 110 and 3A Sanitary Standards apply. Nickel alloy input volatility exposes fabricators to commodity pricing swings.
- Aluminum:Lower-grade castings persist in consumer and light commercial segments. High-shear applications are displacing aluminum in favor of stainless steel as EHEDG guidelines harden.
- Plastic:Glass-reinforced polymers reduce weight in handheld and entry-level stand mixers. REACH compliance frameworks are elevating documentation burdens for lubricants and elastomers in food-contact zones.
- Glass:Borosilicate blender jars and mixing bowls serve premium consumer segments. Fragility limits industrial adoption despite chemical inertness and visual batch monitoring advantages.
Stainless steel commands the premium tier; plastic retains volume leadership in consumer channels while facing regulatory headwinds on material traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces concentrate automated mixing line deployment, while Germany's industrial clusters drive equipment retrofit cycles under refrigerant phase-down mandates.
China
Jiangsu and Zhejiang province dairy processors are scaling commercial bakery capacity fastest, pulling procurement for integrated cooling-mixing systems. SAMR certification procedures govern electromagnetic compatibility for imported equipment. Guangdong manufacturing clusters supply handheld mixer OEM volume through mass retail channels.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia are retrofitting automated lines to comply with EU F-Gas Regulation fluorinated refrigerant restrictions. REACH compliance frameworks elevate material traceability requirements for bowl and blade fabricators. Stuttgart precision engineering suppliers concentrate high-torque planetary gearbox production for viscous mixing applications.
United States
North American dairy cooperatives are shifting toward outcome-based service contracts tied to seasonal production peaks. FDA enforces 21 CFR Part 110 guidelines shaping mixer design for food contact surfaces and clean-in-place protocols. Wisconsin and California processing corridors anchor aftermarket service density competition.
India
State-level milk federation processing plants remain underpenetrated by automated batch mixing systems, creating modernization demand. FSSAI standards govern food contact equipment safety certification requirements. Gujarat and Maharashtra dairy cooperatives are piloting torque-rated planetary drives for viscous product handling.
Japan
Biologics manufacturers are adopting magnetic coupling configurations fastest for monoclonal antibody production. METI industrial policy supports pharmaceutical-grade equipment export competitiveness. Osaka and Nagoya precision engineering clusters supply containment shell fabrication for sterile processing architectures.
Mixers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier players commanding margin pools through sanitation certification depth while volume producers compete on OEM channel access. The structure tilts toward consolidation in high-shear pharmaceutical and dairy processing equipment, where 3A Sanitary Standards and EHEDG compliance create qualification barriers. Three archetypes dominate: heat-transfer engineering specialists, precision gearbox integrators, and aftermarket service platform operators. Competitive moves concentrate on strategic partnerships for clean-in-place protocol validation and geographic expansion into underpenetrated dairy cooperative markets.
Within the heat-transfer engineering tier, Alfa Laval AB and GEA Group AG exemplify premium positioning through hygienic processing expertise. SPX FLOW, Inc. anchors North American aftermarket service density. EKATO Holding GmbH represents German precision engineering concentration in high-torque drive systems.
| Leading Market Players |
|---|
| SPX FLOW, Inc. |
| GEA Group AG |
| Alfa Laval AB |
| EKATO Holding GmbH |
| Tetra Laval International S.A. |
| Sulzer Ltd. |
| Buhler Group |
| Charles Ross & Son Company |
| Hosokawa Micron Corporation |
| Others |
Supply & Pricing Matrix
Nickel alloy futures volatility cascades through bowl and blade fabrication costs, compressing margins for austenitic stainless steel equipment while amplifying price premiums for EHEDG-certified surface finishes in pharmaceutical-grade mixers.
Pricing Analysis
Lead-time premiums dominate transactional pricing, with German precision gearbox suppliers commanding surcharges for sub-12-week delivery against spot-inventory discounts from Asian OEM channels. Three-tier pricing structure across premium, standard, and economy levels separates 3A Sanitary Standards-certified pharmaceutical equipment from commercial bakery units and handheld consumer models. Price differentiation hinges on certification grade and after-sales service bundling, with North American dairy cooperatives showing lowest sensitivity due to outcome-based uptime contracts. Cost compression in the consumer tier intensifies as Guangdong manufacturing clusters compete on volume scale.
Supply Chain Analysis
Freight cost inflation from Asia-Europe routes is rerouting component sourcing toward regional stainless steel mills in Germany and Italy. Supply concentrates in China for handheld mixer OEM production, Germany for precision planetary drives, and Japan for magnetic bearing assemblies. Raw material dependencies center on nickel alloy feedstock, borosilicate glass for blender jars, and specialized lubricants for food-contact zones. Single-source vulnerability concentrates in high-torque gearbox supply from Stuttgart engineering clusters. Distribution runs through equipment distributors serving dairy processing corridors, direct OEM relationships for large food manufacturers, and mass retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precision gearbox production represents the decisive upstream lever, with incumbents and challengers racing to secure captive supply of high-torque planetary drives as lead times extend.
For Market Incumbents: Deploy aftermarket service platform density to lock in North American dairy cooperative accounts before outcome-based contract models mature. Secure ASME BPE-qualified orbital welding capacity through acquisition or exclusive partnership to defend against pharmaceutical-grade equipment challengers. Capacity addition in Jiangsu province manufacturing clusters counters Chinese competitor expansion. For New Entrants and Emerging Players: State-level milk federation processing plants in Gujarat and Maharashtra offer the most penetrable buyer archetype for automated batch mixing systems. FSSAI certification pathways remain less congested than FDA or EU approval routes. Direct technical partnership with regional dairy cooperatives bypasses established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors precision engineering specialists with magnetic coupling or active magnetic bearing capabilities. Long-term viability hinges on biologics manufacturing expansion and sterile processing architecture adoption. Watch for torque signature analysis patent filings as inflection indicator for predictive maintenance platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gearbox Production | Captive supply of high-torque planetary drives secures lead-time advantage against German and Japanese competitors. |
| Magnetic Coupling Technology Licensing | Biologics manufacturers at Osaka and Nagoya clusters drive fastest adoption for monoclonal antibody production lines. |
| Outcome-Based Service Contract Expansion | North American dairy cooperatives negotiating availability clauses tied to seasonal production peaks reshape vendor economics. |
| ASME BPE Welding Certification Investment | Pharmaceutical-grade equipment qualification barriers concentrate among Western European and North American labor pools. |
| India Dairy Cooperative Direct Partnership | Gujarat and Maharashtra state-level milk federations remain underpenetrated by automated batch mixing systems. |
Research Methodology
Document review covered customs and trade flow databases, SEC filings from listed equipment manufacturers, and SAMR certification registries, complemented by interviews with plant engineers at dairy processing facilities, procurement leads at food manufacturers, aftermarket service heads, and precision gearbox suppliers. Technical specification sheets from 3A Sanitary Standards and EHEDG guideline documentation provided secondary validation. Bottom-up equipment shipment tracking and top-down end-use industry demand modeling enabled cross-verification.
Historical capacity expansion patterns from German and Chinese manufacturing clusters were cross-referenced against panel input from maintenance directors and OEM procurement teams. Segmentation dimensions modeled include product type, power rating tier, material grade, end-user vertical, and regional regulatory cluster. CAGRs were derived through trend extrapolation adjusted for EU F-Gas Regulation compliance-driven replacement cycles and coastal China manufacturing capacity scaling. Forecast inputs incorporated nickel alloy price trajectory assumptions and REACH substance-of-very-high-concern screening timelines.
Revisions become necessary when nickel alloy futures volatility exceeds historical bands, EU Green Deal embodied carbon tracking accelerates supplier qualification recalibration, or magnetic bearing technology cost curves shift sterilization economics. Forecasts reflect documented assumptions about regulatory enforcement intensity and dairy cooperative modernization rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Apple Juice Market
Beverages
South America Mate Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Carbonated Soft Drinks Market
Beverages
Baby Drinking Water Market
Beverages
China Soy Beverages Market
Beverages
Caffeinated Beverage Market
Beverages
Europe Coconut Water Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
GCC Fruit Juice Market
Beverages
Coconut Water Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Health Drinks Market