
 Root Beer Market | 2026-2036
Root Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Root Beer Market Intelligence
Consumer demand for beverages with natural ingredients and transparent labeling is expanding the market for premium and craft root beer. Keurig Dr Pepper Inc. sustains its market position through extensive distribution networks for its traditional offerings. Sprecher Brewing Company specializes in the premium craft segment, using fire-brewed techniques. Meanwhile, Reed's Inc. differentiates its products by focusing on all-natural and non-GMO ingredient sourcing.
Root beer is a carbonated soft drink traditionally flavored with the root bark of the sassafras tree or artificial sassafras flavoring. Modern commercial formulations often use a proprietary blend of botanicals like vanilla, licorice root, and wintergreen to achieve its characteristic flavor profile. The craft product type, often packaged in glass bottles, represents the fastest-growing segment due to consumer interest in artisanal products. In contrast, the traditional segment, dominated by canned packaging, remains a mature but high-volume category.
Producers must navigate stringent food and beverage regulations, including the FDA's nutritional labeling requirements in the United States and the EFSA's food additive standards in Europe. Global health guidelines from the WHO concerning sugar consumption also influence product formulation and marketing strategies. Success for market participants will depend on balancing authentic flavor profiles with evolving consumer health preferences and regulatory pressures.
Market Dynamics
The root beer market's evolution is governed by the tension between consumer demand for authentic, traditional flavors and mounting regulatory pressure for healthier beverage options. This dynamic forces producers to innovate with natural sweeteners and botanical ingredients while preserving the distinct flavor profile consumers expect.
Growth Catalysts
- Foodservice Expansion:Restaurants and bars are broadening their non-alcoholic beverage menus, incorporating premium and craft root beers to cater to sober-curious consumers and provide sophisticated alternatives.
- Artisanal Product Demand:Heightened consumer interest in craft-made, small-batch products, particularly in urban centers across the United States and Canada, fuels growth in the premium glass bottle segment.
- Regulatory Push for Reformulation:Stricter FDA guidelines on added sugar labeling compel manufacturers to explore natural sweeteners like stevia and monk fruit, opening new product categories for health-conscious buyers.
Market Restraints
- Ingredient Cost Volatility:The price of key natural flavorings, such as vanilla and specific botanical extracts, is subject to significant fluctuation, impacting production costs and margin stability for craft producers.
- Regulatory Bans on Traditional Ingredients:The historical FDA ban on safrole, the primary component of sassafras oil, necessitates the use of artificial flavorings or complex botanical blends, creating a barrier to true historical authenticity.
- Intense Substitute Competition:The market faces strong competition from a growing array of other craft non-alcoholic beverages, including kombucha, artisanal ginger ales, and functional wellness drinks, vying for the same consumer base.
Strategic Opportunities
- European Market Entry:There is an opportunity for expansion into European countries like the United Kingdom and Germany, where the craft soda movement is less mature but consumer interest in premium, non-alcoholic options is rising.
- Functional Beverage Development:Formulating root beers with functional ingredients, such as probiotics for gut health or adaptogens for stress relief, can attract new consumer segments focused on wellness.
- Direct-to-Consumer Channels:Establishing direct-to-consumer (DTC) e-commerce platforms and subscription models enables brands to build direct relationships with consumers and market limited-edition or exclusive batches effectively.
Industry Challenges
- Flavor Consistency:Maintaining a consistent flavor profile year-round is a significant operational challenge when using natural botanical ingredients, which can vary based on harvest season and origin.
- Cross-Border Regulatory Compliance:Navigating the differences between food additive and labeling standards, such as those from the FDA in the U.S. and the EFSA in Europe, complicates international distribution.
- Scaling Artisanal Production:Producers face difficulties in scaling traditional production methods like fire-brewing to meet higher demand without losing the authentic, craft quality that defines their brand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Root Beer Market |
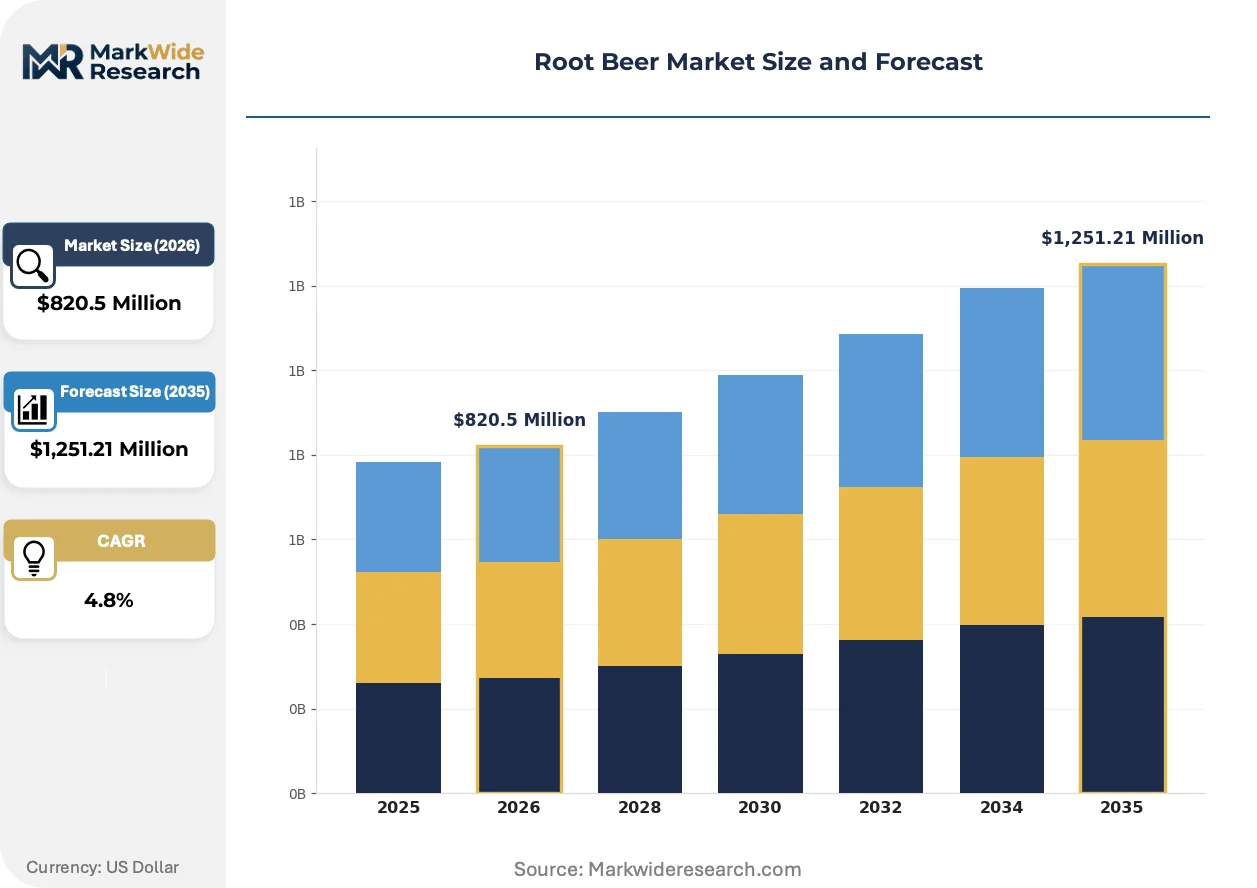
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,251.21 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft, Traditional, Diet, Alcoholic Packaging Type: Cans, Bottles, Kegs, Cartons Distribution Channel: Supermarkets, Liquor Stores, Online Retailers, Foodservice Customer Type: Millennials, Families, Health-Conscious Consumers, Restaurants |
| Companies Covered | PepsiCo Inc., The Boston Beer Co. Inc., Keurig Dr Pepper Inc., Boylan Bottling Co., Reed's Inc., Anheuser-Busch InBev SA/NV, Sprecher Brewing Company, A&W Restaurants, Inc., The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Root Beer Market Strategic Shifts & Innovations
The modernization of this traditional beverage is accelerating through ingredient science and digital consumer engagement. Product development now centers on balancing authentic flavor profiles with clean-label attributes, driven by both regulatory mandates and evolving consumer health consciousness across key markets.
AI-powered flavor development software is a key innovation in product formulation. Product development teams at both large-scale and craft producers are adopting this technology to analyze and predict the outcomes of complex botanical combinations. This technology is automating the process of creating novel flavor profiles that meet specific nutritional targets, such as reduced sugar content, without sacrificing taste.
The European Food Safety Authority’s (EFSA) rigorous standards for food additives and flavorings influence global product strategies. This regulatory environment requires producers targeting the EU market to provide extensive safety and sourcing documentation for each ingredient. Consequently, North American exporters are often compelled to develop specific, EU-compliant formulations, which can impact supply chain complexity and cost.
A shift in purchasing behavior from single-unit impulse buys to planned, multi-pack procurement is altering distribution dynamics. This trend challenges the dominance of convenience stores and single-serve coolers in supermarkets, favoring bulk formats and e-commerce channels. This pattern is most pronounced among consumers in major North American metropolitan areas who use online platforms to explore and purchase craft beverage variety packs.
Root Beer Market Segmentation
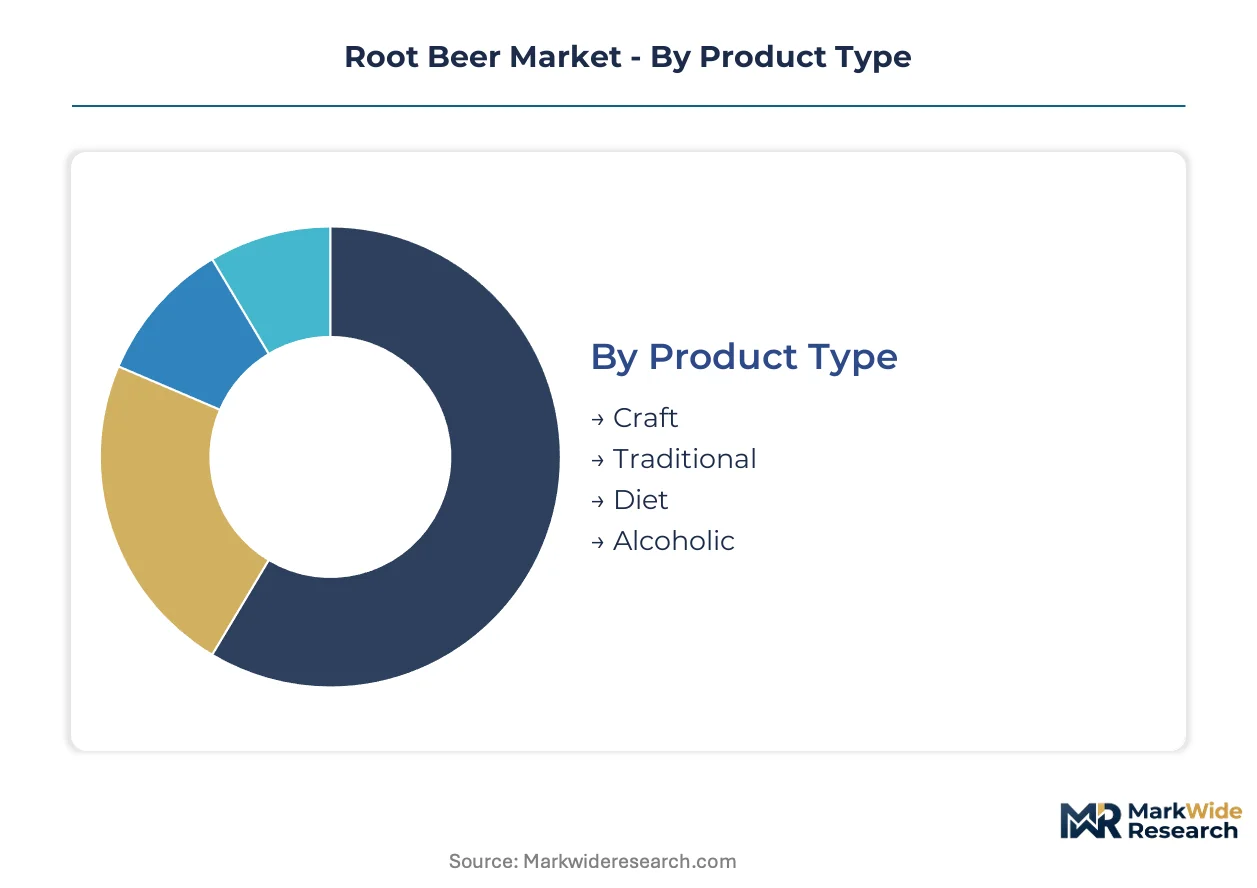
Market segmentation provides a granular view of the root beer landscape, revealing how diverse product types, packaging formats, distribution channels, and customer profiles influence demand and innovation. Understanding these distinct segments is critical for producers to tailor product development and market entry strategies effectively.
Product Type:
The root beer market observes distinct consumer upgrade cycles driven by product type preferences and evolving health trends.
- Craft:These products feature artisanal brewing methods and often incorporate premium, natural botanical ingredients, appealing to consumers seeking unique flavor profiles. Demand for craft root beer is concentrating in major metropolitan areas within the United States and Canada.
- Traditional:This segment includes classic, widely recognized root beer brands, often characterized by a consistent, familiar flavor profile and broad availability. This high-volume category sees sustained demand across established consumer bases.
- Diet:Formulations in this segment use artificial or natural non-caloric sweeteners to reduce sugar content, targeting health-conscious consumers.
- Alcoholic:This niche category offers root beer with an alcoholic base, typically marketed to adult consumers as a nostalgic or novelty beverage.
Volume placements concentrate in Traditional root beer; the Craft segment represents the fastest-growing trajectory.
Packaging Type:
Packaging type segmentation reflects diverse cost structures, consumer value perceptions, and consumption occasions across the market.
- Bottles:Primarily glass, bottles are favored for premium and craft root beer offerings, preserving flavor integrity and enhancing the consumer's perception of quality. This format is strong in specialized retail and foodservice.
- Cans:Aluminum cans provide convenience, portability, and protection from light, making them a dominant format for traditional and high-volume root beer products. Canned products are prevalent in supermarkets and convenience stores.
- Kegs:These larger containers serve the foodservice industry, particularly restaurants and bars, allowing for on-tap root beer service.
- Cartons:Less common, cartons offer a lightweight and often more sustainable packaging option for some specialized or smaller-volume root beer products.
Consumer convenience and bulk purchasing drive demand for Cans, while premium experiences elevate Bottles in specific channels.
Distribution Channel:
Distribution channels are shaped by specific application needs and target customer demographics, influencing product accessibility and market reach.
- Foodservice:This channel includes restaurants, cafes, and bars that offer root beer as part of their non-alcoholic beverage menu, often featuring craft or premium options. Growth in this channel is significant as establishments broaden beverage choices.
- Supermarkets:Large retail chains represent a primary channel for traditional and diet root beer, offering broad selection and competitive pricing for household consumption. This channel accounts for substantial sales volume.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales and provide access to a wider variety of craft and specialty root beers, particularly for urban consumers.
- Liquor Stores:These retail outlets primarily stock alcoholic root beer variants, catering to adult beverage consumers.
The Foodservice channel demonstrates significant expansion, complementing the established reach of Supermarkets.
Customer Type:
Customer type segmentation highlights evolving preferences across different demographic groups and their influence on product innovation.
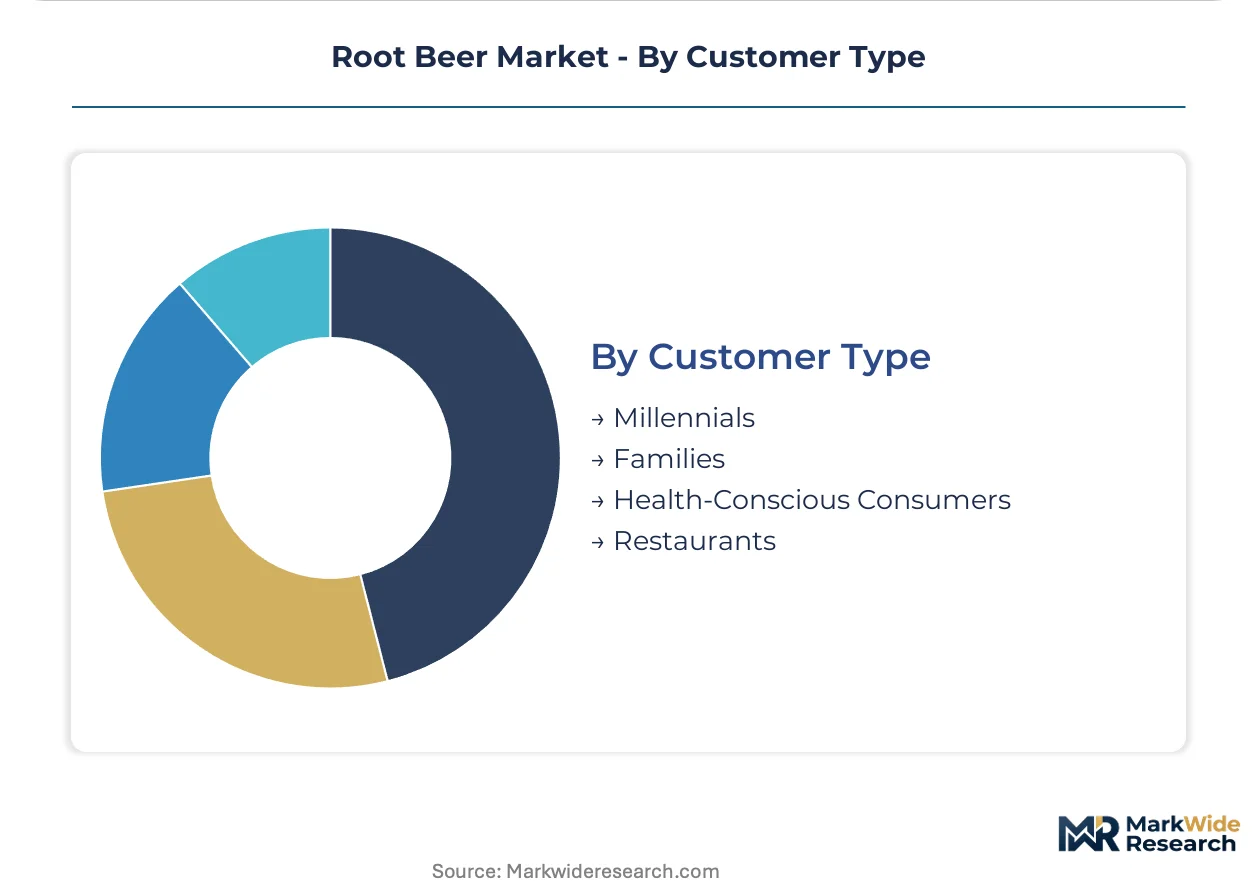
- Health-Conscious Consumers:This segment seeks root beer with natural ingredients, reduced sugar, or functional benefits, often driving demand for diet and natural-sweetener formulations. These consumers influence product reformulation.
- Millennials:This demographic shows a strong interest in artisanal products and unique flavor experiences, propelling the growth of the craft root beer segment. Their purchasing behavior often favors online platforms.
- Families:Families represent a consistent consumer base for traditional root beer, often prioritizing value and wide availability in retail settings.
- Restaurants:As customers, restaurants procure root beer for on-premise consumption, particularly premium or craft options to enhance their beverage offerings.
Health-Conscious Consumers are driving product innovation, alongside consistent demand from Families.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major metropolitan areas across North America drive significant demand for premium root beer, reflecting evolving consumer preferences. This market expansion extends into European countries where craft soda movements are emerging. Specific regulatory frameworks influence product formulation and market access in each region.
United States
Consumer interest in artisanal products and natural ingredients fuels robust demand for craft root beer across the United States. Stringent FDA nutritional labeling requirements compel manufacturers to reformulate products with reduced sugar content. Urban centers like New York City and Los Angeles exhibit concentrated purchasing patterns for premium root beer.
Canada
Demand for artisanal root beer and sophisticated non-alcoholic beverages is strong within Canadian urban centers. Health Canada's food and drug regulations guide ingredient sourcing and labeling, emphasizing consumer safety and transparency. Major urban centers such as Toronto and Vancouver are hubs for craft beverage consumption.
United Kingdom
Rising consumer interest in premium non-alcoholic options supports the nascent craft soda movement across the United Kingdom. The UK Food Standards Agency (FSA) oversees food additive standards, influencing formulation for market entry. London's diverse culinary scene increasingly features unique root beer selections.
Germany
An emerging craft soda market in Germany attracts consumers seeking premium non-alcoholic beverage alternatives. European Food Safety Authority (EFSA) standards for food additives directly impact product development for the German market. Berlin's innovative beverage industry sees increasing experimentation with botanical-infused non-alcoholic drinks.
Australia
Australia's established craft beverage culture drives demand for premium root beer with natural ingredients and distinct flavor profiles. Food Standards Australia New Zealand (FSANZ) regulations dictate ingredient and labeling requirements for all food and beverage products. Melbourne and Sydney's vibrant cafe culture increasingly stocks artisanal root beer brands.
Root Beer Market Key Industry Players
The competitive structure tilts toward a tiered system, balancing established beverage conglomerates with a growing number of specialized craft producers. This market features global beverage companies focused on broad distribution alongside artisanal brewers targeting niche segments. Key strategic archetypes include large-scale manufacturers, premium craft beverage makers, and regional bottlers. Companies pursue geographic expansion into new markets and portfolio diversification to capture evolving consumer preferences. Strategic partnerships also allow smaller brands to expand their reach.
Within the specialized craft segment, Sprecher Brewing Company exemplifies producers focusing on artisanal brewing methods and unique flavor profiles. Reed's Inc. represents companies differentiating through all-natural and non-GMO ingredient sourcing within the premium category. Meanwhile, Keurig Dr Pepper Inc. occupies a position among large-scale beverage manufacturers, leveraging extensive distribution networks for its traditional root beer offerings. These players collectively illustrate the diverse approaches to product development and market penetration.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Boston Beer Co. Inc. |
| Keurig Dr Pepper Inc. |
| Boylan Bottling Co. |
| Reed's Inc. |
| Anheuser-Busch InBev SA/NV |
| Sprecher Brewing Company |
| A&W Restaurants, Inc. |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
FDA nutritional labeling requirements gate access to both qualified natural sweetener supply and premium-tier pricing. These mandates compel producers to reformulate, influencing ingredient costs and consumer perception of value.
Pricing Analysis
Authentic flavor profiles anchor pricing for craft root beer, where consumers pay a premium for artisanal quality. Transactional per-unit pricing dominates across all segments, with price differentiation stemming from brand premium and ingredient sourcing. Pricing pressure stems from intense substitute competition from other craft non-alcoholic beverages. Families represent the most price-sensitive buyers, while Millennials prioritize unique craft experiences.
Supply Chain Analysis
Strict FDA and EFSA food additive standards gate the qualification of botanical ingredients for root beer production. Supply concentrates in regions for key flavorings like Madagascar for vanilla and North America for wintergreen extracts. Raw material dependencies on specific botanicals and natural sweeteners create ingredient cost volatility. Distribution runs primarily through supermarkets for traditional products, while craft variants leverage foodservice and online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The root beer market presents a cost-of-compliance narrative, where stringent FDA nutritional labeling requirements create a barrier-to-entry moat for compliant producers. Navigating these regulations requires significant investment in reformulation and transparent sourcing.
For Market Incumbents: Cement market share by leveraging extensive distribution networks for traditional offerings. Invest in R&D for natural sweeteners to address FDA regulations and mitigate margin pressure from ingredient cost volatility. Strategic acquisitions of successful craft brands can counter intense substitute competition from emerging non-alcoholic options. Deepen channel control within the expanding foodservice segment to secure shelf space.
For New Entrants and Emerging Players: AI-powered flavor development software offers a technology-first wedge, enabling rapid iteration of novel botanical combinations. Target the underpenetrated European market, particularly urban centers in the United Kingdom and Germany, with premium, clean-label formulations. Establish direct-to-consumer e-commerce platforms to build brand loyalty and market functional root beers with probiotics or adaptogens. Focus on artisanal product demand among health-conscious Millennials.
For Investors and Strategic Acquirers: Widespread adoption of natural sweeteners in traditional root beer lines is the leading indicator that the market is shifting towards health-conscious formulations. The market offers sustainable long-term growth driven by premiumization and evolving consumer health preferences. Target mid-sized craft producers with established brand equity and robust compliance with FDA and EFSA standards. Monitor online retail penetration of variety packs as a signal of consumer purchasing behavior shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Reformulation | Addresses FDA sugar regulations, attracting health-conscious consumers with natural ingredients. |
| Direct-to-Consumer Channel Development | Builds brand loyalty and provides direct access to urban consumers for craft offerings. |
| European Market Entry | Captures rising consumer interest in premium non-alcoholic options in nascent craft soda markets. |
| Functional Ingredient Integration | Attracts new consumer segments focused on wellness through probiotics or adaptogens. |
| Craft Brand Acquisition | Consolidates market position and expands portfolio within the fastest-growing root beer segment. |
Research Approach
Multi-period observation of consumer purchasing patterns and regulatory shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with beverage R&D directors, craft brewery owners, and foodservice procurement managers. Secondary validation drew from FDA filings, EFSA reports, and trade association publications. This approach integrated bottom-up and top-down data triangulation.
Segment-weighting across product type, packaging format, and distribution channel formed the basis for volume projections. The analytical framework modeled customer type preferences throughout the forecast period. Compound annual growth rates were derived from historical data and projected market drivers, including consumer health trends and regulatory changes. Raw material prices for botanicals served as a key forecast input.
Several conditions sit outside the modeled scope, including unforeseen global economic downturns or rapid shifts in consumer preferences. Forecasts reflect assumptions regarding stable geopolitical environments and current technological trajectories. A model refresh is warranted upon material change in significant regulatory overhauls.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Japan Kombucha Market
Beverages
GCC Bottled Water Market
Beverages
Europe Bottled Water Processing Market
Beverages
Whole Grain Drinks Market
Beverages
Global Squash Drinks Market
Beverages
South East Asia Bottled Water Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Caffeine Mint Market
Beverages
Fermented Foods and Beverages Market
Beverages
Sarsaparilla Market
Beverages
United States Recovery Drinks Market
Beverages
Water Bottle Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Carbonated Soft Drinks Market