
 Freezer & Beverage and Wine Cooler Market | 2026-2036
Freezer & Beverage and Wine Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer & Beverage and Wine Cooler Market Analytics
Polyurethane foam is shifting toward cyclopentane-blown formulations across freezer and beverage cooler manufacturing, cutting thermal conductivity while eliminating hydrofluorocarbon blowing agents. Electrolux AB leverages its European manufacturing base to sustain premium positioning in energy-efficient wine cooler segments. Haier Group Corporation anchors volume production through its captive compressor supply chain and dominates distribution across Asia-Pacific retail channels.
Freezers and beverage and wine coolers are thermally insulated cabinet appliances designed to maintain temperatures between minus eighteen degrees Celsius and eighteen degrees Celsius, utilizing vapor-compression, thermoelectric, or absorption refrigeration cycles to preserve food, beverages, or wine. Their primary commercial purpose spans foodservice inventory holding, residential bulk storage, and controlled wine aging environments where humidity and vibration parameters matter. Upright freezers occupy the largest installed base in North American households due to footprint efficiency, while wine coolers represent the fastest-growing product type as residential entertaining culture expands. Compressor technology leads value generation through superior coefficient-of-performance ratings, though thermoelectric units capture margin pools in compact countertop beverage applications.
The US Department of Energy and the EPA regulate minimum energy conservation standards and refrigerant phase-down schedules under SNAP rules, compelling manufacturers to redesign systems around R600a or R290 hydrocarbon alternatives. The EU Ecodesign Directive and F-Gas Regulation impose parallel constraints on European imports, tightening market access for products exceeding specified global warming potential thresholds. Stakeholders must monitor refrigerant transition timelines and efficiency tier migrations to avoid stranded inventory positions.
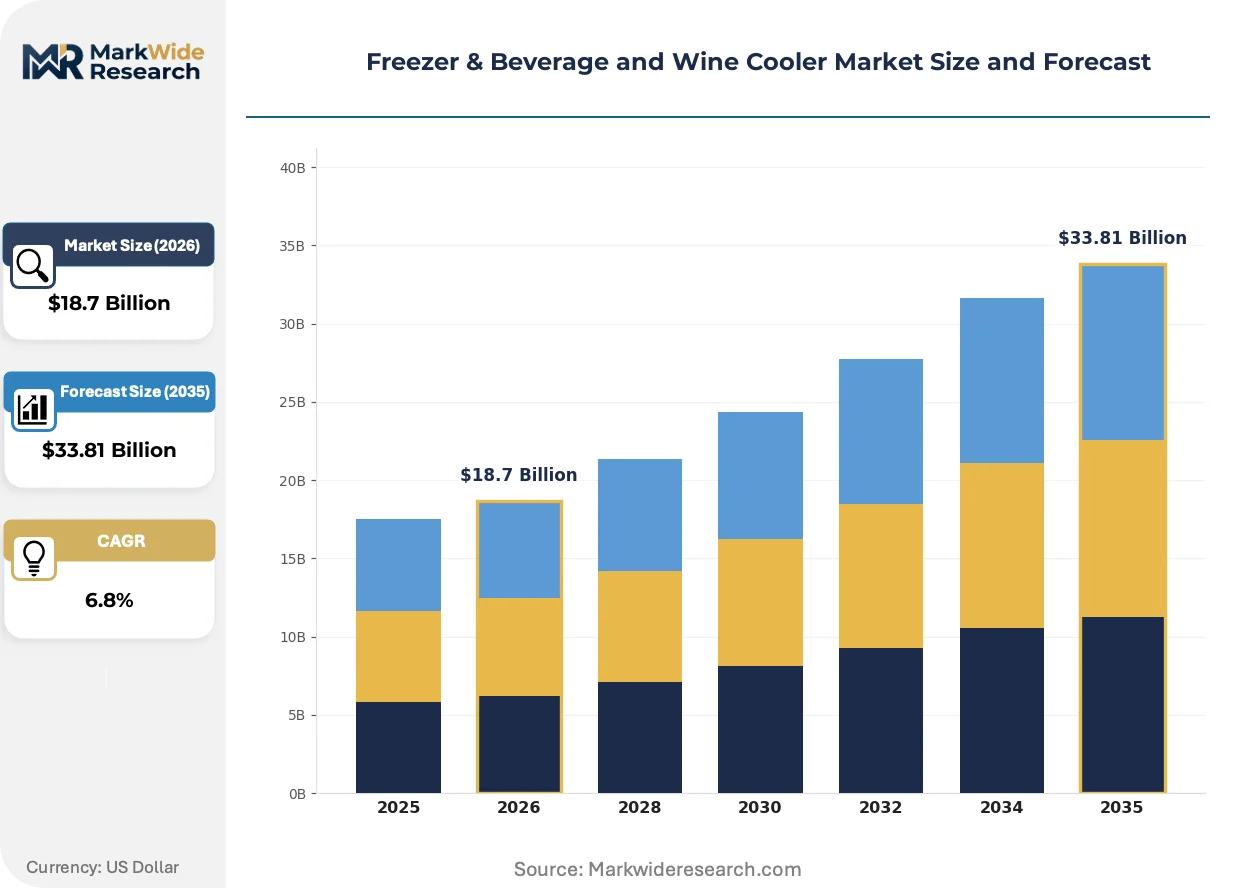
Market Dynamics
The US Department of Energy's updated appliance efficiency standards are compressing design cycles across compressor systems and insulation packages, forcing manufacturers to abandon legacy refrigerant architectures before amortization schedules complete.
Growth Catalysts
- R600a Hydrocarbon Transition:The EPA's SNAP program mandates phase-down of high-global-warming-potential refrigerants, pulling demand toward isobutane-based systems that deliver superior thermodynamic performance.
- Prepared-Meal Delivery Infrastructure:Restaurants and catering services are expanding cold-storage footprints to support ghost kitchen and direct-to-consumer meal models, creating pull-through for upright freezer capacity.
- Urban Kitchen Expansion:China's residential construction boom is embedding dedicated beverage and wine cooling zones into new apartment designs, normalizing second-appliance ownership.
Market Restraints
- Cyclopentane Input Volatility:Polyurethane foam formulations depend on petrochemical feedstock pricing that tracks crude oil benchmarks, compressing margin predictability for insulation suppliers.
- Compressor Supply Concentration:Captive production of rotary and reciprocating compressors clusters among three Asian manufacturing groups, creating single-source vulnerability for mid-tier OEMs.
- Thermoelectric Performance Ceiling:Peltier-based cooling systems face hard physics limits on coefficient-of-performance ratios, restricting their addressable market to sub-50-liter countertop applications.
Strategic Opportunities
- India Residential Penetration:Organized retail expansion and rising disposable income are creating first-time buyer pools for dedicated wine storage among urban professional households.
- Dual-Zone Humidity Control:Convergence of precision sensor networks with variable-speed compressor modulation is opening premium positioning for long-term wine aging applications.
- EU F-Gas Regulation Tailwind:The 2024 tightening of import thresholds for fluorinated gases creates competitive shelter for early hydrocarbon adopters against lagging import competition.
Industry Challenges
- Hydrocarbon Safety Certification:R600a and R290 systems require specialized technician training and facility modifications, extending compliance timelines for retooling manufacturing lines.
- Legacy Control System Integration:Smart-connected freezer architectures must interface with decade-old residential HVAC automation protocols, fragmenting development resources across compatibility layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer & Beverage and Wine Cooler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright Freezers, Chest Freezers, Beverage Coolers, Wine Coolers Technology: Compressor, Thermoelectric, Absorption, Hybrid End User: Restaurants, Hotels, Catering Services, Household Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Haier Group Corporation, Electrolux AB, Whirlpool Corporation, Sub-Zero Group, Liebherr Group, LG Electronics, Bosch Home Appliances, GE Appliances, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer & Beverage and Wine Cooler Market Evolving Landscape
Refrigeration architecture is bifurcating between hydrocarbon-based vapor compression for volume applications and solid-state thermoelectric modules for niche portability, with material science advances compressing the performance gap between the two pathways.
Vacuum insulation panel technology is converging with conventional polyurethane foam in hybrid wall assemblies, delivering thermal resistance values three times higher than legacy foam alone. Premium wine cooler manufacturers are adopting these panels first, exploiting the cost absorption capacity of high-margin segments. The structural consequence is converging with cabinet slimming trends that expand interior volume without footprint expansion, reshaping retail merchandising and kitchen integration possibilities.
The EU F-Gas Regulation's 2024 review is accelerating refrigerant transition timelines, banning imports exceeding specified global warming potential thresholds and compelling Asian exporters to retest entire product portfolios. European customs authorities are deploying portable gas analyzers at border checkpoints, creating enforcement friction that favors regional manufacturers with established hydrocarbon supply chains. Wine cooler imports face the steepest compliance burden due to their higher charge sizes and premium positioning sensitivity.
Residential buyers are unbundling after-sales service from initial purchase decisions, treating extended warranty and maintenance contracts as separately negotiable components rather than bundled add-ons. This pattern is most visible in China's tier-one cities, where e-commerce platforms facilitate transparent comparison of third-party service providers. Distributors are responding by compressing front-margin capture and recovering profitability through recurring service attachment, fundamentally restructuring channel economics away from one-time hardware margins.
Freezer & Beverage and Wine Cooler Market Segmentation
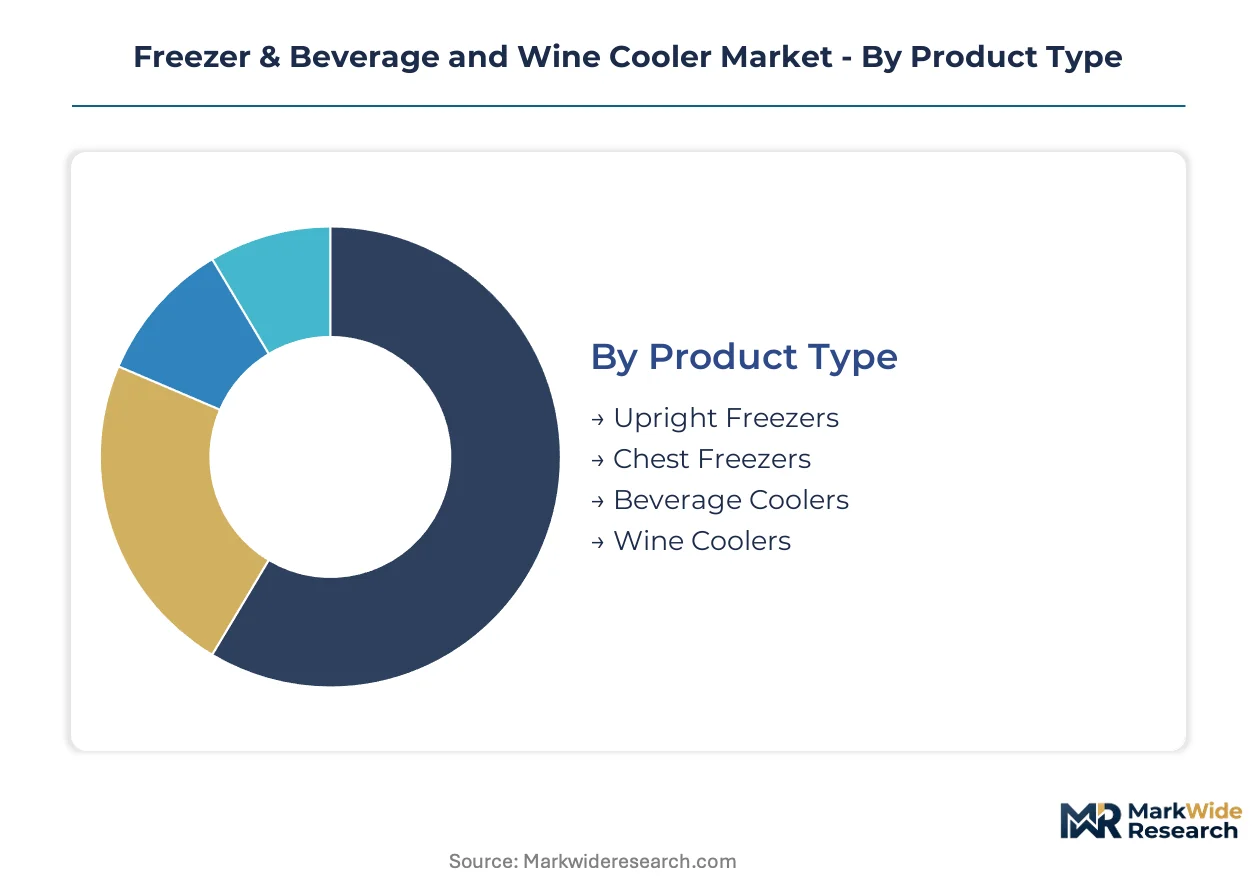
Segmentation in this market reveals divergent performance requirements across thermal mass, precision control, and usage intensity. Buyers select architectures based on inventory turnover frequency, ambient temperature stability, and regulatory compliance obligations in their operating geography.
Product Type:
Buyers differentiate primarily by footprint constraints and access patterns rather than cooling performance alone.
- Upright Freezers:Vertical cabinet configuration with front-facing door access optimizes floor space utilization in constrained kitchen environments. North American households favor these units for bulk frozen food storage, driven by prepared-meal delivery infrastructure expansion and ghost kitchen proliferation.
- Wine Coolers:Precision temperature and humidity control systems designed for long-term aging with vibration isolation. Urban households in China are embedding dedicated wine cooling zones into new residential construction, normalizing second-appliance ownership alongside primary refrigeration.
- Chest Freezers:Top-opening horizontal design with superior thermal retention due to minimal cold air loss during access. Cold-storage-dependent foodservice operations leverage these for high-volume frozen inventory holding.
- Beverage Coolers:Single-zone or dual-zone temperature configurations optimized for canned and bottled drinks. Convenience-focused retail channels and residential entertaining spaces drive procurement decisions.
Volume sits with Upright Freezers; growth tilts toward Wine Coolers.
Technology:
Cost tier and application scale dictate technology selection more than efficiency metrics alone.
- Compressor:Vapor-compression cycles using rotary or reciprocating mechanisms deliver superior coefficient-of-performance ratios across sub-zero to moderate cooling ranges. R600a hydrocarbon refrigerant transition under EPA SNAP rules is pulling demand toward isobutane-based systems that outperform legacy HFC architectures.
- Thermoelectric:Solid-state Peltier modules eliminate moving parts and refrigerant handling requirements entirely. Countertop beverage applications and portable medical storage in the US exploit this technology's silent operation and vibration-free performance despite hard physics limits on cooling capacity.
- Absorption:Heat-driven refrigeration cycles using ammonia-water or lithium bromide solutions operate without electrical compressors. Off-grid installations and LP gas-dependent recreational vehicles represent the primary addressable market.
- Hybrid:Combined thermoelectric and compressor architectures switch between modes based on load conditions and ambient temperature. Premium wine cooler manufacturers are piloting these systems for dual-zone humidity control applications.
Compressor systems dominate installed value; thermoelectric configurations are expanding most quickly in sub-50-liter portable segments.
End User:
Operating intensity and regulatory exposure separate commercial from residential procurement patterns.
- Restaurants:High-frequency door cycling and health code compliance requirements demand robust construction and precise temperature logging. Ghost kitchen operators are expanding cold-storage footprints to support direct-to-consumer meal models.
- Household:Residential buyers prioritize energy efficiency ratings and aesthetic integration with kitchen cabinetry. China's tier-one cities are driving first-time dedicated wine storage purchases as disposable income rises.
- Catering Services:Mobile and event-based operations require portable or trailer-mounted refrigeration with generator compatibility. Prepared-meal delivery infrastructure investments are pulling through upright freezer capacity.
- Hotels:In-room minibars and back-of-house inventory systems operate on divergent specifications. Property-wide procurement consolidates around standardized control interfaces and maintenance contract structures.
Commercial volume concentrates in Restaurants; household penetration is climbing the fastest in emerging urban markets.
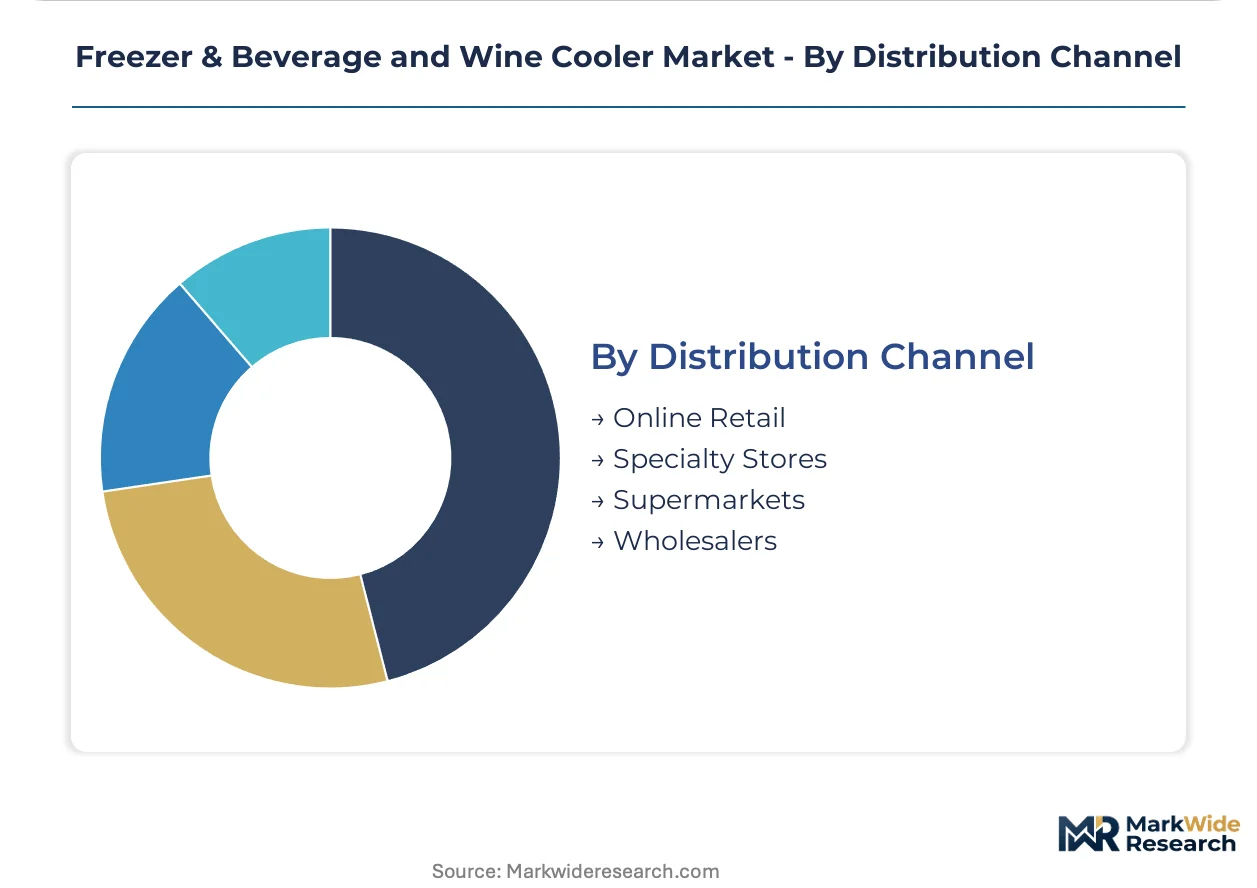
Distribution Channel:
Service attachment and technical support availability shape channel selection beyond price transparency.
- Specialty Stores:Curated product assortments with installation and extended warranty bundling. Premium wine cooler sales depend on staff expertise in humidity control and aging protocol consultation.
- Online Retail:E-commerce platforms facilitate transparent comparison of third-party service providers in China's tier-one cities. Buyers unbundle after-sales support from initial purchase decisions, treating maintenance contracts as separately negotiable components.
- Supermarkets:Mass-market freezer and beverage cooler availability with immediate pickup and basic delivery options. Standardized SKUs limit configuration flexibility but compress lead times.
- Wholesalers:Volume pricing and fleet-standardized procurement for multi-unit commercial operators. Foodservice equipment distributors recover profitability through recurring service attachment rather than front-margin capture.
Specialty Stores anchor premium transaction value; online channels are gaining share fastest in residential replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Haier Industrial Park in Qingdao anchors appliance manufacturing concentration through integrated compressor production and bonded logistics zones that slash component import duties for re-export markets.
United States
Prepared-meal delivery infrastructure expansion drives upright freezer procurement across ghost kitchen clusters in Atlanta, Chicago, and Dallas. The EPA's SNAP program mandates R600a hydrocarbon transition timelines that compress manufacturer compliance windows. Southeast manufacturing corridors in Georgia and Tennessee concentrate assembly capacity serving domestic replacement cycles.
Germany
EU F-Gas Regulation enforcement tightens import thresholds for fluorinated refrigerants, sheltering early hydrocarbon adopters against Asian competition. The Ecodesign Directive imposes parallel efficiency constraints on commercial refrigeration portfolios. Bavarian industrial zones around Munich anchor premium wine cooler engineering for export markets.
China
Urban kitchen expansion in tier-one cities normalizes dedicated beverage and wine cooling zones alongside primary refrigeration. SAMR enforces GB standards alignment with dual carbon goals that accelerate foam formulation transitions. The Yangtze River Delta manufacturing belt concentrates polyurethane panel and compressor component supply.
India
Organized retail penetration and rising disposable income create first-time buyer pools for dedicated wine storage among Mumbai and Delhi professional households. BIS certification requirements for commercial refrigeration equipment extend product registration timelines. Gujarat industrial corridors attract component sourcing investments from multinational OEMs.
Japan
Residential entertaining culture sustains premium wine cooler demand despite demographic headwinds. METI efficiency standards drive inverter compressor adoption across compact appliance segments. Osaka-Kobe manufacturing clusters specialize in precision temperature control modules for luxury export markets.
Freezer & Beverage and Wine Cooler Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line appliance conglomerates dominating volume while niche players capture margin pools in precision-controlled wine storage. The structure concentrates around three to five integrated groups controlling compressor supply and distribution infrastructure. Strategic archetypes span captive-component manufacturers, premium-positioned European specialists, and diversified Asian electronics conglomerates. Competitive moves center on hydrocarbon refrigerant certification acceleration and vacuum insulation panel technology licensing.
Among diversified appliance conglomerates, Haier Group Corporation anchors volume positioning through integrated manufacturing depth, while Electrolux AB occupies the premium-tier vector serving efficiency-sensitive European markets. Sub-Zero Group exemplifies the ultra-premium specialization archetype, representing the convergence of custom cabinetry integration and precision climate engineering for residential wine aging applications.
| Leading Market Players |
|---|
| Haier Group Corporation |
| Electrolux AB |
| Whirlpool Corporation |
| Sub-Zero Group |
| Liebherr Group |
| LG Electronics |
| Bosch Home Appliances |
| GE Appliances |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap insulation suppliers across Italy and South Korea anchor polyurethane foam production for premium wine cooler assemblies, their generational ownership structures enforcing pricing discipline through long-term cyclopentane supply contracts that resist spot-market volatility. This ownership pattern concentrates margin capture upstream while compressing assembler flexibility on input costs.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract pricing dominate procurement negotiations for R600a compressor systems, with foodservice operators absorbing these charges to maintain ghost kitchen uptime during hydrocarbon transition bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates Sub-Zero-grade custom cabinetry integration from Haier-volume retail SKUs, with price differentiation hinging on vacuum insulation panel inclusion and humidity control precision. Pricing pressure stems from crude-linked cyclopentane feedstock volatility that erodes insulation supplier margins without corresponding assembler relief. Commercial restaurants exhibit lowest price sensitivity due to health-code compliance imperatives, while Indian residential first-time buyers drive hardest bargain on entry-level thermoelectric units.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification and China's GB standards alignment are reshaping sourcing patterns, compelling multinational OEMs to localize polyurethane panel production within Gujarat and Yangtze River Delta industrial corridors. Manufacturing gravity centers on China, South Korea, and Germany, with compressor components drawing from captive rotary production at Haier's Qingdao Industrial Park and reciprocating assemblies from Bavarian precision engineering clusters. Raw material dependencies rest on petrochemical-derived cyclopentane blowing agents, copper refrigerant tubing, and rare-earth thermoelectric substrates. Single-source vulnerability concentrates in rotary compressor supply among three Asian manufacturing groups. Distribution runs through bonded logistics zones serving re-export markets, with specialty stores and e-commerce platforms splitting residential channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
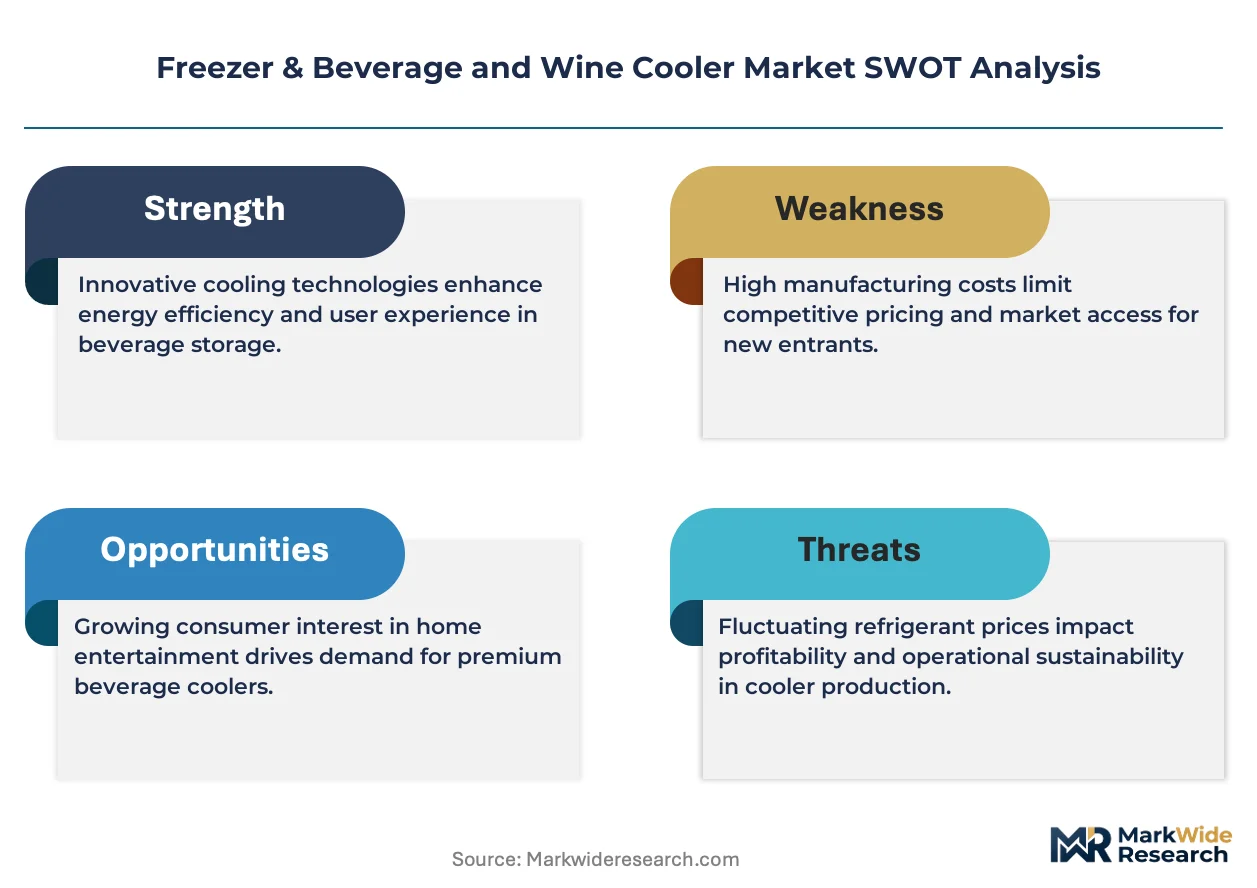
This market reads as a hydrocarbon-certification-driven consolidation play, with EPA SNAP compliance timelines and EU F-Gas enforcement windows forcing weaker players into strategic exits before amortization recovery.
For Market Incumbents: Deepen captive compressor supply integration through backward control over rotary component production in Qingdao or Bavarian engineering corridors, insulating margin positions against single-source vulnerability. Accelerate R600a safety certification investments ahead of 2024 EU border enforcement deployment, converting compliance lead time into pricing power against lagging Asian import competition. Lock in decade-long cyclopentane supply contracts with family-owned Italian foam specialists before crude volatility transmits to spot markets.
For New Entrants and Emerging Players: The mid-tier price-point gap between Electrolux-premium and Haier-economy positioning opens white-space for dual-zone humidity control systems targeting China's tier-one urban professional households. Target India's organized retail expansion corridors around Mumbai and Delhi with BIS-certified compact wine storage units, exploiting first-time buyer pools before multinational incumbents localize production. Pursue direct-to-consumer e-commerce attachment with third-party service provider transparency, unbundling after-sales support from hardware margins as Chinese buyers now demand.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier OEMs with partial hydrocarbon certification progress but stranded HFC inventory positions in Southeast Asian manufacturing corridors. Five-to-ten-year viability hinges on vacuum insulation panel technology licensing portfolios and SAMR-aligned GB standards compliance in Chinese production footprints. Watch for inflection signals in EU customs gas analyzer deployment intensity at Rotterdam and Hamburg checkpoints, which will clarify competitive shelter duration for early hydrocarbon adopters.
| Strategic Initiative | Industry Significance |
|---|---|
| R600a Hydrocarbon Certification Acceleration | EPA SNAP alignment and EU F-Gas compliance create competitive moats against stranded HFC inventory holders. |
| Vacuum Insulation Panel Technology Licensing | Hybrid wall assemblies deliver thermal resistance triple legacy foam values, enabling premium wine cooler slimming. |
| Captive Compressor Supply Integration | Backward control over rotary production in Qingdao or Bavaria insulates margins against Asian manufacturing group concentration. |
| Dual-Zone Humidity Control System Development | Precision sensor convergence with variable-speed modulation opens long-term wine aging applications in Chinese urban households. |
| Third-Party Service Provider E-Commerce Attachment | Unbundling after-sales support from hardware margins restructures channel economics as China's tier-one buyers demand transparency. |
Research Methodology
Independent corroboration across compressor OEM technical documentation, EPA SNAP regulatory filings, and SAMR GB standards enforcement records underwrites the qualitative findings on hydrocarbon transition timelines. Primary interviews with appliance manufacturing executives, polyurethane foam procurement leads, commercial foodservice equipment distributors, and residential channel sales heads combined with secondary validation from customs trade data, SEC 10-K appliance segment disclosures, and EU Ecodesign Directive implementation reports. Bottom-up and top-down triangulation cross-checked installed base estimates against production volume disclosures from Qingdao and Bavarian manufacturing clusters.
Comparable-period anchoring to historical efficiency standard implementation windows calibrated the projection horizon's regulatory compliance assumptions. Segmentation dimensions modeled span product type, refrigeration technology, end-user operating intensity, and distribution channel service attachment patterns across the analysis window. CAGRs derived from slope-consistent extrapolation of efficiency tier migration rates and refrigerant transition penetration curves. Industry-specific forecast inputs include cyclopentane feedstock price elasticity coefficients and ghost kitchen cold-storage capacity expansion trajectories in Atlanta, Chicago, and Dallas clusters.
Inputs from compressor OEM technical documentation and SAMR enforcement records were available through the study window; gaps in real-time EU customs gas analyzer deployment data introduce uncertainty bands around competitive shelter duration estimates. Forecasts reflect assumptions on hydrocarbon certification acceleration rates and cyclopentane supply contract renewal patterns. Refrigerant transition timeline delays, crude oil price dislocations, or BIS certification backlog extensions could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Germany Probiotic Drinks Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
India Sports Drinks Market
Beverages
Coconut Water Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Nitro-Infused Beverages Market
Beverages
Packaged Coconut Water Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
BBQ Charcoal Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
United States Recovery Drinks Market
Beverages
Flavored Powder Drinks Market
Beverages
Rose Floral Water Market
Beverages
Ginger Beer Market
Beverages
Vegetable Juice Market
Beverages
Bottled Air Market