
 Brown Rice Market | 2026-2036
Brown Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Brown Rice Market Analysis
Health-conscious households is redrawing demand patterns across the brown rice landscape, pulling volume away from traditional commodity buyers toward premium-seeking consumers. KRBL Limited leverages its Punjab processing infrastructure to dominate North Indian supply chains. Lundberg Family Farms sustains organic certification density across California's Sacramento Valley. Lotus Foods Inc. specializes in heirloom varietal sourcing from smallholder networks in Southeast Asia.
Brown rice denotes whole-grain Oryza sativa with intact bran layer and germ, retaining approximately 3.5 grams of dietary fiber per cooked cup and requiring hulling without abrasive polishing. Its primary commercial purpose centers on delivering minimally processed carbohydrates to health-oriented food service and retail channels. Organic brown rice occupies the fastest-expanding margin pool as certification premiums widen, while parboiled brown rice anchors institutional procurement for food service operators seeking extended shelf stability. Conventional brown rice still controls volume share through supermarket and bulk container distribution.
FDA food-labeling standards enforce whole-grain content declarations on packaged brown rice sold in the United States, while USDA organic regulations govern pesticide residue thresholds for certified product lines. India's FSSAI mandates fortification compliance and maximum foreign matter limits on milled rice entering domestic commerce. Stakeholders must monitor evolving bran-layer retention standards as regulators tighten nutritional claim verification protocols across multiple jurisdictions.
Market Dynamics
Health-conscious households are redrawing demand patterns across the brown rice landscape, pulling volume away from traditional commodity buyers toward premium-seeking consumers who prioritize bran-layer retention and organic certification. This structural shift concentrates purchasing power among buyers willing to pay certification premiums while marginalizing conventional bulk channels.
Growth Catalysts
- USDA Organic Certification:Rising purity thresholds for imported grain create competitive moats for certified processors. Premium margins widen as health-oriented retailers mandate organic sourcing.
- Food Service Institutional Procurement:Parboiled brown rice anchors extended-shelf-stability contracts with hospital and school cafeteria networks. Operators prioritize reduced spoilage rates over per-unit cost.
- India:Domestic consumption and export processing intensify simultaneously, concentrating demand in Punjab and Haryana milling corridors. FSSAI fortification mandates drive quality investments.
Market Restraints
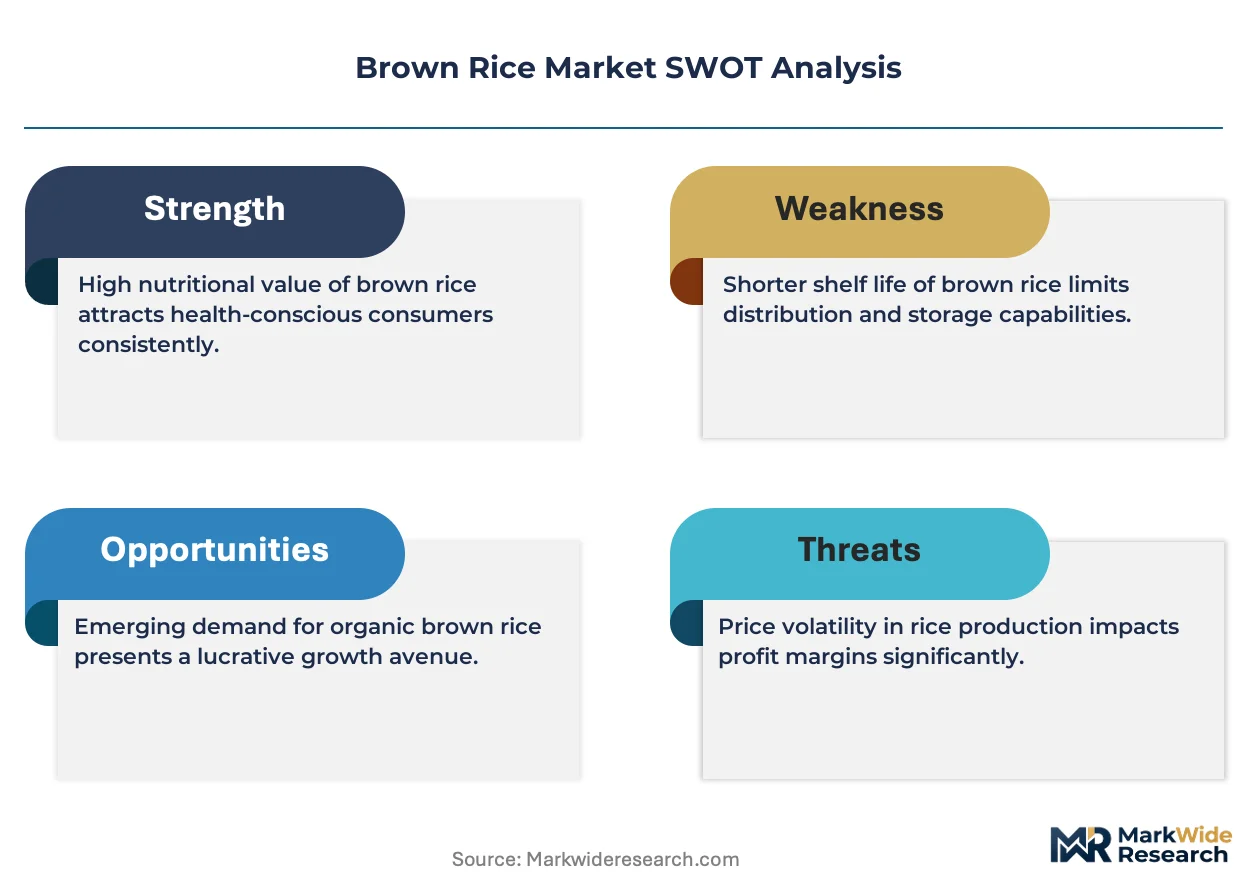
- Input Cost Volatility:Diesel prices and irrigation electricity tariffs swing procurement costs for smallholder paddy suppliers. Margins compress when fuel spikes coincide with harvest gluts.
- Supply Concentration Risk:California's Sacramento Valley dominates US organic brown rice output. Drought cycles in this single geography threaten national supply continuity.
- Substitution Threat:Quinoa and farro capture shelf space in premium retail channels. These ancient grains offer comparable fiber profiles with stronger protein positioning.
Strategic Opportunities
- Underpenetrated Southeast Asia:Smallholder heirloom varietal networks in Cambodia and Laos remain untapped for specialty export channels. Direct-trade premiums bypass commodity exchanges.
- Regulatory Tailwind:India's PLI scheme for food processing incentivizes bran-stabilization technology investments. Eligible mills capture capital subsidies for shelf-life extension equipment.
- E-Commerce Direct Channels:Subscription-based whole-grain delivery models bypass traditional supermarket slotting fees. Health-conscious households accept auto-replenishment for certified organic SKUs.
Industry Challenges
- Certification Timeline Compression:USDA organic transition periods lock land for three years before premium pricing applies. Growers face cash-flow gaps during conventional-to-organic conversion.
- Bran-Stabilization Skill Scarcity:Qualified technicians who can operate enzyme-inactivation equipment without compromising germ integrity command wage premiums. Training pipelines lag equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brown Rice Market |
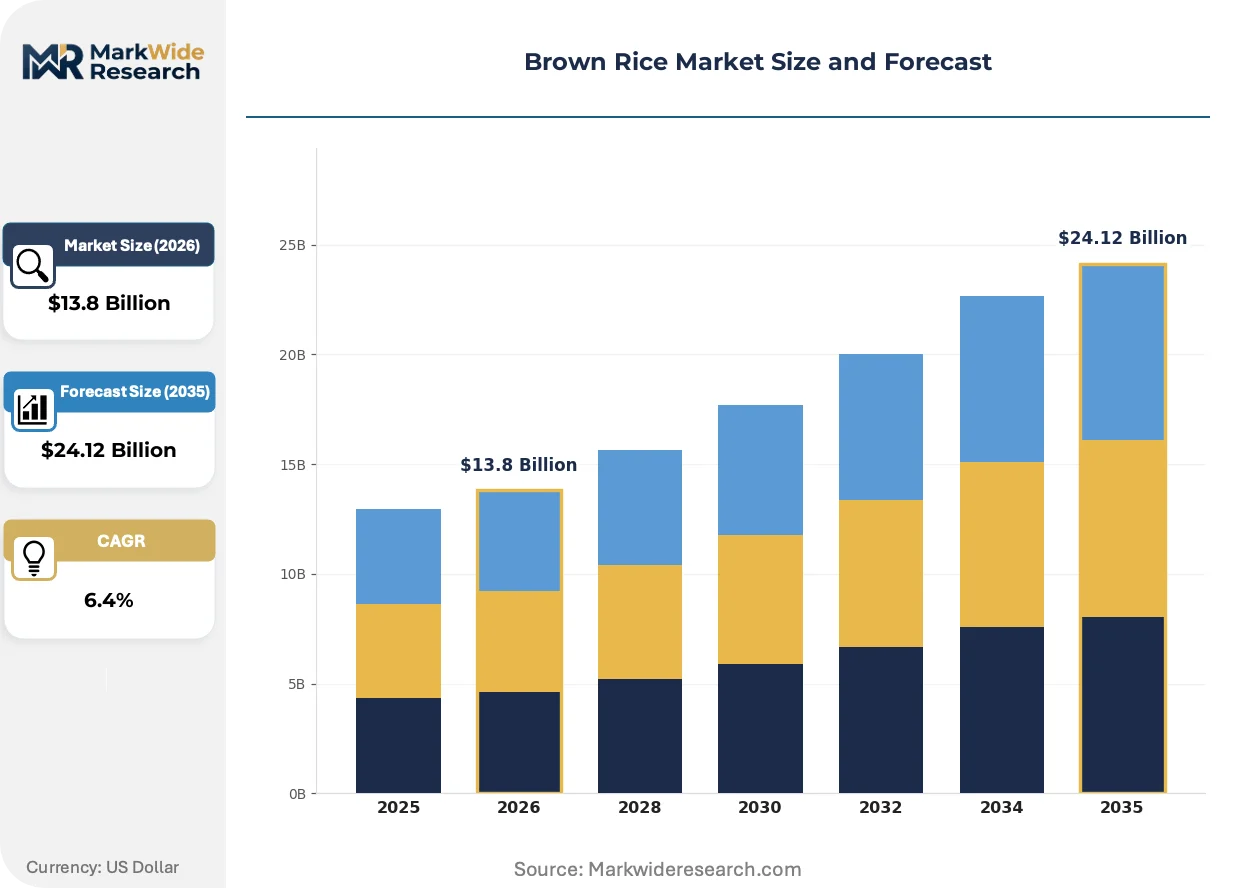
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Brown Rice, Conventional Brown Rice, Parboiled Brown Rice, Instant Brown Rice Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Grocery End Use: Food Service, Household, Industrial, Snack Production Packaging Type: Bags, Boxes, Bulk Containers, Cans |
| Companies Covered | Riviana Foods Inc., KRBL Limited, LT Foods Limited, Cargill Incorporated, Amira Nature Foods Ltd., Kohinoor Foods Limited, Lundberg Family Farms, Daawat, Lotus Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brown Rice Market Emerging Trajectories
Processing technology and certification protocols are converging to redefine competitive advantage in brown rice supply chains. Stakeholders who master bran-layer stabilization while maintaining organic integrity capture disproportionate margin pools.
Enzyme-inactivation steam treatment is supplanting traditional hot-air drying for bran stabilization. Premium organic processors in California's Sacramento Valley adopt this method to extend shelf life without chemical preservatives. The technology compresses spoilage windows from months to weeks, enabling direct-to-retailer contracts that bypass regional distributors.
FDA food-labeling standards now enforce whole-grain content declarations with stricter fiber verification protocols. Packaged brown rice sold in US channels must substantiate bran-layer retention claims through third-party assay. Organic SKUs face heightened scrutiny, with several private-label suppliers reformulating to meet tightened threshold definitions.
Health-conscious households now subscribe to direct-shipment whole-grain programs rather than replenishing through supermarket bulk bins. This channel shift disintermediates traditional food-service distributors who previously captured institutional volume. The behavior is most visible in coastal US metropolitan markets where delivery density supports logistics economics.
Brown Rice Market Segmentation
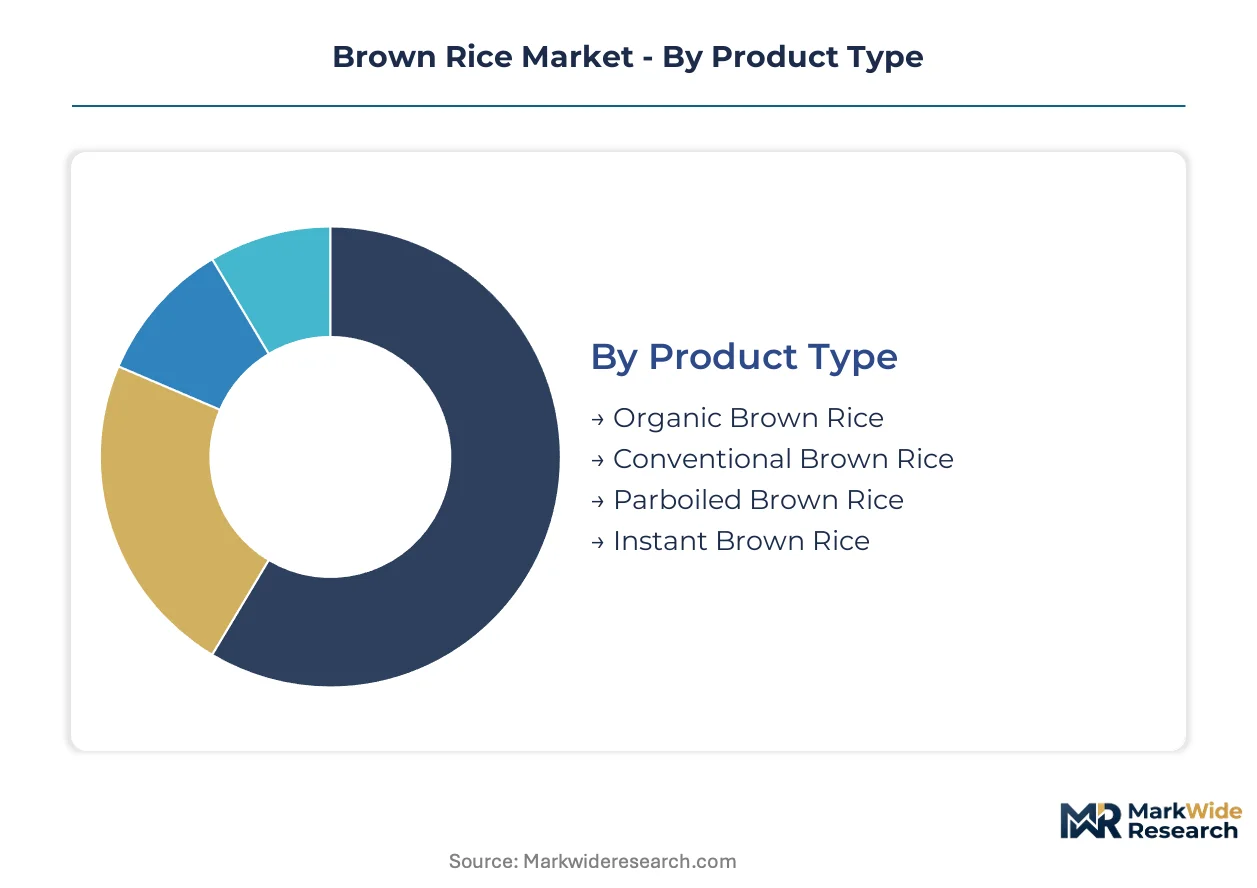
Brown rice segmentation reflects diverging purity standards and channel economics. USDA organic thresholds, FDA labeling enforcement, and FSSAI fortification mandates each reshape how product categories compete for shelf space and procurement contracts.
Product Type:
USDA organic regulations impose three-year land conversion timelines and pesticide residue ceilings that conventional lines bypass entirely.
- Organic Brown Rice:Bran-layer integrity must survive enzyme-inactivation steam treatment without synthetic preservative contact. California's Sacramento Valley and Punjab's milling corridors concentrate certified output as health-oriented retailers mandate organic provenance.
- Conventional Brown Rice:Hull removal without abrasive polishing yields intact germ and fiber content at lower unit cost. Supermarket bulk bins and food-service procurement networks absorb volume through price-sensitive contracts that sacrifice certification premiums.
- Parboiled Brown Rice:Pre-cooking gelatinization extends shelf stability for institutional buyers. Hospital and school cafeteria operators prioritize reduced spoilage rates.
- Instant Brown Rice:Partial hydration and rapid-drying processing targets convenience-oriented household demand. E-commerce subscription channels capture repeat purchases.
Conventional brown rice handles the majority of throughput; organic brown rice is the fastest mover on share.
Distribution Channel:
Channel selection determines margin capture through slotting fee exposure versus direct customer relationships.
- Supermarkets:Dominant volume conduit with established bulk bin infrastructure and private-label placement. Conventional SKUs absorb price competition while organic lines fight for premium shelf positioning.
- Online Retailers:Subscription-based auto-replenishment models bypass traditional distributor markups. Health-conscious households in coastal metropolitan markets drive logistics density.
- Health Food Stores:Curated organic assortment with certification verification protocols. Staff expertise justifies price premiums to wellness-focused consumers.
- Specialty Grocery:Heirloom varietal sourcing from smallholder networks in Cambodia and Laos. Direct-trade premiums bypass commodity exchange pricing.
Supermarkets handle the majority of throughput; online retailers are expanding most quickly.
End Use:
Application requirements split between bran-stabilization durability and preparation convenience.
- Food Service:Parboiled formats anchor extended-shelf-stability contracts with institutional operators. Spoilage reduction outweighs per-unit cost in procurement decisions.
- Household:Retail-packaged organic and instant formats dominate pantry replenishment. Subscription models capture loyalty through certification transparency.
- Industrial:Milled brown rice flour and bran extraction supply bakery and nutritional supplement manufacturers. FSSAI fortification compliance governs ingredient specifications.
- Snack Production:Puffed and extruded applications leverage intact bran for fiber claims. FDA whole-grain content declarations require third-party assay verification.
Household consumption handles the majority of throughput; snack production is climbing the fastest.
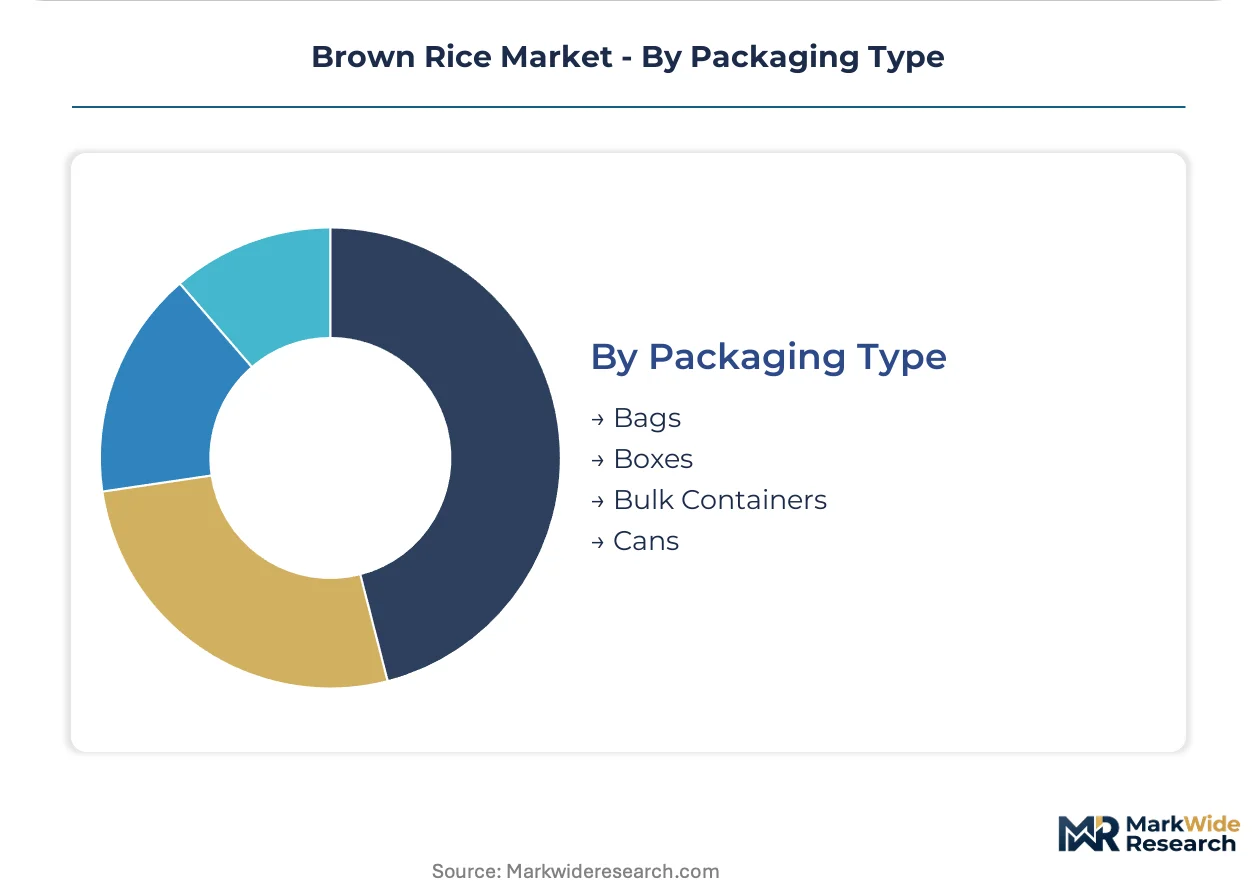
Packaging Type:
Packaging economics align with volume scale and shelf-life requirements across channel tiers.
- Bags:Flexible polymer or paper laminate dominates retail SKUs from 500g to 5kg. Barrier properties preserve bran-layer freshness against oxidation.
- Boxes:Secondary containment for multi-bag gift sets or premium organic positioning. Structural rigidity supports shelf presence in specialty retail.
- Bulk Containers:Food-service and industrial procurement at 25-50kg scale. Reduced per-unit packaging cost offsets spoilage risk from repeated opening.
- Cans:Airtight metal packaging for instant and parboiled formats requiring extended ambient stability. Higher material cost limits penetration.
Bags handle the majority of throughput; bulk containers are gaining share fastest in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports processed brown rice to Gulf Cooperation Council states and European health-food distributors. This trade corridor concentrates milling capacity in Punjab and Haryana. California's Sacramento Valley supplies organic certified grain to US coastal metropolitan markets.
United States
Health-conscious households in coastal metropolitan markets drive organic brown rice consumption through subscription delivery channels. FDA food-labeling standards enforce whole-grain content declarations with third-party fiber verification protocols. California's Sacramento Valley dominates certified organic output, though drought cycles threaten supply continuity.
India
Domestic consumption and export processing intensify simultaneously across North Indian plains. FSSAI mandates fortification compliance and maximum foreign matter limits on milled rice entering domestic commerce. Punjab and Haryana milling corridors concentrate bran-stabilization investments as PLI scheme subsidies attract capital equipment deployment.
Thailand
Parboiled brown rice exports anchor institutional procurement contracts with Middle Eastern food-service operators. The country's national agricultural regulator enforces paddy variety registration and export quality grading standards. Bangkok-centered processing clusters supply extended-shelf-stability formats to hospital and school cafeteria networks across GCC states.
Vietnam
Mekong Delta smallholders supply conventional brown rice to bulk container export channels. The government's agricultural development programs promote mechanized drying infrastructure to reduce post-harvest losses. Ho Chi Minh City logistics hubs coordinate containerized shipments to European and North African buyers.
Italy
Specialty grocery channels across Northern Europe import Italian organic brown rice for premium positioning. EU organic regulations govern pesticide residue thresholds and conversion period requirements for certified product lines. Po Valley milling operations in Piedmont and Lombardy concentrate heritage varietal processing for direct-trade export contracts.
Brown Rice Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and channel access. The vendor base fragments across geographic processing clusters rather than consolidating around integrated multinationals. Three archetypes dominate: heritage family farms with organic density, South Asian integrated millers with export infrastructure, and specialty importers with smallholder direct-trade relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure bran-stabilization equipment and cross-border distribution agreements.
Within the heritage farm tier, Lundberg Family Farms and Lotus Foods Inc. exemplify certification-centric positioning. KRBL Limited anchors the South Asian integrated milling archetype with Punjab infrastructure. These three occupy positions spanning organic provenance, export scale, and heirloom varietal sourcing respectively.
| Leading Market Players |
|---|
| Riviana Foods Inc. |
| KRBL Limited |
| LT Foods Limited |
| Cargill Incorporated |
| Amira Nature Foods Ltd. |
| Kohinoor Foods Limited |
| Lundberg Family Farms |
| Daawat |
| Lotus Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day organic certification transition timelines compress working capital cycles for growers converting conventional acreage, amplifying pricing power for established California and Punjab processors who already hold certified inventory. This lead-time asymmetry rewards early organic adopters with margin premiums while locking out price-sensitive bulk buyers from premium channels.
Pricing Analysis
Enzyme-inactivation steam treatment versus conventional hot-air drying creates a technology-generation pricing gap that stratifies the market into three tiers. Three-tier pricing structure across premium organic steam-treated, standard certified organic, and economy conventional levels captures value from bran-stabilization durability. Price differentiation rests on USDA organic certification density and bran-layer retention assay scores. Pricing pressure stems from diesel and irrigation electricity tariff volatility squeezing smallholder paddy suppliers. Food-service institutional buyers exhibit lowest price sensitivity, prioritizing spoilage reduction over per-unit cost.
Supply Chain Analysis
Punjab and Haryana milling corridors constitute the primary chokepoint for Indian export-grade brown rice entering Gulf Cooperation Council and European channels. Geographic supply concentration centers on India, California's Sacramento Valley, and Thailand's Bangkok-centered processing clusters. Raw material dependencies include paddy varietal purity, diesel fuel for mechanized harvesting, and irrigation water access. Single-source vulnerability threatens US organic supply given California's drought exposure. Distribution runs through supermarket bulk bins, e-commerce subscription platforms, and food-service institutional procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-inactivation steam treatment adoption represents a high-growth disruption as FDA fiber verification protocols tighten, favoring processors with capital equipment already deployed. USDA organic certification acceleration creates winner-take-most dynamics across premium channels.
For Market Incumbents: Consolidate bran-stabilization equipment holdings through targeted acquisition of Punjab and Sacramento Valley mills with certified organic throughput. KRBL Limited and Lundberg Family Farms should deepen backward integration into paddy varietal breeding programs to lock in germ integrity specifications. Quinoa and farro substitution threats demand faster organic certification pipeline expansion to maintain shelf-space dominance. For New Entrants and Emerging Players: USDA organic transition fast-tracks offer entry into premium channels previously blocked by three-year land conversion barriers. Cambodia and Laos smallholder heirloom varietal networks remain the most penetrable white-space geography, with direct-trade premiums bypassing commodity exchange pricing. E-commerce subscription auto-replenishment models provide the optimal go-to-market angle for coastal US metropolitan household penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underperforming brown rice divisions lacking organic certification density. Long-term viability favors processors with bran-stabilization technology deployment and cross-border distribution agreements already operational. Watch India's PLI scheme capital subsidy disbursement velocity as the signal indicating accelerated industry consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bran-Stabilization Equipment Deployment | Steam treatment adoption extends shelf life without chemical preservatives, unlocking direct-to-retailer contracts. |
| USDA Organic Certification Expansion | Three-year land conversion timelines create competitive moats as health-oriented retailers mandate organic provenance. |
| Direct-Trade Smallholder Sourcing | Heirloom varietal networks in Cambodia and Laos bypass commodity exchanges for specialty export premiums. |
| E-Commerce Subscription Channel Buildout | Auto-replenishment models capture coastal metropolitan household loyalty through certification transparency. |
| Backward Integration into Paddy Breeding | In-house varietal development locks germ integrity specifications against substitution threats from ancient grains. |
Methodological Framework
Operator-level perspectives from rice mill procurement directors, organic certification auditors, food-service institutional buyers, and e-commerce subscription platform managers anchored the qualitative base. Primary fieldwork combined with secondary validation from USDA organic certification databases, FSSAI fortification compliance records, FDA food-labeling guidance documents, and customs trade flow data. Bottom-up volume modeling across product type, distribution channel, end use, and packaging format segments triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across diesel price volatility scenarios, drought severity assumptions for California's Sacramento Valley, and PLI scheme subsidy disbursement trajectories. Segmentation dimensions modeled include organic versus conventional versus parboiled product tiers, supermarket versus online retailer versus health food store channels, and household versus food-service versus industrial end uses. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Bran-stabilization equipment deployment rates and organic certification pipeline velocity served as industry-specific forecast inputs.
Underlying assumptions cover stable FDA fiber verification protocol enforcement, uninterrupted India-GCC trade corridor access, and moderate drought recurrence cycles in California, with deviation risk concentrated in climate-induced yield shocks and sudden organic certification standard revisions. Practitioners should keep alternative scenarios live as India's PLI scheme implementation pace and FDA labeling threshold adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soya Flour Market
Grains
White Rice Flour Market
Grains
India Rice Market
Grains
China Maize Market
Grains
Uganda Grains Market
Grains
China Rice Market
Grains
Rolled Oats Market
Grains
Grain Dryers Market
Grains
Global Quinoa Market
Grains
Non-Basmati Rice Market
Grains
United States Rice Market
Grains
North America Wheat Market
Grains
Grain Silos and Storage System Market
Grains
Global Rice Market
Grains
Rye Market
Grains
Wheat Flour Market