
 Gluten Free Ancient Grain Market | 2026-2036
Gluten Free Ancient Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Ancient Grain Market Insights
Subscription-based replenishment services for specialty flour blends is repositioning how ancient grain suppliers engage household buyers. Ardent Mills leverages its vertically integrated milling network to secure consistent quinoa supply across North American foodservice channels. Bob's Red Mill Natural Foods sustains brand loyalty through transparent sourcing narratives and certified gluten-free production protocols. Nature's Path Foods anchors its portfolio in organic ancient grain cereals that command shelf space in natural retail segments.
Gluten-free ancient grains comprise seed varieties from non-cereal grasses including Chenopodium quinoa, Amaranthus species, Eragrostis tef, and Panicum miliaceum, all structurally lacking the glutenin and gliadin proteins found in Triticum wheats, and they serve primarily as functional ingredients in allergen-free food formulations targeting celiac-disease patients and discretionary wellness consumers. Quinoa dominates volume among product types due to established processing infrastructure and broad culinary familiarity in Western markets. Millet competes aggressively on price in bulk ingredient procurement by food manufacturers seeking cost-advantaged gluten-free extenders. Teff occupies a premium niche within specialty stores where Ethiopian-origin positioning supports higher per-unit margins.
The FDA enforces its gluten-free labeling rule at 20 ppm maximum detectable gluten, while the EU requires CE-marked allergen controls under Regulation EU No 1169/2011, and both frameworks compel ingredient suppliers to invest in dedicated handling equipment and third-party certification. The USDA Organic seal intersects with gluten-free claims to create dual-certified SKUs that retailers prioritize in planogram resets. Stakeholders must monitor evolving Codex Alimentarius standards for ancient grain definitions that could reshape import eligibility and tariff classifications.
Market Dynamics
Certified gluten-free supply chain segregation now commands capital allocation priority as dual USDA Organic and FDA gluten-free certification requirements reshape facility investment decisions across North American milling operations.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The 20 ppm threshold mandates dedicated handling infrastructure that locks in compliant suppliers and creates barriers for non-certified competitors seeking retail shelf placement.
- Clean-label pasta manufacturing:Specialty food producers now specify ancient grain flours as functional wheat replacements in allergen-free product lines targeting celiac-disease patients.
- Quinoa processing infrastructure:Established supply networks across the Andean region and North American cultivation zones reduce raw material volatility for downstream formulators.
Market Restraints
- Teff supply concentration:Ethiopian-origin sourcing limits volume scalability and exposes buyers to export licensing fluctuations and geopolitical disruption risks.
- Cross-contamination prevention costs:Dedicated milling equipment, separate storage silos, and third-party gluten testing impose capital burdens that disadvantage smaller regional processors.
- Buckwheat and rice flour substitution:Lower-cost gluten-free alternatives compete aggressively in commodity baking applications where ancient grain premiums face resistance.
Strategic Opportunities
- Subscription flour replenishment:Direct-to-consumer channels for specialty ancient grain blends bypass conventional retail slotting fees and capture household pantry loyalty.
- South American teff cultivation:Climate-appropriate growing regions in Bolivia and Argentina offer supply diversification beyond Ethiopian dependency.
- EU Regulation 1169/2011 alignment:Harmonized allergen disclosure standards enable unified packaging for transatlantic export and reduce SKU complexity.
Industry Challenges
- Certified gluten-free agronomist shortage:Field expertise in gluten-free crop rotation planning and contamination prevention remains scarce relative to expansion timelines.
- Multi-certification audit complexity:Simultaneous USDA Organic, Non-GMO Project, and gluten-free verification creates documentation burdens that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Ancient Grain Market |
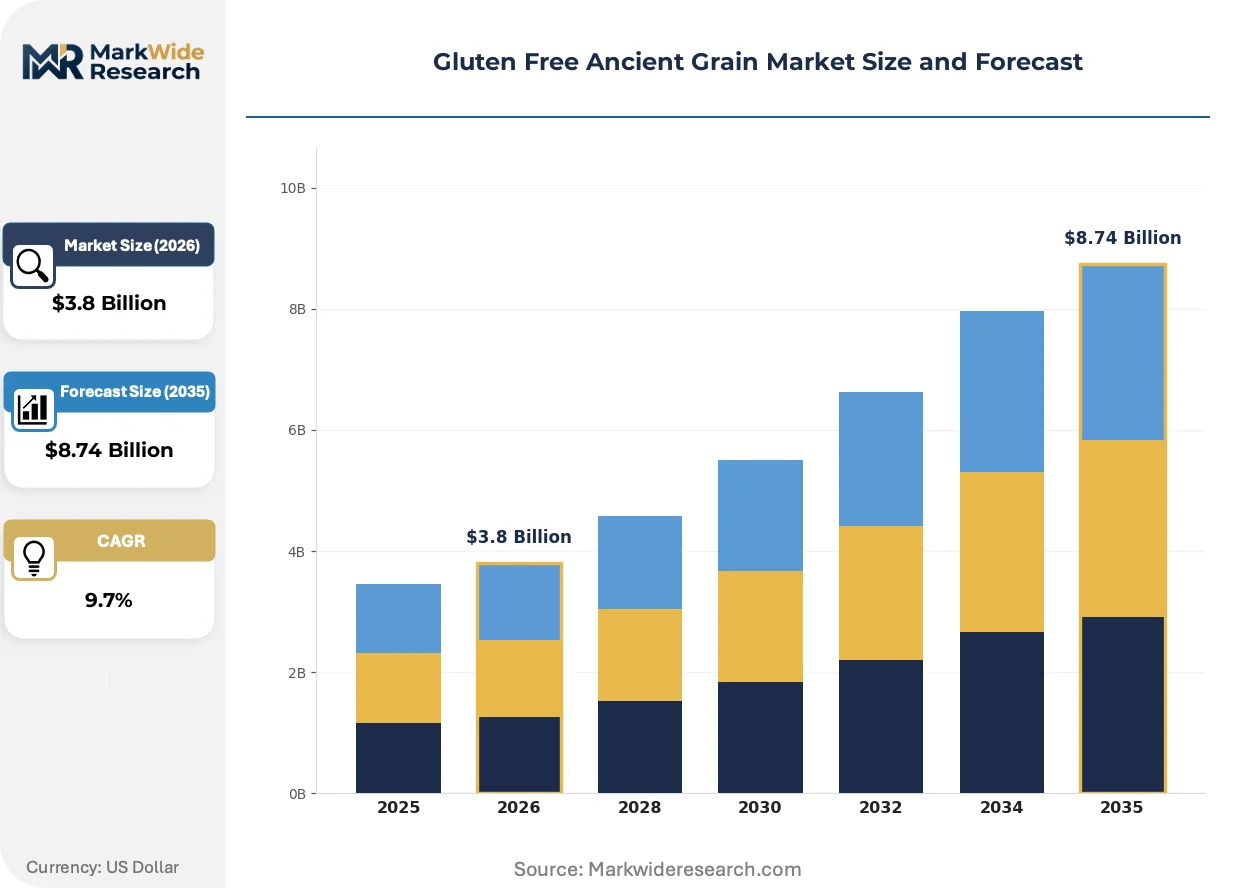
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quinoa, Amaranth, Teff, Millet End User: Households, Restaurants, Food Manufacturers, Specialty Stores Packaging Type: Bags, Boxes, Bulk Containers, Pouches Form: Whole Grains, Flours, Pasta, Breakfast Cereals |
| Companies Covered | The J.M. Smucker Co., Ardent Mills, Bunge, ADM, Bob's Red Mill Natural Foods, Nature's Path Foods, Ancient Harvest, Healthy Food Ingredients, Factoria Quinoa Zona Franca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Ancient Grain Market Trends and Innovations
Processing technology and certification protocols are converging to redefine competitive advantage in ancient grain value chains, with automation and traceability systems now determining supplier viability.
Optical sorting technology is integrating into quinoa cleaning operations to detect and remove gluten-containing grain contamination at throughput rates exceeding manual inspection capacity. Large-scale millers in the United States and Canada now deploy these systems as standard equipment. This capability compression is enabling single-facility processing of both conventional and gluten-free grains without cross-contact risk.
EU Regulation 1169/2011 enforcement is tightening traceability documentation requirements for ancient grain imports entering European food manufacturing channels. Ingredient suppliers must now maintain lot-level allergen testing records across multi-country supply chains. Organic ancient grain cereal producers targeting German and French retail channels are responding by consolidating sourcing relationships to reduce audit fragmentation.
Household buyers now specify certified gluten-free ancient grains through direct subscription channels that displace conventional grocery replenishment cycles. Natural retail segments in the United States are losing volume to specialty e-commerce platforms offering transparent sourcing narratives. This channel rotation is most visible in quinoa and amaranth flour categories where origin storytelling commands premium pricing.
Gluten Free Ancient Grain Market Segmentation
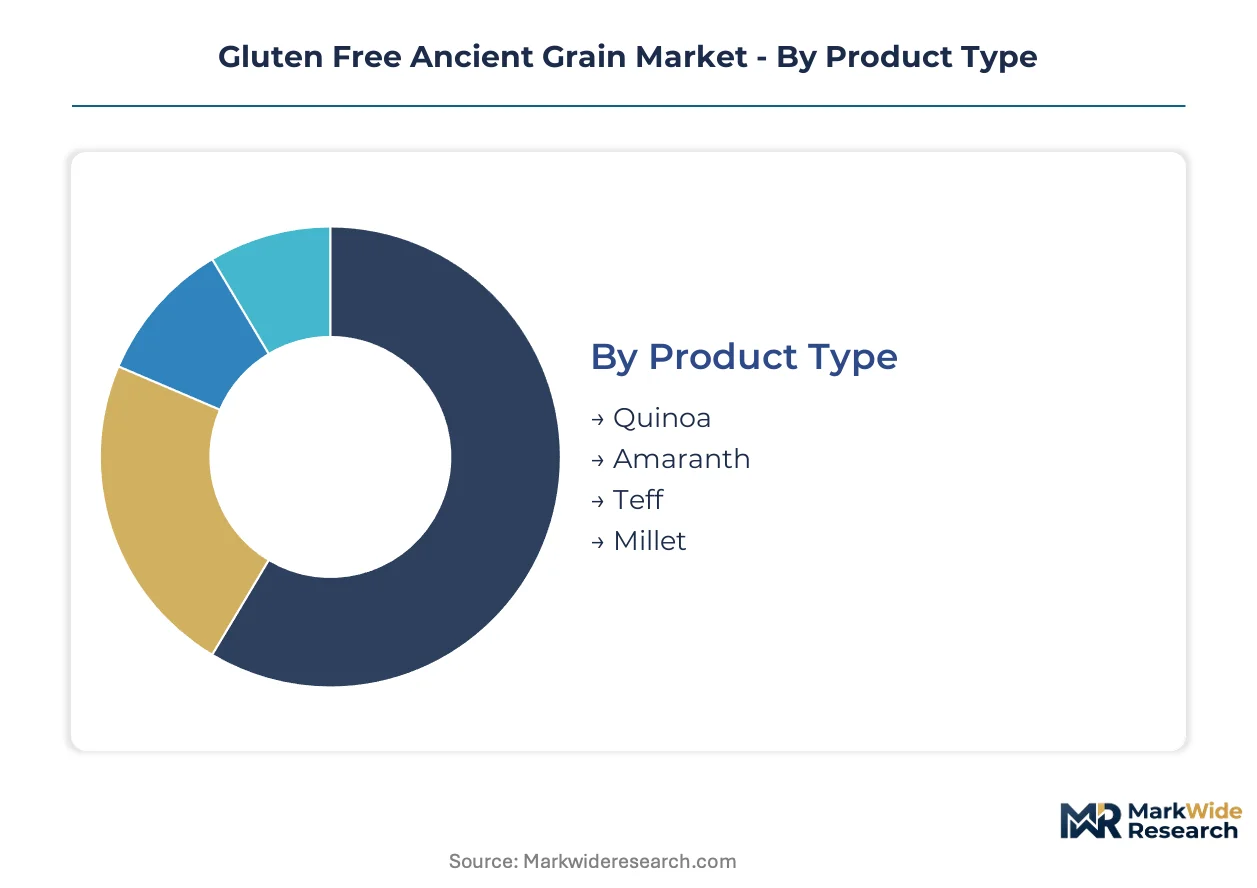
Segmentation in gluten-free ancient grains reveals how certification requirements, processing infrastructure, and channel economics allocate value across distinct product configurations. Each dimension exposes different barriers to entry and margin structures for suppliers navigating dual organic and gluten-free compliance.
Product Type:
Volume leadership concentrates in established categories with proven supply chains, while premium positioning attaches to origin-specific varieties with limited geographic sourcing.
- Quinoa:Chenopodium quinoa delivers complete protein profiles with all nine essential amino acids, making it the functional benchmark for gluten-free formulation. Household buyers in the United States drive replenishment through both retail grocery and direct subscription channels, with Andean and North American cultivation zones reducing supply volatility for downstream millers.
- Teff:Eragrostis tef maintains Ethiopian-origin positioning that commands specialty store premiums despite supply concentration risks. Restaurant demand for authentic injera production and specialty flour blends concentrates in urban markets where Ethiopian diaspora communities anchor consistent procurement.
- Amaranth:Amaranthus species offer heat-tolerant cultivation with similar protein completeness to quinoa at lower input costs.
- Millet:Panicum miliaceum competes aggressively on price in bulk ingredient procurement by food manufacturers seeking cost-advantaged gluten-free extenders.
Mature deployment sits with quinoa. Newer deployment is concentrated in teff as suppliers invest in South American cultivation diversification.
End User:
Channel economics diverge sharply between direct household relationships and institutional procurement governed by food safety audit requirements.
- Food Manufacturers:Specialty pasta and cereal producers specify certified gluten-free ancient grains as functional wheat replacements, with FDA 20 ppm compliance mandatory for retail shelf placement. Clean-label product lines targeting celiac-disease patients require dedicated handling infrastructure that locks in qualified suppliers.
- Households:Subscription-based replenishment services now capture pantry loyalty through transparent sourcing narratives and certified gluten-free production protocols. E-commerce platforms displace conventional grocery cycles for quinoa and amaranth flour categories where origin storytelling supports premium pricing.
- Restaurants:Ethiopian and health-focused establishments drive teff demand for injera and ancient grain bowls.
- Specialty Stores:Natural retail segments prioritize dual USDA Organic and gluten-free SKUs in planogram resets.
Volume scale concentrates with food manufacturers. Margin expansion is climbing the fastest with households through direct channels.
Packaging Type:
Packaging selection reflects contamination risk management, shelf-life requirements, and channel-specific handling economics.
- Bags:Multi-layer paper and polymer constructions dominate retail flour distribution with moisture barriers protecting gluten-free integrity.
- Pouches:Stand-up flexible formats with resealable closures capture household premium positioning in natural retail segments.
- Bulk Containers:Foodservice and manufacturing procurement relies on super sacks and totes with lot-level traceability documentation.
- Boxes:Breakfast cereal and pasta applications require rigid secondary packaging for shelf stability and retail display efficiency.
Standardization sits with bags. Innovation is concentrating in pouches as direct-to-consumer channels expand.
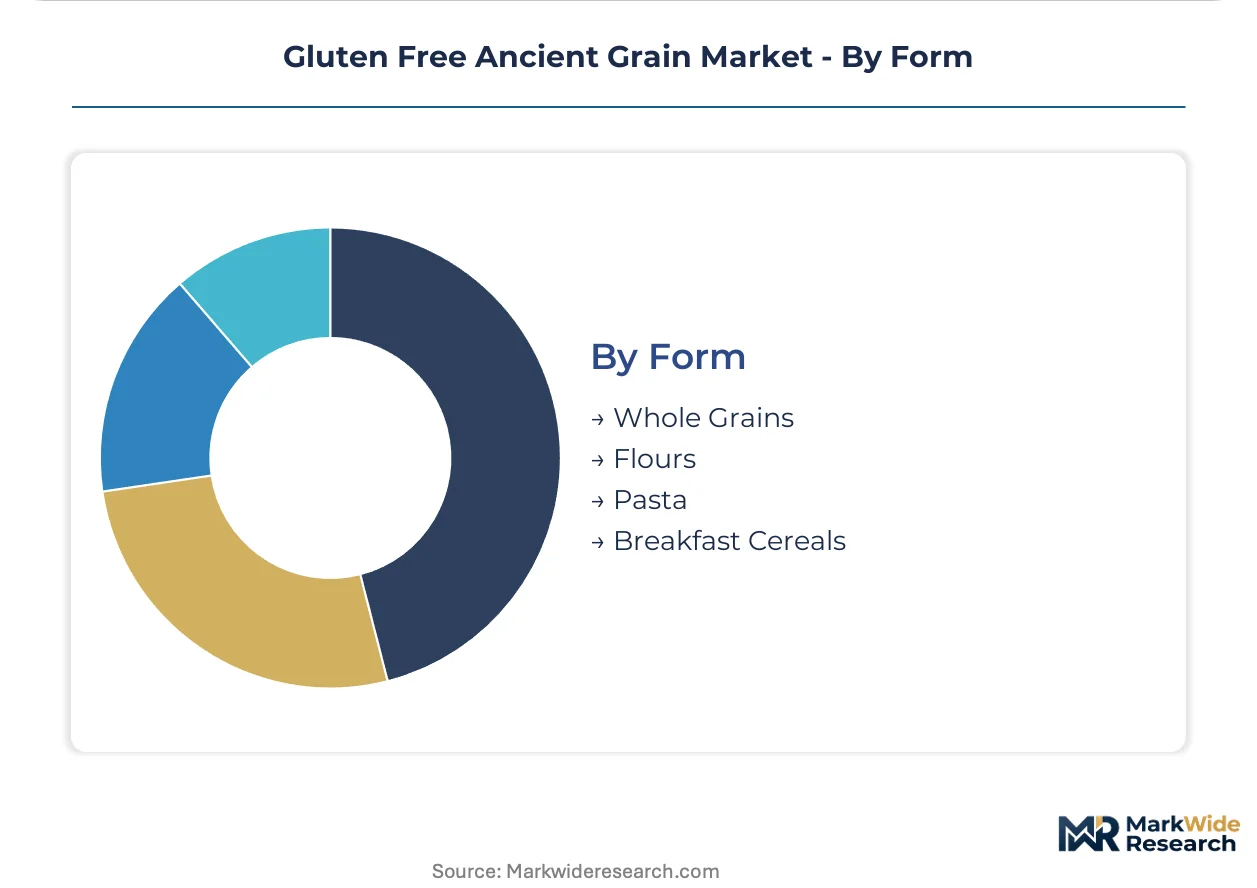
Form:
Processing intensity and value addition separate commodity grain trading from branded ingredient and finished food positioning.
- Flours:Milled quinoa, teff, and amaranth serve as direct wheat substitutes in allergen-free baking with particle size specifications governing water absorption and texture outcomes.
- Breakfast Cereals:Puffed and flaked ancient grains command shelf space in natural retail segments where organic certification intersects with gluten-free claims.
- Whole Grains:Unprocessed seed forms supply bulk ingredient procurement and household cooking applications with minimal processing overhead.
- Pasta:Extruded ancient grain formulations target clean-label positioning in specialty food channels.
Processing maturity sits with whole grains. Value-added expansion is gaining share fastest in flours as home baking and specialty manufacturing demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American quinoa milling capacity through Ardent Mills' vertically integrated processing campus serving foodservice and retail channels.
United States
Household buyers in the Pacific Northwest and Northeast Corridor drive subscription-based flour replenishment through direct e-commerce platforms. The FDA enforces its 20 ppm gluten-free labeling threshold, compelling dedicated handling infrastructure investment. Minneapolis-St. Paul concentrates organic certification expertise with milling clusters serving dual USDA Organic and gluten-free production protocols.
Canada
Saskatchewan prairie provinces expand quinoa cultivation acreage to reduce Andean import dependency for North American supply chains. Health Canada maintains aligned gluten-free standards with cross-border recognition facilitating integrated US-Canada distribution. Vancouver and Toronto anchor natural retail segments prioritizing dual-certified ancient grain cereals in planogram resets.
Germany
Food manufacturers in Bavaria specify ancient grain flours for clean-label pasta lines targeting celiac-disease patients and wellness consumers. EFSA enforces allergen disclosure under Regulation EU No 1169/2011 with traceability documentation requirements tightening for import suppliers. Munich industrial zones concentrate organic processing infrastructure serving German and French retail channels.
France
Paris metropolitan natural retail segments command premium shelf positioning for Ethiopian-origin teff products with origin storytelling. The EU Green Deal intersects with gluten-free certification to incentivize sustainable sourcing protocols in ancient grain procurement. Lyon foodservice clusters drive restaurant demand for authentic injera production in urban markets.
Ethiopia
Domestic teff production anchors global supply for specialty flour blends with export licensing governing international volume allocation. The country's national food safety regulator maintains phytosanitary controls on grain shipments entering European and North American channels. Addis Ababa processing zones concentrate cleaning and packaging infrastructure for premium positioning in Western markets.
Gluten Free Ancient Grain Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct operational models in gluten-free ancient grain supply. Vertically integrated millers with dedicated gluten-free facilities lock in retail shelf placement through certification compliance that smaller regional processors cannot replicate. Three archetypes dominate: multi-commodity agribusiness conglomerates with ancient grain divisions, specialty organic millers with transparent sourcing narratives, and Andean-origin cooperatives controlling quinoa cultivar access. Capacity expansion and backward integration into certified gluten-free seed multiplication represent the primary competitive vectors.
Among North American integrated millers, Ardent Mills and Bob's Red Mill Natural Foods exemplify divergent strategic positions. Ardent Mills occupies the scale-driven archetype with vertically controlled supply networks spanning cultivation zones through foodservice distribution. Bob's Red Mill Natural Foods anchors the specialty transparency tier where certified gluten-free production protocols and sourcing narratives command household pantry loyalty. ADM represents the diversified agribusiness model with ancient grain lines embedded within broader ingredient portfolios.
| Leading Market Players |
|---|
| The J.M. Smucker Co. |
| Ardent Mills |
| Bunge |
| ADM |
| Bob's Red Mill Natural Foods |
| Nature's Path Foods |
| Ancient Harvest |
| Healthy Food Ingredients |
| Factoria Quinoa Zona Franca |
| Others |
Pricing and Supply Chain Analysis
FDA-mandated gluten-free certification at 20 ppm compels food manufacturers to source exclusively from suppliers with dedicated handling infrastructure, forcing supply consolidation around capital-intensive millers and compressing margins for non-certified regional processors.
Pricing Analysis
Cost compression in bulk quinoa procurement accelerates as Saskatchewan cultivation expansion reduces Andean import dependency and spot-market volatility. Three-tier pricing structure across certified organic-premium, conventional gluten-free-standard, and commodity-grade-economy levels separates buyers by certification stringency and volume commitment. Price differentiation hinges on dual USDA Organic and FDA gluten-free verification status plus geographic proximity to North American milling clusters. Food manufacturers exhibit highest price sensitivity due to bulk ingredient substitution options, while specialty retailers and direct-to-consumer channels absorb premiums for transparent sourcing narratives.
Supply Chain Analysis
Direct-to-household subscription channels bypass conventional retail slotting fees and capture pantry loyalty through transparent sourcing narratives and certified gluten-free production protocols. Raw material flows concentrate in Peru, Bolivia, and Saskatchewan for quinoa; Ethiopia for teff; and the United States for amaranth and millet. Processing infrastructure draws from optical sorting systems, dedicated gluten-free milling lines, and third-party certification audits. Single-source vulnerability in Ethiopian teff exposes buyers to export licensing fluctuations and geopolitical disruption. Distribution runs through vertically integrated millers, specialty e-commerce platforms, and natural retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical sorting technology is displacing manual inspection in quinoa cleaning operations, enabling single-facility processing of both conventional and gluten-free grains without cross-contact risk and resetting capital requirements for supplier viability.
For Market Incumbents: Deploy dedicated gluten-free facility certification as a defensive moat against regional processors lacking capital for segregated infrastructure. Expand backward integration into certified seed multiplication in Saskatchewan and Bolivian highlands to reduce Andean supply volatility. Lock in foodservice channel contracts through Ardent Mills-style vertically controlled supply networks before subscription-based household channels erode institutional procurement volume. For New Entrants and Emerging Players: Subscription-based flour replenishment technology offers a white-space entry path around incumbent retail slotting fee structures. Target Pacific Northwest and Northeast Corridor household buyers through direct e-commerce platforms with origin storytelling for quinoa and amaranth categories. Pursue South American teff cultivation partnerships in Bolivia and Argentina as supply diversification beyond Ethiopian dependency creates procurement relationships with specialty pasta manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with specialty organic millers possessing dual USDA Organic and FDA gluten-free certification given clean-label pasta manufacturing demand acceleration. Long-term viability across the analysis window favors suppliers with in-house optical sorting capability and captive North American cultivation relationships. Watch for FDA gluten-free labeling rule enforcement tightening as signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Deployment | Enables single-facility gluten-free and conventional grain processing without cross-contact risk. |
| South American Teff Cultivation Expansion | Bolivian and Argentine growing regions reduce Ethiopian supply concentration and export licensing exposure. |
| Subscription-Based Direct-to-Consumer Launch | Bypasses retail slotting fees and captures household pantry loyalty through transparent sourcing narratives. |
| Dual Certification Investment | USDA Organic and FDA gluten-free verification locks in planogram priority during natural retail resets. |
| Backward Integration into Seed Multiplication | Saskatchewan and Andean captive supply reduces raw material volatility for downstream formulators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across milling operations executives, specialty food manufacturer procurement leads, natural retail category buyers, and certified gluten-free facility auditors. Secondary sources included FDA gluten-free labeling guidance documents, USDA Organic certification databases, EU Regulation 1169/2011 implementation records, and Andean trade export statistics. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates.
Data-stream reconciliation across supply-side cultivation acreage, processing capacity utilization, and demand-side channel shipment patterns informed the analytical framework. Segmentation dimensions modeled included product type, end user, packaging format, and form across the projection horizon. CAGRs derived from fitted growth curves applied to verified base-year volumes. Industry-specific forecast inputs comprised quinoa processing infrastructure expansion timelines and teff export licensing fluctuation patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory threshold revisions, abrupt Ethiopian export policy shifts, and substitution acceleration toward buckwheat and rice flour alternatives. Forecasts reflect documented assumptions regarding certification compliance cost trajectories and household channel migration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Pea Grits Market
Grains
Global Quinoa Market
Grains
Corn Gluten Feed Market
Grains
Europe Maize Market
Grains
China Rice Market
Grains
Soybean Market
Grains
Basmati Rice Market
Grains
Durum Wheat Flour Market
Grains
Africa Maize Market
Grains
Global Grain Mill Products Market
Grains
Corn Silage Market
Grains
Green Banana Flour Market
Grains
Grain Roller Market
Grains
Asia-Pacific Wheat Market
Grains
North America Wheat Flour Market
Grains
Spain Rice Market