
 Wheat Flour Market | 2026-2036
Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Flour Market Intelligence
Asset-light milling contracts and third-party tolling arrangements are reshaping competitive entry in wheat flour, lowering the capital barrier for regional brands. Archer Daniels Midland Company leverages its North American grain origination network to secure cost-advantaged feedstock. Manildra Group anchors Australian domestic supply through integrated wheat processing and starch co-production. Nisshin Flour Milling dominates Japanese premium flour segments with specialized milling technology for ramen and confectionery applications.
Wheat flour consists of finely ground endosperm from common wheat (Triticum aestivum), typically milled to protein levels between 8% and 14% depending on extraction rate and ash content, with its primary purpose being a structural and nutritional base for baked goods, pasta, and processed foods. All-purpose and bread flour categories occupy the largest volume pools in commercial channels, where protein content drives pricing differentiation among industrial buyers. Whole wheat flour represents the fastest-growing product type, as food manufacturers reformulate labels to capture clean-label and high-fiber positioning in retail and foodservice.
FDA enforcement of Food Safety Modernization Act preventive controls and EPA oversight of grain dust emissions shape U.S. milling facility compliance costs and capital planning. China's SAMR implements GB standards for wheat flour fortification and contaminant limits that govern import acceptance and domestic mill licensing. EFSA and national regulators across Europe enforce pesticide residue thresholds and mycotoxin ceilings that filter supply sources into the EU market. Stakeholders must monitor evolving fortification mandates and carbon accounting rules for grain transport to anticipate where procurement economics will shift.
Market Dynamics
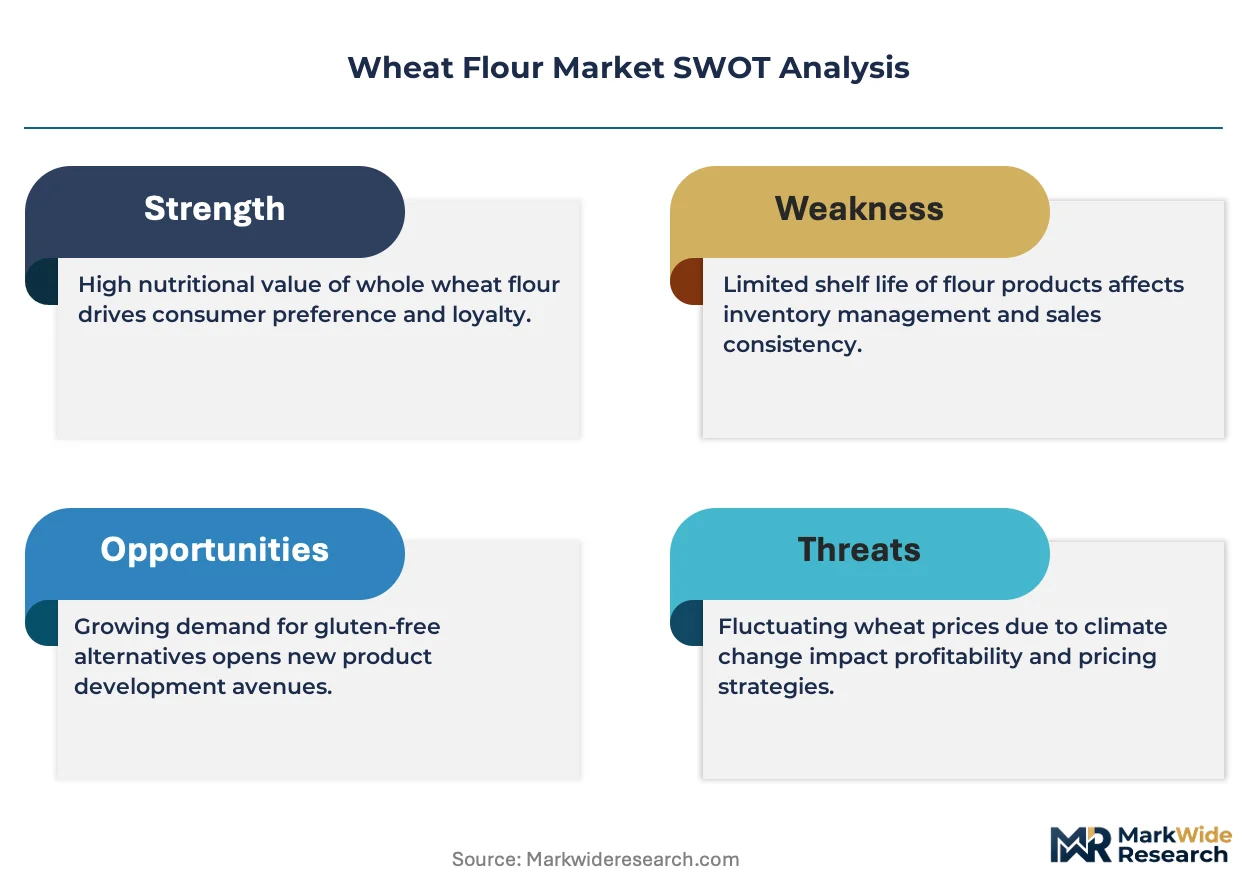
Whole wheat flour adoption is compressing margins for commodity-grade millers while creating premium pricing power for processors with certified clean-label capabilities. India's FSSAI fortification mandates and China's GB standards are accelerating capital deployment toward segregated milling lines and traceability infrastructure.
Growth Catalysts
- India FSSAI Fortification Mandates:Government food distribution programs require iron, folic acid, and vitamin B12 enrichment in subsidized wheat flour, forcing millers to upgrade blending equipment and creating volume guarantees for compliant suppliers.
- Clean-Label Bakery Chains:Urban foodservice buyers in India and China specify whole wheat and ancient grain blends for menu differentiation, pulling premium flour varieties through commercial channels at price multiples above commodity grades.
- NIR Spectroscopy Deployment:Inline protein and ash measurement systems allow real-time extraction adjustment, reducing off-spec batches and enabling contract precision for industrial buyers with tight tolerances.
Market Restraints
- Black Sea Supply Concentration:Ukraine and Russia wheat export disruptions expose import-dependent markets in Egypt and Indonesia to price volatility and forced origin switching.
- EPA Grain Dust Compliance:U.S. milling facilities face capital-intensive ventilation and ignition-source controls under OSHA and EPA joint enforcement, elevating facility upgrade costs above replacement economics for aging plants.
- Pulse Flour Substitution:Chickpea and lentil flours capture formulation share in gluten-free and high-protein applications, displacing wheat in specific nutrition-positioned product lines.
Strategic Opportunities
- Sub-Saharan Africa Underpenetration:Per-capita wheat flour consumption in Nigeria and Ethiopia remains below half of South Asian levels, creating white space for regional milling joint ventures with grain traders.
- EU CSRD Carbon Accounting:Scope 3 emissions disclosure requirements for food manufacturers create procurement preference for millers with verified low-carbon grain sourcing and renewable energy processing.
- E-Commerce Bulk Channels:Direct-to-bakery flour platforms in India bypass traditional distributor markups, capturing margin compression as volume aggregation tools for small and mid-size processors.
Industry Challenges
- Mycotoxin Testing Bottlenecks:EU EFSA and China SAMR tightening of aflatoxin and deoxynivalenol limits extends lot-release timelines, requiring millers to hold inventory longer or invest in rapid-testing infrastructure.
- Milling Engineer Scarcity:Specialized knowledge of pneumatic conveying and roll stand adjustment is concentrating among aging workforces in Europe and North America, elevating training costs for facility expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Flour Market |
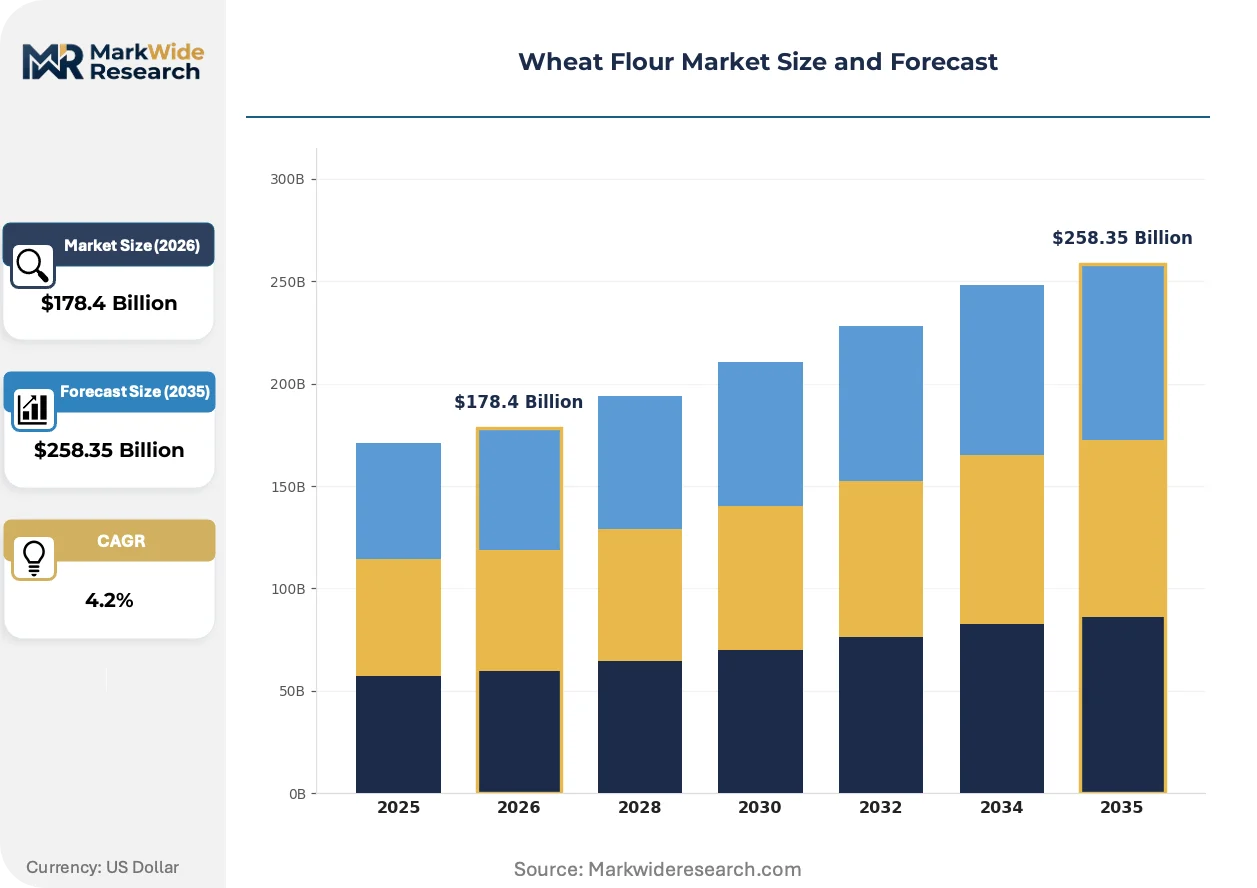
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $258.35 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose, Bread, Cake, Whole Wheat, Self-Rising, Pastry Application: Baking, Pasta Production, Snack Foods, Cereals, Confectionery, Coating End User Type: Bakeries, Food Manufacturers, Foodservice, Household Consumers, Institutional Kitchens Packaging Format: Bagged, Boxed, Bulk, Paper Sack, Plastic Sack, Reusable Container |
| Companies Covered | Bob's Red Mill Natural Foods, Allied Pinnacle Pty Ltd, Archer Daniels Midland Company, Nisshin Flour Milling, Acarsan Holding, Ardent Mills, King Arthur Baking Company, Manildra Group, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Flour Market Strategic Shifts & Innovations
Digital traceability and automated process control are displacing manual quality verification and paper-based lot tracking across wheat flour supply chains. These shifts compress decision cycles while raising compliance precision.
Near-infrared spectroscopy paired with cloud-based batch analytics is digitizing quality assurance workflows in industrial mills. Large bakery conglomerates in Germany and Japan are requiring supplier integration with their ERP systems for real-time specification verification. This connectivity is compressing supplier qualification timelines and elevating data infrastructure to a competitive threshold.
China's SAMR is tightening GB 2762 contaminant limits and GB 14880 fortification standards, forcing import mills to segregate production lines and maintain dual certification documentation. Domestic Chinese millers with integrated testing laboratories capture procurement preference from multinational food manufacturers. The compliance burden is filtering smaller traders from cross-border supply positions.
Food manufacturers are consolidating supplier rosters and demanding outcome-based flour performance guarantees rather than commodity specifications. This compression of vendor lists is visible in India's organized bakery sector, where national chains now contract directly with integrated millers for customized protein and ash profiles. Distributor networks face disintermediation as volume concentrates with traceable direct relationships.
Wheat Flour Market Segmentation
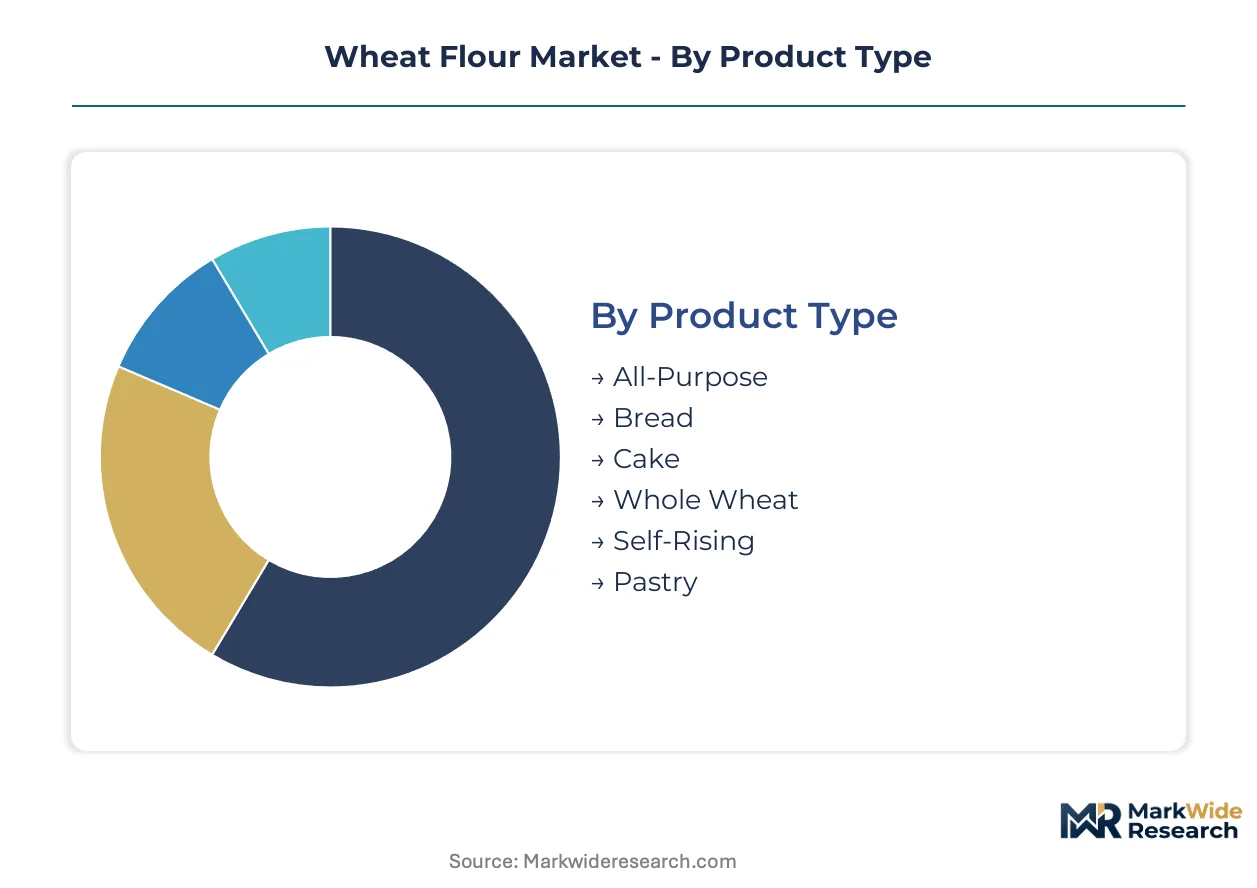
Wheat flour segmentation reveals divergent margin structures and procurement rhythms across product grades, end-use channels, and packaging formats. Industrial buyers prioritize protein consistency and traceability, while retail channels demand shelf-stable packaging and clean-label positioning. Understanding these segment dynamics exposes where capital deployment yields pricing power versus commodity exposure.
Product Type:
Cycle times vary dramatically across flour grades, with commodity all-purpose turning weekly and specialty whole wheat rotating monthly due to shorter shelf life and premium positioning.
- All-Purpose:Milled to 10-12% protein with moderate ash content, serving as the workhorse flour for general baking and home cooking. Demand concentrates in North American retail channels and Asian noodle manufacturing, where processors value specification consistency for automated production lines.
- Whole Wheat:Contains full bran and germ with protein levels of 13-14% and elevated fiber content, commanding price multiples in clean-label bakery applications. India's FSSAI fortification mandates and China's GB standards are accelerating certified organic whole wheat procurement from integrated millers with segregated production lines.
- Bread:High-gluten formulation at 12-14% protein optimized for yeast-raised dough elasticity. Commercial bakeries in Germany and Japan specify custom protein ranges for artisan and industrial production.
- Cake:Low-protein soft wheat milled to 7-9% protein for tender crumb structure. Premium confectionery manufacturers in France and Belgium source heritage wheat varieties for differentiated texture profiles.
- Self-Rising:Pre-blended with leavening agents and salt for convenience baking. North American retail distribution and UK supermarket private labels drive volume concentration.
- Pastry:Low-protein soft wheat with fine granulation for laminated dough applications. Specialized French and Japanese millers dominate supply to luxury hotel chains and patisserie networks.
All-purpose dominates installed base. Whole wheat is where expansion concentrates.
Application:
Cost tier separation is pronounced, with baking and pasta production absorbing bulk commodity grades while confectionery and coating applications command premium specifications.
- Baking:Encompasses bread, pastry, and cake production across artisan, industrial, and in-store bakery formats. India's organized bakery chains and Germany's wholesale bakeries are consolidating supplier rosters toward direct mill relationships with customized protein profiles.
- Pasta Production:Requires durum wheat semolina or high-protein common wheat for extruded and sheeted products. Italian and Turkish manufacturers enforce strict ash and gluten index specifications for export-grade dried pasta.
- Snack Foods:Wheat flour serves as structural base for crackers, pretzels, and extruded snacks. US and Mexican processors reformulate toward whole grain positioning to capture clean-label retail placement.
- Cereals:Breakfast cereal manufacturers utilize heat-treated and pre-gelatinized wheat flours for flake and puff production. Kellogg and General Mills procurement specifications drive milling technology investment.
- Confectionery:Ultra-fine milled specialty flours for wafer, biscuit, and chocolate-enrobed applications. Swiss and Belgian processors demand traceable heritage wheat with documented mycotoxin testing.
- Coating:Pre-dust and batter applications for fried and baked protein products. Foodservice distributors in the US and UK specify gluten-free alternatives for allergen-sensitive menu items.
Baking commands the largest volume footprint. Confectionery is climbing the fastest on value per ton.
End User Type:
Customer type determines contract structure, with food manufacturers locking annual supply agreements while foodservice operates on spot purchasing with shorter lead times.
- Food Manufacturers:Industrial processors of baked goods, pasta, and prepared foods requiring specification-tight flour with lot traceability. China's SAMR GB standards and US FDA preventive controls are mandating supplier certification and inline testing infrastructure.
- Bakeries:Artisan and commercial bread producers purchasing bulk flour with protein and ash customization. India's urban bakery chains are bypassing distributors for direct mill contracts with guaranteed fortification compliance.
- Foodservice:Restaurants, hotels, and catering operations buying bagged or bulk flour with flexible delivery schedules. Japanese ramen chains specify proprietary milling curves for noodle texture differentiation.
- Household Consumers:Retail packaged flour purchases through supermarkets and e-commerce platforms. Indian direct-to-bakery platforms are aggregating small-processor demand to compress distributor markups.
- Institutional Kitchens:Schools, hospitals, and military facilities procuring fortified flour through government tender programs. India's government food distribution channels mandate FSSAI-compliant iron and folic acid enrichment.
Food manufacturers anchor procurement volume. Bakeries are gaining share fastest on premium grade demand.
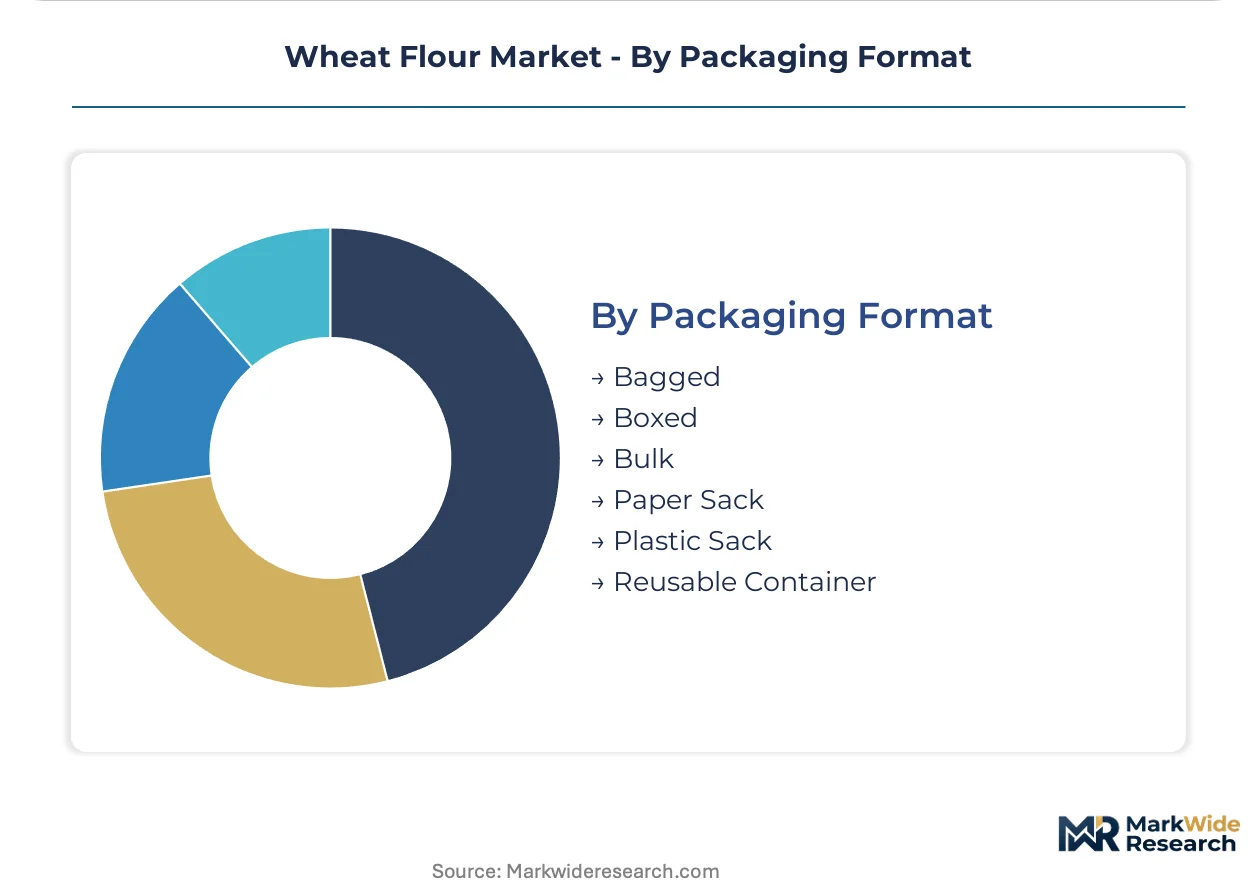
Packaging Format:
Volume scale inversely correlates with packaging sophistication, with bulk rail and truck shipments serving industrial users while retail channels require multi-layer barrier protection.
- Bulk:Unpackaged flour delivered by pneumatic tanker or rail car for high-volume industrial users. German and Japanese milling clusters optimize bulk logistics through dedicated grain elevator networks.
- Paper Sack:Multi-wall kraft construction with moisture barriers for 25-50kg industrial and commercial distribution. EU CSRD carbon accounting is pressuring converters toward recyclable and compostable material specifications.
- Bagged:Consumer retail packaging in 1-5kg formats with oxygen and moisture barriers for extended shelf stability. Indian e-commerce bulk channels are experimenting with consolidated bagged shipments for small bakery aggregation.
- Plastic Sack:Polyethylene and polypropylene woven bags for export and humid-climate distribution. Nigerian and Ethiopian importers favor plastic sacks for port handling and warehouse storage durability.
- Boxed:Corrugated retail cases for club store and foodservice multi-packs. US warehouse retailers specify pallet-ready configurations for automated distribution center handling.
- Reusable Container:Bulk totes and deposit-based systems for closed-loop bakery and food manufacturing supply chains. French and Dutch circular economy pilots are testing standardized container pooling across miller-processor networks.
Bulk and paper sack dominate installed base. Reusable container is where pilot investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government fortification mandates and subsidy programs are redrawing procurement maps for wheat flour, channeling investment toward compliant milling capacity in high-population markets. Cross-border grain flows face tightening contaminant standards from national regulators. Urban bakery chain expansion is pulling premium flour varieties through commercial channels at differentiated price points.
United States
Commercial bakeries and snack food manufacturers anchor industrial flour demand, with EPA grain dust regulations and FDA Food Safety Modernization Act preventive controls elevating facility compliance costs. Large milling clusters in Kansas and Minnesota optimize bulk rail logistics for bread and all-purpose grades. Chicago and St. Louis serve as distribution hubs for eastern and southern bakery networks.
China
Urban bakery chains and instant noodle manufacturers are pulling high-protein and specialty flour varieties through commercial channels. SAMR GB standards for wheat flour fortification and contaminant limits govern import acceptance and domestic mill licensing. Yangtze River Delta milling clusters around Shanghai and Wuxi capture procurement preference from multinational food manufacturers seeking integrated testing capabilities.
India
FSSAI fortification mandates for iron, folic acid, and vitamin B12 enrichment in subsidized wheat flour are forcing millers to upgrade blending equipment. Government food distribution programs create volume guarantees for compliant suppliers. Mumbai and Delhi-NCR urban bakery chains are bypassing distributors for direct mill contracts with guaranteed fortification compliance and customized protein profiles.
Germany
Artisan and industrial bakeries enforce strict protein and ash specifications for bread flour, with EU EFSA pesticide residue thresholds and mycotoxin ceilings filtering supply sources. CSRD carbon accounting requirements create procurement preference for millers with verified low-carbon grain sourcing. Bavarian and North Rhine-Westphalia milling clusters serve wholesale bakery networks across Central Europe.
Australia
Asian noodle manufacturers and Middle Eastern importers drive export-oriented wheat flour production, with Manildra Group anchoring domestic supply through integrated wheat processing. Quality benchmarks for cross-border grain shipments tighten under destination-country regulations. Sydney and Melbourne milling facilities optimize starch co-production alongside flour output for diversified revenue streams.
Wheat Flour Market Key Industry Players
On the supply side, the industry is consolidating around integrated grain processors with captive origination networks and segregated milling lines for specialty grades. Three archetypes dominate: North American grain traders with downstream milling assets, Asia-Pacific specialists in premium and application-specific flours, and regional integrated processors with starch or co-product diversification. Competitive moves center on direct-to-bakery platform development and fortification compliance certification.
Among North American integrated processors, Archer Daniels Midland Company and Ardent Mills exemplify scale-driven supply chain control, while Nisshin Flour Milling occupies a position within the Asia-Pacific premium specialty tier. King Arthur Baking Company represents the clean-label and heritage-positioned archetype in consumer-facing channels. These three anchors illustrate how geographic origin and product focus stratify competitive positioning across commercial and retail segments.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| Allied Pinnacle Pty Ltd |
| Archer Daniels Midland Company |
| Nisshin Flour Milling |
| Acarsan Holding |
| Ardent Mills |
| King Arthur Baking Company |
| Manildra Group |
| General Mills |
| Others |
Cost & Logistics Intelligence
Black Sea grain origination concentration in Ukraine and Russia anchors global wheat flour pricing volatility, compressing margin pools for import-dependent millers in Egypt and Indonesia while rewarding integrated processors with captive North American or Australian supply bases.
Pricing Analysis
Certification level creates the primary spread between commodity and premium flour tiers. Three-tier pricing structure across organic-certified, fortified-compliant, and standard grades governs contract negotiations. Pricing pressure stems from FSSAI and SAMR fortification mandates forcing capital deployment into segregated milling lines. Industrial food manufacturers show lowest price sensitivity due to specification-locked supply agreements, while small bakeries and institutional kitchens face acute cost compression.
Supply Chain Analysis
Tariff exposure between Black Sea exporters and MENA importers dominates supply chain risk calculus. Geographic supply concentrates in Russia, Ukraine, and the European Union for raw wheat, while finished flour processing clusters in China, India, and the United States. The supply chain rests on pneumatic grain handling equipment, roll stand milling technology, and fortification blending systems. Single-source vulnerability runs through Black Sea port access for Egyptian and Indonesian millers. Distribution runs through bulk rail and tanker networks for industrial buyers, with bagged channels serving retail and foodservice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-bakery platform economics are reshaping procurement relationships, with ERP-integrated suppliers capturing volume concentration as interoperability becomes the competitive threshold for industrial flour contracts.
For Market Incumbents: Build fortification compliance certification as the primary moat. Secure backward integration into Australian or North American grain origination to insulate against Black Sea volatility. Deploy NIR spectroscopy and cloud-based batch analytics to compress supplier qualification timelines for multinational food manufacturers. For New Entrants and Emerging Players: Sub-Saharan African markets offer the most penetrable white space, with Nigerian and Ethiopian per-capita consumption below half of South Asian levels. Target regional milling joint ventures with grain traders to establish local processing capacity. Leverage e-commerce bulk channels in India to aggregate small-processor demand and bypass traditional distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward integrated millers with dual starch-flour co-production and verified low-carbon grain sourcing for EU CSRD compliance. Long-term viability favors processors with segregated organic and fortified production lines. Monitor EU EFSA and China SAMR contaminant limit tightening as the inflection signal for rapid-testing infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fortification Compliance Certification | FSSAI and SAMR mandates create procurement preference for certified integrated millers with segregated production lines. |
| Direct-to-Bakery Platform Development | ERP-integrated supply relationships disintermediate distributors and capture volume from India's organized bakery chains. |
| Regional Milling Joint Ventures | Sub-Saharan African partnerships with grain traders address underpenetrated Nigerian and Ethiopian consumption gaps. |
| NIR Spectroscopy Deployment | Inline protein and ash measurement enables real-time extraction adjustment for industrial buyers with tight tolerances. |
| Low-Carbon Sourcing Verification | EU CSRD Scope 3 disclosure requirements create procurement preference for renewable energy processing and verified grain sourcing. |
Research Approach
Cross-validation between primary interviews with milling operations directors, grain procurement managers, and bakery chain supply heads and secondary sources including customs trade data, FSSAI fortification compliance records, and SEC filings anchors the qualitative findings. Bottom-up facility capacity assessments and top-down consumption estimates triangulate market sizing across product grades and end-use channels.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the projection framework. Segmentation dimensions span product type, application, end user category, and packaging format across the modeling period. CAGRs derive from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs incorporate FSSAI fortification mandate compliance rates and EU EFSA mycotoxin limit enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive vertical consolidation by North American grain traders or accelerated SAMR standard tightening would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Cereals Market
Grains
Organic Rice Market
Grains
Guar Complex Market
Grains
Grain Roller Market
Grains
Grain Storage Systems Market
Grains
Italy Rice Market
Grains
Grain Storage Silos Market
Grains
Wheat Bran Market
Grains
Quinoa Flour Market
Grains
India Rice Market
Grains
Low Fat Rice Market
Grains
Grain Augers Market
Grains
Rice Flour Market
Grains
Cameroon Grains Market
Grains
Green Banana Flour Market
Grains
Europe Wheat Protein Market