
 Global Rice Market | 2026-2036
Global Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Market Outlook
Thai fragrant rice exporters are realigning supply chains after Mekong basin water policy shifts. Cargill Incorporated leverages its integrated origination network across multiple continents. Olam International Limited anchors African distribution through localized processing facilities. KRBL Limited dominates basmati exports with heritage variety preservation programs.
Rice constitutes the seed of Oryza sativa, a semi-aquatic annual grass typically milled to 5-20% moisture content for stable storage and culinary preparation. Basmati commands premium positioning through protected geographical indication status and elongated kernel morphology. Long grain varieties sustain volume leadership in institutional food service channels across West Africa and the Caribbean. Retort pouch packaging is capturing share from traditional bulk formats in urban Asian markets.
FSSAI in India enforces pesticide residue ceilings and fortification standards that reshape milling infrastructure requirements. EMA and EFSA frameworks in Europe govern maximum contaminant levels for imported rice, directly conditioning market access for Asian exporters. USDA grading protocols in the United States classify kernel integrity and chalkiness, influencing price discovery at Gulf Coast ports. Stakeholders must track water allocation conflicts between agricultural and industrial users in major producing basins.
Market Dynamics
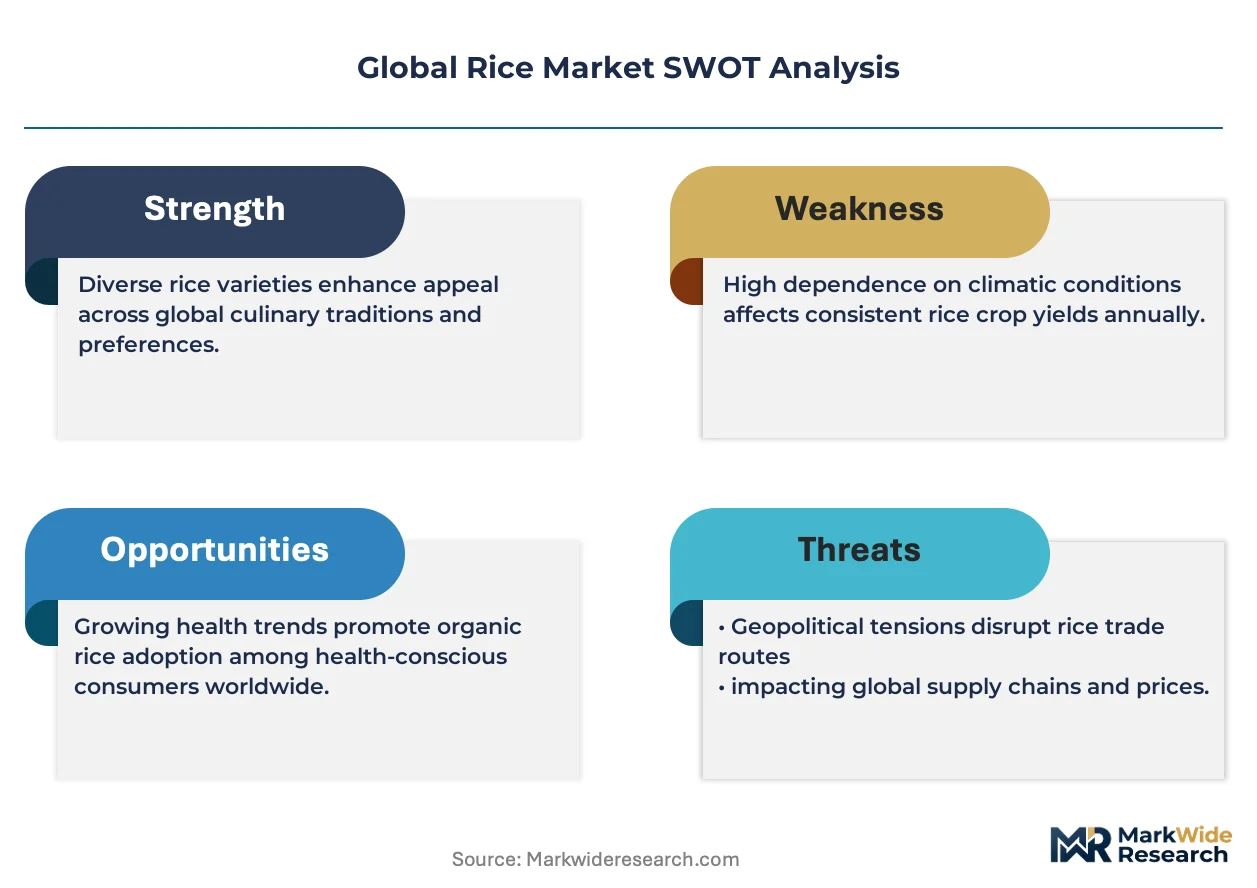
Water allocation conflicts between agricultural and industrial users across the Mekong Delta and Indus-Ganges basins are restructuring procurement geography and milling investment priorities.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory micronutrient enrichment standards redirect capital toward nutrient-enhanced milling infrastructure, creating compliant output premiums.
- Aromatic variety demand:Southeast Asian food processors expand procurement of Thai Hom Mali and Vietnamese Jasmine varieties for premium retail positioning.
- Heritage variety preservation:Geographical indication protections for Basmati in India and Pakistan sustain price premiums through controlled seed certification.
Market Restraints
- Input cost volatility:Fertilizer and diesel price swings in Punjab and Haryana compress margins for mechanized transplanting and harvesting operations.
- Supply concentration risk:The Mekong Delta corridor accounts for disproportionate export volume, exposing buyers to single-basin climate and policy disruptions.
- Regulatory friction:EFSA maximum contaminant levels for arsenic and cadmium create non-tariff barriers for South Asian exporters seeking European market access.
Strategic Opportunities
- Underpenetrated African markets:West African urbanization drives demand for packaged parboiled rice, with localized processing investments reducing import dependency.
- Retort pouch distribution:Urban Asian consumers shift from bulk wholesale to shelf-stable convenience formats, opening branded retail channels.
- Technology convergence:Blockchain traceability platforms integrate with IoT moisture sensors to verify origin and quality across fragmented supply chains.
Industry Challenges
- Skill gaps in precision agriculture:Drone-based crop monitoring and variable-rate input application require technical training unavailable in rural Thai and Vietnamese farming communities.
- Certification timeline compression:Organic and fair-trade accreditation processes lag planting cycles, preventing timely premium market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Market |
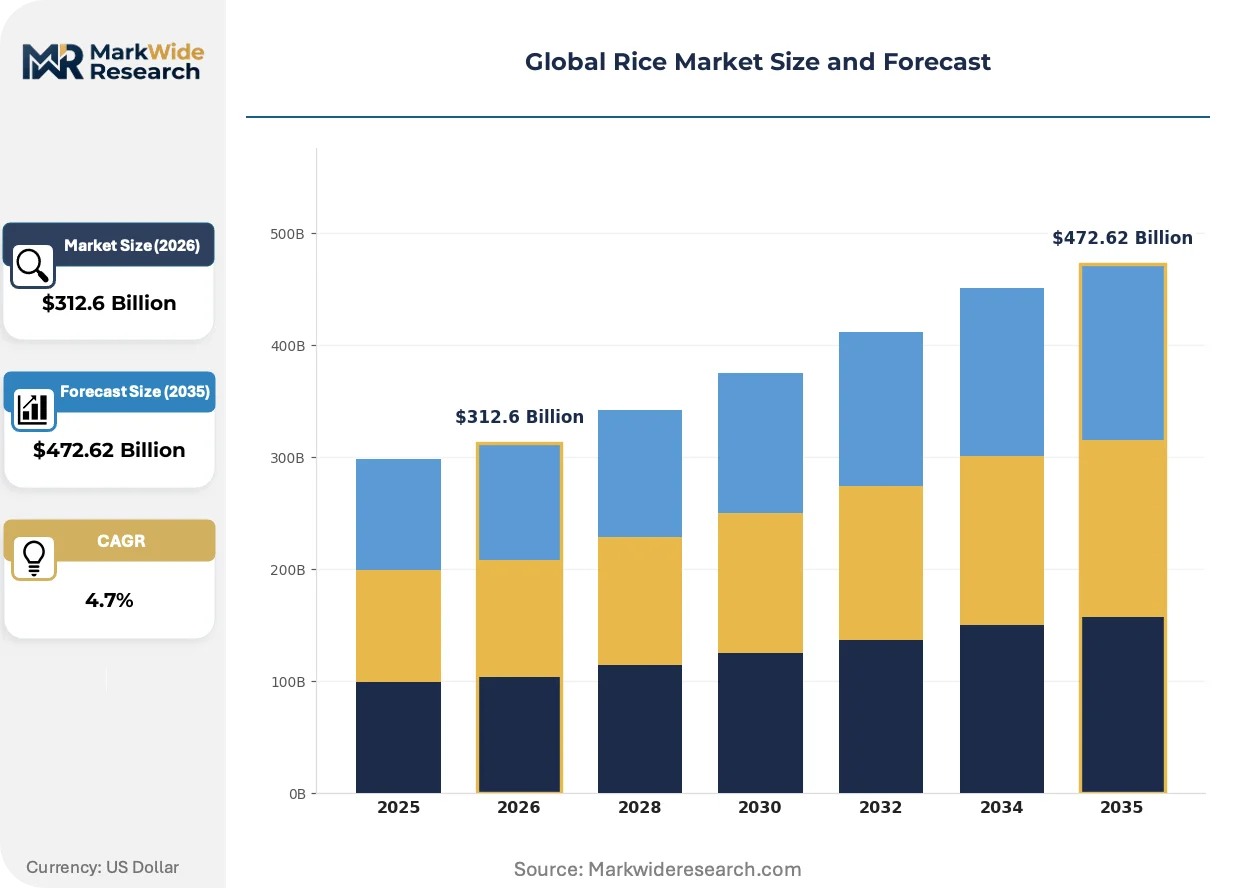
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basmati, Jasmine, Arborio, Long Grain End User: Food Processing, Catering Services, Retail Consumers, Exporters Distribution Channel: Online Sales, Supermarkets, Wholesale, Direct Sales Packaging Type: Bags, Containers, Bulk, Retort Pouches |
| Companies Covered | Cargill Incorporated, China National Cereals, Oils and Foodstuffs Corporation, Charoen Pokphand Foods, Olam International Limited, Ebro Foods, LT Foods, KRBL Limited, Riceland Foods Inc., Adani Wilmar Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Market Strategic Shifts
Digital traceability infrastructure and climate-adaptive breeding programs are compressing quality verification cycles while expanding cultivable zones for heritage varieties.
Gene-edited drought tolerance traits is unifying yield stability across rain-fed and irrigated production systems. Seed multinationals deploy CRISPR-derived water-use efficiency markers across Indian and Bangladeshi breeding programs. This convergence is compressing the risk premium between flood-prone delta cultivation and upland farming.
REACH chemical registration requirements in Europe now extend to pesticide metabolite residues in rice imports. Asian exporters face expanded testing protocols for glyphosate and tricyclazole derivatives. Premium aromatic suppliers in Thailand and Cambodia are accelerating integrated pest management adoption to maintain shelf access.
Direct-to-retailer contracting is displacing traditional auction-floor price discovery in Bangkok and Ho Chi Minh City trading hubs. Supermarket chains and food service aggregators negotiate fixed-volume agreements with designated millers. This concentration is most visible in Vietnam's Mekong Delta, where cooperatives bypass wholesale intermediaries entirely.
Global Rice Market Segmentation
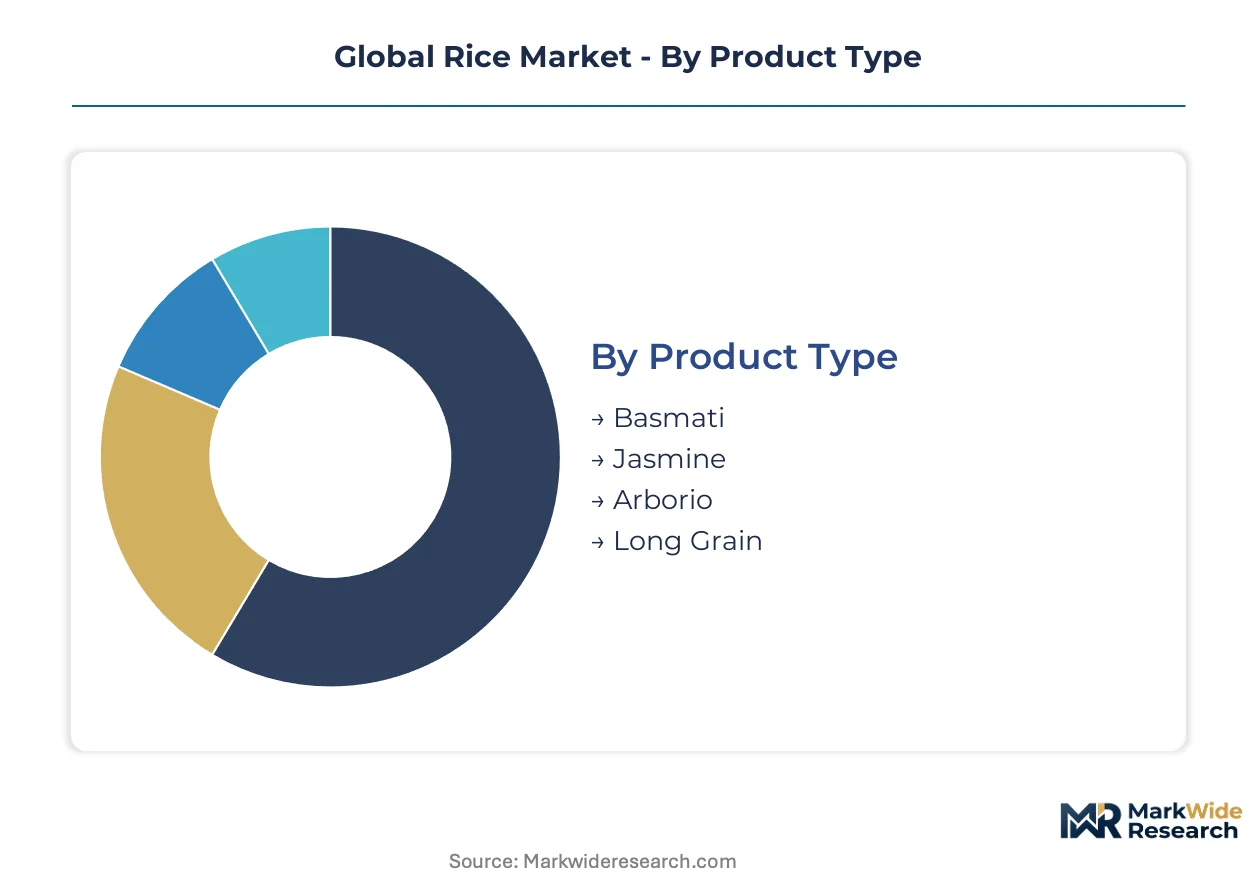
Rice market segmentation tracks how varietal specialization, procurement channel evolution, and packaging format innovation reshape margin structures across origin and destination markets. Distinct quality tiers and distribution pathways create divergent investment requirements for milling infrastructure and cold chain logistics.
Product Type:
Supply concentration in heritage aromatic varieties determines premium capture potential and geographical indication enforcement intensity across South Asian and Southeast Asian export zones.
- Basmati:Elongated kernel morphology and protected geographical indication status in India and Pakistan command price premiums through controlled seed certification. Demand concentrates in Middle Eastern import markets and diaspora retail channels in the United Kingdom and United States, sustained by heritage authenticity requirements and strict aroma compound standards.
- Jasmine:Thai Hom Mali and Vietnamese KDM varieties deliver distinctive pandan-like fragrance through elevated 2-acetyl-1-pyrroline content. Procurement concentrates in Southeast Asian food processing clusters seeking premium retail positioning, though water allocation conflicts in the Mekong Delta constrain volume expansion.
- Arborio:Italian-origin short-grain variety with high amylopectin content enables creamy risotto texture. European Union protected designation of origin frameworks restrict authentic labeling to Po Valley cultivation zones.
- Long Grain:High-amylose varieties sustain volume leadership in institutional food service channels across West Africa and the Caribbean, with parboiling treatments extending shelf stability for tropical storage conditions.
Long grain absorbs the bulk of installed capacity; Jasmine is expanding most quickly.
End User:
Cost tier differentiation separates commodity bulk purchasers from premium segment buyers willing to absorb traceability and certification premiums.
- Food Processing:Ready-meal manufacturers and snack producers require consistent grain dimensions and moisture specifications for automated handling systems. Procurement concentrates in Thailand's central plains and Vietnam's Mekong Delta corridor, where integrated milling clusters deliver standardized output.
- Catering Services:Institutional food service operators prioritize parboiled varieties for holding stability and portion consistency. Demand clusters in West African urban centers and Gulf Cooperation Council labor accommodation facilities.
- Retail Consumers:Branded packaged rice purchases accelerate in Asian urban markets as consumers shift from bulk wholesale toward convenience formats with visible quality grading.
- Exporters:Trading houses and origin-integrated multinationals manage cross-border logistics, quality arbitration, and phytosanitary compliance across fragmented regulatory environments.
Food Processing commands dominant volume share; Retail Consumers are climbing the fastest.
Distribution Channel:
Customer type fragmentation between price-sensitive bulk buyers and convenience-seeking urban households drives channel diversification strategies.
- Supermarkets:Modern retail chains in Bangkok, Ho Chi Minh City, and Lagos negotiate direct-to-retailer contracts with designated millers, displacing traditional auction-floor price discovery and compressing wholesale intermediary margins.
- Wholesale:Traditional trading hubs at Gulf Coast ports and West African gateway cities sustain price discovery for containerized bulk shipments, though volume share erodes under supermarket consolidation pressure.
- Online Sales:E-commerce platforms and quick-commerce aggregators penetrate urban Indian and Southeast Asian markets with subscription-based replenishment models for branded packaged varieties.
- Direct Sales:Cooperative bypass arrangements in Vietnam's Mekong Delta enable grower groups to capture milling and export margins previously absorbed by intermediary traders.
Wholesale retains dominant volume throughput; Online Sales are gaining share fastest.
Packaging Type:
Margin structure varies sharply between commodity bulk handling and value-added convenience formats requiring capital-intensive retort processing equipment.
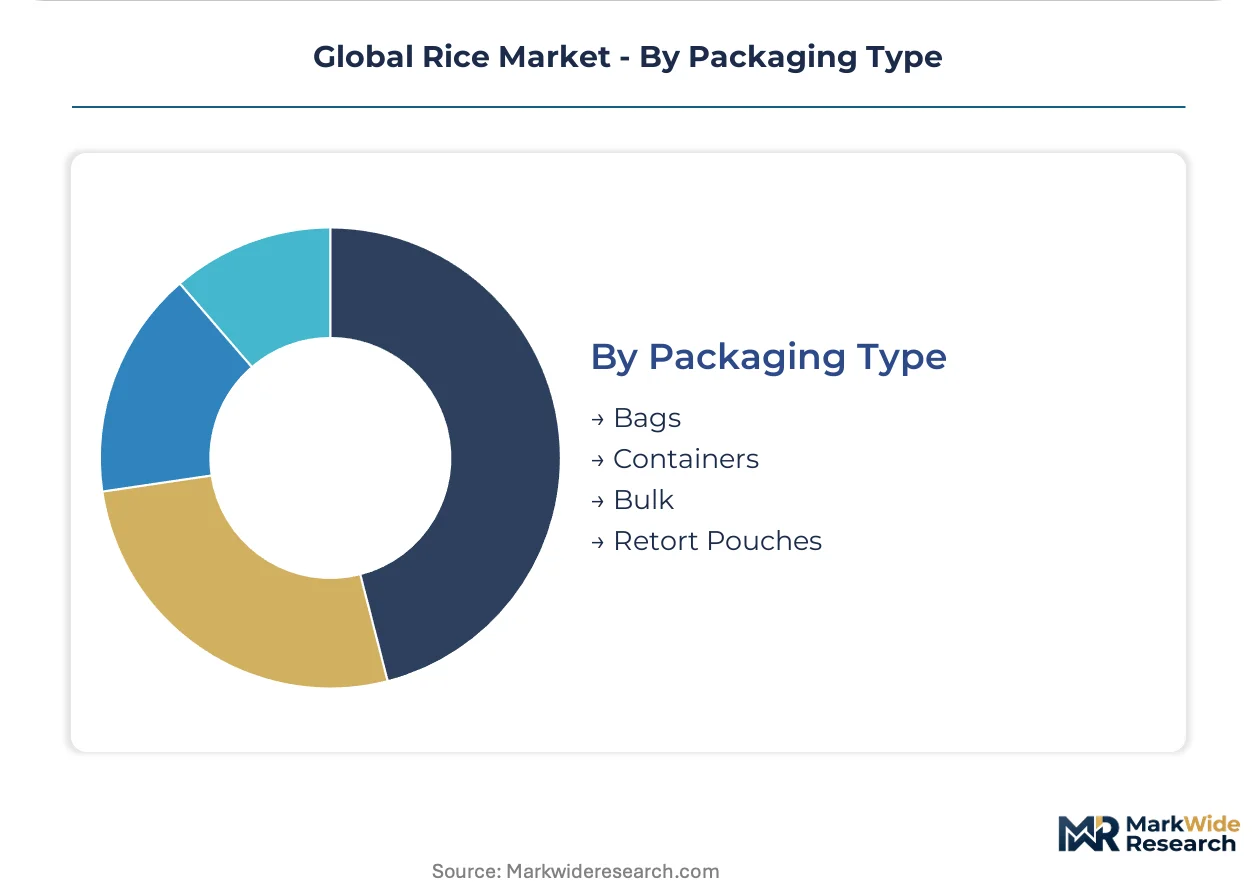
- Retort Pouches:Shelf-stable, pre-cooked rice formats capture share from traditional bulk in Asian urban markets where refrigeration constraints and convenience preferences converge. Cargill and Olam International have expanded retort line investments to serve supermarket private label programs.
- Bags:Woven polypropylene and laminated paper bags dominate export logistics for 5kg to 50kg retail and institutional formats, with moisture barrier specifications critical for tropical transit conditions.
- Bulk:Containerized loose grain shipments minimize unit packaging costs for industrial processors and large-scale food service operators with captive milling capabilities.
- Containers:Rigid plastic and metal canister formats target premium gift segments and air freight channels where crush resistance and shelf presentation justify higher packaging expenditure.
Bags absorb the bulk of packaging volume; Retort Pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mekong Delta's water-stressed paddies and the Indus-Ganges basin's fertilizer-intensive plains anchor regional production geography. Climate variability and irrigation policy shifts are redrawing procurement corridors across four major origin markets.
Thailand
Thai Hom Mali exports face irrigation quota constraints as industrial users compete for Chao Phraya basin allocations. The country's agricultural ministry enforces seed certification protocols that preserve aromatic compound standards. Ubon Ratchathani and Surin provinces concentrate heritage variety cultivation, with millers investing in moisture-controlled storage to combat harvest-season humidity spikes.
Vietnam
Vietnamese KDM and OM 5451 varieties command premium positioning in Southeast Asian food processing channels. The Ministry of Agriculture and Rural Development regulates pesticide residue thresholds for European-bound shipments. An Giang and Dong Thap provinces host integrated milling clusters where cooperatives negotiate direct-to-retailer contracts with supermarket chains.
India
Basmati exports from Punjab and Haryana sustain Middle Eastern and diaspora market demand through FSSAI-enforced geographical indication protections. The Food Safety and Standards Authority of India mandates iron and folic acid fortification standards that redirect capital toward nutrient-enhanced milling infrastructure. Karnal and Panipat districts concentrate parboiling and sorting facilities serving containerized export logistics.
United States
Long-grain production in Arkansas and Louisiana supplies institutional food service channels across the Caribbean and West Africa. USDA grading protocols classify kernel integrity and chalkiness at Gulf Coast ports, conditioning price discovery for export cargoes. The Mississippi Delta corridor integrates seed breeding, mechanized harvesting, and river-barge logistics into vertically coordinated supply chains.
Pakistan
Pakistani Basmati competes with Indian heritage varieties for Middle Eastern import share through controlled seed certification and aroma compound verification. The Pakistan Standards and Quality Control Authority enforces pesticide residue ceilings aligned with EFSA maximum contaminant levels. Sheikhupura and Gujranwala districts concentrate export-oriented milling capacity with dedicated parboiling lines for Saudi and UAE buyers.
Global Rice Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue convenience-format packaging and blockchain traceability services. The market structures around three concentration layers: integrated multinationals with origination networks across multiple continents, regional specialists anchored in single-origin heritage varieties, and cooperative federations capturing milling margins through direct-export arrangements. Strategic moves center on backward integration into seed certification programs and forward integration into retail private-label contracting.
Among Asia-anchored heritage specialists, KRBL Limited exemplifies geographical indication enforcement through controlled seed distribution and aroma compound preservation. Cargill Incorporated occupies a position representing integrated origination scale across Thai, Vietnamese, and Indian supply basins. Olam International Limited sits within the African distribution archetype, with localized processing facilities reducing import dependency in West African urban markets.
| Leading Market Players |
|---|
| Cargill Incorporated |
| China National Cereals, Oils and Foodstuffs Corporation |
| Charoen Pokphand Foods |
| Olam International Limited |
| Ebro Foods |
| LT Foods |
| KRBL Limited |
| Riceland Foods Inc. |
| Adani Wilmar Limited |
| Others |
Value Chain & Pricing Dynamics
Premium-commodity bifurcation between heritage aromatic varieties and bulk long-grain segments manifests in divergent pricing power and supply chain configurations across Thai, Vietnamese, and Indian export zones. Geographical indication enforcement for Basmati and Hom Mali sustains origin premiums through controlled seed certification, while commodity grades compete on delivered cost efficiency through containerized bulk logistics.
Pricing Analysis
Service-bundling separates certified-origin premiums from unbundled commodity spot transactions. Three-tier pricing structure across heritage aromatic, premium standard-grade, and economy bulk levels reflects quality grade and certification tier differentiation. Price differentiation stems from FSSAI fortification compliance costs and EFSA contaminant testing requirements. Pricing pressure intensifies in commodity segments as Mekong Delta water allocation constraints compress harvest volumes. Institutional food service buyers exhibit highest price sensitivity; Middle Eastern import houses absorb heritage premiums with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from European and Middle Eastern buyers mandate multi-origin qualification across Thai, Vietnamese, and Indian supply basins. Raw material dependencies center on Chao Phraya and Mekong basin water allocations, Punjab-Haryana fertilizer inputs, and certified seed stock from agricultural ministries. Single-basin climate vulnerability in the Mekong Delta corridor concentrates supply risk. Distribution runs through Gulf Coast port grading facilities and Bangkok-Ho Chi Minh City direct-retailer contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-stressed production basins in the Mekong Delta and Indus-Ganges corridor constrain volume expansion, propping heritage variety premiums through sustained supply scarcity.
For Market Incumbents: Acquire certified seed distribution networks to lock Basmati and Hom Mali genetic integrity against unauthorized cross-breeding. Secure backward integration into parboiling infrastructure in Karnal and An Giang districts. Defend against blockchain-traceability entrants by embedding IoT moisture sensors in cooperative storage facilities. For New Entrants and Emerging Players: FSSAI fortification mandates in India open a window for nutrient-enhanced milling equipment deployment. Target West African urban packaged rice segments where localized processing gaps persist. Pursue retort pouch private-label contracts with Lagos and Bangkok supermarket chains as entry pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in African distribution platform roll-ups and heritage variety seed technology licensing. Long-term viability favors origin-integrated specialists with captive water access across multiple basins. Watch Mekong basin water policy arbitration outcomes as inflection indicator for Southeast Asian supply reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Seed Certification Program | FSSAI and Thai agricultural ministry protocols preserve aromatic compound standards for export premiums. |
| Retort Pouch Capacity Expansion | Cargill and Olam investments capture urban Asian convenience format migration from bulk wholesale. |
| Blockchain Traceability Integration | IoT sensor networks verify origin and quality for European EFSA compliance and Middle Eastern import houses. |
| West African Localized Processing | Dedicated milling facilities in Lagos and Abidjan reduce import dependency for parboiled rice demand. |
| Direct-to-Retailer Contracting | Vietnamese cooperatives bypass wholesale intermediaries to capture export margins in supermarket channels. |
Study Parameters
Document review covered customs trade databases, FSSAI fortification guidelines, and EFSA contaminant threshold regulations, complemented by interviews with rice mill operations directors, agricultural ministry certification officers, Middle Eastern import procurement managers, and European retail category buyers. Secondary validation drew from USDA grading protocols, Mekong River Commission water allocation reports, and SEC filings from listed grain traders. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Historical export volume trajectories cross-referenced against expert panel assessments of irrigation policy impacts. Segmentation modeling tracked varietal type, end-use channel, packaging format, and regional production cluster across the projection horizon. CAGRs derived from trend extrapolation moderated by basin-specific water stress indices and regulatory compliance cost buildups.
The model assumes a particular technology adoption path for gene-edited drought tolerance traits; alternative pathways for CRISPR-derived water-use efficiency would alter the outlook for rain-fed cultivation expansion. Deviation in Mekong Delta water allocation arbitration or EFSA maximum contaminant level revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Spain Rice Market
Grains
Pulses Market
Grains
Pea Grits Market
Grains
Oat Bran Market
Grains
South Africa Maize Market
Grains
Global Grain Mill Products Market
Grains
Global Quinoa Market
Grains
Quinoa Flour Market
Grains
Uganda Grains Market
Grains
Mesquite Flour Market
Grains
Wheat Fiber Market
Grains
Global Wheat Market
Grains
Ancient Grain Market
Grains
Wheat Bran Market
Grains
Triticale Market
Grains
Green Banana Flour Market