
 Grain Dryers Market | 2026-2036
Grain Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Dryers Market Analysis
Buyer concentration among agricultural cooperatives and commercial elevators is pivoting toward fewer, larger procurement decisions that favor full-system suppliers over component vendors. Brock Grain Systems leverages its integrated storage and handling portfolio to capture these consolidated buyers. GSI Group anchors its position through extensive North American distribution and service infrastructure. Buhler Group differentiates via advanced process control systems that reduce energy intensity per bushel dried.
A grain dryer is a forced-air thermal processing unit that reduces harvested grain moisture content to safe storage levels, typically operating between 120°F and 220°F with airflow rates measured in cubic feet per minute per bushel. Continuous flow systems dominate commercial elevator installations where throughput volume determines equipment selection, while batch type units retain strong penetration among mid-size farms seeking operational flexibility. Mobile dryers represent the fastest-expanding category as custom harvest operators and rental services address seasonal demand spikes without fixed capital commitment.
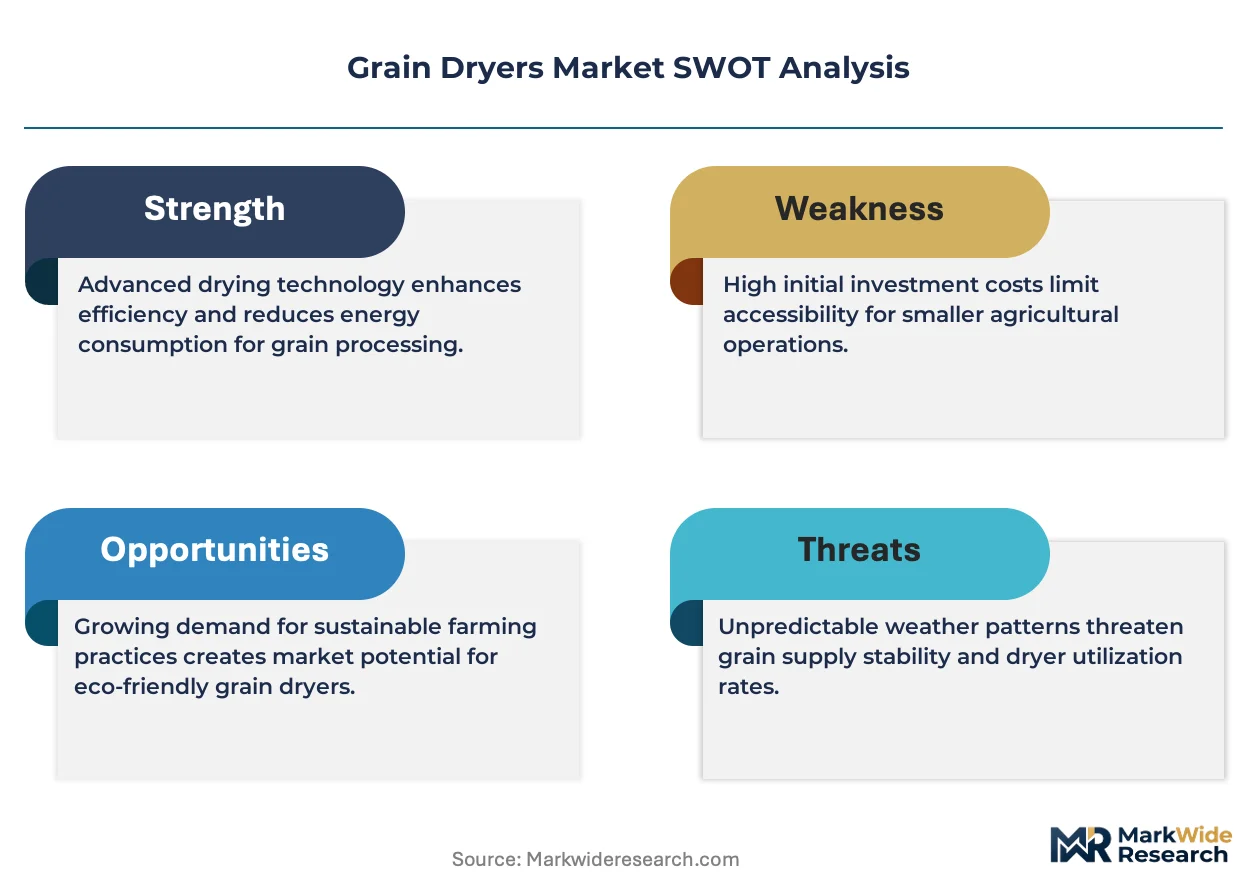
The EPA enforces emissions thresholds for grain dryer burners under the Clean Air Act, compelling manufacturers toward low-NOx combustion and alternative heat sources. EU REACH and F-Gas Regulation constrain refrigerant selection in heat pump dryer designs, adding compliance cost but creating technical barriers for non-European suppliers. Stakeholders must monitor evolving carbon border adjustments and state-level renewable energy incentives that could restructure total cost of ownership calculations for thermal drying equipment.
Market Dynamics
The grain dryers sector faces a structural pivot as EPA emissions thresholds and EU F-Gas Regulation force thermal system redesign, compressing legacy burner architectures while elevating heat pump and indirect fire alternatives to commercial viability.
Growth Catalysts
- US Corn Belt infrastructure buildout:Cooperative storage capacity expansion across Iowa, Illinois, and Nebraska is generating fleet-scale procurement of continuous flow systems for post-harvest moisture management.
- Heat pump technology maturation:Advances in refrigerant efficiency and compressor durability are enabling commercial-scale deployment where natural gas infrastructure is sparse or carbon pricing applies.
- EU carbon border adjustment anticipation:Export-oriented grain handlers in France and Germany are pre-emptively upgrading drying assets to avoid future tariff exposure on commodity shipments.
Market Restraints
- Stainless steel and aluminum input volatility:Dryer fabrication relies heavily on these metals, with price swings compressing manufacturer margins and destabilizing project quoting.
- Refrigerant supply concentration:Heat pump dryer production depends on specialized refrigerant chemistries controlled by a limited supplier base concentrated in China and Germany.
- Natural gas infrastructure lock-in:Existing direct-fire installations across the US Plains create replacement inertia, delaying technology transitions despite regulatory pressure.
Strategic Opportunities
- Mobile dryer rental services:Custom harvest operators in Kansas and the Dakotas are building seasonal fleet businesses that bypass fixed capital requirements for mid-size farms.
- Process control software integration:Convergence of IoT sensors and predictive algorithms enables real-time moisture optimization, opening premium pricing tiers for technology-integrated systems.
- US state renewable energy incentives:Programs in Minnesota and Wisconsin are subsidizing electric and heat pump dryer conversions, creating localized demand acceleration.
Industry Challenges
- Combustion engineering talent scarcity:Low-NOx burner design and heat pump system integration require specialized expertise that agricultural equipment manufacturers struggle to recruit.
- Legacy control system integration:Upgrading decades-old elevator automation to interface with modern dryer process controls creates deployment friction and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Dryers Market |
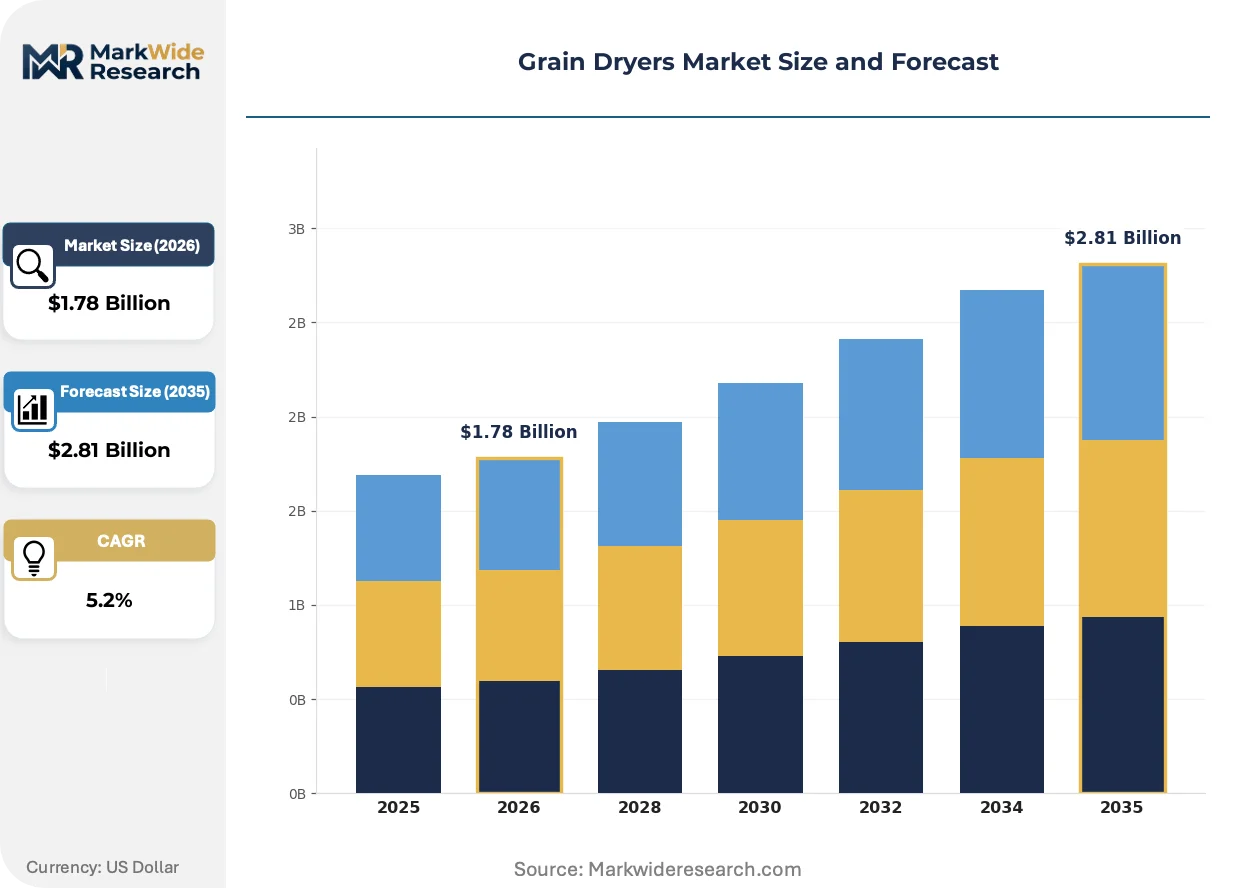
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.81 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Batch Type, Mobile Dryers, Hybrid Dryers Application: Corn, Wheat, Soybeans, Barley End User: Agricultural Cooperatives, Farmers, Grain Merchandisers, Storage Facilities Technology: Heat Pump, Direct Fire, Indirect Fire, Infrared |
| Companies Covered | Cimbria, Brock Grain Systems, GSI Group, Jiangsu Liyang Morning Machinery, Zhengzhou Sanzhong Machinery, Buhler Group, Alvan Blanch, Kasten Manufacturing, Sukup Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Dryers Market Emerging Trajectories
Heat pump drying architecture is consolidating market position as regulatory pressure compounds energy cost differentials, while digital process control and service model unbundling reshape how buyers access drying capacity.
Heat pump grain dryers are consolidating their position in commercial elevator installations by delivering thermal efficiency gains of forty to sixty percent versus conventional direct-fire units. Agricultural cooperatives in Denmark and the Netherlands are adopting these systems most aggressively due to carbon pricing and natural gas supply constraints. This technology is consolidating the competitive landscape by favoring suppliers with refrigeration engineering capabilities over traditional combustion equipment manufacturers.
The EU F-Gas Regulation is progressively constraining refrigerant selection for heat pump dryer designs, forcing manufacturers toward lower-global-warming-potential alternatives with higher material costs. This regulatory pressure is accelerating R&D investment in CO2 transcritical cycles and hydrocarbon refrigerant architectures. German and French equipment suppliers are responding fastest, leveraging existing industrial refrigeration expertise to maintain market access.
Service unbundling is fragmenting traditional equipment procurement patterns as rental and pay-per-dried-bushel models gain traction among seasonal operators. Custom harvest businesses across the US High Plains are displacing capital purchase with short-term equipment access, compressing manufacturer direct sales cycles. This shift is most visible in Nebraska and South Dakota, where harvest timing volatility makes fixed asset ownership economically unattractive for mid-scale grain handlers.
Grain Dryers Market Segmentation

Grain dryer procurement varies sharply by operational scale, crop type, and thermal technology preference. Buyers select systems based on throughput requirements, energy infrastructure access, and regulatory exposure rather than price alone.
Product Type:
Volume throughput and capital commitment separate buyers across these equipment architectures.
- Continuous Flow:These systems process grain through vertical or horizontal columns with concurrent airflow and grain movement, enabling elevator-scale throughput exceeding thousands of bushels per hour. Commercial operators across Iowa and Illinois favor continuous flow installations where harvest windows compress drying schedules and labor availability constrains batch handling.
- Batch Type:Stationary units dry discrete grain quantities in cycles, offering operational flexibility for mid-size farms with variable harvest timing. Farmers in Nebraska and Kansas retain strong preference for batch systems where crop diversity and storage fragmentation make continuous flow economics unworkable.
- Mobile Dryers:Portable units mounted on trailers serve custom harvest operators and rental services across the Dakotas.
- Hybrid Dryers:Dual-mode systems combine batch flexibility with continuous flow efficiency for cooperative operations.
Continuous Flow leads volumes today; Mobile Dryers are gaining share fastest.
Application:
Crop moisture profiles and commodity pricing drive divergent equipment specifications.
- Corn:High initial moisture content at harvest—often exceeding 25 percent—demands aggressive drying capacity with sustained high-temperature operation. The US Corn Belt generates concentrated demand where cooperative elevators scale continuous flow infrastructure to manage 13-billion-bushel annual production.
- Wheat:Lower harvest moisture and temperature sensitivity require gentler drying curves to preserve germination and milling quality. Canadian Prairie operators and Kansas handlers specify lower maximum temperatures, favoring heat pump and indirect fire technologies where protein integrity commands price premiums.
- Soybeans:Oilseed processors prioritize moisture uniformity to prevent storage spoilage and maintain crush margins.
- Barley:Maltsters enforce strict moisture specifications for brewing quality, driving precision control adoption.
Corn dominates installed capacity; Wheat applications are climbing the fastest.
End User:
Capital structure and harvest risk allocation determine procurement patterns.
- Agricultural Cooperatives:Member-owned elevators aggregate drying demand across hundreds of farms, justifying fleet-scale continuous flow investments. Iowa and Illinois cooperatives are expanding storage-drying complexes where USDA loan programs reduce capital barriers.
- Farmers:On-farm installations range from small batch units to substantial tower dryers, with selection hinging on trucking distance to commercial elevators and crop insurance structures. Minnesota and Wisconsin farmers are converting to electric and heat pump systems where state renewable incentives offset higher first costs.
- Grain Merchandisers:Independent traders prioritize throughput flexibility and quality preservation for export contracts.
- Storage Facilities:Dedicated warehousing operators focus on moisture management as a value-added service.
Agricultural Cooperatives lead volumes today; Farmers are expanding most quickly.
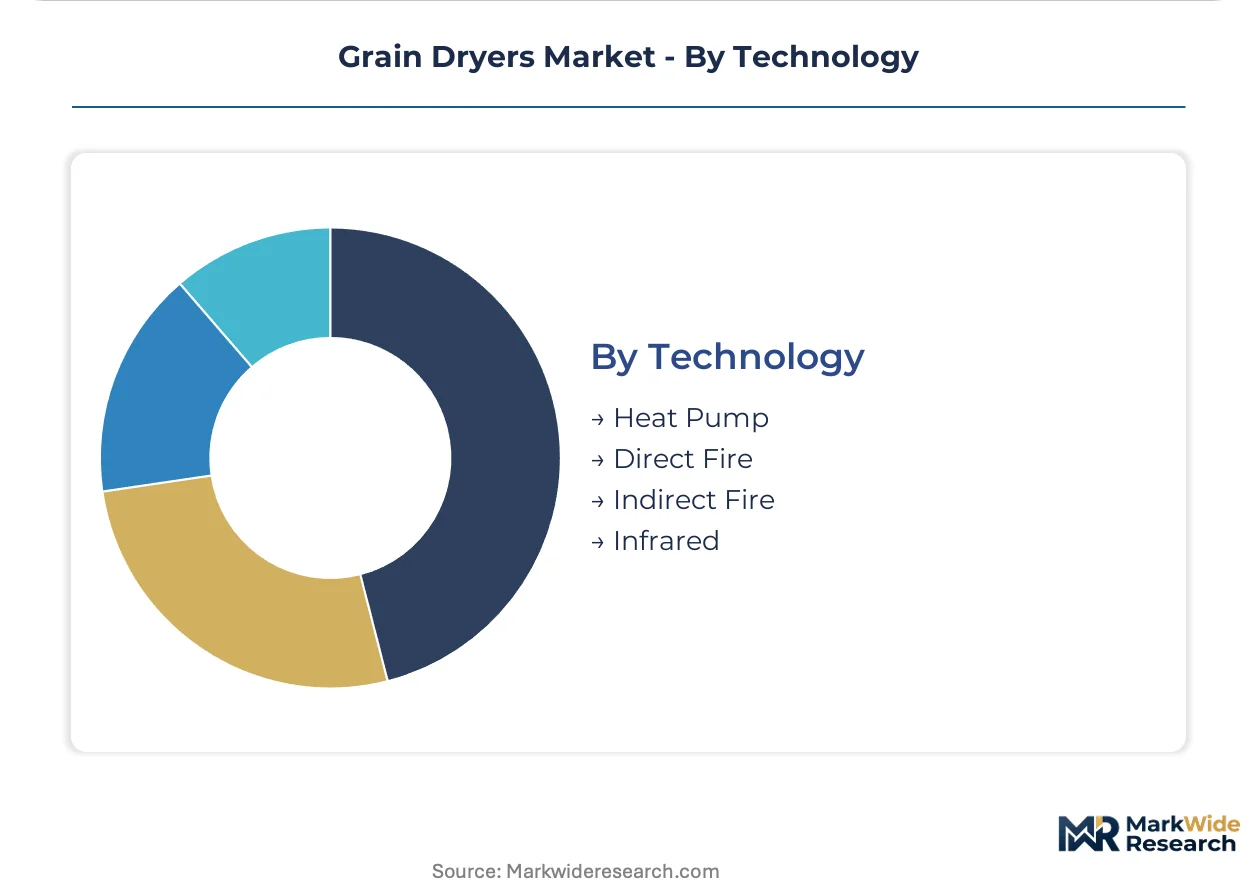
Technology:
Energy cost trajectories and emissions compliance reshape thermal system selection.
- Heat Pump:Refrigeration-based systems extract ambient thermal energy, delivering 40-60 percent efficiency gains over combustion alternatives. Danish and Dutch cooperatives are deploying heat pumps aggressively where EU carbon pricing and natural gas constraints compound economic advantage.
- Direct Fire:Natural gas or propane burners heat drying air directly, maintaining lowest capital cost but highest emissions exposure. EPA Clean Air Act thresholds are forcing burner redesigns across US Plains installations where legacy infrastructure creates replacement inertia.
- Indirect Fire:Heat exchangers separate combustion gases from drying air, enabling low-NOx compliance without full heat pump conversion cost.
- Infrared:Electromagnetic radiation systems offer precise moisture targeting for specialty grain applications.
Direct Fire leads volumes today; Heat Pump is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France deploys heat pump dryers aggressively where carbon pricing bites hardest, while the United States clings to direct-fire infrastructure despite EPA pressure. Brazil scales mobile rental fleets to serve fragmented soybean operations. This divergence shapes equipment procurement across major grain-producing economies.
United States
Corn Belt cooperatives in Iowa and Illinois drive continuous flow system procurement as harvest windows compress drying schedules. EPA Clean Air Act thresholds force low-NOx burner redesigns across Plains installations where legacy natural gas infrastructure creates replacement inertia. Minneapolis-St. Paul anchors heat pump adoption where Minnesota renewable energy incentives offset higher capital costs.
Germany
Grain handlers in Lower Saxony and Bavaria pre-emptively upgrade drying assets to avoid EU carbon border adjustment exposure on export shipments. F-Gas Regulation constrains refrigerant selection, accelerating R&D investment in CO2 transcritical cycles among industrial refrigeration specialists. Hamburg port elevators concentrate heat pump deployment where natural gas supply constraints compound economic advantage.
France
Export-oriented cooperatives in Île-de-France and Hauts-de-France prioritize moisture management upgrades to preserve commodity shipment access. EU REACH compliance adds cost but creates technical barriers for non-European suppliers seeking market entry. Lille and Paris basin storage facilities anchor precision control adoption where maltsters enforce strict brewing-quality specifications.
Brazil
Soybean belt operators in Mato Grosso and Rio Grande do Sul expand mobile dryer rental services to bypass fixed capital requirements amid harvest timing volatility. The country's national agricultural regulator enforces moisture uniformity standards for oilseed export contracts. São Paulo-based merchandisers drive throughput flexibility investments where crush margins depend on spoilage prevention.
Canada
Prairie wheat handlers in Saskatchewan and Manitoba specify gentler drying curves to preserve germination and milling quality for protein premiums. Health Canada and PMRA coordinate emissions and pesticide residue standards affecting dryer fuel selection. Winnipeg and Regina anchor indirect fire adoption where temperature sensitivity commands equipment specification discipline.
Grain Dryers Market Vendor Landscape
North American producers anchor one tier; European specialists hold process control and heat pump integration advantages. The vendor base separates into consolidated full-system suppliers, component fabricators, and emerging mobile rental service operators. Three archetypes dominate: integrated storage-handling portfolios, advanced automation platforms, and seasonal fleet operators. Competitive dynamics center on geographic expansion into Corn Belt cooperative procurement and technology licensing for refrigerant-compliant heat pump architectures.
Among European industrial equipment conglomerates, Buhler Group and Cimbria occupy positions emphasizing process control integration and turnkey system delivery. Sukup Manufacturing and Brock Grain Systems exemplify North American fabrication scale serving elevator and on-farm segments. Jiangsu Liyang Morning Machinery represents Chinese equipment cost positioning for emerging market volume procurement.
| Leading Market Players |
|---|
| Cimbria |
| Brock Grain Systems |
| GSI Group |
| Jiangsu Liyang Morning Machinery |
| Zhengzhou Sanzhong Machinery |
| Buhler Group |
| Alvan Blanch |
| Kasten Manufacturing |
| Sukup Manufacturing |
| Others |
Supply Flow & Price Mechanics
Stainless steel and aluminum sheet metal move from Chinese and German foundries through fabrication tiers to arrive at three distinct price levels: premium heat pump systems for Danish cooperatives, mid-range continuous flow units for Iowa elevators, and economy batch dryers for Kansas mid-size farms. Input volatility in these metals compresses margins unevenly, forcing manufacturers to push cost absorption differentially across buyer segments based on contract structure and switching costs.
Pricing Analysis
Capacity additions in Nebraska and South Dakota are reshaping price floors for mobile dryer rentals as seasonal fleet operators compete for custom harvest contracts. Three-tier pricing structure across premium, standard, and economy levels separates heat pump systems with process control integration from direct-fire units with basic automation and stripped-down batch configurations. Price differentiation hinges on energy efficiency certification tiers and geographic delivery distance from manufacturing clusters in Iowa and Illinois. Cost compression in the economy tier is intensifying because Chinese equipment imports pressure domestic fabricators on small-farm procurement. Agricultural cooperatives show lowest price sensitivity due to USDA loan program availability, while independent mid-size farmers in the Dakotas face acute capital constraints.
Supply Chain Analysis
Refrigerant supply rests on Chinese and German specialty chemical producers who control heat pump dryer compressor chemistries under EU F-Gas Regulation constraints. Dryer fabrication draws from stainless steel mills in China, aluminum extrusion in Germany, and combustion components from US Midwest machine shops. Single-source vulnerability concentrates in refrigerant precursors where REACH compliance creates import barriers for non-European suppliers. Distribution runs through manufacturer-direct sales teams for large cooperative installations, independent dealers for on-farm equipment, and emerging rental fleet operators for seasonal mobile access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grain dryers market represents a late-cycle quality story where EU carbon border adjustments and EPA emissions thresholds redirect procurement toward premium heat pump specifications with integrated process control. Buyers now prioritize total cost of ownership over first cost, compressing legacy direct-fire margins while elevating technology-integrated suppliers.
For Market Incumbents: Anticipate refrigerant compliance cost escalation under EU F-Gas Regulation by accelerating CO2 transcritical cycle R&D partnerships with German industrial refrigeration specialists. Defend position against emerging mobile rental fleet operators by embedding predictive maintenance software that locks cooperative buyers into service contracts. Vertical integration into compressor manufacturing offers margin protection where refrigerant supply concentrates in China and Germany. For New Entrants and Emerging Players: EPA Clean Air Act thresholds in the United States open a window for low-NOx burner specialists to displace legacy direct-fire installations across Plains states where replacement inertia delays full heat pump conversion. Target Nebraska and South Dakota mobile dryer rentals where harvest timing volatility makes fixed asset ownership uneconomical for mid-scale grain handlers. Pursue pay-per-dried-bushel service models that bypass capital purchase barriers among price-sensitive farmers. For Investors and Strategic Acquirers: Consolidation pressure builds where heat pump technology maturation favors suppliers with refrigeration engineering capabilities over traditional combustion equipment manufacturers. Focus acquisition screening on mid-cap European process control specialists with EU F-Gas Regulation-compliant refrigerant architectures and established Danish or Dutch cooperative reference sites. Watch Minnesota and Wisconsin state renewable energy incentive program expansions as inflection indicators for electric dryer conversion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Licensing | EU F-Gas Regulation compliance unlocks market access for refrigeration-capable suppliers in Denmark and Germany. |
| Mobile Fleet Expansion | Nebraska and South Dakota rental operators capture seasonal demand without fixed capital commitment from farmers. |
| Process Control Integration | IoT-enabled moisture optimization commands premium pricing from Iowa and Illinois cooperative buyers. |
| Refrigerant Supply Agreement | Long-term contracts with Chinese and German chemical producers secure heat pump production continuity. |
| Aftermarket Service Unbundling | Predictive maintenance subscriptions lock in recurring revenue from elevator-scale continuous flow installations. |
Methodological Framework
Direct dialogue with grain elevator operations managers, agricultural cooperative procurement directors, dryer manufacturer sales engineers, and EPA regional compliance officers anchored qualitative findings, cross-checked against USDA grain storage statistics, EIA energy consumption data for agricultural processing, EU ETS carbon price series, and SEC filings from listed industrial equipment conglomerates. Bottom-up equipment shipment tallies by state and crop type converged with top-down macroeconomic drivers across the analysis window.
Segment-level projections emerged from modeling continuous flow, batch, mobile, and hybrid dryer architectures against corn, wheat, soybean, and barley application demand, with technology splits between heat pump, direct fire, indirect fire, and infrared systems. CAGRs were derived from regression analysis of historical installation rates against regulatory phase-in schedules and energy price trajectories. Forecast inputs incorporated EPA Clean Air Act enforcement intensity variation by region and EU carbon border adjustment implementation timing.
Revisions become necessary when refrigerant supply disruptions, stainless steel tariff escalations, or state-level renewable incentive program cancellations materialize beyond baseline assumptions. Forecasts reflect documented driver sensitivities without claiming predictive certainty. A small set of named triggers—EPA enforcement acceleration, EU F-Gas Regulation expansion, and Corn Belt cooperative consolidation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Uganda Grains Market
Grains
Rolled Oats Market
Grains
Green Pea Grits Market
Grains
Precooked Flour Market
Grains
Grain and Cereal Crop Market
Grains
Asia Pacific Wheat Protein Market
Grains
Global Rice Market
Grains
Fortified Rice Market
Grains
Spelt Wheat Market
Grains
North America Oats Market
Grains
Tunisia Grain Market
Grains
Organic Cereals Market
Grains
Quinoa Flour Market
Grains
India Rice Market
Grains
United States Gluten-Free Oats Market
Grains
South American Maize Market