
 Uganda Grains Market | 2026-2036
Uganda Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Uganda Grains Market Analytics
The gap between premium packaged grains and loose commodity supplies is broadening across Ugandan wholesale channels. Bakhresa Grain Milling Uganda Ltd leverages its integrated milling network to dominate urban flour distribution. Afgri Uganda anchors its position through backward integration into grain sourcing from cooperative networks. Kasawo Grain Millers Ltd differentiates by specializing in regional maize varieties tailored to local taste preferences.
Uganda grains encompass cereal crops cultivated across diverse agro-ecological zones, typically harvested at moisture contents below 14 percent for safe storage, then milled or processed into flour, grits, and feed inputs for human and animal consumption. Maize leads volume throughput as the staple crop for household consumption and industrial milling, while rice commands premium positioning through imports and domestic cultivation expansion in eastern wetland districts. The bakery end-use segment draws concentrated investment in fortified flour processing, whereas animal feed applications sustain steady offtake from commercial poultry operations around Kampala and Jinja.
The Uganda National Bureau of Standards enforces grain quality specifications that shape milling eligibility and export access, while the Ministry of Agriculture's crop protection regulations govern pesticide residue thresholds for domestic and cross-border trade. Compliance with East African Community harmonized standards determines regional market participation for Ugandan millers and traders. Stakeholders must monitor evolving seed certification requirements and regional tariff adjustments to secure supply chain positioning.
Market Dynamics
Urbanization around Kampala and Entebbe is compressing grain supply chains toward centralized milling infrastructure, while the Uganda National Bureau of Standards tightens quality specifications that filter informal traders from formal channels.
Growth Catalysts
- Fortification mandates:The Ministry of Health's maize flour fortification requirements are pulling investment into micronutrient premix capacity at industrial mills serving the bakery sector.
- Improved seed distribution:Uganda's National Agricultural Research Organisation certified varieties are expanding yield stability across the Central and Eastern regions, reducing production volatility for contract suppliers.
- East African Community harmonization:Cross-border standard alignment is enabling Ugandan millers to access Kenyan and Tanzanian retail channels without duplicate certification costs.
Market Restraints
- Input cost volatility:Fertilizer import dependence exposes producers to shilling-dollar exchange rate swings and global urea price spikes.
- Supply concentration risk:Kampala-centered milling capacity creates single-point vulnerability for national flour distribution during transport disruptions.
- Technical limitation:Aflatoxin detection infrastructure gaps at primary collection points allow contaminated lots to enter processing streams.
Strategic Opportunities
- Eastern wetland rice expansion:Irrigation development in Butaleja and Kibuku districts offers import substitution potential for premium rice demand in urban hotels and restaurants.
- Cold storage channel innovation:Solar-powered decentralized silos in the Northern Region could capture post-harvest losses currently exceeding safe moisture thresholds.
- Regional tariff tailwind:East African Community duty remission schemes for value-added grain products incentivize export-oriented milling capacity expansion.
Industry Challenges
- Certification timeline compression:Uganda National Bureau of Standards laboratory backlogs delay organic and fortified product approvals, freezing new product launches for six to nine months.
- Integration complexity with legacy systems:Cooperative aggregation networks lack digital traceability infrastructure required by supermarket chains and export buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uganda Grains Market |
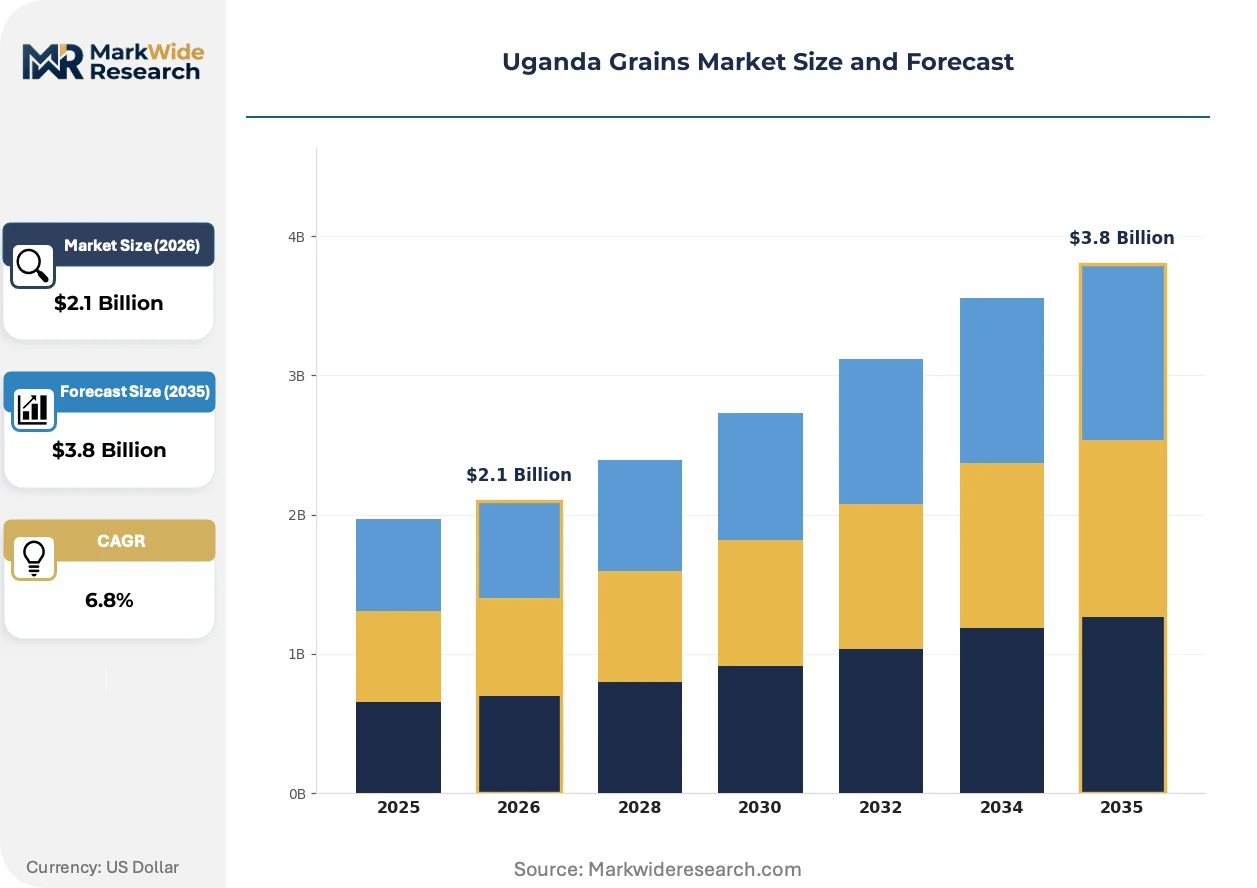
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maize, Sorghum, Millet, Rice Packaging Type: Bags, Bulk, Boxes, Roll Stocks End Use Industry: Bakery, Confectionery, Snacks, Animal Feed Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | Afgri Uganda, Afro Kai Limited, Agahikaine Grains, Agroways Limited, Arise and Shine Maize Millers Ltd, Bakhresa Grain Milling Uganda Ltd, Kibimba Rice, Tilda Uganda, Kasawo Grain Millers Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uganda Grains Market Evolving Landscape
Grain handling technology in Uganda is pivoting toward moisture-controlled storage and rapid testing equipment that reduces post-harvest losses and quality disputes between farmers and millers.
Mobile solar dryers equipped with digital humidity sensors are modularizing on-farm grain conditioning, allowing smallholders in Masaka and Mbarara to meet miller moisture specifications without transporting wet grain to centralized facilities. Commercial poultry operations around Jinja are adopting these units fastest, cutting rejection rates at intake points. The technology is compressing the traditional two-week field-drying window into forty-eight-hour cycles, reducing aflatoxin risk and enabling just-in-time delivery contracts.
Uganda National Bureau of Standards enforcement of East African Community grain aflatoxin limits is disqualifying informal traders from supermarket supply chains, redirecting volume toward certified millers with in-house testing laboratories. The regulation is fragmenting procurement patterns, as bakeries and feed manufacturers now require batch certificates for every delivery. Central Region industrial users are responding by consolidating supplier lists to five or fewer certified sources, accelerating cooperative formalization in source districts.
Supermarket expansion in Kampala and Entebbe is shortening grain product switching cycles, as shelf-space competition forces packagers to refresh branding and fortification claims every eighteen months. Traditional loose-grain retailers in Nakasero and Kikuubo markets are losing bakery-sector customers to pre-packaged alternatives with visible Uganda National Bureau of Standards marks. The shift is most pronounced among middle-income households in the Central Region, where cold-chain bread distribution has created packaged-ingredient preference lock-in.
Uganda Grains Market Segmentation
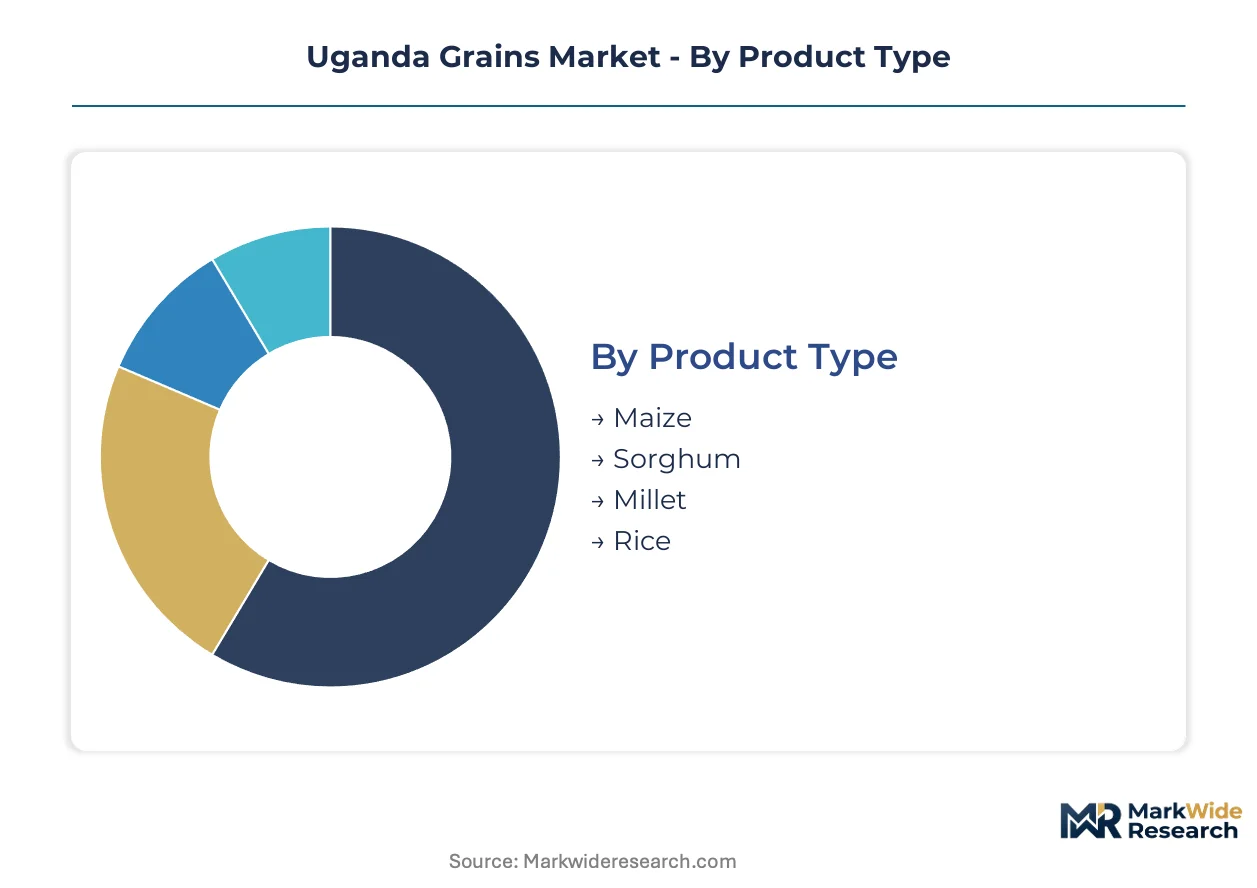
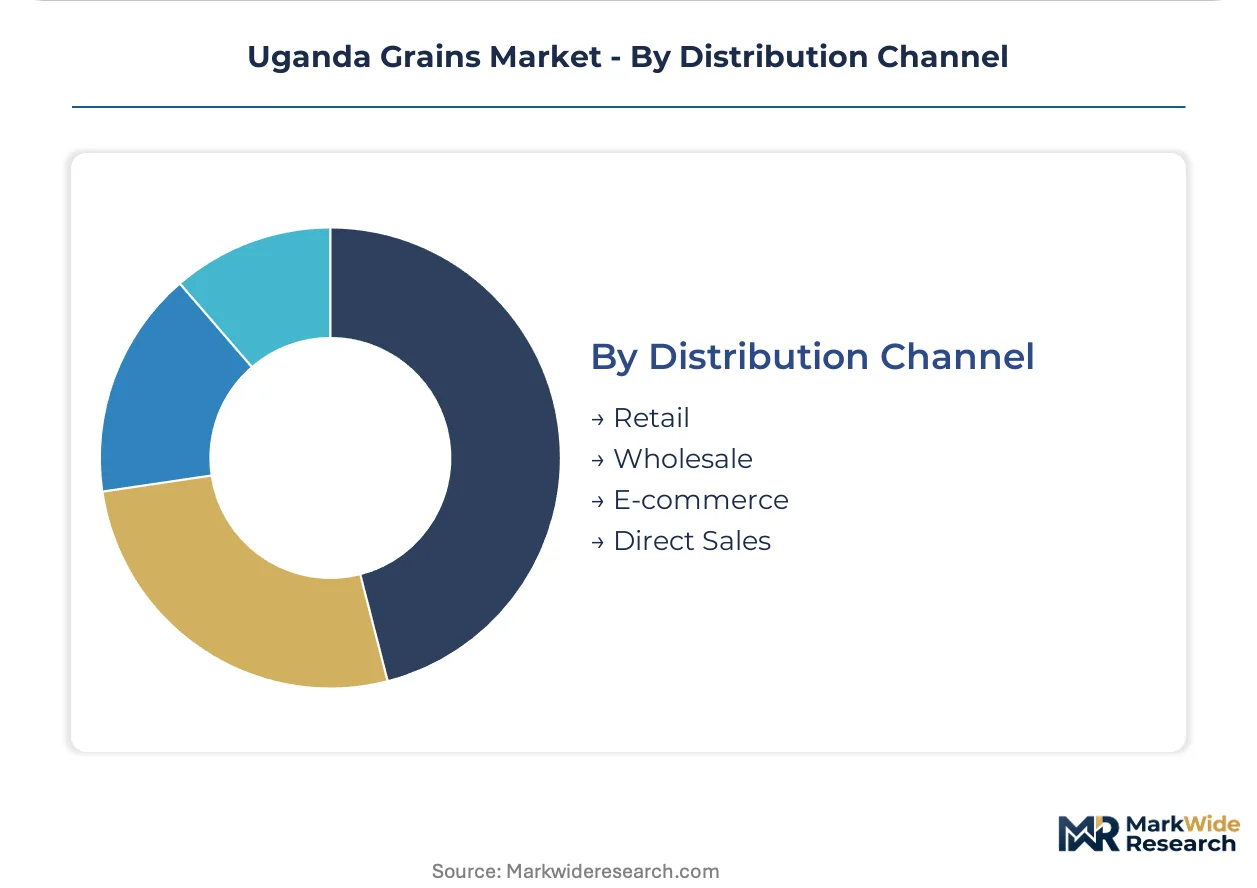
Grain segmentation in Uganda determines milling eligibility, storage protocols, and channel access. Product type dictates moisture specifications and fortification requirements. Packaging and distribution choices filter which suppliers reach formal retail versus informal markets.
Product Type:
Upgrade cycles in Ugandan grain production center on yield stability and post-harvest loss reduction, with farmers replacing traditional varieties every three to four seasons.
- Maize:Uganda's dominant staple, harvested at 12-14% moisture for safe storage and processed into fortified flour for household consumption and industrial baking. Demand concentrates in Kampala's bakery sector, where Uganda National Bureau of Standards fortification mandates pull volume toward certified millers with premix capacity.
- Rice:Cultivated in eastern wetland districts including Butaleja and Kibuku, commanding premium positioning through domestic expansion and limited imports for urban hotels and restaurants. Uganda's National Agricultural Research Organisation certified varieties are displacing informal seed sources, tightening quality consistency for export-oriented milling.
- Sorghum:Drought-tolerant cereal sustaining household consumption in northern and eastern agro-ecological zones with erratic rainfall patterns.
- Millet:Traditional smallholder crop processed into flour for porridge and brewing applications, retaining regional preference lock-in despite lower commercial throughput.
Maize sits at the top of the volume ranking, with rice climbing the fastest.
Packaging Type:
Cost tier segmentation separates commodity handlers from premium channel suppliers, with packaging investment determining supermarket shelf eligibility.
- Bags:Polypropylene and woven sacks dominate formal procurement, enabling Uganda National Bureau of Standards mark visibility and traceability batch codes required by bakery and feed manufacturers. Central Region industrial users now mandate bagged delivery with moisture certification, filtering informal traders from approved supplier lists.
- Bulk:Loose grain movement persists in cooperative aggregation and primary collection, though aflatoxin detection gaps at intake points create compliance risk for millers sourcing from uncertified networks.
- Boxes:Corrugated packaging for specialty rice and premium maize grits targeting hotel and restaurant segments in Kampala and Entebbe.
- Roll Stocks:Flexible film for automated packing lines at integrated milling facilities serving supermarket private label programs.
Bags capture the largest procurement volume, with boxes expanding most quickly in premium channels.
End Use Industry:
Application-based segmentation reveals diverging quality specifications, with fortification mandates creating irreversible technical barriers between food-grade and feed-grade supply chains.
- Bakery:Industrial bread and confectionery production drives demand for refined, fortified wheat and maize flour with specified protein and ash content. Ministry of Health mandates pull investment into micronutrient premix capacity at Kampala-centered mills.
- Animal Feed:Commercial poultry operations around Jinja sustain steady offtake for maize bran and broken rice, with mobile solar dryers reducing rejection rates at intake points through rapid moisture conditioning.
- Confectionery:Specialized starch and grit requirements for snack manufacturing, with quality certification determining miller eligibility.
- Snacks:Extruded and fried product applications sourcing specific grain size fractions from regional millers.
Bakery commands the highest quality premium, with animal feed gaining share fastest through poultry sector expansion.
Distribution Channel:
Geographic concentration of milling capacity shapes channel viability, with Kampala-centered infrastructure compressing supply chain options for northern and western producers.
- Wholesale:Dominant channel for industrial millers and feed manufacturers, consolidating volume through certified cooperative networks and traceable aggregation points. East African Community harmonized standards enable cross-border shipment to Kenyan and Tanzanian buyers without duplicate certification.
- Retail:Supermarket expansion in Kampala and Entebbe accelerates packaged grain switching cycles, with shelf-space competition forcing eighteen-month branding refresh cycles and visible Uganda National Bureau of Standards mark requirements.
- Direct Sales:Contract arrangements between large millers and bakery or feed operations, bypassing intermediary margins through captive supply relationships.
- E-commerce:Emerging channel for urban middle-income households, though cold-chain bread distribution has already locked in packaged-ingredient preferences that favor established retail networks.
Wholesale retains the deepest volume penetration, with retail expanding most quickly through supermarket format growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled agricultural labor concentrates in Uganda's Central Region, where urban milling operations draw technical talent from surrounding districts and anchor the nation's grain processing capacity.
Central Region
Kampala's bakery sector and Entebbe's cold storage infrastructure drive demand for refined maize and wheat flour. Uganda National Bureau of Standards fortification mandates filter informal traders from formal supply channels. Industrial milling clusters in Kampala and Jinja compress supply chains toward centralized infrastructure.
Eastern Region
Wetland rice cultivation in Butaleja and Kibuku districts expands domestic production for urban hotel and restaurant segments. Uganda's National Agricultural Research Organisation certified varieties displace informal seed sources. Mobile solar dryers equipped with digital humidity sensors reduce post-harvest losses in Masaka proximity zones.
Northern Region
Erratic rainfall patterns sustain sorghum as a drought-tolerant household staple. Post-harvest losses exceed safe moisture thresholds due to limited cold storage infrastructure. Solar-powered decentralized silos offer channel innovation potential for cooperative aggregation networks.
Western Region
Regional maize varieties tailored to local taste preferences support differentiated milling operations. Cooperative formalization accelerates as bakeries consolidate supplier lists to certified sources. Primary collection points face aflatoxin detection infrastructure gaps that create compliance risk.
Uganda Grains Market Competitive Landscape
Capital-heavy integrated millers compete with asset-light regional specialists across Uganda's grain supply chain. The market structure fragments across three tiers: multinational milling networks with backward integration into cooperative sourcing, mid-scale regional processors specializing in local variety adaptation, and informal traders losing share to certified channels under tightening quality enforcement. Strategic archetypes include integrated premix fortifiers, cooperative-anchored aggregators, and mobile solar dryer operators. Competitive dynamics center on certification compliance acceleration and captive supply relationships with bakery and poultry operations.
Among integrated milling specialists, Bakhresa Grain Milling Uganda Ltd exemplifies the capital-intensive tier with urban distribution dominance, while Afgri Uganda occupies a position anchored through cooperative network integration. Kasawo Grain Millers Ltd represents the regional specialization archetype, with positioning derived from local variety expertise. These three patterns illustrate how compliance capability and sourcing control separate formal channel participants from disqualifying informal competitors.
| Leading Market Players |
|---|
| Afgri Uganda |
| Afro Kai Limited |
| Agahikaine Grains |
| Agroways Limited |
| Arise and Shine Maize Millers Ltd |
| Bakhresa Grain Milling Uganda Ltd |
| Kibimba Rice |
| Tilda Uganda |
| Kasawo Grain Millers Ltd |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between Uganda National Bureau of Standards-compliant millers and informal traders manifests in parallel pricing ladders and supply chain access tiers. Premium channels demand batch-certified deliveries with visible moisture documentation, while commodity flows persist through cooperative aggregation with higher rejection risk at intake points.
Pricing Analysis
Packaged-versus-loose grain service unbundling separates formal supermarket channels from traditional wholesale. Three-tier pricing structure across premium, standard, and economy levels reflects fortification investment, brand visibility, and traceability batch codes. Cost compression in commodity maize intensifies because fertilizer import dependence exposes producers to shilling-dollar volatility. Bakery operations show least price sensitivity due to Ministry of Health mandate compliance requirements, while household consumers in informal markets remain most responsive to spot-price movements.
Supply Chain Analysis
Fertilizer supply rests on import flows through Kenyan and Tanzanian ports, with urea and NPK blends arriving via Mombasa and Dar es Salaam corridors. Seed genetics draw from Uganda's National Agricultural Research Organisation certified varieties, while premix micronutrients for fortification feed from South African and Kenyan suppliers. Single-source vulnerability concentrates at Kampala-centered milling infrastructure, where transport disruptions freeze national flour distribution. Distribution runs through certified cooperative networks for industrial offtake, with direct contract arrangements bypassing intermediary margins for large bakery and poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uganda's grains sector functions as a regulatory compounder, with Uganda National Bureau of Standards fortification mandates and East African Community harmonization protocols continuously upgrading compliance thresholds and locking in formal channel expansion.
For Market Incumbents: Anchor market position through backward integration into cooperative sourcing networks and accelerated certification laboratory investment. Threat from mobile solar dryer operators enabling smallholder quality compliance demands preemptive supplier list consolidation. Priority lever sits with captive supply relationships with Jinja poultry operations and Kampala bakery chains. For New Entrants and Emerging Players: Begin with solar-powered decentralized silo deployment in Northern Region post-harvest loss zones, where moisture threshold failures currently exclude cooperative volume from formal channels. Most penetrable segment lies with regional rice milling for Butaleja and Kibuku wetland expansion. Go-to-market angle centers on Uganda National Bureau of Standards batch certification as supermarket shelf eligibility threshold. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative aggregation networks lack digital traceability infrastructure required by export buyers and supermarket chains. Long-term viability favors millers with integrated premix fortification capacity and cross-border East African Community certification. Acquisition target archetype includes regional specialists with local variety expertise and latent cooperative relationships. Signal to watch is Uganda National Bureau of Standards laboratory backlog resolution timelines, which currently freeze new product launches for extended periods.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Sourcing | Captures supply security and Uganda National Bureau of Standards traceability compliance for formal channel access. |
| Mobile Solar Dryer Network Deployment | Compresses post-harvest conditioning cycles and reduces aflatoxin risk for just-in-time delivery contracts. |
| Premix Fortification Capacity Expansion | Meets Ministry of Health mandates and locks in bakery sector offtake with micronutrient batch certification. |
| East African Community Cross-Border Certification | Enables Kenyan and Tanzanian retail channel access without duplicate compliance cost burden. |
| Digital Traceability Infrastructure Investment | Closes supermarket and export buyer eligibility gap for cooperative-anchored aggregation networks. |
Research Methodology
Multiple input streams — miller procurement managers, cooperative aggregation officers, Uganda National Bureau of Standards certification leads, and bakery sector quality directors — were reconciled against trade flow databases, agricultural ministry crop reports, and East African Community tariff schedules. Bottom-up volume estimates from district-level production data and top-down demand calibration from industrial offtake records were cross-validated through structured primary interviews and secondary source triangulation.
Historical shipment patterns were cross-referenced against expert panel assessments of seed variety adoption curves and fortification mandate implementation timelines. Segmentation modeling spanned product type, packaging format, end-use application, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts, with specific inputs including Uganda's National Agricultural Research Organisation yield improvement trajectories and cold storage infrastructure buildout rates.
Several conditions sit outside the modeled scope, including extreme weather events affecting harvest moisture content, currency devaluation spikes beyond historical bands, and abrupt East African Community tariff reconfigurations. Forecasts reflect documented assumptions about cooperative formalization pace and laboratory certification throughput. A small set of named triggers warrants ongoing watch: fertilizer import cost volatility, aflatoxin detection infrastructure deployment, and regional harmonization protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Ancient Grain Market
Grains
Asia-Pacific Rice Market
Grains
Grain Storage Silos Market
Grains
Brown Rice Market
Grains
Green Pea Grits Market
Grains
Africa Maize Market
Grains
Ancient and Specialty Grain Flour Market
Grains
North America Rice Market
Grains
Wild Rice Market
Grains
Europe Wheat Market
Grains
Organic Oats Market
Grains
00 Flour Market
Grains
Corn Market
Grains
North America Oats Market
Grains
Global Flour Market
Grains
Non-Basmati Rice Market