
 Soya Flour Market | 2026-2036
Soya Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Soya Flour Market Analysis
EU Green Deal sustainability mandates are repositioning soya flour processors toward lower-carbon sourcing benchmarks. Archer Daniels Midland Company leverages its North American crush capacity to secure defatted soya flour supply chains. Cargill, Incorporated anchors its position through direct farmer partnerships across the Brazilian Cerrado. CHS Inc. competes via cooperative ownership structures that control grain origination in the upper Midwest.
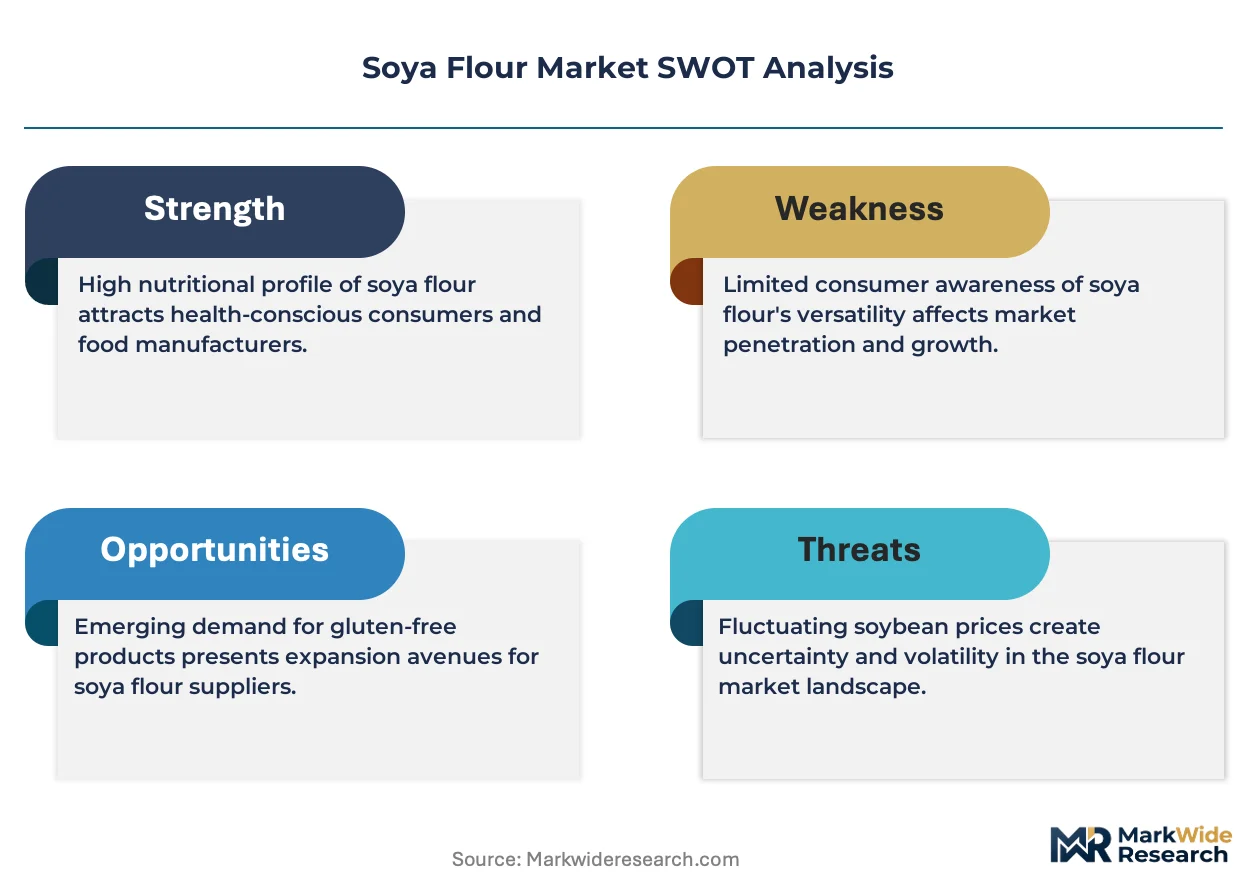
Soya flour consists of finely ground soybean meal containing 40-50% protein by weight, produced through either solvent extraction or mechanical pressing of oilseeds before thermal treatment and milling. It functions primarily as an emulsifier, moisture binder, and protein fortifier in commercial food manufacturing. Defatted soya flour dominates volume due to its extended shelf stability and neutral flavor profile in baked goods applications. Full-fat soya flour is gaining traction within meat alternatives as brands seek cleaner-label fat sources that improve mouthfeel without hydrogenated oils.
FDA allergen labeling rules, USDA organic certification standards, and EU REACH chemical compliance frameworks collectively elevate testing and documentation costs for cross-border soya flour trade. Brazil's national agricultural regulator enforces genetically modified organism traceability requirements that affect export eligibility to European destinations. Stakeholders must monitor evolving deforestation-linked due diligence laws in the European Union and emerging carbon border adjustments that could restructure South American crushing economics.
Market Dynamics
Plant-based meat alternatives are compressing supply chains toward higher-protein soya flour grades, forcing processors to reconfigure extraction lines for defatted varieties that bind moisture without hydrogenated oils.
Growth Catalysts
- EU Green Deal sustainability mandates:Lower-carbon sourcing benchmarks are redirecting procurement toward certified deforestation-free Brazilian and North American supply chains.
- Mechanical pressing technology:Cold-press extraction preserves protein integrity for meat alternative applications, displacing solvent-based methods in premium segments.
- China's food fortification policies:School nutrition programs and bakery standards are embedding soya flour as a mandatory protein additive in institutional procurement.
Market Restraints
- Soybean price volatility:Weather-driven yield fluctuations in Brazil's Cerrado and US Midwest crush margins unpredictably.
- EU REACH chemical compliance:Residue testing and documentation burdens slow cross-border shipments, elevating working capital requirements.
- Pulse protein substitution:Pea and fava concentrates are capturing clean-label positioning in European meat alternatives, constraining soya flour premiumization.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation rewards South American processors with verified low-emission crushing, creating first-mover certification advantages.
- Fermented soya flour:Controlled fermentation reduces beany off-flavors, opening beverage and infant nutrition applications previously closed to conventional grades.
- Direct-to-bakery distribution:Bypassing traditional ingredient distributors via regional milling partnerships captures margin and formulation collaboration rights.
Industry Challenges
- Allergen control protocols:FDA labeling rules require segregated production lines, complicating multi-product facility economics.
- Organic certification timelines:Three-year transition periods for non-GMO acreage lock up land commitments before premium pricing materializes.
- IP fragmentation in enzyme-assisted extraction:Patent thickets around novel protease applications delay process innovation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soya Flour Market |
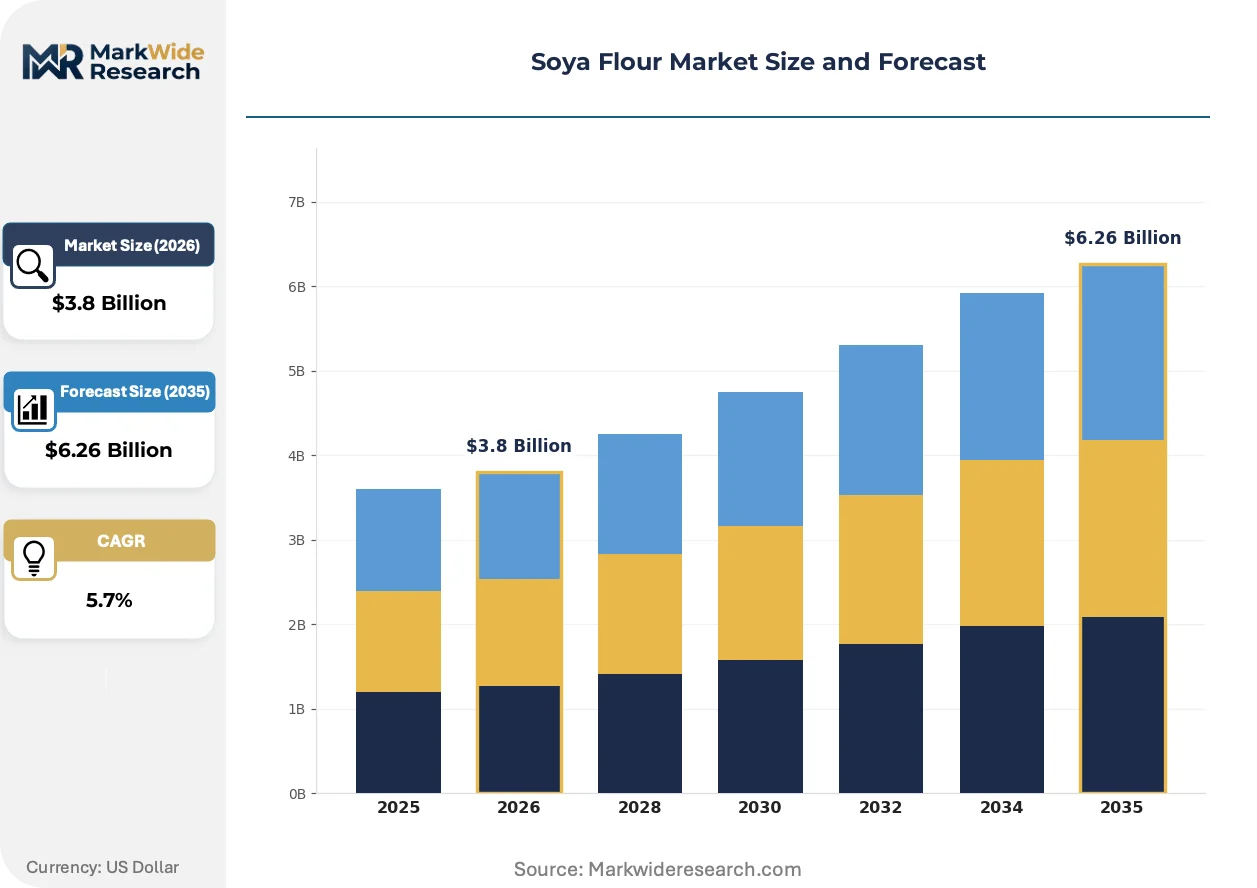
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defatted Soya Flour, Full-Fat Soya Flour, Instant Soya Flour, Soya Protein Concentrate Application: Baked Goods, Snacks, Meat Alternatives, Protein Supplements End User: Food Industry, Dietary Sector, Nutraceutical Companies, Animal Feed Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, DuPont, Ruchi Soya Industries Ltd., CHS Inc., Bob's Red Mill Natural Foods, Inc., Sinoglory Enterprise Group Co. Ltd., The Scoular Company, Foodchem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soya Flour Market Emerging Trajectories
Processing technology and regulatory compliance are converging to reshape competitive positioning, with sustainability verification and protein functionality emerging as the primary axes of differentiation.
Extrusion-based texturization is decentralizing soya flour value capture. High-moisture extrusion transforms defatted flour into fibrous structures that replicate meat mouthfeel without additional binders. Plant-based meat manufacturers in the United States and Germany are adopting twin-screw systems at commercial scale. This equipment shift is decentralizing protein ingredient sourcing away from centralized isolate production toward integrated flour-to-final-product operations.
EU deforestation due diligence laws are tightening traceability requirements. The regulation mandates geolocation verification for all soya entering European food supply chains, effective for large operators. Brazilian exporters must deploy satellite-linked farm monitoring systems to maintain market access. Mid-sized processors lacking compliance infrastructure face exclusion from premium European bakery and meat alternative contracts.
Buyer consolidation among contract manufacturers is compressing supplier negotiation cycles. Large co-manufacturers serving multiple plant-based brands are consolidating flour procurement into annual volume tenders with strict sustainability riders. This procurement concentration favors processors with certified supply chains and penalizes spot-market dependent operators. The shift is most pronounced in Netherlands-based meat alternative production clusters.
Soya Flour Market Segmentation
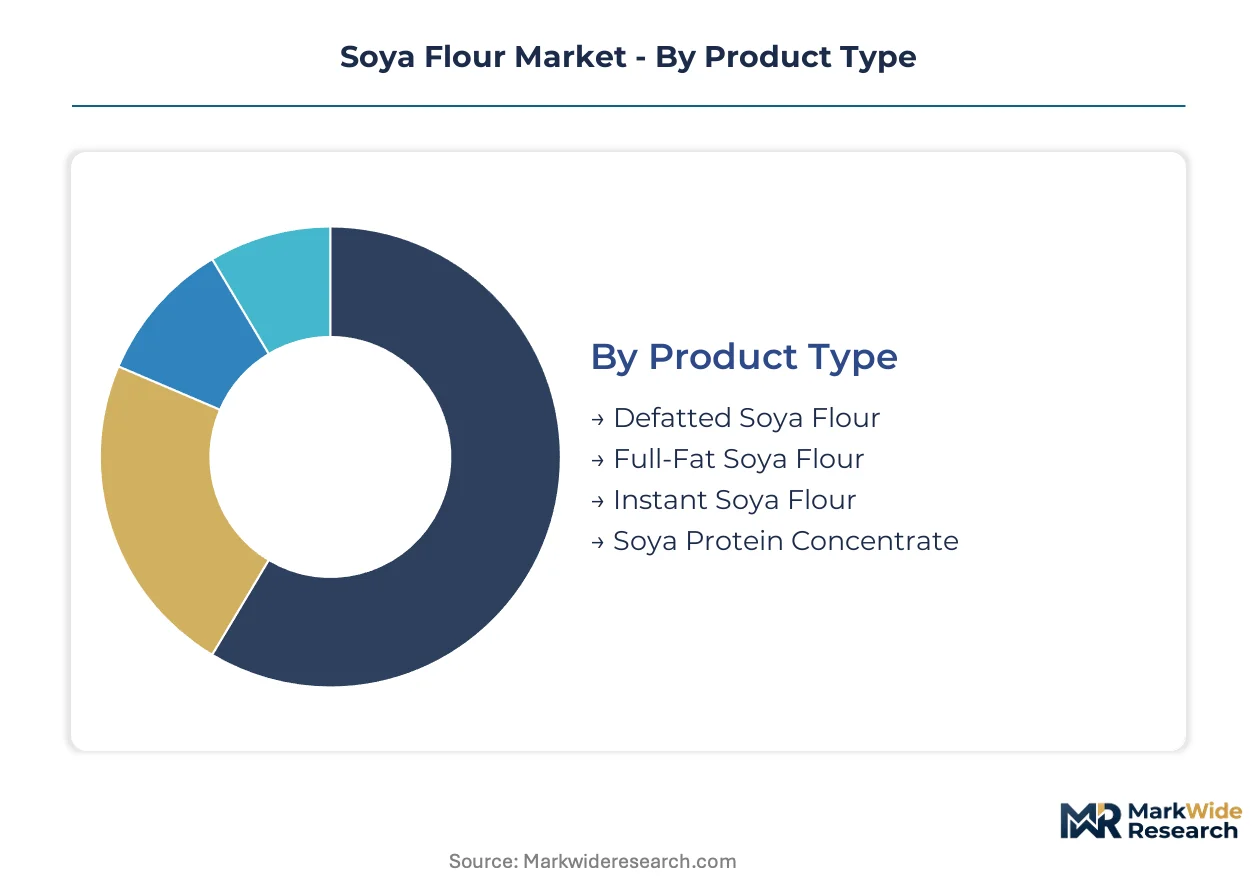
Soya flour segmentation tracks divergent processing economics across protein concentration levels and end-use specifications. Product type and application splits reveal where margin compression and premiumization operate simultaneously.
Product Type:
Supply concentration clusters around extraction technology sophistication, with solvent-based defatted capacity dominating volume and mechanical pressing commanding price premiums.
- Defatted Soya Flour:Solvent-extracted meal containing less than 1% residual oil content delivers extended shelf stability for industrial bakery procurement. Archer Daniels Midland's North American crush network supplies major US bread manufacturers seeking consistent protein fortification at scale.
- Full-Fat Soya Flour:Mechanical pressing preserves 18-20% native oil content, improving mouthfeel in plant-based meat formulations without hydrogenated additives. Cargill's Brazilian Cerrado partnerships anchor supply for European clean-label meat alternative producers navigating EU deforestation due diligence laws.
- Instant Soya Flour:Pre-gelatinized particles disperse rapidly in beverage applications; CHS Inc. distributes through cooperative channels to Midwestern dairy alternatives processors.
- Soya Protein Concentrate:Higher protein fraction (65-70%) extracted via aqueous processing serves specialized nutraceutical encapsulation; limited suppliers constrain availability for functional food developers.
Defatted soya flour absorbs the bulk of installed capacity; full-fat soya flour is expanding most quickly.
Application:
Cost tier differentiation separates commodity volume plays from formulation partnerships that capture technical service margins.
- Baked Goods:Standardized defatted grades integrate into commercial bread and pastry production as cost-efficient protein extenders. China's school nutrition mandates embed soya flour in institutional bakery procurement specifications.
- Meat Alternatives:High-moisture extrusion of defatted flour creates fibrous textures replicating animal protein mouthfeel. Twin-screw processing adoption in Germany and the United States shifts value capture toward integrated flour-to-final-product operations.
- Snacks:Extruded puffs and crisps utilize full-fat varieties for flavor carrying capacity; Brazilian processors supply regional South American snack manufacturers.
- Protein Supplements:Isolated protein fractions dominate this premium segment, limiting conventional flour penetration outside emerging market powder formulations.
Baked goods command the largest volume commitments; meat alternatives show the steepest expansion trajectory.
End User:
Customer type fragmentation creates divergent service intensity requirements, from technical formulation support to commodity spot pricing.
- Food Industry:Large-scale manufacturers negotiate annual contracts with sustainability certification riders. Netherlands-based meat alternative co-manufacturers consolidate procurement into volume tenders favoring certified supply chains.
- Dietary Sector:Specialized nutrition providers require allergen-segregated production lines compliant with FDA labeling rules, elevating qualification barriers for multi-product facilities.
- Nutraceutical Companies:Encapsulation-grade specifications demand enhanced protein solubility profiles; limited qualified suppliers concentrate in North American and European processing clusters.
- Animal Feed:Lower-protein grades absorb residual crush output; price sensitivity limits margin capture despite substantial volume flow.
The food industry locks in the majority of contracted volume; the dietary sector is climbing the fastest on clean-label positioning.
Distribution Channel:
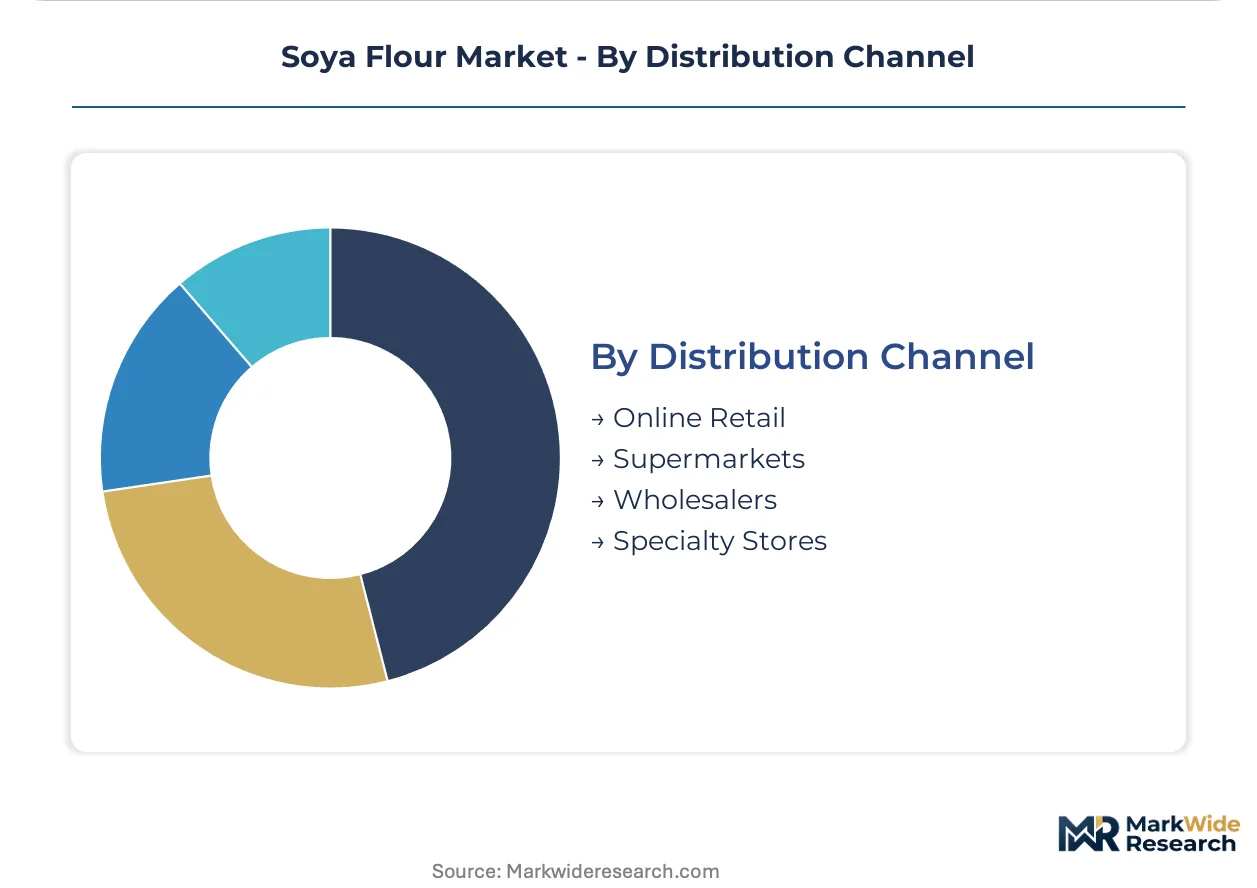
Geography of demand shapes channel economics, with urban density favoring direct distribution and dispersed markets requiring intermediary layers.
- Wholesalers:Bulk ingredient distributors serve mid-sized bakery and snack manufacturers across the US Midwest and Brazilian interior with standardized defatted grades.
- Supermarkets:Retail-packaged full-fat and instant varieties reach consumer kitchens through private-label programs; shelf space competition intensifies in Chinese urban centers.
- Online Retail:Direct-to-consumer protein supplement sales bypass traditional distribution; specialty fermented soya flour variants target niche beverage applications.
- Specialty Stores:Organic and non-GMO certified products command premium positioning; three-year transition timelines for acreage certification constrain supply elasticity.
Wholesalers handle the greatest tonnage; online retail is gaining share fastest on formulation customization services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Brazil's Mato Grosso and China's Yangtze River Delta concentrate crush capacity near soybean origination points. These zones attract processors with tax holidays on capital equipment imports and streamlined customs procedures for defatted flour exports.
United States
The USDA's biofuel mandates and school nutrition fortification programs sustain institutional procurement volumes. FDA allergen labeling rules require segregated production lines, elevating capital barriers for multi-product facilities. Illinois and Iowa host integrated crush-to-flour operations serving domestic bakery chains and meat alternative startups in Chicago.
Brazil
ANVISA traceability requirements and EU deforestation due diligence laws are restructuring export eligibility. The country's national agricultural regulator enforces geolocation verification for European-bound shipments. Mato Grosso and Goiás processors deploy satellite-linked farm monitoring to maintain access to Netherlands-based meat alternative contracts.
China
SAMR food fortification standards embed soya flour in institutional bakery procurement specifications. The national regulator's dual carbon goals pressure processors toward lower-emission crushing technologies. Shandong and Jiangsu provinces concentrate extrusion equipment manufacturing for domestic meat alternative producers.
Germany
EU REACH chemical compliance and EFSA novel food regulations elevate documentation burdens for imported flour. The country's federal food safety authority enforces residue testing protocols that slow cross-border shipments. Cologne and Hamburg host formulation labs serving European clean-label meat alternative brands.
India
FSSAI protein fortification mandates in mid-day meal programs drive institutional demand. The national food regulator's standards for edible-grade soya products constrain small-scale processor participation. Madhya Pradesh and Maharashtra crush facilities supply defatted grades to domestic snack manufacturers and export-oriented protein concentrate producers.
Soya Flour Market Vendor Landscape
North American producers anchor one tier; Brazilian specialists hold deforestation-free certification advantages. The vendor base splits between integrated agribusiness conglomerates with captive crush capacity and regional millers serving niche organic segments. Three archetypes dominate: multinational traders with origination control, cooperative-owned processors with farmer-aligned supply chains, and specialty millers targeting clean-label positioning. Competitive moves center on sustainability certification acquisition and direct-to-manufacturer distribution partnerships that bypass traditional ingredient distributors.
Within the integrated trader tier, Archer Daniels Midland Company and Cargill, Incorporated exemplify scale-driven positioning through North American and South American crush network control. CHS Inc. occupies a distinct cooperative-ownership archetype, with farmer-member governance structures anchoring grain origination in the upper Midwest. These three entities represent the dominant supply chain configurations: multinational vertical integration, cooperative farmer alignment, and regional specialty distribution.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| DuPont |
| Ruchi Soya Industries Ltd. |
| CHS Inc. |
| Bob's Red Mill Natural Foods, Inc. |
| Sinoglory Enterprise Group Co. Ltd. |
| The Scoular Company |
| Foodchem International Corporation |
| Others |
Supply Flow & Price Mechanics
Chicago Board of Trade soybean futures transmit volatility through crushing margins into three distinct pricing tiers across defatted and full-fat soya flour grades. Spot procurement from Brazilian Cerrado crushers commands premium positioning against contract-based North American supply, while mechanical pressing technology extracts additional margin for clean-label meat alternative specifications.
Pricing Analysis
Short lead-time premiums reward processors holding certified deforestation-free inventory near Rotterdam and Hamburg port facilities. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant Brazilian supply from conventional North American grades and spot-market dependent regional millers. Pricing pressure stems from pulse protein substitution in European meat alternatives, compressing soya flour premiumization potential. Mid-sized contract manufacturers exhibit highest price sensitivity due to working capital constraints, while multinational food conglomerates absorb certification premiums for supply security.
Supply Chain Analysis
Direct-to-bakery channels handle hyperscale buyer demand from institutional bread manufacturers in the United States and China. Supply concentrates in Brazil, the United States, and Argentina, with crush capacity clustering near Mato Grosso soybean origination and Iowa-Illinois processing corridors. Raw material flows draw from genetically modified and non-GMO seed stocks, hexane solvent supplies for extraction, and natural gas for thermal treatment. Single-source vulnerability around Brazilian export logistics creates structural exposure to port congestion and ANVISA documentation delays. Distribution runs through cooperative-owned elevators, multinational trader networks, and regional miller partnerships serving specialty organic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into origination-controlled crush capacity anchors competitive position as EU deforestation due diligence laws tighten procurement qualification. Players securing satellite-verified farm monitoring and segregated allergen-handling infrastructure capture first-mover certification premiums.
For Market Incumbents: Cement deforestation-free supply chain dominance through Mato Grosso farmer partnership extensions and North American organic acreage lock-ups. Pulse protein substitution in European clean-label positioning threatens soya flour premiumization; counter via fermented soya flour R&D for beverage and infant nutrition white-space. Capacity addition in Shandong province captures China's food fortification procurement consolidation. For New Entrants and Emerging Players: Launch via direct-to-bakery distribution partnerships bypassing traditional ingredient wholesalers in the US Midwest and Chinese Yangtze Delta clusters. Fermented soya flour for allergen-reduced infant nutrition applications represents the most penetrable segment given limited qualified suppliers. Target Brazilian Cerrado mid-sized processors lacking EU compliance infrastructure for acquisition or toll-processing arrangements. For Investors and Strategic Acquirers: Distressed-cycle entries favor cooperative-owned processors with farmer-aligned origination in Iowa and Minnesota during soybean margin compression periods. Long-term viability hinges on carbon border adjustment mechanism positioning across the analysis window. Monitor EU CBAM implementation timelines as inflection indicator for South American crushing asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Certification Program | EU due diligence laws mandate geolocation verification for Rotterdam and Hamburg port access. |
| Mechanical Pressing Capacity Expansion | Cold-press extraction preserves protein integrity for Cargill's European clean-label meat alternative contracts. |
| Fermented Soya Flour R&D Investment | Controlled fermentation reduces beany off-flavors for SAMR-compliant Chinese beverage applications. |
| Direct-to-Bakery Distribution Partnership | Bypassing wholesalers captures margin and formulation collaboration rights with Chicago bakery chains. |
| Organic Acreage Transition Lock-Up | Three-year USDA certification timelines require advance land commitment before premium pricing materializes. |
Methodological Framework
Independent corroboration across crush facility operators, bakery procurement directors, and meat alternative formulation scientists underwrites the qualitative findings. Primary interviews with plant managers at Brazilian Cerrado processing complexes, technical R&D directors at European extrusion equipment manufacturers, and cooperative grain origination specialists in the upper Midwest combined with secondary validation. Secondary sources include ANVISA traceability filings, EU REACH compliance registries, SAMR food fortification standards, and SEC 10-K disclosures from integrated agribusiness conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price realization across product type, application, end user, and distribution channel dimensions. CAGRs derive from trend extrapolation of crush margin economics, protein substitution elasticity, and regulatory compliance cost absorption. Segmentation modeling incorporates extraction technology tier, certification status, and regional production hub clustering. Forecast inputs include soybean yield variance patterns and EU carbon border adjustment mechanism implementation phasing.
Weather-driven yield collapse, abrupt EU deforestation regulation enforcement, and pulse protein cost parity breakthrough are the dominant revision risks. Forecasts reflect assumptions regarding crush capacity expansion timelines and certification adoption rates across Brazilian processor tiers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Dried Spent Grain Market
Grains
China Wheat Protein Market
Grains
Ghana Grain Market
Grains
North America Wheat Protein Market
Grains
White Rice Flour Market
Grains
Green Banana Flour Market
Grains
Torrified Wheat Market
Grains
Global Rice Market
Grains
Pulses Market
Grains
Millet Flour Market
Grains
Europe Rice Market
Grains
Lentil Market
Grains
Asia Pacific Maize Market
Grains
Egypt Rice Market
Grains
Asia-Pacific Guar Market
Grains
Global Cassava Flour Market