
 Middle East and Africa Plant Growth Regulators Market | 2026-2036
Middle East and Africa Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plant Growth Regulators Market Foresight
Precision fermentation and microbial synthesis of bioactive compounds is reconfiguring how plant growth regulators are manufactured and formulated for regional conditions. BASF SE leverages its Ludwigshafen-derived biotechnology platforms to sustain auxin production at scale for African distribution networks. Bayer AG anchors its position through integrated seed-treatment-to-regulator portfolios tailored to Mediterranean-climate horticulture. Syngenta Group competes via biological-derived cytokinin lines developed for water-scarce environments.
Plant growth regulators comprise organic compounds—synthetic auxins, gibberellins, cytokinins, and ethylene modulators—that regulate physiological processes including cell elongation, fruit set, and senescence at concentrations typically below one part per million, serving primarily to optimize yield consistency and post-harvest shelf life in commercial agriculture. Cytokinins command the strongest margin pool due to their stress-mitigation utility in arid-zone vegetable production, while liquid formulations lead volume because of compatibility with drip-irrigation systems prevalent in Egyptian and Israeli greenhouse operations. Granular formulations occupy a niche in broad-acre grain applications across South Africa's maize belt, where mechanized spreading reduces labor dependency.
South Africa's Department of Agriculture enforces residue limits under the Plant Improvement Act and Fertilizers, Farm Feeds, Seeds, and Remedies Act, compelling importers to submit toxicological dossiers that filter out uncertified suppliers. Egypt's Ministry of Agriculture and Land Reclamation regulates agrochemical registration through its Central Administration of Pesticides, creating procedural delays that favor established multinationals with regulatory affairs capacity. Stakeholders must monitor how Gulf Cooperation Council harmonization of maximum residue limits reshapes product eligibility across Saudi Arabian and UAE horticulture sectors.
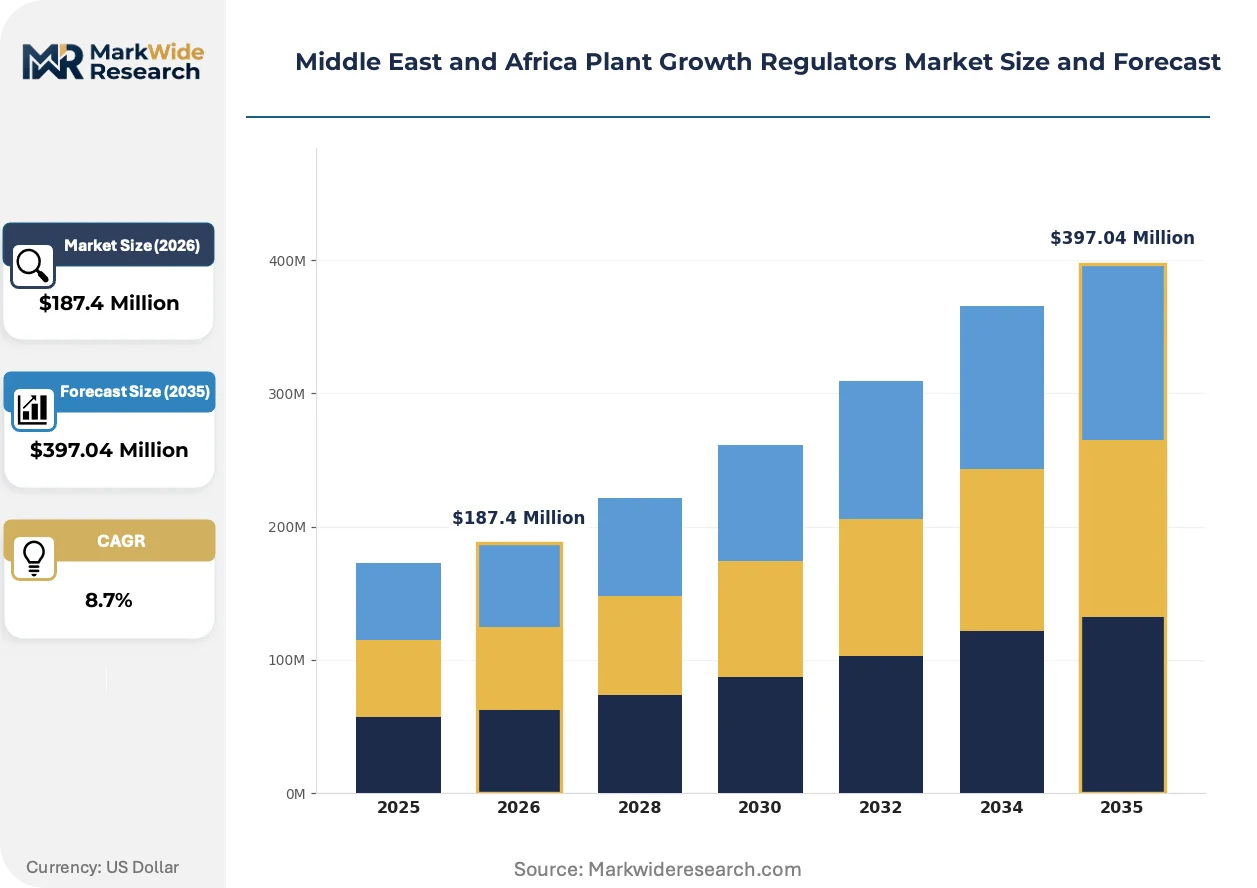
Market Dynamics
Precision fermentation and microbial synthesis platforms are compressing production costs for cytokinin-based formulations while South Africa's tightened residue limits under the Plant Improvement Act force reformulation strategies across the value chain.
Growth Catalysts
- Arid-zone horticulture expansion:Egypt's Nile Delta greenhouse belts deploy cytokinin-based stress mitigation protocols to maintain yields under water constraints. Vegetable producers in water-stressed zones drive uptake of precision-applied regulators.
- Regulatory harmonization momentum:Gulf Cooperation Council alignment of maximum residue limits creates unified product eligibility standards across Saudi Arabian and UAE horticulture sectors. This reduces fragmentation for certified formulation suppliers.
- Precision fermentation scale-up:Biotechnology platforms enable auxin production at commercial volumes previously unachievable through extraction-based methods. Manufacturing cost curves flatten for high-purity synthetic compounds.
Market Restraints
- Petrochemical feedstock volatility:Synthetic auxin precursors remain tethered to benzene and naphthalene derivative pricing. Input cost swings compress margin predictability for formulation houses.
- Regulatory dossier burden:Egypt's Central Administration of Pesticides mandates toxicological submissions that extend registration timelines. Procedural delays filter out suppliers lacking dedicated regulatory affairs capacity.
- Biostimulant substitution threat:Seaweed extract and protein hydrolysate products compete for the same stress-mitigation budget in greenhouse vegetable operations. Growers trial lower-cost biological alternatives.
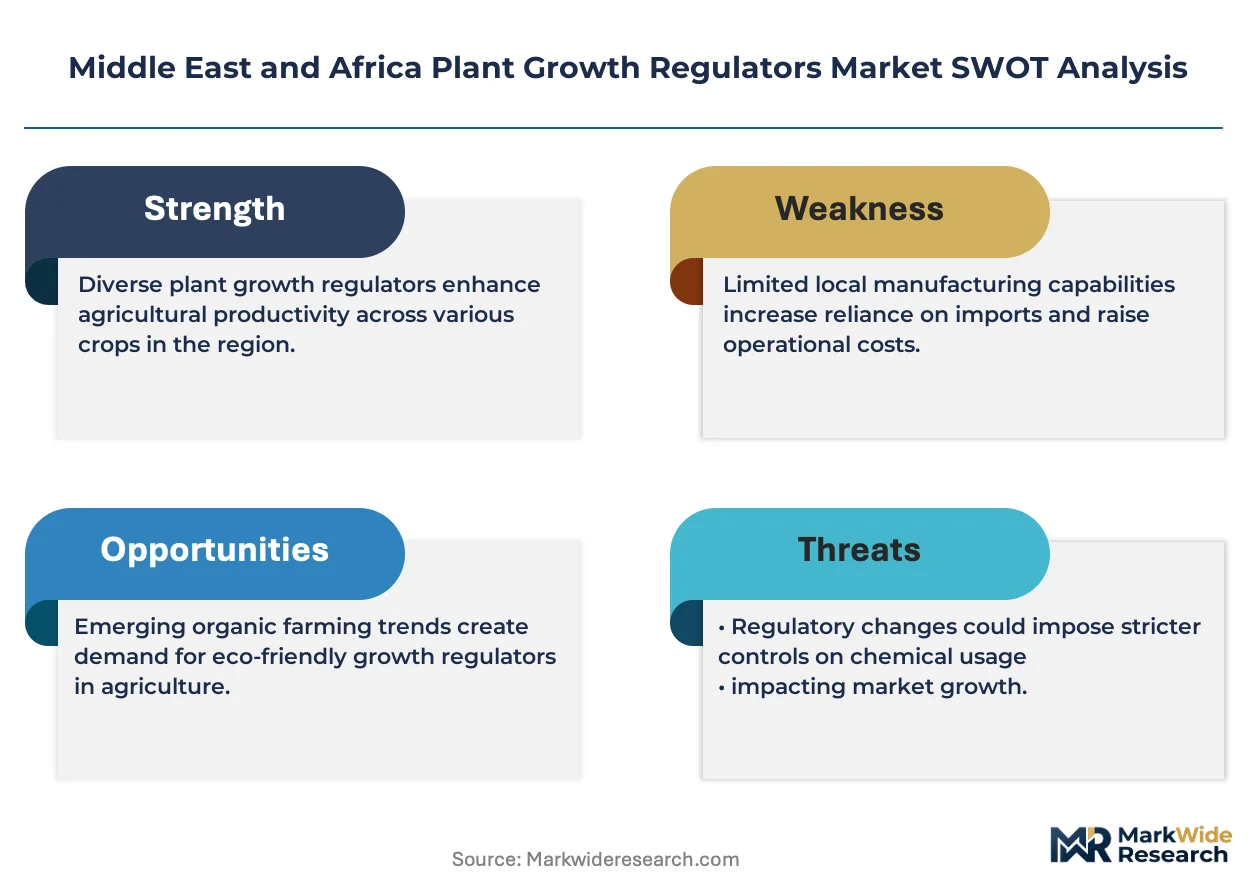
Strategic Opportunities
- Moroccan citrus export corridor:Specialty fruit cultivation across expanding orchard acreage creates demand for precision-applied regulators meeting EU import residue standards. Certification-compliant formulations capture premium positioning.
- Integrated seed-treatment portfolios:Convergence of regulator application with coated seed delivery systems reduces field labor and improves dosage accuracy. Technology bundling opens subscription-style revenue models.
- Drip-irrigation compatibility:Liquid formulation development aligns with Egyptian and Israeli greenhouse infrastructure expansion. Channel partnerships with irrigation equipment distributors unlock new access points.
Industry Challenges
- Formulation chemist scarcity:Regional talent pools lack depth in stabilizing bioactive compounds for high-temperature storage and transport. Recruitment competes with pharmaceutical and personal care sectors.
- Residue testing infrastructure gaps:Laboratory capacity for metabolite confirmation remains concentrated in South Africa and Egypt. Other markets face delayed compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plant Growth Regulators Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Ethylene Application: Fruit Production, Grain Crops, Vegetables, Ornamental Plants Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrate End User: Agriculturists, Nurseries, Greenhouses, Home Gardeners |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, UPL Limited, Sumitomo Chemical Co., Ltd., FMC Corporation, Zagro Group, Nufarm Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plant Growth Regulators Market Shifts & Advancements
Biological manufacturing methods and digital application systems are restructuring how plant growth regulators reach commercial agriculture, while regulatory tightening across the Middle East and Africa reshapes product development priorities.
Sensor-guided variable-rate application technology is digitizing how growers deploy cytokinin treatments across heterogeneous field conditions. Israeli and South African citrus operations adopt drone-mounted and tractor-integrated systems that map canopy density and apply regulators at sub-field resolution. This compresses over-application waste and builds compliance documentation for residue audits.
South Africa's Department of Agriculture enforces maximum residue limits under the Plant Improvement Act and Fertilizers, Farm Feeds, Seeds, and Remedies Act. Importers must submit toxicological dossiers that filter uncertified suppliers from the market. Established multinationals with regulatory affairs infrastructure capture share as compliance costs rise.
Greenhouse vegetable producers in Egypt's Nile Delta are consolidating procurement through cooperative buying structures that negotiate volume contracts directly with formulation manufacturers. Traditional agrochemical distributor margins compress as these collectives demand technical support bundled with price transparency. This channel shift is most visible in water-stressed vegetable belts where input costs dominate profitability calculations.
Middle East and Africa Plant Growth Regulators Market Segmentation
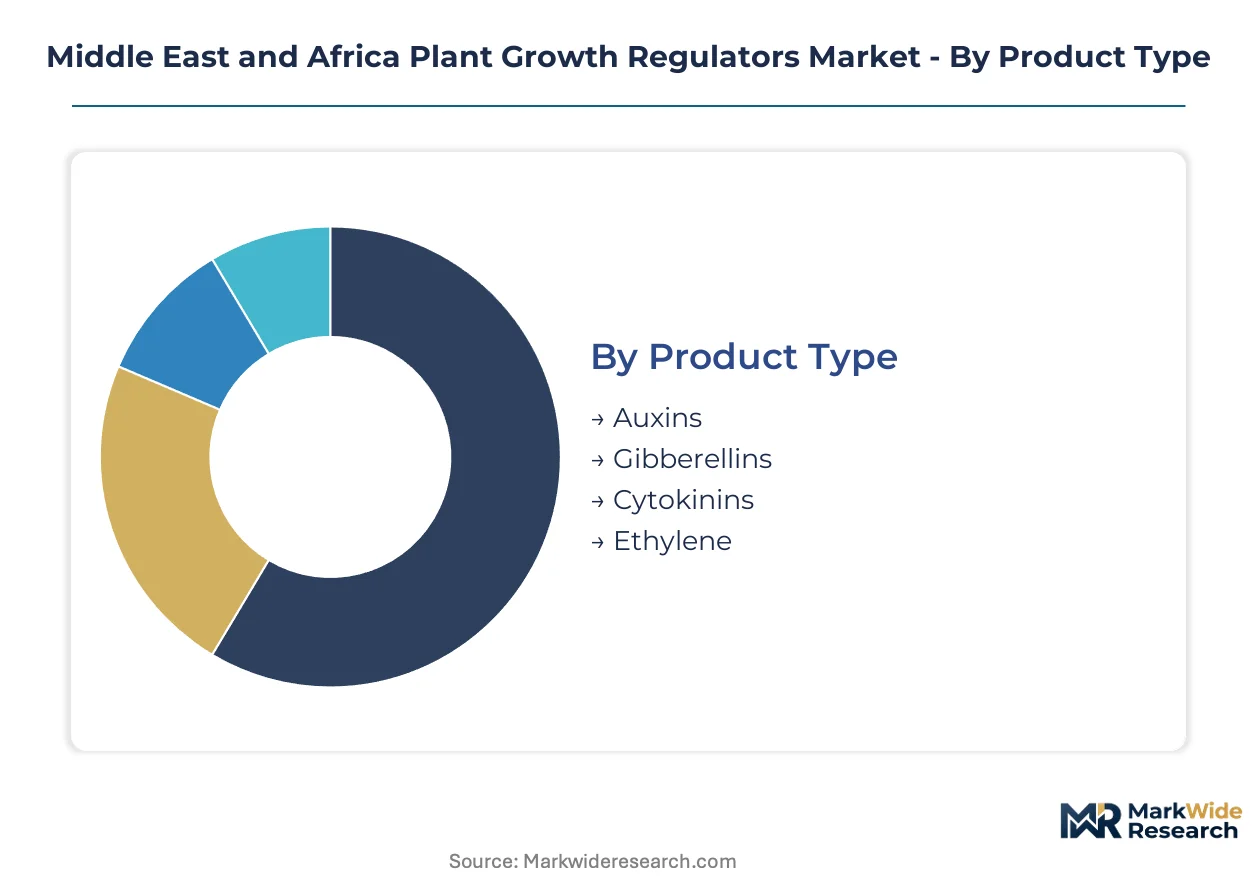
Plant growth regulator segmentation across the Middle East and Africa reflects divergent agronomic requirements across arid-zone horticulture, broad-acre grain systems, and protected cultivation infrastructure. Each dimension captures distinct procurement patterns, formulation preferences, and compliance obligations that shape supplier positioning.
Product Type:
Cost tier differentiation separates commodity synthetic compounds from precision-fermented biological analogs, with margin structures varying dramatically by manufacturing pathway.
- Cytokinins:These adenine-derived compounds regulate cell division and delay senescence in water-stressed vegetable systems. Egyptian Nile Delta greenhouse operators deploy cytokinin protocols to maintain tomato and pepper yields under salinity pressure, paying premium pricing for certified residue-compliant formulations.
- Auxins:Indole-3-acetic acid derivatives and synthetic analogs control root initiation and fruit setting. South African citrus nurseries anchor demand for precision-applied auxin formulations that meet EU export residue standards under the Plant Improvement Act's tightened limits.
- Gibberellins:Diterpenoid acids promoting stem elongation and seed germination.
- Ethylene:Gaseous hormone and release inhibitors modulating ripening schedules.
Cytokinins hold installed capacity. Auxins are rotating up the share rankings.
Application:
Application segmentation tracks where physiological intervention delivers measurable commercial returns across distinct crop value chains.
- Vegetables:Greenhouse tomato, pepper, and cucumber operations in Egypt and Israel deploy cytokinin-based stress mitigation to maintain yields under water constraints. Drip-irrigation compatibility drives liquid formulation preference in these controlled environments.
- Fruit Production:South African citrus and Moroccan orange exporters require residue-compliant regulators that satisfy EU maximum residue limits. Precision application technology maps canopy density for sub-field resolution dosing.
- Grain Crops:South Africa's maize belt utilizes granular formulations for mechanized broad-acre application.
- Ornamental Plants:UAE and Saudi Arabian commercial nurseries serving landscaping markets.
Vegetable applications hold installed capacity. Fruit production is rotating up the share rankings.
Formulation Type:
Volume concentration aligns with irrigation infrastructure prevalence and labor availability across the regional footprint.
- Liquid:Aqueous solutions and soluble concentrates integrate directly with drip-irrigation systems prevalent in Egyptian and Israeli greenhouse belts. Compatibility with fertigation infrastructure eliminates separate application passes and reduces labor dependency.
- Granular:Slow-release pellets suit mechanized spreading across South Africa's maize belt where broad-acre grain operations prioritize equipment efficiency over precision targeting.
- Powder:Dry formulations requiring reconstitution before application.
- Emulsifiable Concentrate:Oil-based carriers for specific crop penetration requirements.
Liquid formulations hold installed capacity. Granular types are rotating up the share rankings.
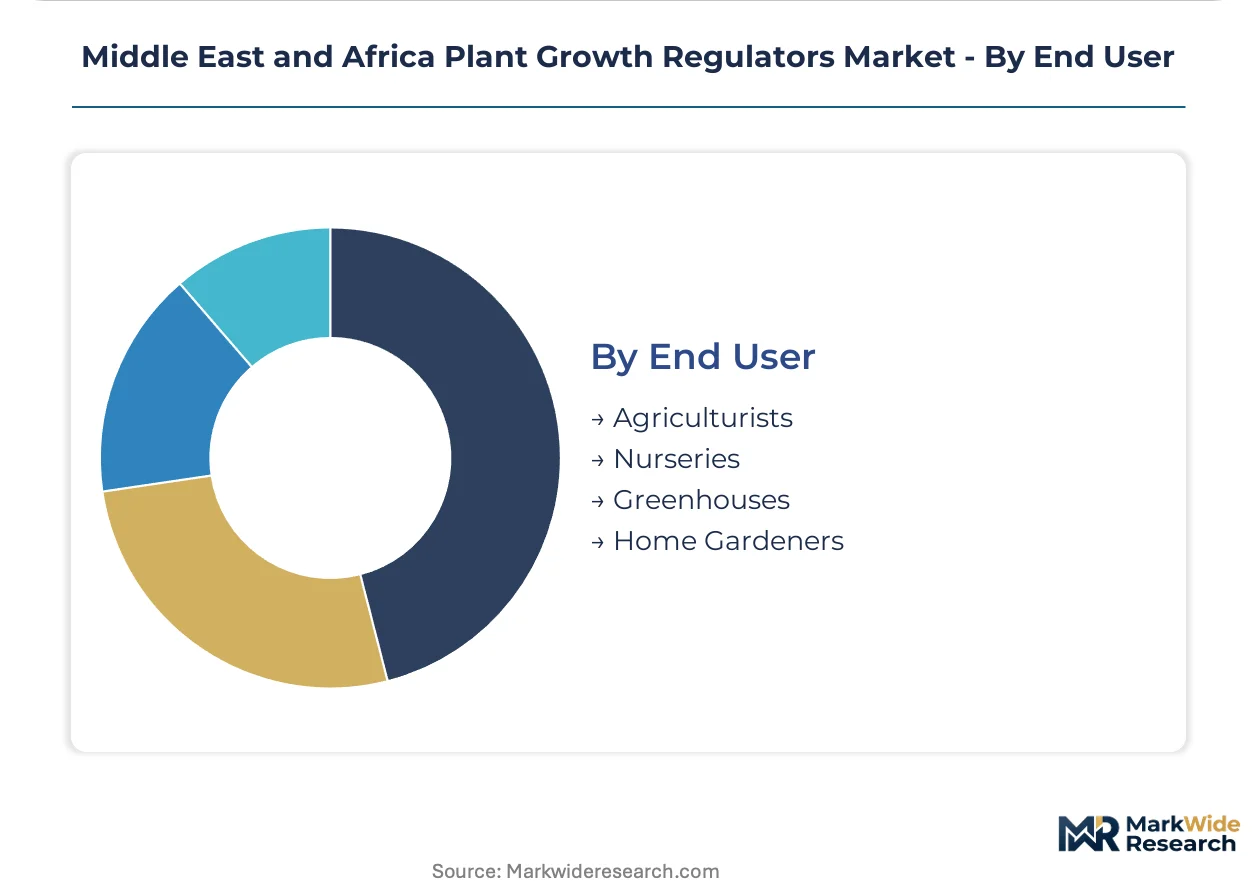
End User:
Customer type segmentation captures procurement sophistication divergence between commercial operations and smallholder systems.
- Greenhouses:Egyptian Nile Delta protected vegetable operations consolidate procurement through cooperative buying structures that negotiate direct manufacturer contracts. These collectives demand technical support bundled with price transparency, compressing traditional distributor margins.
- Agriculturists:Commercial farming enterprises across South Africa's citrus orchards and grain belts.
- Nurseries:Propagation specialists serving export-oriented fruit industries.
- Home Gardeners:Retail-packaged consumer segment with limited regional penetration.
Greenhouse end users hold installed capacity. Agriculturists are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African citrus exports to European Union markets drive residue-compliant formulation demand across the Middle East and Africa corridor. Egyptian greenhouse vegetable production supplies Gulf Cooperation Council retail chains with year-round produce. Israeli precision agriculture technology anchors regional innovation in sensor-guided application systems.
South Africa
Specialty citrus cultivation in Limpopo and Eastern Cape provinces requires precision-applied regulators meeting EU maximum residue limits. The Department of Agriculture enforces toxicological dossier requirements under the Plant Improvement Act. Cape Town-based formulation facilities serve export-oriented orchard operations with certified residue-compliant products.
Egypt
Nile Delta greenhouse belts deploy cytokinin-based stress mitigation for water-stressed tomato and pepper production. The Ministry of Agriculture and Land Reclamation regulates registration through the Central Administration of Pesticides. Kafr El-Sheikh governorate concentrates cooperative buying structures that negotiate direct manufacturer contracts.
Israel
Protected cultivation in the Arava and Jordan Valley regions drives drip-irrigation compatible liquid formulation uptake. The national plant protection regulator mandates residue monitoring for export-oriented produce. Tel Aviv-area agrotech clusters develop drone-mounted variable-rate application systems for sub-field resolution dosing.
Saudi Arabia
Controlled-environment agriculture in Riyadh and Qassim regions supplies domestic food security targets with greenhouse vegetables. The Saudi Food and Drug Authority aligns maximum residue limits with Gulf Cooperation Council harmonization standards. Al-Kharj agricultural cluster hosts expanding commercial nursery operations serving landscaping markets.
Morocco
Citrus export corridors in Gharb-Chrarda-Béni Hssen and Souss-Massa regions demand precision-applied regulators satisfying EU import standards. The national food safety authority enforces residue limits under harmonized trade protocols. Agadir-based packing and treatment facilities coordinate pre-export phytosanitary compliance for European retail chains.
Middle East and Africa Plant Growth Regulators Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning across formulation and distribution tiers. The market structure concentrates around multinational agrochemical conglomerates with integrated seed-treatment-to-regulator portfolios and regional distributors with regulatory affairs infrastructure. Three archetypes dominate: biotechnology-platform multinationals, integrated crop protection conglomerates, and regional formulation specialists. Competitive moves center on precision fermentation capacity expansion and strategic partnerships with irrigation equipment distributors.
Within the biotechnology-platform tier, BASF SE and Bayer AG exemplify integrated players leveraging Ludwigshafen-derived and German-based manufacturing platforms respectively. Syngenta Group occupies a position among biological-derived specialists targeting water-scarce environments. These three entities anchor the premium formulation segment through regulatory compliance capabilities and established distribution networks across Egyptian and South African agricultural belts.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| UPL Limited |
| Sumitomo Chemical Co., Ltd. |
| FMC Corporation |
| Zagro Group |
| Nufarm Limited |
| Others |
Supply & Pricing Matrix
Precision fermentation capacity concentration in Ludwigshafen and Leverkusen anchors margin capture for high-purity cytokinin formulations, while Egyptian and South African formulation houses compete on cost-optimized liquid blends for greenhouse vegetable operations.
Pricing Analysis
Extraction-based versus precision-fermented production methods create a pronounced technology-generation pricing gap across the Middle East and Africa corridor. Three-tier pricing structure across certified residue-compliant, standard commercial-grade, and unregistered economy formulations dominates the market. Certification under South Africa's Plant Improvement Act and Egypt's Central Administration of Pesticides protocols commands substantial premia from citrus export operations. Cost compression in economy-tier synthetic auxins is intensifying because of benzene derivative feedstock volatility. Greenhouse cooperatives in Egypt's Nile Delta exhibit highest price sensitivity, while South African citrus exporters demonstrate lowest sensitivity due to EU market access requirements.
Supply Chain Analysis
Contract manufacturing for active pharmaceutical-grade ingredients concentrates among German biotechnology platforms and Indian fine chemical specialists serving African distribution networks. Geographic supply concentration centers on Germany for precision-fermented biological analogs, India for synthetic precursor chemicals, and South Africa for regional formulation and repackaging. Raw material dependencies rest on adenine derivatives, indole-3-acetic acid precursors, and benzene-based synthetic auxin feedstocks. Single-source vulnerability around German precision fermentation capacity presents structural risk for high-margin cytokinin supply. Distribution runs through established agrochemical distributor networks in Egypt and South Africa, with cooperative buying structures in the Nile Delta compressing traditional channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across regulatory jurisdictions and crop-specific residue protocols creates multiple niche entry points for specialized formulation suppliers. Cooperative procurement consolidation in Egyptian greenhouse belts and precision agriculture adoption in Israeli citrus operations generate distinct demand-side niches.
For Market Incumbents: Pre-empt biostimulant substitution by bundling cytokinin formulations with drip-irrigation technical support packages for Egyptian cooperative buyers. Defend South African citrus market share through backward integration into residue testing infrastructure, addressing laboratory capacity gaps that delay compliance verification. Accelerate precision fermentation scale-up to flatten manufacturing cost curves against emerging microbial synthesis competitors.
For New Entrants and Emerging Players: Build out regional formulation capabilities in Morocco's citrus export corridor, where EU residue standard compliance creates barrier-protected demand for certified suppliers. Target Saudi Arabian controlled-environment agriculture expansion, where Gulf Cooperation Council regulatory harmonization reduces market entry complexity. Deploy channel partnerships with irrigation equipment distributors as primary go-to-market mechanism for liquid formulation penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as platform technologies achieve commercial scale. Long-term viability over the next decade favors biotechnology-platform multinationals with regulatory affairs infrastructure and regional formulation specialists with cooperative channel relationships. Acquisition target archetype: mid-cap regional formulators with Central Administration of Pesticides registration dossiers and established South African citrus customer relationships. Quarterly review of cooperative procurement consolidation rates and precision agriculture equipment deployment metrics is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | BASF SE's Ludwigshafen biotechnology platforms compress cytokinin production costs for African distribution. |
| Regulatory Dossier Investment | Central Administration of Pesticides submissions filter uncertified competitors from Egyptian greenhouse markets. |
| Irrigation Equipment Partnership | Liquid formulation compatibility with Israeli and Egyptian drip systems unlocks cooperative procurement channels. |
| Residue Testing Infrastructure | Laboratory capacity expansion in South Africa accelerates Plant Improvement Act compliance verification. |
| Cooperative Channel Development | Direct manufacturer contracts with Nile Delta collectives compress traditional distributor margin capture. |
Research Methodology
Initial hypotheses were tested against primary input from agrochemical formulation chemists, regulatory affairs managers at multinational suppliers, Egyptian cooperative procurement officers, South African citrus export operations managers, and Israeli precision agriculture technology providers and refined through secondary validation. Primary research drew from trade data through South Africa's Department of Agriculture, Egyptian Ministry of Agriculture registration filings, SEC 10-K disclosures from listed agrochemical conglomerates, and industry association reports from CropLife International. Bottom-up volume estimates across cytokinin, auxin, and gibberellin product categories were triangulated against top-down market sizing from production capacity analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application crop category, formulation compatibility with irrigation infrastructure, and end-user procurement sophistication. CAGRs were derived from growth driver elasticity analysis applied to baseline penetration rates. Industry-specific forecast inputs incorporated cooperative buying structure expansion trajectories in Egypt and precision agriculture adoption curves in Israeli and South African citrus operations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by biotechnology-platform multinationals or rapid cooperative consolidation in Egyptian greenhouse belts would shift outcomes. Forecasts incorporate assumptions around regulatory harmonization timelines and precision fermentation cost reduction curves. Quarterly review of Central Administration of Pesticides registration approval rates and cooperative procurement volume concentration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Potassium Humate Market
Agrochemicals
Superphosphates Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market