
 White Rice Flour Market | 2026-2036
White Rice Flour Market Size, Share, and Industry Trends Forecast 2026-2036
White Rice Flour Market Analytics
Modular packaging formats is broadening buyer choice across retail and food-service channels. Archer-Daniels-Midland Company leverages its grain origination network to secure long-dated rice supply contracts. Ingredion Incorporated differentiates through modified rice starch co-development with downstream customers. Thai Flour Industry Co Ltd anchors regional distribution across Southeast Asian markets.
White rice flour consists of finely milled endosperm from Oryza sativa grains, typically achieving particle sizes below 180 microns with amylose content ranging from fifteen to twenty-five percent depending on cultivar. Manufacturers employ either dry milling or wet milling processes, with the latter yielding lower fat content and extended shelf stability for industrial baking applications. The gluten-free product type commands premium positioning as celiac-safe certification expands across European and North American retail shelves. Noodle applications represent the fastest-growing segment as Asian convenience food formats penetrate Western markets. Bulk packaging dominates volume flows into food processing while retail bags capture higher per-unit margins.
The FDA enforces allergen labeling and preventive controls under FSMA for domestic and imported rice flour facilities. The EU's REACH framework governs processing aid chemicals used in wet milling operations. Thailand's Ministry of Agriculture and Cooperatives maintains varietal registration and export quality standards for hom mali and pathum thani rice destined for milling. Stakeholders must monitor evolving glyphosate residue limits across destination markets and align milling investments with certified gluten-free capacity.
Market Dynamics
The FDA's Food Safety Modernization Act is compressing compliance timelines for rice flour processors while Thailand's central plains milling cluster concentrates supply leverage among a handful of integrated operators.
Growth Catalysts
- FSMA traceability mandates:The FDA's preventive controls rule forces domestic and imported facilities to implement hazard analysis plans, accelerating certified gluten-free capacity investments across North American processing plants.
- Celiac-safe certification expansion:European retail shelves now demand third-party gluten-free validation, pulling modified starch co-development programs into industrial baking supply chains.
- Noodle format Westernization:Asian convenience food penetration into US and European markets is electrifying demand for specialized amylose-content flour blends in fresh and instant noodle production.
Market Restraints
- Input cost volatility:Thai hom mali and pathum thani varietal prices swing with monsoon-dependent harvest cycles, squeezing margin predictability for long-dated supply contract holders.
- Supply concentration risk:Bangkok-proximate milling clusters control the majority of export-grade white rice flour volume, creating single-point vulnerability for international buyers.
- Glyphosate residue friction:Diverging maximum residue limits across destination markets force processors to maintain multiple production lines or risk border rejection.
Strategic Opportunities
- Underpenetrated European gluten-free bakery:Celiac awareness in Germany and France lags Nordic penetration rates, leaving room for certified flour positioning in artisan bread and pastry segments.
- Modified rice starch convergence:Wet milling technology integration with enzymatic modification processes enables functional ingredient substitution for chemically modified starches in clean-label applications.
- Food-service pouch formats:Modular retail packaging is displacing bulk bags in restaurant and catering procurement, capturing premium per-unit margins through portion-controlled SKUs.
Industry Challenges
- Certification timeline compression:Gluten-free facility audits and third-party validations now require 12-18 month lead times, delaying new market entry for greenfield milling investments.
- Wet milling capex intensity:Lower-fat, extended-shelf-life production demands specialized centrifugation and drying equipment that strains mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Rice Flour Market |
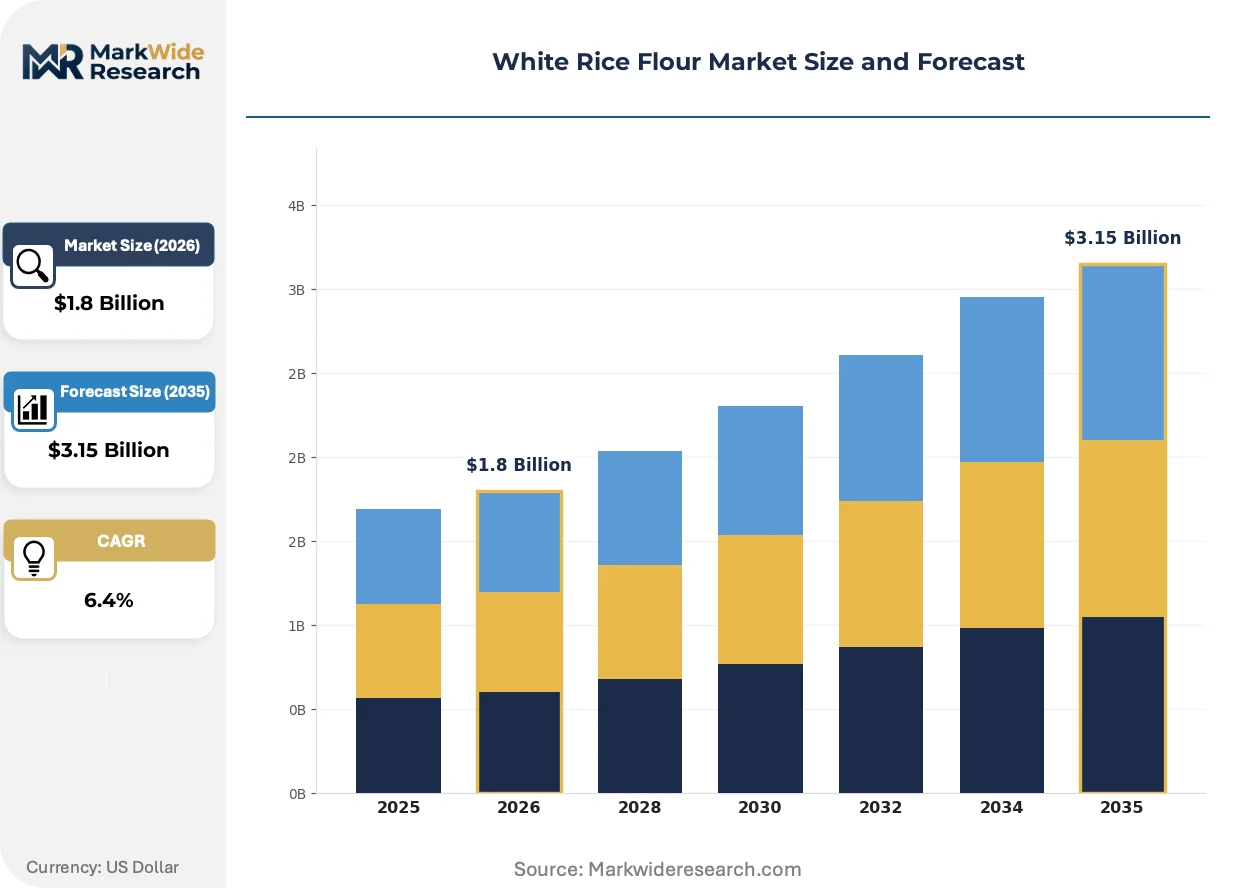
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Gluten-Free, Conventional, Instant Application: Baking, Thickening, Noodles, Snacks Packaging Type: Bulk, Retail, Sachets, Bags End User: Household, Restaurants, Bakeries, Food Processing |
| Companies Covered | Archer-Daniels-Midland Company, Ingredion Incorporated, General Mills, Cargill Incorporated, Bunge Limited, Burapa Prosper, Bob's Red Mill Natural Foods, Thai Flour Industry Co Ltd, Erawan Flour Mill Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Rice Flour Market Evolving Landscape
Processing technology advancement and regulatory stringency are converging to reshape competitive positioning in rice flour manufacturing, with sustainability and traceability emerging as non-negotiable buyer criteria.
Enzymatic modification of rice starch is electrifying functional performance in industrial baking applications. Large-scale bread and pastry manufacturers in North America are adopting these modified flours at accelerating pace to replace chemically treated alternatives. This technology is compressing the clean-label ingredient supply chain by enabling single-source rice-derived solutions that meet both performance and certification requirements.
REACH framework oversight of processing aid chemicals is tightening wet milling operations across European facilities. The ECHA's substance evaluation program now requires detailed safety documentation for solvents and enzymes used in starch extraction, adding compliance layers for exporters serving EU food manufacturers. Industrial baking and noodle segments are responding by demanding pre-certified flour shipments with complete chemical inventory disclosure.
Buyer procurement patterns are fragmenting across channel-specific specifications. Food processors now maintain separate quality standards for bulk industrial shipments versus retail-branded co-packing arrangements, forcing mills to operate parallel production certifications. This bifurcation is most visible in US and German markets where private-label gluten-free brands command distinct supply chain audits from commodity ingredient buyers.
White Rice Flour Market Segmentation
White rice flour procurement patterns fragment sharply across certification tiers, end-use specifications, and channel formats. Each segmentation dimension carries distinct margin profiles and compliance burdens that reshape supplier competitive positioning.
Product Type:
Supply concentration in Thai milling clusters favors large-batch conventional output, while certified variants demand dedicated facility investments and extended validation timelines.
- Gluten-Free:Achieves celiac-safe status through third-party audit protocols and segregated production lines. European retail shelves in Germany and France now mandate this certification for shelf placement, compressing facility conversion timelines for Asian exporters.
- Organic:Requires varietal traceability from paddy field through milling, with glyphosate-free cultivation protocols and accredited handler certification. Thai hom mali organic premiums attract contract farming arrangements in Suphan Buri and Chainat provinces.
- Conventional:Standard milled endosperm serving industrial baking and thickening applications with minimal certification overhead.
- Instant:Pre-gelatinized flour enabling cold-water reconstitution for convenience food formats.
Conventional product absorbs the bulk of installed capacity; gluten-free is expanding most quickly.
Application:
Cost tier differentiation separates commodity thickening uses from premium bakery and noodle segments requiring precise amylose content and particle size distribution.
- Noodles:Fresh and instant noodle manufacturers specify 18-22% amylose content for optimal texture retention during sheeting and drying. Western penetration of Asian convenience formats electrifies demand for specialized flour blends in US and European production facilities.
- Baking:Industrial bread and pastry operations demand modified starch functionality through enzymatic treatment, replacing chemically modified alternatives in clean-label formulations.
- Thickening:Standard viscosity applications in soups, sauces, and gravies prioritize cost efficiency over functional specificity.
- Snacks:Extruded and sheeted snack applications utilize lower-protein flour fractions for texture control.
Noodle applications command the steepest expansion trajectory; thickening remains the volume anchor.
Packaging Type:
Customer type bifurcation drives parallel production certifications, with food processors maintaining distinct quality standards from retail co-packing arrangements.
- Bulk:Tanker and tote shipments dominate industrial procurement, capturing volume discounts but surrendering per-unit margin to downstream packagers.
- Retail:Branded bag formats for supermarket and specialty store channels command premium positioning through certified gluten-free and organic claims.
- Sachets:Single-serve pouches target food-service portion control and emerging market affordability segments.
- Bags:Intermediate 5-25 kg formats bridge industrial and artisan bakery procurement needs.
Bulk packaging absorbs the bulk of installed capacity; retail formats are expanding most quickly.
End User:
Margin structure varies dramatically across end-user categories, with food processing commanding scale efficiencies and bakeries demanding technical service support.
- Food Processing:Large-scale manufacturers integrate rice flour into multi-ingredient formulations, requiring consistent lot-to-lot specification and long-dated supply contracts.
- Bakeries:Artisan and industrial bread producers specify modified starch performance characteristics, often co-developing blends with millers for proprietary applications.
- Restaurants:Food-service procurement is shifting toward pre-portioned formats that reduce waste and simplify inventory management.
- Household:Retail package consumers respond to celiac-safe certification and clean-label positioning in specialty and mainstream grocery channels.
Food processing absorbs the bulk of installed capacity; bakeries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand mills the majority of export-grade white rice flour while the United States and Germany absorb premium certified volumes. Consumption clusters in Western markets pull against concentrated Asian supply origins.
United States
The FDA's FSMA preventive controls rule compresses compliance timelines for imported rice flour facilities. Celiac-safe certification now dominates retail shelf placement negotiations. California and Texas house the largest gluten-free bakery manufacturing clusters, drawing specialized amylose-content blends from Thai exporters.
Germany
Industrial bread producers specify enzymatically modified rice starch for clean-label formulations. The EU's REACH framework governs processing aid chemicals in wet milling operations. Bavaria and North Rhine-Westphalia concentrate European demand for certified gluten-free flour in artisan and industrial baking segments.
Thailand
Hom mali and pathum thani varietals supply the global export market from central plains milling clusters near Bangkok. The Ministry of Agriculture and Cooperatives maintains varietal registration and export quality standards. Suphan Buri and Chainat provinces anchor organic contract farming arrangements for premium flour production.
China
Noodle manufacturers drive demand for 18-22% amylose content flour in fresh and instant production. GB standards regulate food additive usage in rice processing. Yangtze River Delta processing hubs integrate wet milling capacity with downstream convenience food manufacturing.
France
Artisan bakery segments lag Nordic celiac awareness rates, creating positioning opportunities for certified flour suppliers. ANSM oversees food contact material safety in packaging applications. Île-de-France and Auvergne-Rhône-Alpes regions concentrate gluten-free retail distribution infrastructure.
White Rice Flour Market Competitive Landscape
The competitive structure tilts toward integrated grain traders with origination networks and specialized Asian millers with varietal proximity. Large-scale agricultural conglomerates leverage long-dated supply contracts to secure paddy streams. Regional milling specialists and modified starch developers constitute the remaining archetypes. Capacity certification investments and enzymatic modification technology licensing dominate current competitive moves.
Among North American agricultural conglomerates, Archer-Daniels-Midland Company and Ingredion Incorporated occupy positions spanning grain origination through functional ingredient development. Thai Flour Industry Co Ltd anchors the Southeast Asian specialist tier. These three exemplify the structure's division between scale-driven traders and proximity-based millers.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| General Mills |
| Cargill Incorporated |
| Bunge Limited |
| Burapa Prosper |
| Bob's Red Mill Natural Foods |
| Thai Flour Industry Co Ltd |
| Erawan Flour Mill Co Ltd |
| Others |
Value Network & Pricing Analysis
Celiac-safe certification mandates from European retailers are forcing Thai exporters to segregate production lines and absorb extended validation timelines, compressing margins on conventional grades while inflating premiums for validated gluten-free output. This specification-driven bifurcation concentrates pricing power among integrated millers with certified capacity, leaving commodity processors exposed to raw material volatility without offsetting price leverage.
Pricing Analysis
Margin tightening in conventional flour reflects monsoon-dependent harvest swings for Thai hom mali and pathum thani varietals that destabilize long-dated contract economics. Three-tier pricing structure across certified gluten-free, organic, and conventional grades segments buyers by compliance burden rather than functional performance alone. Cost-down pressure on standard milled endosperm accelerates because industrial baking customers consolidate procurement volumes and demand freight-absorbed delivered pricing. Food processing conglomerates exhibit highest price sensitivity due to formula cost targets, while artisan bakeries accept premiums for co-developed modified starch functionality.
Supply Chain Analysis
Certified gluten-free facility audits now require 12-18 month lead times, gating new supplier qualification and entrenching incumbent relationships with validated European and North American distribution channels. Geographic supply concentration centers on Thailand, Vietnam, and India, with Thai central plains clusters controlling the majority of export-grade amylose-specified blends. Raw material dependencies rest on paddy field traceability systems, glyphosate-free cultivation protocols, and enzymatic modification reagent streams. Single-source vulnerability concentrates in Bangkok-proximate milling infrastructure, where flooding or political disruption would sever international volume flows. Distribution runs through bulk tanker shipments to industrial processors, parallel with retail-branded bag formats for supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The White Rice Flour Market functions as a cost-of-compliance arena where FDA's FSMA preventive controls rule and EU REACH framework erect capital-intensive barriers that favor incumbent integrated operators with validated facility networks and regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into organic paddy contract farming in Suphan Buri and Chainat provinces to secure glyphosate-free supply streams and buffer against Thai harvest volatility. Expand certified gluten-free capacity ahead of European retail shelf mandate expansion, leveraging existing audit relationships to compress validation timelines for greenfield competitors. Channel control through direct food-service pouch format development captures premium per-unit margins as restaurant procurement shifts toward portion-controlled inventory management. For New Entrants and Emerging Players: FDA's Food Safety Modernization Act in the United States opens a window for domestic toll milling arrangements that bypass Thai supply concentration risk and reduce tariff exposure. Target underpenetrated artisan bakery segments in France and Germany where celiac awareness lags Nordic penetration rates, enabling certified flour positioning without entrenched competitor relationships. A co-development go-to-market angle with industrial bread manufacturers for enzymatically modified starch blends builds technical credibility faster than commodity volume plays. For Investors and Strategic Acquirers: The window for entry favors wet milling technology specialists with enzymatic modification capabilities that enable clean-label ingredient substitution. Long-term viability hinges on capturing gluten-free certification moats before European retail consolidation locks out new validated suppliers. Monitor glyphosate residue limit harmonization across destination markets as the inflection signal—divergent standards force costly parallel production lines, while alignment would compress compliant capacity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Gluten-Free Capacity Expansion | FSMA and EU retail mandates compress facility conversion timelines for Asian exporters seeking shelf placement. |
| Backward Integration into Organic Paddy Contract Farming | Thai hom mali organic premiums in Suphan Buri and Chainat provinces secure glyphosate-free supply streams. |
| Enzymatic Modification Technology Licensing | REACH framework oversight of processing aid chemicals favors enzymatic starch treatment over solvent-based alternatives. |
| Food-Service Pouch Format Development | Modular packaging captures premium margins as restaurant procurement shifts toward portion-controlled SKUs. |
| Long-Dated Supply Contract Structuring | Industrial baking customers demand consistent lot-to-lot amylose specification across multi-year procurement horizons. |
Research Methodology
Document review covered Thai Ministry of Agriculture export quality standards, FDA FSMA preventive controls guidance, and EU REACH substance evaluation documentation, complemented by interviews with rice mill operations managers, gluten-free certification auditors, industrial bakery procurement leads, and enzymatic starch modification technology suppliers. Secondary validation drew from customs trade databases, food processing industry association reports, and agricultural commodity price indices. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Segment-level demand projections incorporated product type tiers, application specifications across noodle and baking segments, packaging format channels, and end-user categories spanning food processing and artisan bakery operations. CAGRs were derived from elasticity modeling against paddy price volatility, certification penetration curves, and convenience food format adoption rates. Wet milling capacity expansion schedules and enzymatic modification technology diffusion patterns informed supply-side constraints across the projection horizon.
The model assumes a particular technology adoption path for enzymatic starch modification; alternative pathways involving chemically treated alternatives would alter the outlook if clean-label preferences shift or REACH enforcement relaxes. Forecasts reflect assumptions regarding monsoon pattern stability, glyphosate regulatory harmonization, and gluten-free certification audit capacity expansion. A model refresh is warranted upon material change in FDA enforcement posture or European retail certification mandate timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Wheat Market
Grains
North America Wheat Flour Market
Grains
Global Cassava Flour Market
Grains
Sorghum Flour Market
Grains
Global Rice Market
Grains
Organic Rice Market
Grains
Heritage Grain Market
Grains
Barley Grass Market
Grains
North America Oats Market
Grains
White Beans Market
Grains
Millet Flour Market
Grains
South Africa Maize Market
Grains
Guar Complex Market
Grains
China Maize Market
Grains
Europe Wheat Market
Grains
Global Maize Market