
 Rye Market | 2026-2036
Rye Market Size, Share, and Industry Trends Forecast 2026-2036
Rye Market Outlook
Wheat is realigning rye's role in baking formulations as millers reformulate for protein stability and cost control. Michter's leverages its Kentucky operations to secure heritage rye stocks for limited whiskey releases. Sazerac sustains vertical integration from grain procurement through bottling across multiple distillery properties. Wild Turkey anchors its portfolio with high-rye bourbon recipes that compete for shelf space against straight rye offerings.
Rye is a winter cereal grain of the Poaceae family with protein content ranging from 8% to 14%, valued for drought tolerance and performance on poor soils in cool climates. Its primary commercial purpose spans distillation for whiskey production, milling for dense breads, and malting for brewing applications. Whiskey commands the premium tier within product type segmentation, while flour maintains volume leadership across European and North American bakery channels. Specialty stores represent the fastest-growing distribution channel as consumers seek craft and heritage-labeled rye products.
The USDA and EPA shape rye agriculture through crop insurance programs and biofuel blending mandates that influence planting decisions. FDA labeling requirements and TTB standards of identity define how distillers market straight rye versus blended products. EFSA and national regulators across the EU enforce mycotoxin thresholds that affect grain acceptance for food use. Stakeholders must monitor how carbon accounting rules and regenerative agriculture certifications will reshape sourcing premiums and supply base requirements.
Market Dynamics
Heritage grain movements and craft distillery sourcing are concentrating demand around identity-preserved rye varieties, forcing millers and maltsters to rebuild procurement networks around varietal traceability rather than commodity grades.
Growth Catalysts
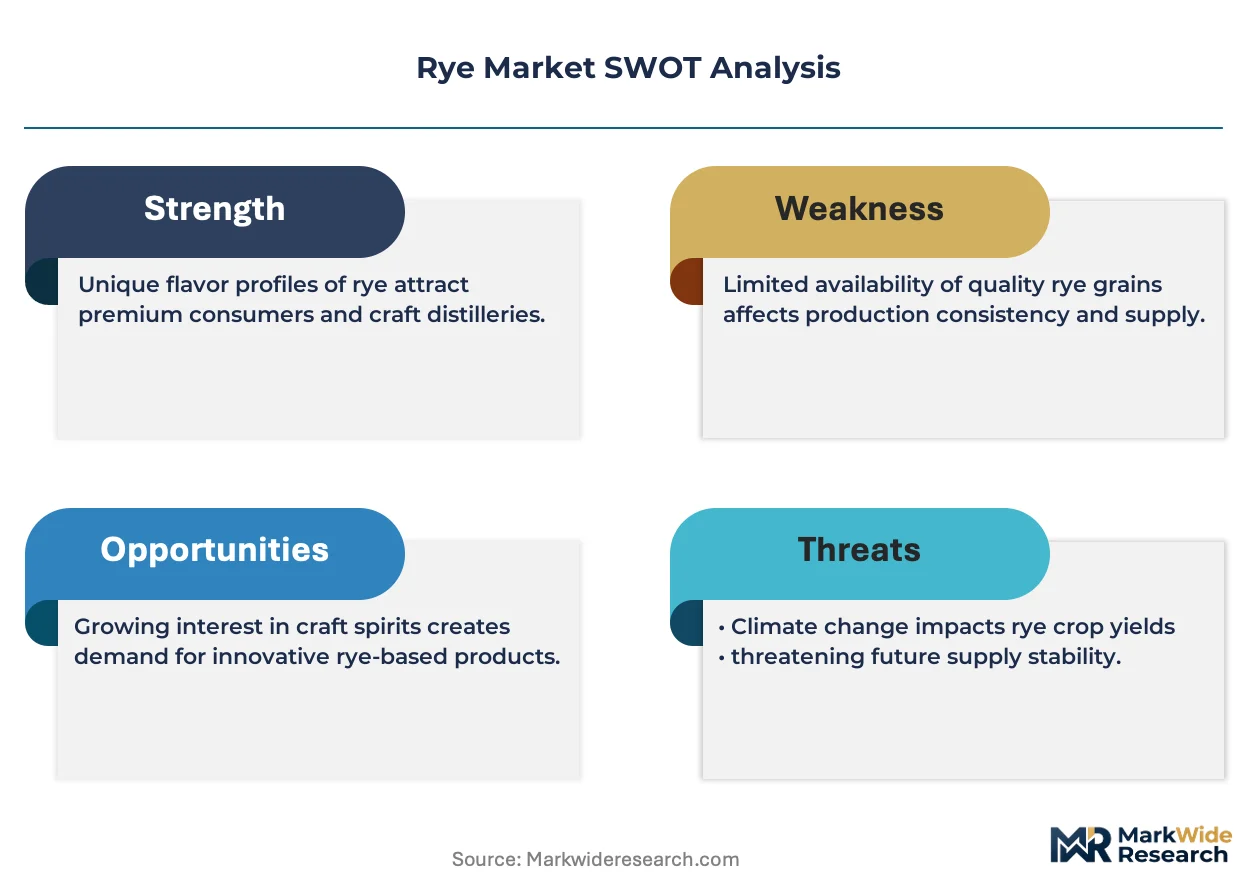
- FDA and TTB Standards of Identity:The strict definition of straight rye whiskey (minimum 51% rye mash, new charred oak barrels) creates premium tier separation that commands shelf price premiums in United States retail channels.
- Climate-adaptive breeding programs:Poland and Germany are deploying winter-hardy cultivars with improved frost tolerance, expanding plantable acreage into marginal soils where wheat underperforms.
- Heritage grain movements:Regional food systems in the United States are resurrecting pre-hybrid rye landraces for flavor differentiation in artisan baking and distilling applications.
Market Restraints
- Input cost volatility:Nitrogen fertilizer prices and natural gas-derived ammonia inputs swing planting economics unpredictably for rye growers in Germany and Poland.
- Substitution threat:Wheat flour reformulations with added gluten and enzymes are displacing rye in commercial bread production where protein stability and cost control dominate purchasing decisions.
- Supply concentration risk:Distilling-grade rye contracts concentrate among a narrow base of large-scale maltsters in North America, creating bottlenecks during harvest quality shortfalls.
Strategic Opportunities
- Carbon accounting rules:The EU Green Deal and emerging soil carbon protocols in the United States are creating sourcing premiums for rye grown under regenerative agriculture certifications.
- Specialty store channel expansion:Direct-to-retail heritage labeling is expanding into independent grocers and farm stores across the United States, bypassing commodity grain handlers.
- Malting innovation:Modified atmospheric steeping and germination control technologies are converging with small-batch kilning to enable craft brewery sourcing of varietal-specific rye malts.
Industry Challenges
- Varietal certification timelines:Identity-preserved supply chains require third-party verification of heritage landraces, adding 12-18 month lag to contract fulfillment.
- Mycotoxin compliance complexity:EFSA ergot and DON thresholds for food-use grain force costly sorting and rejection protocols at European mill intake points.
- Skill gaps in heritage agronomy:Pre-hybrid rye cultivation knowledge has atrophied among extension services, forcing distillers and maltsters to rebuild grower training programs from seed archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rye Market |
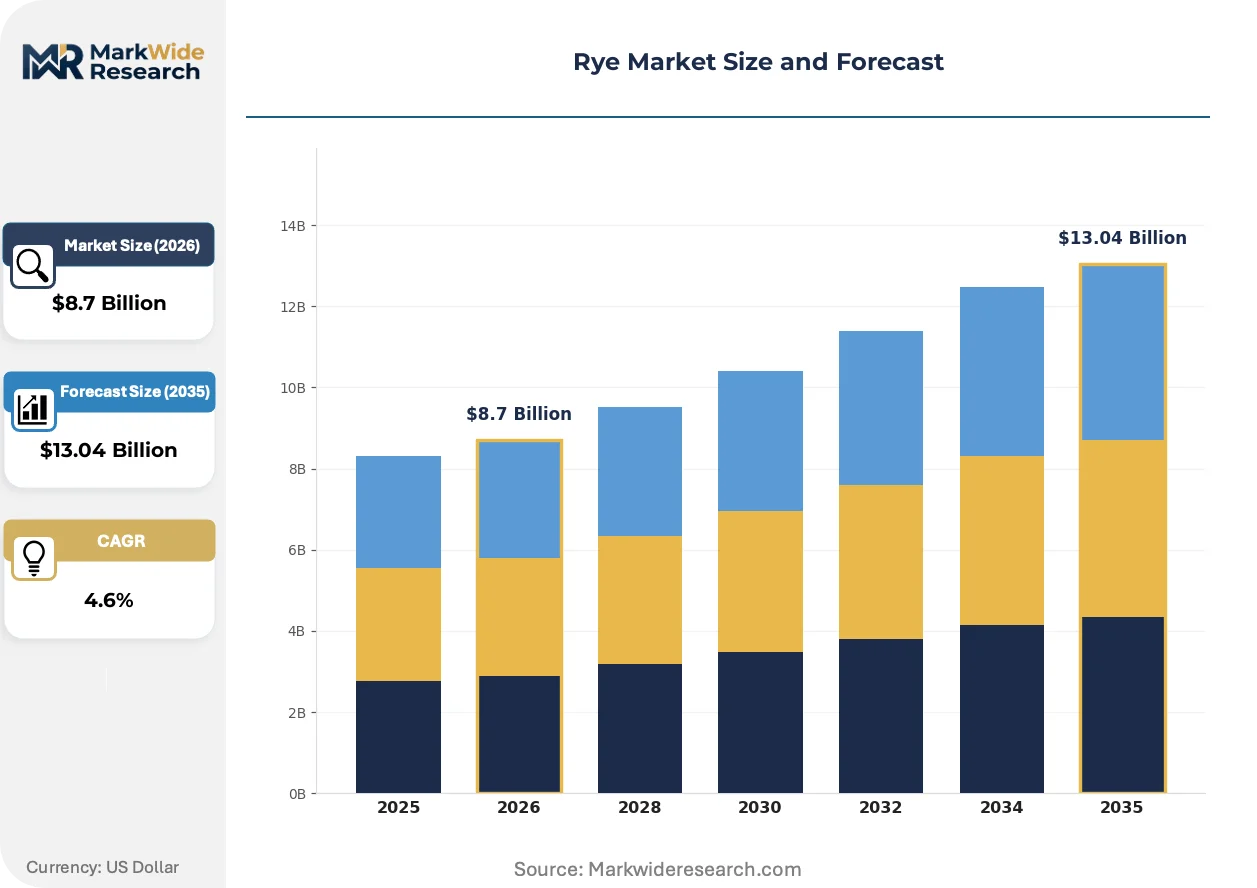
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Flour, Malt, Whiskey End Use Industry: Beverages, Bakery, Animal Feed, Snacks Packaging Type: Bags, Bulk, Bottles, Boxed Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Michter’s, Rittenhouse, Sazerac, Elijah Craig, Pikesville, WhistlePig, Bulleit, High West, Wild Turkey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rye Market Strategic Shifts
Active breeding programs and processing technology investments are unlocking new functional applications for rye protein and fiber fractions, extending the grain's commercial relevance beyond traditional whiskey and bread channels.
Precision fermentation of rye-derived proteins is expanding into plant-based meat analog formulations, where the grain's distinctive flavor profile and binding properties attract clean-label product developers in European and North American food manufacturing. CPG formulators are adopting these ingredients at pilot scale, with commercial volumes projected to follow capacity buildouts at specialty ingredient facilities. This technology is expanding into alternative protein markets previously dominated by soy and pea isolates, compressing the addressable premium for commodity pulse proteins.
The EU Green Deal's carbon border adjustment mechanism and soil health certification requirements are reshaping grain procurement specifications for European millers and maltsters. Industrial buyers now mandate regenerative agriculture documentation and Scope 3 emissions accounting from upstream suppliers, with compliance costs passed through contract premiums. Distilling and food manufacturing segments in Germany and Poland are responding by consolidating sourcing around verified low-carbon growers and investing in on-farm methane capture verification.
Direct contracting between craft distilleries and heritage grain growers is displacing commodity elevator channels for identity-preserved rye in the United States. Small-batch producers in Kentucky and Pennsylvania are establishing multi-year varietal development agreements with regional seed savers, securing exclusive access to pre-hybrid landraces. This pattern concentrates most visibly in the Mid-Atlantic and Upper South, where terroir-linked whiskey positioning commands retail price multiples over standard straight rye offerings.
Rye Market Segmentation
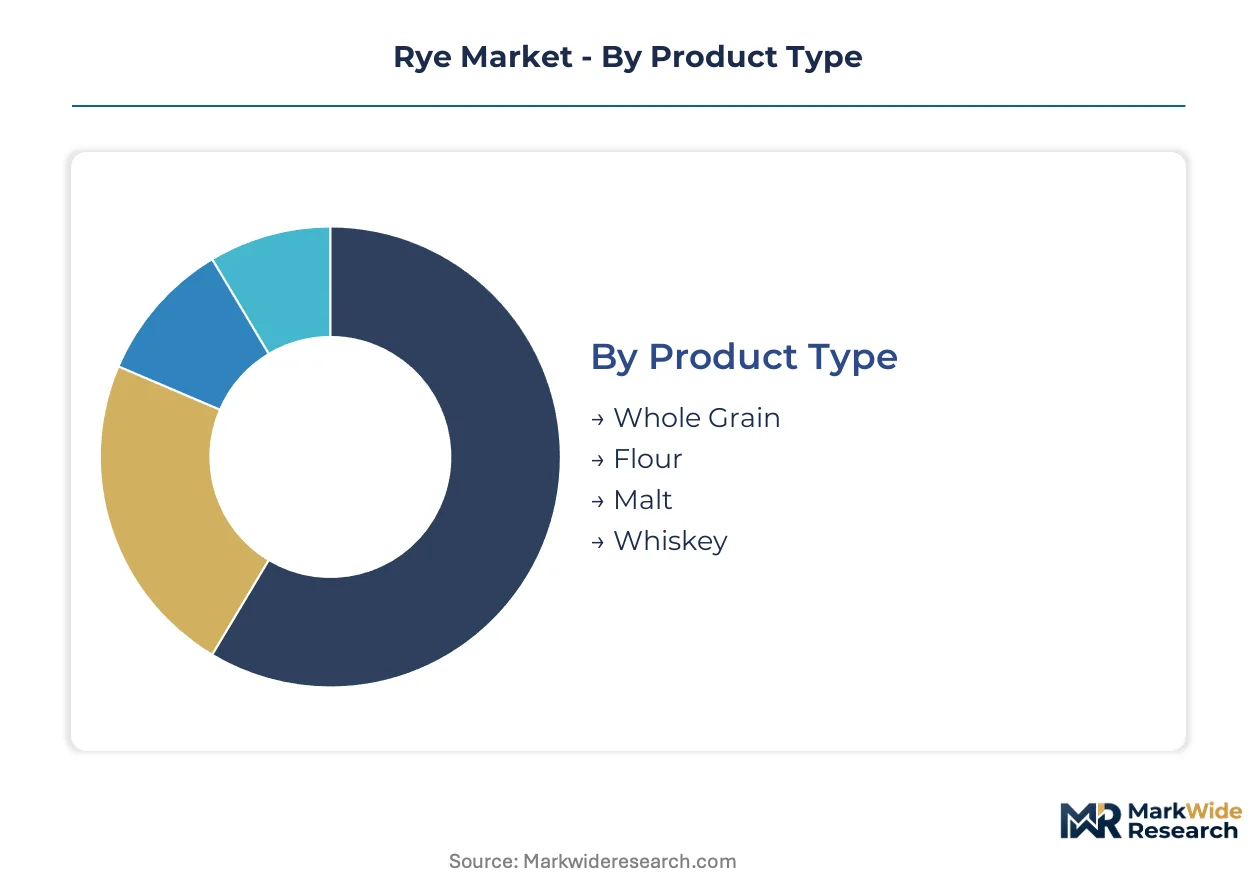
Segmentation in the rye market reveals how value migrates across processing stages and customer touchpoints. Distillers, millers, and maltsters each demand distinct specifications that reshape procurement priorities and margin capture.
Product Type:
Upgrade cycles in rye processing favor higher-value derivatives as end-users reformulate for protein functionality and flavor differentiation.
- Whole Grain:Unprocessed kernels retain bran and germ layers with protein content between 8% and 14%. Animal feed compounders in Poland and Germany concentrate procurement here for winter ration formulations, though ergot screening adds handling costs.
- Flour:Roller-milled endosperm fractions yield dense, low-gluten doughs prized in northern European baking traditions. Millers in Germany are reformulating extraction rates to balance ash content against bread volume specifications demanded by commercial bakers.
- Malt:Germinated and kilned grains supply craft breweries with enzymatic conversion potential for rye-forward beer styles.
- Whiskey:Distillation-grade rye with specific starch gelatinization profiles commands contract premiums from Kentucky and Pennsylvania distilleries.
Volume placements concentrate in Flour; the faster expansion belongs to Whiskey.
End Use Industry:
Cost tier stratification separates commodity feed applications from certified food and beverage segments with divergent margin structures.
- Beverages:Distilling and brewing applications demand identity-preserved varieties with traceable provenance for straight rye whiskey and craft beer labeling. Kentucky distilleries are locking multi-year contracts with heritage grain growers to secure mash bill consistency.
- Bakery:Dense, sourdough-compatible crumb structures drive artisan and commercial bread formulations across Germany and Poland. Reformulation toward wheat-rye blends is compressing pure rye volumes in cost-sensitive channels.
- Animal Feed:Whole grain and milling byproducts supply ruminant rations where energy density and fiber content balance ration economics.
- Snacks:Extruded and puffed applications leverage rye's distinct flavor profile in premium positioned crisp and cracker segments.
Volume concentrates in Bakery; Beverages claim the steepest expansion trajectory.
Packaging Type:
Customer type segmentation splits procurement between industrial scale handlers and direct-to-retail channels with opposing logistics requirements.
- Bulk:Unpackaged grain in rail cars and truckloads serves millers, maltsters, and feed compounders with dedicated intake infrastructure. German and Polish grain handlers dominate this channel with elevator networks optimized for commodity flow.
- Bags:25-50 kg woven polypropylene units bridge industrial and artisan users lacking bulk handling capacity. Specialty stores and small bakeries in the United States source through this intermediate format.
- Bottles:Glass and PET containers carry finished whiskey through retail and on-premise channels with TTB-mandated labeling.
- Boxed:Bag-in-box and folding carton formats serve premium flour and malt retail segments with shelf differentiation.
Volume concentrates in Bulk; Specialty Stores are gaining share fastest through Bagged formats.
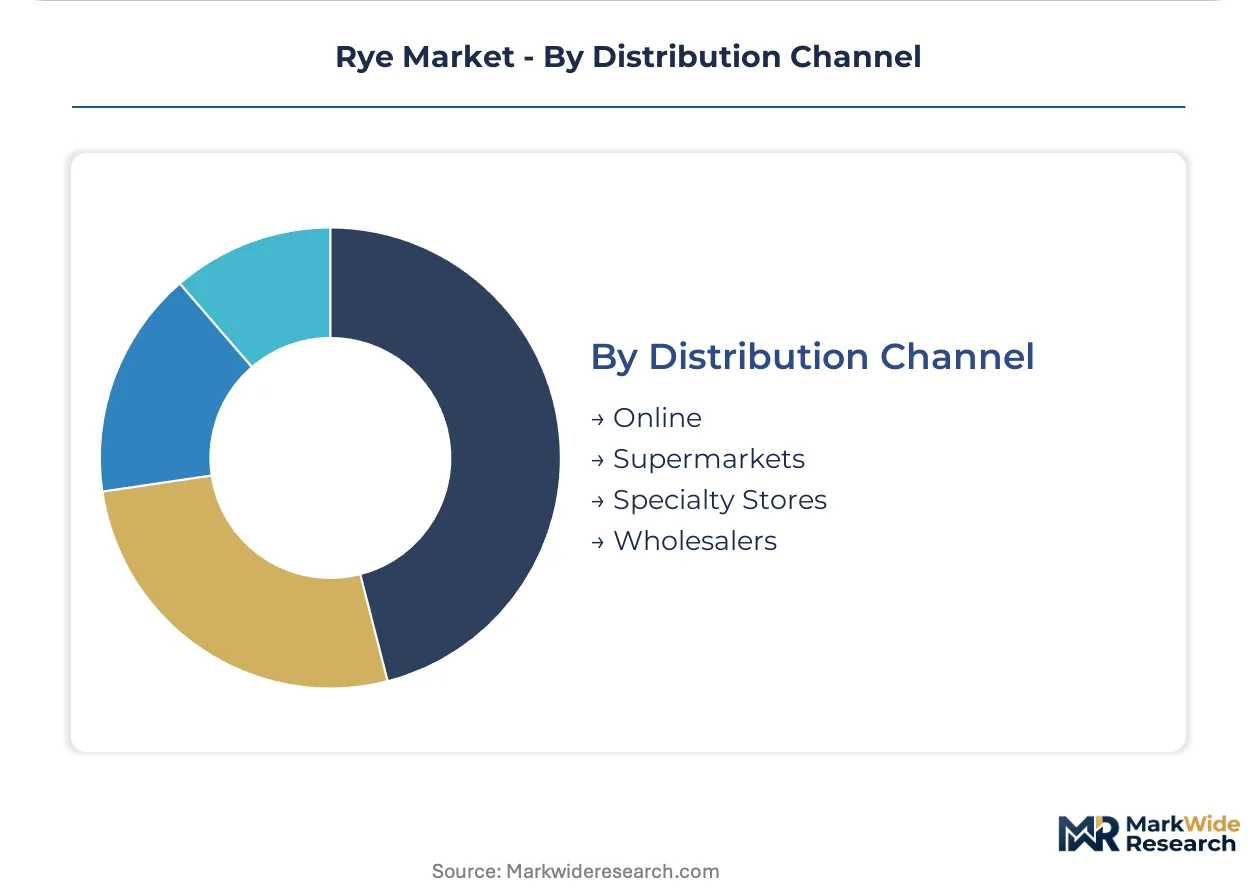
Distribution Channel:
Supply concentration in legacy grain handling infrastructure is fragmenting as identity-preserved contracts bypass traditional elevator channels.
- Wholesalers:Regional grain merchants and cooperative elevators aggregate commodity grades for mill and feed mill delivery. Concentration among North American maltsters creates bottleneck risk during harvest quality shortfalls.
- Supermarkets:Mass retail chains carry packaged flour and finished whiskey with standardized SKU economics that favor national brand distribution.
- Specialty Stores:Independent grocers, farm stores, and distillery tasting rooms enable direct heritage labeling with terroir-linked provenance. United States craft distilleries are building captive retail networks to capture margin upstream.
- Online:Direct-to-consumer platforms extend reach for limited whiskey releases and heirloom flour varieties with subscription fulfillment models.
Volume concentrates in Wholesalers; the faster climb belongs to Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rye concentrates in the United States, where craft distilleries and heritage grain movements are expanding sourcing, while European breeding programs and Asian feed applications sustain production diversity across three continents.
United States
Kentucky and Pennsylvania distilleries are locking multi-year contracts with heritage grain growers to secure mash bill consistency for straight rye whiskey. The FDA and TTB standards of identity create premium tier separation that commands shelf price premiums in retail channels. Louisville anchors the bourbon-rye corridor where Michter's and Wild Turkey maintain captive grain procurement networks.
Germany
Climate-adaptive breeding programs are deploying winter-hardy cultivars with improved frost tolerance, expanding plantable acreage into marginal soils where wheat underperforms. EFSA enforces mycotoxin thresholds that force costly sorting protocols at mill intake points. The Bavarian grain belt concentrates milling capacity where rollers reformulate extraction rates to balance ash content against commercial bread specifications.
Poland
Whole grain rye supplies animal feed compounders for winter ration formulations, though ergot screening adds handling costs at elevator networks. The EU Green Deal's carbon border adjustment mechanism is reshaping procurement specifications toward regenerative agriculture documentation. The Greater Poland Voivodeship hosts the densest concentration of winter cereal breeding stations developing frost-tolerant germplasm.
Canada
Prairie provinces sustain export-oriented production of milling-grade rye with protein stability prized in northern European baking traditions. Health Canada and PMRA regulate pesticide residues and mycotoxin limits that affect grain acceptance for food use. Manitoba's Red River Valley anchors the country's largest concentration of identity-preserved contract acres linking directly to German and Polish millers.
United Kingdom
Artisan bakers in London and the Southeast are resurrecting pre-hybrid rye landraces for sourdough-compatible crumb structures in premium positioned products. Defra and the FSA enforce labeling requirements and grain hygiene standards that shape import sourcing decisions. The Cotswolds cluster concentrates heritage grain millers supplying direct-to-retail channels bypassing commodity handlers.
Rye Market Competitive Environment
Multi-year varietal development agreements dominate the current landscape as craft distilleries secure exclusive access to pre-hybrid landraces. The vendor base splits between integrated spirits conglomerates with captive grain procurement and specialized heritage grain suppliers with identity-preserved certification capabilities. Three archetypes occupy distinct positions: legacy Kentucky distillers with backward integration into grain sourcing, independent craft producers with direct farmer contracts, and commodity maltsters serving volume distilleries. Geographic expansion into new terroir-linked positioning and portfolio diversification across whiskey styles represent the dominant competitive vectors.
Among heritage-focused specialists, WhistlePig and High West exemplify the craft archetype built around direct grower relationships and limited release positioning. Michter's occupies a position within the legacy integrated tier, leveraging Kentucky operations to secure heritage rye stocks. These three names anchor the competitive map without exhausting its diversity, as regional maltsters and cooperative elevators retain significant share in bulk supply channels.
| Leading Market Players |
|---|
| Michter's |
| Rittenhouse |
| Sazerac |
| Elijah Craig |
| Pikesville |
| WhistlePig |
| Bulleit |
| High West |
| Wild Turkey |
| Others |
Value Chain & Pricing Dynamics
Captive grain procurement networks among Kentucky distilleries anchor both supply security and premium pricing power, locking heritage rye stocks through multi-year grower contracts that insulate mash bill consistency from commodity volatility. This backward integration into identity-preserved sourcing creates tier separation between straight rye whiskey and blended alternatives, with FDA and TTB standards of identity reinforcing price premiums at retail.
Pricing Analysis
Volume placements concentrate in flour and feed grades where commodity spot markets dominate, while margin capture concentrates in whiskey and heritage-labeled segments where contract-based long-term offtake secures varietal traceability. Price differentiation stems from certification level—regenerative agriculture documentation and carbon accounting verification—and from brand premium linked to terroir-linked provenance. Cost compression in standard flour channels is intensifying because wheat reformulations with added gluten displace rye in commercial baking, squeezing margins for millers without specialty positioning. Feed compounders in Poland and Germany exhibit highest price sensitivity due to nitrogen fertilizer cost volatility, while Kentucky distilleries show lowest sensitivity given captive sourcing and premium shelf positioning.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's carbon border adjustment mechanism are reshaping sourcing toward verified low-carbon growers in Germany and Poland, forcing importers to document regenerative agriculture practices. Geographic supply concentration centers on Germany, Poland, and the United States, with Canadian prairie provinces feeding northern European milling demand. Raw material dependencies include nitrogen fertilizers, natural gas-derived ammonia inputs, and certified seed stocks for heritage landraces. Single-source vulnerability runs through concentrated North American maltsters serving volume distilleries, where harvest quality shortfalls create bottleneck risk. Distribution runs through specialty store channels gaining fastest share, bypassing commodity elevator networks for direct heritage labeling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as input cost volatility and mycotoxin compliance complexity force smaller millers and commodity handlers toward exit, concentrating procurement networks around integrated players with certification capabilities and captive grower relationships.
For Market Incumbents: Anchor market position through exclusive varietal development agreements with regional seed savers, securing multi-year access to pre-hybrid landraces before heritage grain knowledge atrophies further among extension services. Expand backward integration into on-farm methane capture verification to meet EU Green Deal procurement specifications and capture carbon accounting premiums. Defend against wheat substitution in commercial baking by investing in malting innovation for craft brewery sourcing. For New Entrants and Emerging Players: Capture white-space opportunity in direct-to-retail heritage labeling through independent grocers and farm stores across the Mid-Atlantic and Upper South, where terroir-linked whiskey positioning commands retail multiples. Target specialty store channel expansion with bagged flour formats bridging artisan users lacking bulk handling capacity. Enter through subscription fulfillment models for limited whiskey releases and heirloom varieties, bypassing established wholesale networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated spirits conglomerates seeking captive grain procurement and heritage brand portfolios. Long-term viability favors players with identity-preserved certification capabilities and direct grower contract infrastructure spanning the analysis window. Target acquisition archetype: regional maltsters with established elevator networks and regenerative agriculture verification programs. Watch nitrogen fertilizer price volatility as inflection indicator for planting economics and contract renegotiation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Contracting | Multi-year varietal agreements with seed savers secure exclusive pre-hybrid landrace access for Kentucky distilleries. |
| Carbon Certification Investment | Regenerative agriculture documentation meets EU Green Deal procurement mandates for German and Polish millers. |
| Specialty Store Channel Expansion | Direct-to-retail bypasses commodity handlers, capturing margin upstream through farm stores and independent grocers. |
| Malting Technology Scale-Up | Modified atmospheric steeping enables craft brewery sourcing of varietal-specific rye malts with flavor differentiation. |
| Backward Integration into Sourcing | Captive grain procurement networks insulate mash bill consistency from commodity volatility for straight rye producers. |
Study Parameters
Multi-period observation of planting acreage trends, varietal certification timelines, and distilling-grade contract premiums anchored the trend analysis, supplemented by interviews with distillery procurement managers, heritage grain growers, cooperative elevator operators, and EFSA regulatory affairs specialists. Secondary validation drew from USDA crop insurance data, EU agricultural statistics, TTB labeling guidance documents, and customs trade records. Bottom-up grower contract analysis and top-down market sizing triangulated volume estimates across product segments.
Input-output matrix modeling connected rye starch gelatinization profiles to whiskey production economics, flour extraction rates to bakery cost structures, and malting specifications to craft brewery procurement patterns across the analysis window. Segmentation dimensions included product type, end-use industry, packaging format, and distribution channel, with CAGRs derived from trend extrapolation of heritage grain adoption curves and climate-adaptive breeding program outputs. Forecast inputs incorporated nitrogen fertilizer price sensitivity and carbon accounting rule implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ergot and DON mycotoxin threshold enforcement, nitrogen cost volatility, and wheat substitution rates in commercial baking. Forecasts reflect documented assumptions regarding regulatory stability and grower training program effectiveness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Rice Market
Grains
Argentina Grains Market
Grains
Asia-Pacific Guar Market
Grains
Grain and Cereal Crop Market
Grains
IQF Rice Market
Grains
Grain Dryers Market
Grains
North America Oats Market
Grains
Italy Rice Market
Grains
Global Quinoa Market
Grains
Mexico Rice Market
Grains
Grain Silos Market
Grains
Global Wheat Market
Grains
Corn Silage Market
Grains
China Rice Market
Grains
Rice Flour Market
Grains
Global Grain Analysis Market