
 Rice Flour Market | 2026-2036
Rice Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Flour Market Analysis
Gluten-free product manufacturers are unwinding reliance on traditional wheat alternatives as celiac awareness and clean-label preferences expand across North American and European retail channels. Ingredion Inc. leverages its modified starch portfolio to anchor supply relationships with large-scale bakery operations seeking texture stability in gluten-free formulations. Associated British Foods plc sustains competitive positioning through its AB Mauri division, which dominates yeast and specialty ingredient distribution networks across Europe. Bob's Red Mill Natural Foods, Inc. differentiates via stone-ground production credentials and direct-to-consumer channel control in the U.S. natural foods sector.
Rice flour consists of finely milled endosperm and bran fractions from Oryza sativa grains, typically achieving particle sizes between 80 and 200 micrometers depending on intended application, with amylose content ranging from near-zero in waxy varieties to roughly 30 percent in long-grain cultivars determining gelatinization behavior and final texture in food systems. White rice flour leads volume consumption due to neutral flavor profiles and extended shelf stability, though organic rice flour represents the fastest-expanding product type as EU organic certification requirements and USDA National Organic Program standards reshape procurement criteria for export-oriented mills. Within end-use applications, thickening agent demand in Asian sauce and soup manufacturing occupies mature, price-sensitive volume pools, while coating agent applications for battered proteins in quick-service restaurant supply chains concentrate margin capture among specialized millers with custom granulation capabilities.
The FDA enforces Current Good Manufacturing Practice regulations for grain processing facilities, with particular scrutiny of allergen cross-contact controls that directly determine market access for U.S.-destined rice flour shipments. India's FSSAI mandates fortification and labeling standards that govern both domestic distribution and export eligibility for rice flour produced under its jurisdiction. Stakeholders must monitor evolving EU pesticide residue thresholds under EFSA guidance, as MRL adjustments for rice cultivation inputs reshape sourcing requirements for mills serving European gluten-free and baby food segments.
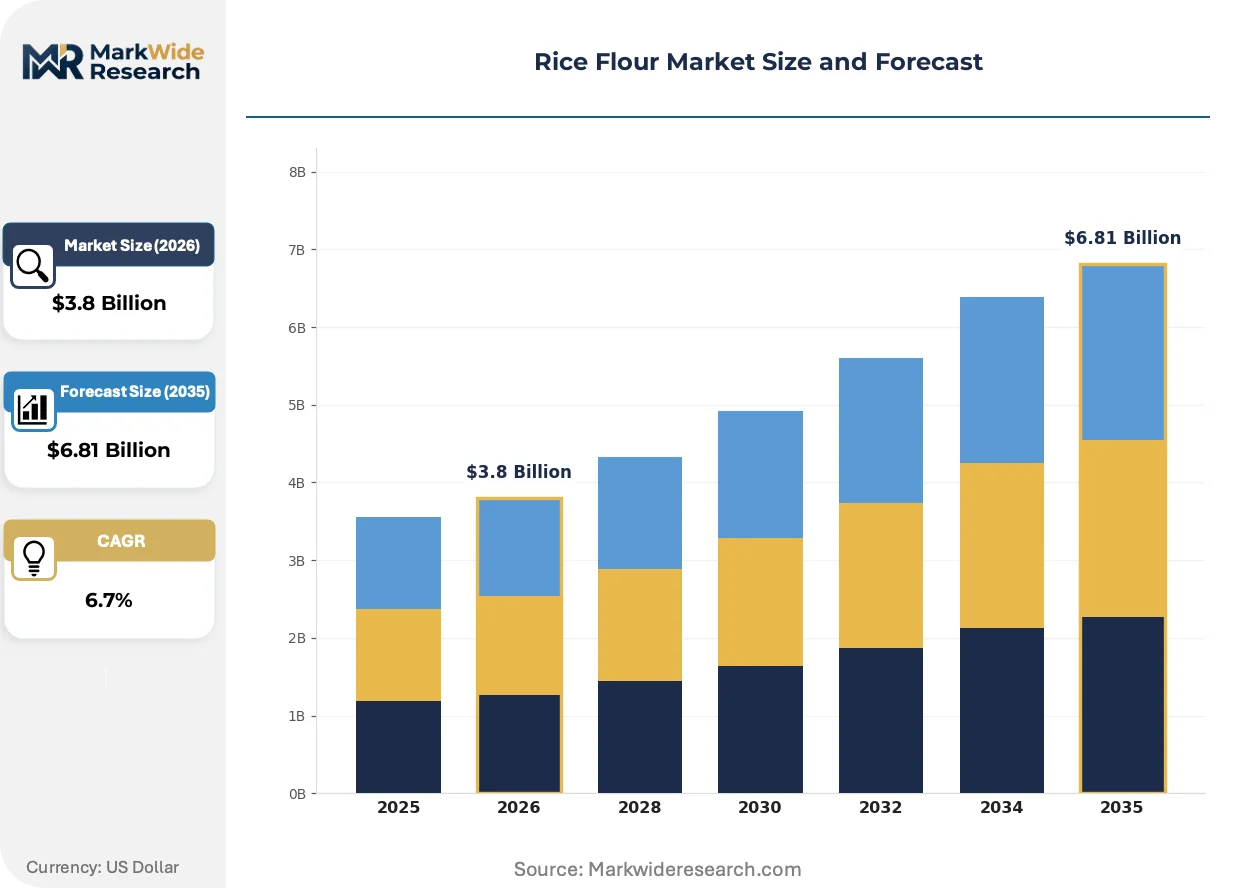
Market Dynamics
Gluten-free bakery manufacturers are consolidating procurement around rice flour as FDA allergen cross-contact enforcement tightens and celiac diagnosis rates climb in North American retail channels. This structural pull is compressing supplier qualification timelines and reshaping mill capacity allocation toward food-grade certifications.
Growth Catalysts
- FDA Food Safety Modernization Act:Mandatory preventive controls for human food are accelerating mill investment in HACCP-compliant processing lines, expanding addressable supply for branded gluten-free product manufacturers.
- Clean-label sauce thickening:Asian quick-service restaurant chains are substituting modified starches with native rice flour to meet consumer ingredient transparency demands in soup and sauce applications.
- EU organic certification expansion:Mills achieving EU 2018/848 compliance are capturing premium positioning in export-oriented baby food segments where pesticide residue thresholds are tightening.
Market Restraints
- Input cost volatility:Thai and Vietnamese white rice export prices fluctuate with monsoon patterns, compressing margin stability for toll millers lacking long-term grower contracts.
- Supply concentration risk:Premium waxy rice varieties for frozen dough applications concentrate in Mekong Delta cultivation zones, creating single-region exposure for texture-critical formulations.
- Substitution threat:Cassava flour and green banana flour are displacing rice flour in certain cost-sensitive coating applications where neutral flavor is less critical.
Strategic Opportunities
- Underpenetrated Mexico retail:Traditional masa supply chains create whitespace for gluten-free rice flour tortilla positioning in Mexico City and Guadalajara supermarket channels.
- Precision fermentation convergence:Rice flour substrates paired with enzymatic modification are enabling clean-label texturizers that bypass synthetic additive disclosure requirements.
- Direct-to-bakery distribution:Bypassing ingredient distributors through contracted drop-ship programs is capturing margin and formulation collaboration access with artisan gluten-free bakeries.
Industry Challenges
- Certification timeline compression:BRCGS and SQF dual certification for rice flour mills now requires 14-18 month implementation cycles, delaying market entry for new processing investments.
- Skill scarcity in gluten-free segregation:Qualified technicians for dedicated line sanitation and allergen control command premium wages in U.S. grain processing labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Flour Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice Flour, Brown Rice Flour, Glutinous Rice Flour, Organic Rice Flour End User: Food Industry, Bakery, Snack Manufacturers, Gluten-Free Products Application: Thickening Agent, Baking Ingredient, Coating Agent, Noodles Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Ingredion Inc., Associated British Foods plc, Archer Daniels Midland Company, Bob's Red Mill Natural Foods, Inc., Bunge Limited, Cargill, Inc., Thai Flour Industry Co., Ltd., Wilmar International Limited, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Flour Market Emerging Trajectories
Stone-ground and air-classified milling technologies are diverging in capital allocation as specialty rice flour grades fragment toward distinct end-use performance specifications. Equipment suppliers and mill engineering firms are responding with modular processing architectures.
Air-classification systems with integrated particle size distribution control are fragmenting traditional mill output categories. Frozen dough manufacturers in the U.S. Midwest are adopting these systems to achieve sub-100-micron fractions without heat damage to starch granules. The technology is fragmenting supplier tiers into precision-capable specialists versus commodity volume players.
EFSA guidance on arsenic in rice-based foods for infants is tightening maximum levels for inorganic arsenic species. European baby food manufacturers are now requiring batch-level testing documentation from Asian mill suppliers. Rice flour destined for EU infant nutrition channels is commanding segregated supply chains with enhanced testing protocols.
Bakeries are consolidating supplier relationships around mills offering integrated formulation support rather than commodity spot purchasing. Large-scale gluten-free bread operations in Germany and the Netherlands are locking multi-year supply agreements with technical service components. This bundling is most visible in North Rhine-Westphalia where industrial bakery clusters concentrate.
Rice Flour Market Segmentation
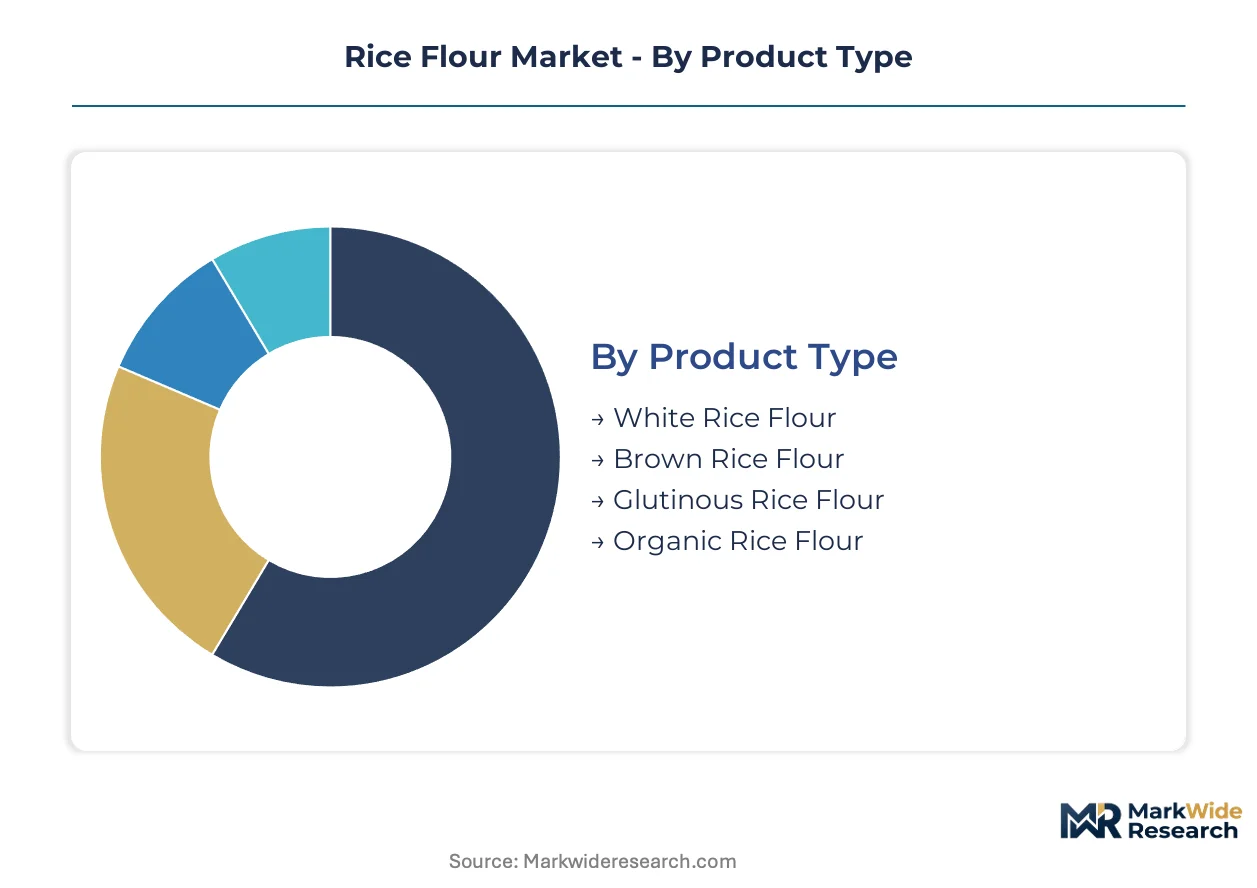
Rice flour segmentation reflects divergent regulatory pressures across food safety, organic certification, and gluten-free labeling regimes. Procurement patterns fragment as FDA enforcement, EU pesticide thresholds, and India's FSSAI fortification mandates reshape supplier qualification requirements for each product tier.
Product Type:
FDA allergen cross-contact controls and EU organic certification standards create divergent compliance burdens across milled rice flour grades, fragmenting supplier capabilities and pricing tiers.
- White Rice Flour:Milled from polished endosperm with amylose content between 20-30 percent in long-grain cultivars, delivering neutral flavor and extended shelf stability. Quick-service restaurant chains in the U.S. specify this grade for coating applications where batch-to-batch consistency determines oil absorption rates in frying operations.
- Organic Rice Flour:Processed from certified organic paddy with full traceability documentation meeting EU 2018/848 and USDA National Organic Program standards. EU baby food manufacturers in Germany and the Netherlands are consolidating procurement around mills offering batch-level arsenic testing and pesticide residue documentation below EFSA thresholds.
- Brown Rice Flour:Retains bran layer with higher fiber content and shorter shelf life, requiring modified atmosphere packaging for export distribution.
- Glutinous Rice Flour:Near-zero amylose waxy varieties from Mekong Delta cultivation zones, essential for frozen dough texture stability in Asian bakery applications.
Established volume favors white rice flour; emerging adoption favors organic rice flour.
End User:
Customer procurement sophistication varies sharply, with industrial bakeries demanding integrated formulation support while snack manufacturers prioritize spot-market flexibility.
- Gluten-Free Products:Dedicated production lines with HACCP-compliant segregation protocols prevent cross-contact with wheat, barley, and rye. Celiac diagnosis rates climbing across North American retail channels are compressing supplier qualification timelines to 14-18 months for BRCGS and SQF dual certification.
- Food Industry:Encompasses sauce and soup manufacturers substituting modified starches with native rice flour to meet clean-label transparency demands in Asian quick-service chains.
- Bakery:Industrial bread operations in Germany's North Rhine-Westphalia cluster are locking multi-year supply agreements with technical service components rather than commodity spot purchasing.
- Snack Manufacturers:Cost-sensitive coating applications where cassava flour substitution threatens rice flour positioning in certain flavor-neutral formulations.
Margin capture concentrates in gluten-free products; volume expansion runs through food industry procurement.
Application:
Functional performance requirements fragment milling specifications, with particle size distribution and gelatinization behavior determining grade suitability.
- Thickening Agent:Native starch functionality in Asian sauce and soup manufacturing occupies mature, price-sensitive volume pools where monsoon-driven Thai and Vietnamese white rice export price volatility compresses margin stability.
- Baking Ingredient:Air-classified sub-100-micron fractions without heat damage to starch granules enable frozen dough manufacturers in the U.S. Midwest to achieve precise texture control in gluten-free formulations.
- Coating Agent:Custom granulation capabilities for battered proteins in quick-service restaurant supply chains concentrate margin capture among specialized millers.
- Noodles:Specific amylose-amylopectin ratios determine cooking tolerance and texture retention in instant and fresh noodle segments.
Price pressure dominates thickening applications; technical differentiation defines baking ingredient procurement.
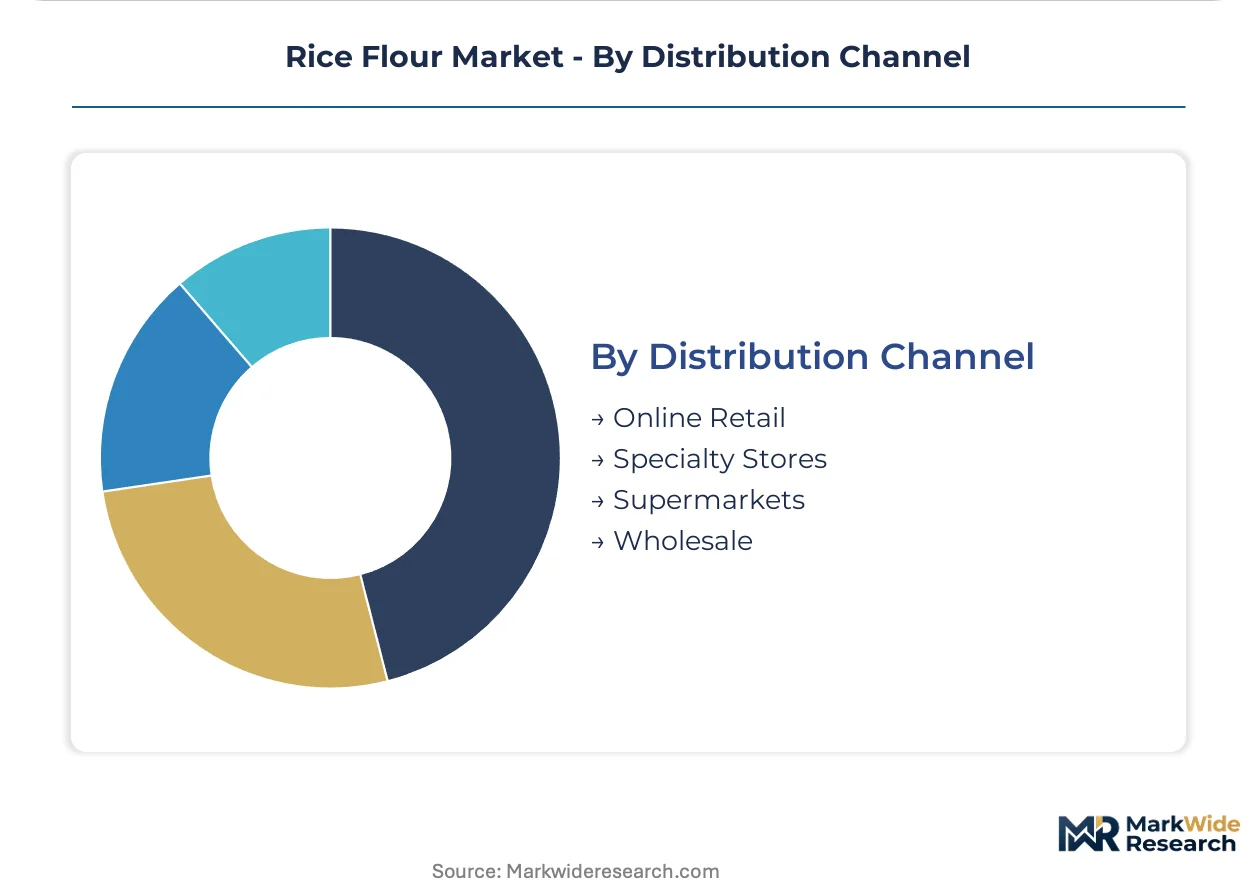
Distribution Channel:
Channel control determines margin retention and customer relationship depth, with direct-to-bakery models bypassing traditional ingredient distributor markups.
- Wholesale:Bulk procurement by industrial-scale gluten-free bakery operations with contracted drop-ship programs capturing formulation collaboration access and margin.
- Supermarkets:Retail-packaged rice flour for home bakers seeking gluten-free alternatives, with shelf placement competition intensifying in North American natural foods sectors.
- Specialty Stores:Stone-ground credentials and organic certification visibility drive premium positioning in U.S. natural foods channels.
- Online Retail:Direct-to-consumer access for artisan gluten-free bakeries and small-scale food manufacturers seeking technical documentation and smaller minimum order quantities.
Volume flows through wholesale; relationship depth and margin expansion favor online retail and direct contracted models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Vietnamese mills dominate export flows to European gluten-free manufacturers, while Indian processors serve domestic traditional applications and Middle Eastern buyers. Regulatory divergence across FDA, EFSA, and FSSAI jurisdictions fragments supplier qualification requirements.
United States
FDA Food Safety Modernization Act enforcement compresses supplier qualification timelines to 14-18 months for BRCGS and SQF dual certification. Celiac diagnosis rates climbing across retail channels pull procurement toward dedicated gluten-free production lines. Minneapolis-St. Paul industrial bakery clusters lock multi-year supply agreements with technical service components.
Germany
EFSA guidance on inorganic arsenic in rice-based infant foods mandates batch-level testing documentation from Asian suppliers. North Rhine-Westphalia industrial bakery clusters concentrate demand for air-classified sub-100-micron fractions. EU 2018/848 organic certification requirements reshape procurement criteria for export-oriented mills.
India
FSSAI fortification and labeling standards govern domestic distribution and export eligibility for rice flour produced under its jurisdiction. Traditional and industrial applications converge in Maharashtra and Gujarat processing hubs. Mumbai-Pune corridor mills serve both domestic quick-service restaurant chains and Middle Eastern buyers.
Thailand
Monsoon-driven white rice export price volatility compresses margin stability for toll millers lacking long-term grower contracts. Premium waxy rice varieties for frozen dough applications concentrate in Mekong Delta cultivation zones. Bangkok-based processors export to EU baby food manufacturers requiring pesticide residue documentation below EFSA thresholds.
Vietnam
Mekong Delta cultivation zones create single-region exposure for texture-critical glutinous rice flour formulations. Export-oriented mills achieve EU organic certification to capture premium positioning in gluten-free segments. Ho Chi Minh City processors serve Japanese and South Korean instant noodle manufacturers demanding specific amylose-amylopectin ratios.
Rice Flour Market Vendor Landscape
Player mix skews toward diversified ingredient conglomerates with modified starch portfolios and regional milling specialists with organic certification capabilities. Market structure fragments across three tiers: multinational food ingredient suppliers with integrated formulation support, mid-scale regional millers with custom granulation capabilities, and artisan stone-ground specialists with direct-to-consumer channel control. Dominant competitive moves include backward integration into paddy sourcing and contracted drop-ship programs bypassing traditional ingredient distributors.
Among North American ingredient suppliers, Ingredion Inc. and Archer Daniels Midland Company occupy positions anchoring supply relationships with large-scale bakery operations. Bob's Red Mill Natural Foods, Inc. exemplifies the artisan specialist archetype through stone-ground production credentials. Associated British Foods plc represents European market presence through its AB Mauri division.
| Leading Market Players |
|---|
| Ingredion Inc. |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Bob's Red Mill Natural Foods, Inc. |
| Bunge Limited |
| Cargill, Inc. |
| Thai Flour Industry Co., Ltd. |
| Wilmar International Limited |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month certification timelines for BRCGS and SQF dual standards compress working capital cycles and amplify pricing power for incumbent mills with existing food-grade credentials, while new processing investments face deferred revenue recognition until compliance gates clear.
Pricing Analysis
Stone-ground heritage milling commands 15-25 percent premiums over air-classified commodity grades, while precision fermentation-modified rice flour substrates for clean-label texturizers occupy emerging next-generation positioning. Three-tier pricing structure across premium organic, standard food-grade, and economy industrial levels stratifies by certification depth and arsenic testing documentation. Cost compression in economy coating applications intensifies because cassava flour substitution threats force margin concessions. Snack manufacturers in cost-sensitive battered protein applications exhibit highest price sensitivity; EU baby food manufacturers show lowest sensitivity due to regulatory compliance non-negotiability.
Supply Chain Analysis
Thailand and Vietnam anchor white rice and waxy variety cultivation for export-oriented milling, while India and Bangladesh feed domestic traditional applications and Middle Eastern re-export channels. Paddy sourcing draws from Mekong Delta monsoon-dependent cultivation zones, bran fraction handling, and EU-compliant organic certification tracking systems. Single-region exposure for glutinous rice varieties creates vulnerability to flood and drought patterns in Vietnam's Mekong Delta. Distribution runs through Bangkok and Ho Chi Minh City toll millers for European gluten-free manufacturers, with direct-to-bakery drop-ship programs bypassing traditional ingredient distributors for North American artisan accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice flour sits in early-cycle expansion as celiac diagnosis rates climb across North American retail channels and FDA allergen cross-contact enforcement tightens procurement standards for gluten-free bakery inputs.
For Market Incumbents: Fortify dedicated gluten-free line segregation capabilities and lock multi-year paddy supply contracts with Mekong Delta growers before monsoon volatility intensifies. Invest in EU 2018/848 organic certification and batch-level arsenic testing infrastructure to capture premium positioning in infant nutrition channels where EFSA thresholds are tightening. For New Entrants and Emerging Players: Lead with precision fermentation substrate partnerships for clean-label texturizer applications, targeting whitespace in enzymatic modification services for frozen dough manufacturers. Mexico's underpenetrated gluten-free tortilla segment in Mexico City and Guadalajara supermarket channels offers lowest competitive density for branded rice flour positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified grain conglomerates with underutilized organic-certified milling assets and stranded technical service capabilities. Five-to-ten-year viability hinges on backward integration into paddy sourcing and formulation support bundling. Monitor FDA enforcement intensity on allergen cross-contact controls as inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paddy Sourcing | Long-term grower contracts in Thailand and Vietnam insulate margin stability from monsoon-driven export price volatility. |
| EU Organic Certification Investment | EU 2018/848 compliance unlocks premium positioning in German and Dutch baby food segments with tightening pesticide thresholds. |
| Direct-to-Bakery Distribution Launch | Contracted drop-ship programs bypass ingredient distributor markups and capture formulation collaboration access with artisan gluten-free bakeries. |
| Precision Fermentation Substrate Partnership | Enzymatic modification of rice flour substrates enables clean-label texturizers that bypass synthetic additive disclosure requirements. |
| Air-Classification Technology Upgrade | Sub-100-micron fraction capability without heat damage attracts frozen dough manufacturers in the U.S. Midwest seeking precise texture control. |
Methodological Framework
A spread of perspectives from rice mill operations managers, gluten-free bakery procurement leads, EU baby food regulatory affairs directors, and Asian quick-service restaurant supply chain heads converged on the working assumptions. Primary interview insights combined with secondary validation from FDA FSMA guidance documents, EFSA pesticide residue threshold advisories, FSSAI fortification mandates, Thai and Vietnamese customs export data, and EU 2018/848 organic certification registries. Bottom-up volume modeling from end-use application demand and top-down triangulation against aggregate milling capacity produced convergent estimates.
Segmentation dimensions modeled include product type tier, end-user procurement sophistication, application functional requirements, and distribution channel control intensity across the projection horizon. CAGRs derived from weighted average of historical volume trajectories and adoption curve penetration assumptions for gluten-free and organic certified segments. Forecast inputs incorporated celiac diagnosis rate projections, FDA enforcement intensity scenarios, and EFSA arsenic threshold evolution patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA allergen cross-contact enforcement, stable EU organic certification requirements, or manageable Thai and Vietnamese export price volatility would require recalibration. Forecasts reflect documented assumptions about procurement consolidation velocity and substitution threat intensity from cassava and green banana flour alternatives. Recalibration cycles align with material shifts in FDA inspection frequency, EFSA guidance updates, and monsoon pattern disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Guar Complex Market
Grains
Global Oats Market
Grains
Global Grain Analysis Market
Grains
Global Flour Market
Grains
Africa Wheat Flour Market
Grains
Canada Pulses Market
Grains
Pulses Market
Grains
Global Precooked Corn Flour Market
Grains
Quinoa Flour Market
Grains
Oat Bran Market
Grains
Black Gram Market
Grains
Millets Market
Grains
Barley Grass Market
Grains
Masa Corn Products Market
Grains
Cornmeal Market
Grains
Organic Rice Market