
 Global Quinoa Market | 2026-2036
Global Quinoa Market Size, Share, and Industry Trends Forecast 2026-2036
Global Quinoa Market Outlook
EU Green Deal sustainability mandates are rebalancing the cost-of-entry calculus for South American exporters seeking European market access. Andean Naturals Inc. leverages its vertical integration across Bolivian growing regions to control quality from farm to processor. NorQuin anchors North American supply through its Saskatchewan cultivation network. Alter Eco differentiates via Fair Trade certification and regenerative agriculture partnerships.
Quinoa is a gluten-free pseudocereal seed from Chenopodium quinoa containing complete protein with all nine essential amino acids and saponin-coated hulls requiring mechanical abrasion or washing prior to consumption. Its primary commercial purpose centers on human nutrition as a rice alternative and as a functional ingredient in baked goods, breakfast cereals, and plant-based meat analogues. Organic quinoa commands premium shelf positioning in specialty stores and online retail channels where consumer willingness-to-pay for certified origin exceeds conventional grades. Quinoa flour competes with almond and coconut flours in gluten-free bakery applications. Quinoa snacks occupy the fastest-expanding slot within the product type matrix as portable protein formats gain traction in convenience-oriented distribution.
FDA oversees quinoa labeling under the Food Allergen Labeling and Consumer Protection Act while USDA administers organic certification standards governing cross-border trade. EFSA evaluates novel food applications for quinoa-derived ingredients entering European formulations. REACH compliance shapes saponin processing chemical disclosures for EU-bound shipments. Stakeholders must monitor evolving organic equivalency agreements between major producing nations and importing blocs to preempt supply chain disruptions.
Market Dynamics
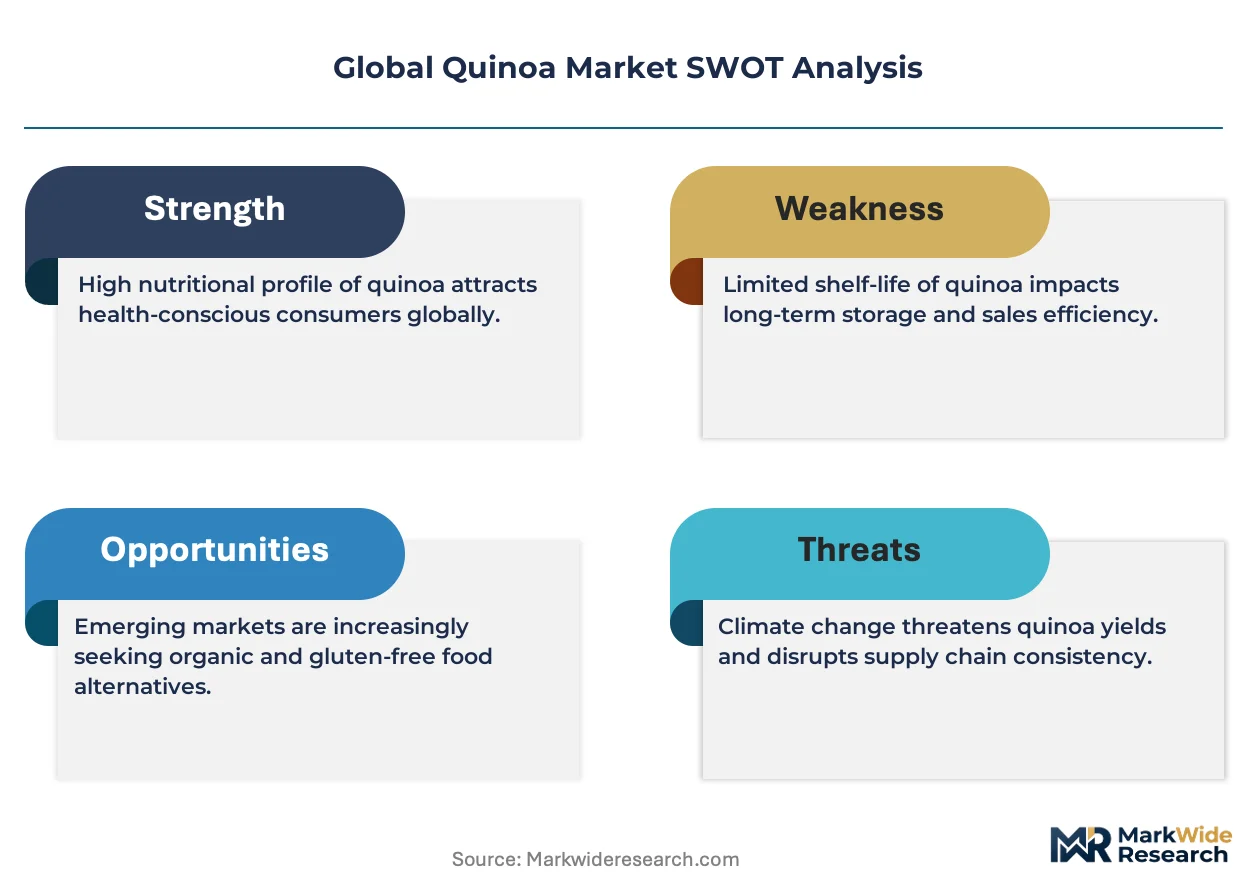
EU Green Deal sustainability mandates are compressing market access timelines for Andean exporters while simultaneously opening premium positioning for certified organic supply chains. This regulatory pressure is redrawing competitive boundaries between conventional and certified-grade producers.
Growth Catalysts
- EU Green Deal:Sustainability certification requirements for imported grains are accelerating procurement shifts toward traceable Bolivian and Peruvian supply chains with verified carbon footprints.
- Plant-based meat analogues:Food technologists are formulating quinoa protein isolates into next-generation meat alternatives, creating pull-through demand for high-protein grain varieties.
- Gluten-free bakery:Functional flour applications in celiac-safe baked goods are displacing rice flour in premium formulation pipelines across North American and European commercial bakeries.
Market Restraints
- Input cost volatility:Diesel and synthetic fertilizer prices in the Altiplano region directly compress farm-gate margins for smallholder cooperatives dependent on mechanized cultivation.
- Supply concentration risk:Over 80% of exportable surplus originates from Bolivia and Peru, creating single-source vulnerability to El Niño-driven yield shocks.
- Saponin processing limitation:Mechanical abrasion or aqueous washing remains mandatory for human-grade consumption, adding capital intensity that excludes underfinanced processors.
Strategic Opportunities
- Australia:Emerging cultivation in Tasmania and South Australia offers Southern Hemisphere counter-seasonality to Andean harvest cycles for year-round supply security.
- Regenerative agriculture partnerships:Carbon credit stacking on certified organic plots generates ancillary revenue streams for producers meeting EU Green Deal soil health benchmarks.
- Direct-to-consumer channels:Subscription-based specialty grain platforms are bypassing conventional bulk commodity brokers, capturing margin previously lost to intermediaries.
Industry Challenges
- Organic equivalency negotiation delays:Bilateral recognition agreements between major producing nations and importing blocs remain incomplete, forcing redundant certification audits.
- Climate adaptation capex:Irrigation infrastructure and drought-resistant varietal development require capital deployment beyond smallholder cooperative balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Quinoa Market |
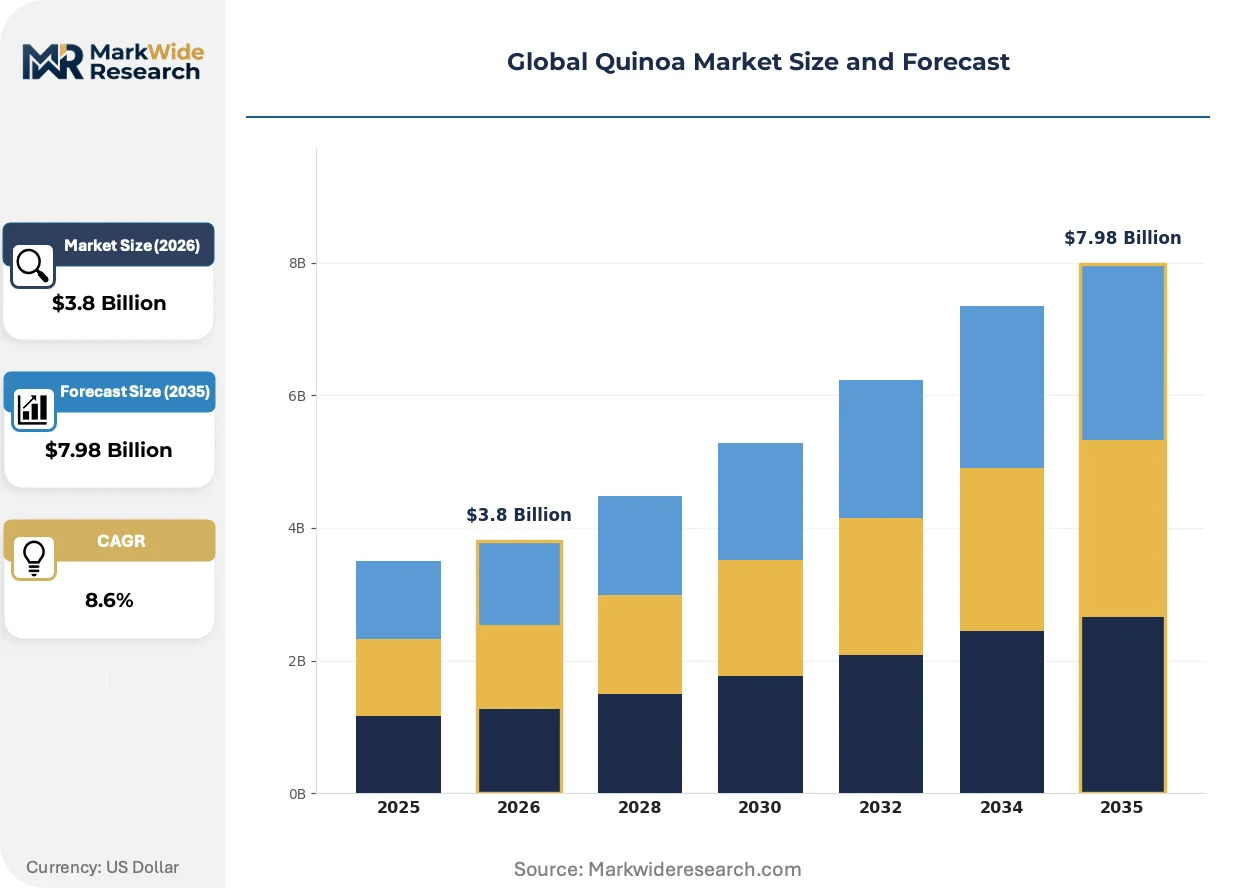
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Quinoa, Inorganic Quinoa, Quinoa Flour, Quinoa Snacks End Use Industry: Food & Beverage, Cosmetics, Nutraceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Bags, Bulk Containers, Cans, Bottles |
| Companies Covered | Andean Naturals Inc., Quinoa Foods Company, Northern Quinoa Production Corporation, The British Quinoa Company, Alter Eco, NorQuin, Keen One Quinoa, General Mills, Inc., Above Food Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Quinoa Market Strategic Shifts
Processing technology and certification architecture are converging to fragment the commodity-grade bulk market while concentrating value in identity-preserved supply chains. These shifts favor producers with traceability infrastructure and penalize undifferentiated exporters.
Mechanical saponin removal systems are expanding into mid-scale processing facilities previously limited to hand-washed or water-intensive methods. European organic certifiers and North American co-packers are adopting these systems to reduce water usage and labor dependency. The technology is expanding into smaller Bolivian and Peruvian cooperatives, compressing the quality gap between artisanal and industrial supply tiers.
REACH compliance requirements for chemical disclosures in saponin-derived processing byproducts are tightening documentation burdens on EU-bound shipments. EFSA novel food application pathways for quinoa protein isolates are extending time-to-market for ingredient innovators. German and French formulators are responding by front-loading regulatory submission investments before product development completion.
Specialty retailers are consolidating shelf space around single-origin certified supply, displacing blended anonymous grades in premium positioning. Direct sourcing contracts between European supermarkets and named Bolivian cooperatives are replacing spot-market procurement for organic SKUs. This pattern is most visible in German and Swiss retail channels where consumer willingness-to-pay for provenance verification exceeds conventional price elasticity thresholds.
Global Quinoa Market Segmentation
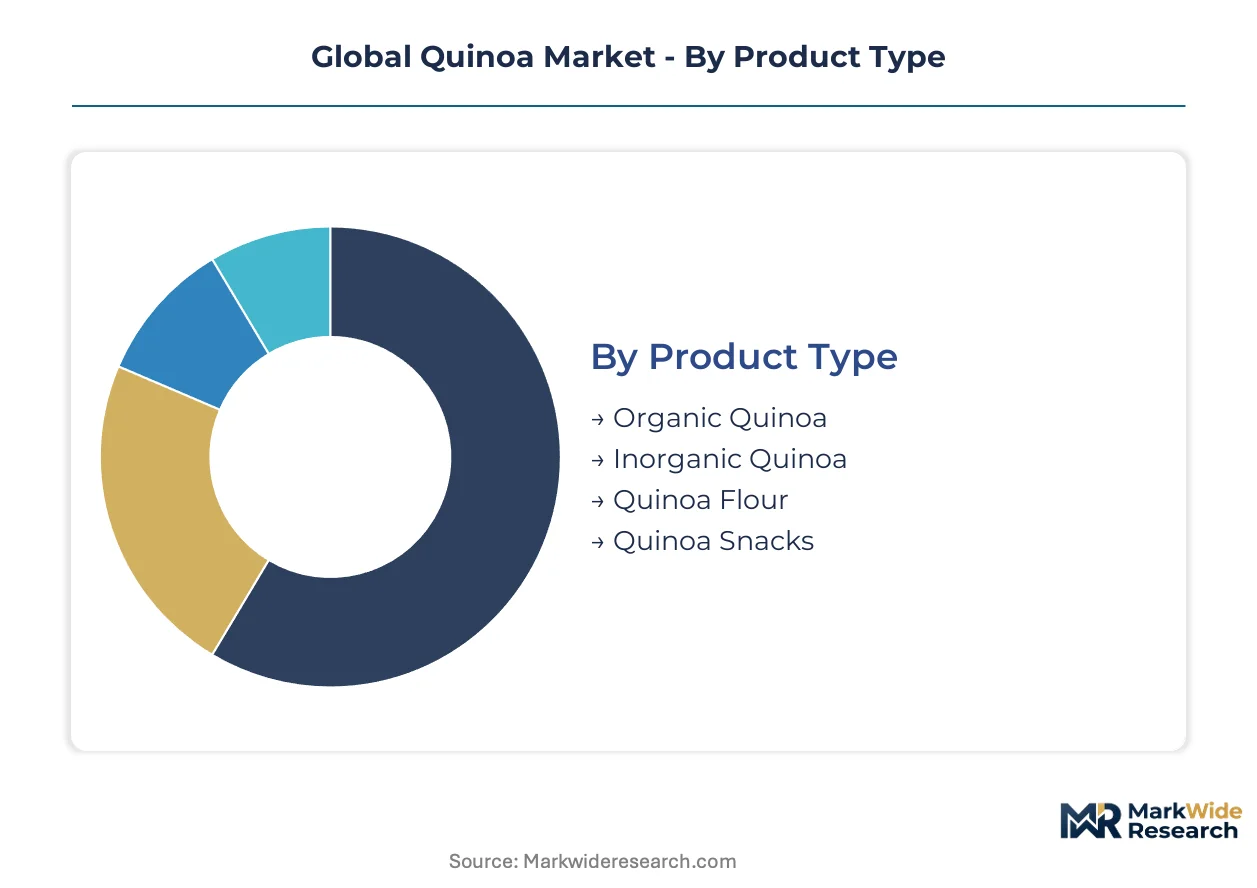
Quinoa market segmentation reveals how certification tiers, end-use applications, and channel strategies fragment what began as a commodity grain trade. Each dimension carries distinct margin structures and regulatory exposure that reshape competitive positioning across the value chain.
Product Type:
Supply concentration in Bolivian and Peruvian growing regions directly shapes product type availability, with certified organic output commanding preferential access to European and North American premium channels.
- Organic Quinoa:Cultivated without synthetic inputs under USDA or EU organic standards, this grade carries full traceability documentation from Altiplano cooperatives. German and Swiss retailers source almost exclusively from certified organic supply chains to meet EU Green Deal procurement mandates, with consumers absorbing 40-60% price premiums over conventional grades.
- Quinoa Snacks:Puffed, extruded, or clustered formats target convenience-oriented protein consumption in portable packaging. Australian and US coastal markets show strongest uptake as functional snacking displaces traditional energy bars, with formulators prioritizing crunch texture and clean-label ingredient decks.
- Inorganic Quinoa:Conventional cultivation using synthetic fertilizers dominates volume production in Peruvian coastal zones and emerging Australian acreage.
- Quinoa Flour:Milled from dehulled seeds for gluten-free bakery applications, competing against almond and coconut flour alternatives.
Today's leader: Organic Quinoa. Tomorrow's challenger: Quinoa Snacks.
End Use Industry:
Application diversity determines processing investment requirements, with food-grade saponin removal separating human consumption from lower-margin industrial uses.
- Food & Beverage:Rice alternatives, breakfast cereals, plant-based meat analogues, and gluten-free bakery formulations absorb the majority of processed quinoa volume. EFSA novel food approvals for quinoa protein isolates are unlocking ingredient applications in European meat alternative formulations.
- Nutraceuticals:Protein isolates, saponin extracts, and amino acid concentrates target sports nutrition and clinical dietary supplements. TGA registration pathways in Australia and FDA structure-function claims in the United States create divergent compliance costs for finished product marketers.
- Cosmetics:Saponin-rich fractions serve as natural surfactants in personal care formulations, though REACH compliance for chemical disclosures limits EU-bound ingredient shipments.
- Animal Feed:High-protein quinoa meal from processing byproducts supplies poultry and aquaculture operations, particularly in Peruvian domestic markets where human-grade sorting rejects redirect to feed channels.
Food & Beverage commands current volume. Nutraceuticals present the steepest expansion trajectory as protein isolation technology matures.
Distribution Channel:
Channel selection determines margin capture and brand control, with direct and digital formats eroding traditional wholesale intermediation.
- Specialty Stores:Independent natural food retailers and organic cooperatives stock identity-preserved single-origin SKUs with full provenance labeling. These outlets command highest consumer willingness-to-pay for Bolivian cooperative-sourced product in German, Swiss, and Australian urban centers.
- Online Retail:Subscription-based specialty grain platforms and Amazon marketplace sellers bypass conventional bulk commodity brokers. Direct-to-consumer fulfillment captures margin previously lost to intermediaries, with US and Australian consumers showing strongest adoption of recurring delivery models.
- Supermarkets:Mass retail placement requires volume scale and private-label compliance that favors larger Peruvian processors.
- Direct Sales:Food service contracts and industrial ingredient supply agreements link processors directly to bakery and meat alternative manufacturers.
Specialty Stores anchor premium positioning. Online Retail is gaining share fastest as logistics infrastructure penetrates secondary markets.
Packaging Type:
Packaging format reflects customer scale and shelf-life requirements, with sustainability credentials increasingly influencing procurement specifications.
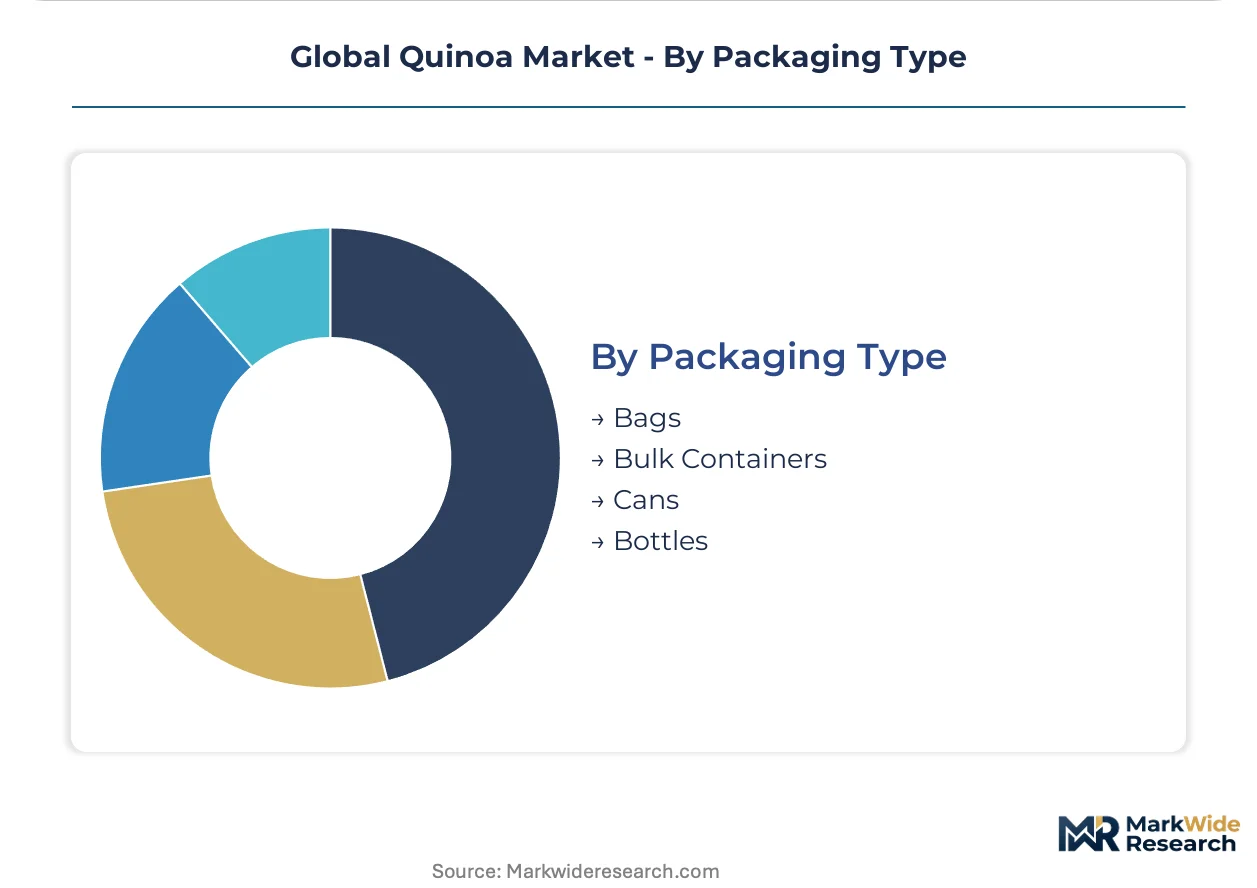
- Bags:Flexible retail pouches dominate consumer-facing SKUs in supermarkets and specialty channels, with compostable film options emerging in German and Swiss markets responding to EU Green Deal circular economy targets.
- Bulk Containers:Food service totes and industrial ingredient totes serve bakery and meat analogue manufacturers requiring volume scale with minimal handling. Australian and US West Coast processors favor this format for B2B supply efficiency.
- Cans:Shelf-stable retail formats for pre-cooked ready-to-eat quinoa target emergency preparedness and outdoor recreation segments.
- Bottles:Beverage applications for quinoa milk and fermented drinks occupy niche positioning in North American natural food channels.
Bags maintain retail dominance. Bulk Containers are climbing fastest as ingredient manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quinoa processing expertise clusters in the Bolivian Altiplano and Peruvian Andes, where indigenous cultivation knowledge anchors supply-side talent pools. German food technologists and Australian agronomists are transferring that knowledge to new growing regions.
United States
Plant-based meat analogue startups in California and Colorado are pulling quinoa protein isolates into formulation pipelines. FDA oversees novel ingredient approvals under the Food Allergen Labeling and Consumer Protection Act. The Pacific Northwest hosts emerging domestic cultivation trials in Oregon's Willamette Valley.
Germany
Retail chains in Berlin and Munich are consolidating shelf space around single-origin certified organic SKUs. EU Green Deal procurement mandates require verified carbon footprint documentation for Andean imports. Hamburg's port infrastructure handles the majority of European quinoa transshipment.
Australia
Tasmanian and South Australian growers are exploiting Southern Hemisphere counter-seasonality to Andean harvest cycles. TGA registration pathways create divergent compliance costs for nutraceutical applications. Melbourne's food processing corridor is scaling mechanical saponin removal capacity.
Bolivia
Altiplano cooperatives supply identity-preserved organic grades commanding German and Swiss retail premiums. The country's national agricultural regulator enforces organic equivalency protocols for EU-bound exports. Oruro and Potosí departments concentrate smallholder processing infrastructure.
Peru
Coastal zone mechanized farms dominate conventional-grade volume production for North American bulk contracts. EFSA novel food evaluations shape ingredient innovation timelines for European formulators. Arequipa's processing cluster integrates saponin extraction with cosmetic surfactant manufacturing.
Global Quinoa Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and channel strategies. The vendor base separates into three layers: vertically integrated Andean cooperatives with farm-to-processor control, North American cultivators with regional distribution networks, and multinational food corporations with private-label scale. Two strategic archetypes dominate competitive behavior—quality-differentiated players investing in organic certification infrastructure, and volume-driven operators expanding mechanized acreage. M&A activity concentrates on mid-scale processors with established export licenses, while strategic partnerships link Andean growers directly to European retail procurement desks.
Among vertically integrated Andean specialists, Andean Naturals Inc. and Alter Eco exemplify the certified organic archetype with traceable supply chain architecture. NorQuin anchors the North American cultivation tier through its Saskatchewan-based growing network. General Mills, Inc. occupies the diversified corporate position, leveraging existing distribution infrastructure to access mass retail channels without dedicated quinoa processing investment.
| Leading Market Players |
|---|
| Andean Naturals Inc. |
| Quinoa Foods Company |
| Northern Quinoa Production Corporation |
| The British Quinoa Company |
| Alter Eco |
| NorQuin |
| Keen One Quinoa |
| General Mills, Inc. |
| Above Food Inc. |
| Others |
Value Chain & Pricing Dynamics
German and Swiss organic retailers command the dominant buyer archetype in quinoa procurement, forcing a certification-grade pricing model where EU Green Deal compliance documentation determines access to premium shelf positioning. This buyer concentration compresses margins for undifferentiated Andean exporters while amplifying returns for traceable supply chains.
Pricing Analysis
Unbundled saponin processing services and bundled direct-to-retail contracts split the pricing landscape, with mechanical abrasion add-ons quoted separately from farm-gate grain purchases. Three-tier pricing structure across organic certified, conventional food-grade, and feed-grade levels tracks input costs from Altiplano cultivation through Hamburg transshipment. Pricing pressure stems from diesel and synthetic fertilizer volatility in Bolivian mechanized zones, squeezing smallholder cooperatives most acutely. Industrial ingredient buyers exhibit highest price sensitivity, while German specialty retailers absorb substantial premiums for single-origin documentation.
Supply Chain Analysis
Regional distribution centers in Hamburg, Rotterdam, and Melbourne anchor hub-and-spoke patterns for European and Asia-Pacific quinoa flows. Supply concentrates in Bolivia, Peru, and emerging Australian acreage, with over eighty percent of exportable surplus originating from Andean cooperatives. Raw material dependencies include diesel for Altiplano mechanized cultivation, synthetic fertilizers for Peruvian coastal zones, and water for saponin washing operations. Single-source vulnerability to El Niño-driven yield shocks constitutes the primary structural risk. Distribution runs through bulk commodity brokers for conventional grades, while certified organic supply chains bypass intermediaries via direct retail contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal sustainability mandates continuously tighten entry barriers and revalue certified supply chains. The EU Green Deal's carbon footprint verification requirements for imported grains serve as the principal demand accelerator, redirecting procurement toward traceable Andean producers.
For Market Incumbents: Cement control over organic certification infrastructure and backward integration into Altiplano cooperative networks to preempt margin compression from emerging Australian counter-seasonal supply. Incumbents must defend against new entrants exploiting Southern Hemisphere harvest windows by locking multi-year direct contracts with German and Swiss retail procurement desks. Priority investment in mechanical saponin removal capacity at cooperative level secures quality tier access. For New Entrants and Emerging Players: Australian nutraceutical formulators represent the most underserved buyer archetype, with TGA registration pathways creating compliance moats that deter established Andean suppliers. Tasmania and South Australian cultivation offers white-space entry with Southern Hemisphere counter-seasonality to Bolivian harvest cycles. Direct-to-consumer subscription platforms provide the most penetrable go-to-market angle, bypassing entrenched bulk commodity brokerage relationships. For Investors and Strategic Acquirers: European organic food conglomerates are the most active acquirer in this space, seeking mid-scale processors with established export licenses and EU organic equivalency documentation. Long-term viability hinges on climate adaptation infrastructure deployment and regenerative agriculture partnership scalability. Watch for El Niño intensity signals as the critical inflection indicator for supply-side disruption and pricing volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Partnership | Carbon credit stacking under EU Green Deal soil health benchmarks generates ancillary revenue for certified Bolivian cooperatives. |
| Mechanical Saponin Removal Scale-Up | Melbourne processing corridor investments reduce water dependency and labor intensity for Australian cultivation expansion. |
| Direct-to-Consumer Channel Launch | Subscription platforms capture margin previously lost to bulk commodity brokers in US and Australian urban markets. |
| Organic Equivalency Certification Investment | Bilateral recognition agreements between Andean regulators and EU authorities preempt redundant audit burdens. |
| Southern Hemisphere Cultivation Expansion | Tasmanian and South Australian acreage exploits counter-seasonality to Andean harvest cycles for year-round supply security. |
Study Parameters
Direct dialogue with Altiplano cooperative managers, German retail procurement directors, Australian agronomists, and Peruvian processing facility operators grounded this analysis in operational reality. Primary fieldwork combined with secondary validation against EU organic certification databases, EFSA novel food submission records, USDA organic equivalency agreements, and Hamburg port customs transshipment data. Bottom-up cultivation acreage estimates and top-down retail channel revenue analysis were triangulated to constrain variance.
Segment-level value outputs across the projection horizon reflect modeled interactions between certification tier penetration, end-use application mix, and channel strategy evolution. The analytical framework incorporated product type, end-use industry, distribution channel, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from supply-side capacity expansion trajectories and demand-pull estimates from plant-based meat analogue formulation pipelines.
Underlying measurement precision varies by segment; organic certified grades carry tighter precision than conventional volumes due to traceability documentation density. Forecasts reflect documented assumptions regarding EU Green Deal implementation timelines and El Niño frequency patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Dryers Market
Grains
Grain-Based Flours Market
Grains
Brazil Maize Market
Grains
Europe Wheat Protein Market
Grains
Oat Bran Market
Grains
South American Maize Market
Grains
Corn Market
Grains
Global Grain Analysis Market
Grains
Tunisia Grain Market
Grains
Grain Silos Market
Grains
Wheat Fiber Market
Grains
Low Fat Rice Market
Grains
Whole-Wheat Flour Market
Grains
Green Banana Flour Market
Grains
Triticale Market
Grains
Millet Flour Market