
 China Maize Market | 2026-2036
China Maize Market Size, Share, and Industry Trends Forecast 2026-2036
China Maize Market Outlook
The capital-intensity divergence between multinational traders and domestic processors is collapsing as local firms build captive port and storage infrastructure. COFCO Corporation leverages state-backed grain reserve mandates to anchor procurement networks across Heilongjiang and Jilin. Cargill sustains competitive positioning through specialized deep-water terminal operations at Dalian and Guangzhou. Archer Daniels Midland differentiates via integrated starch and sweetener complexes that convert raw maize into higher-margin food ingredients.
Maize, Zea mays L., is a cereal grain containing approximately 72% starch, 10% protein, and 4% oil by dry weight, with kernel hardness varying by endosperm composition from flint to dent types; it serves as the primary carbohydrate feedstock for livestock nutrition, bioethanol fermentation, and industrial starch extraction. Yellow maize dominates procurement volumes for animal feed and ethanol channels due to higher energy density and established grading standards, while sweet maize occupies premium food-grade segments with tighter moisture and sugar specifications. Starch manufacturing draws the most margin-sensitive sourcing, as Grade A specifications command price premiums from pharmaceutical and textile buyers.
China's Ministry of Agriculture and Rural Affairs sets national grain reserve targets and import quota allocations that directly shape domestic price floors and market access for foreign traders. The National Development and Reform Commission coordinates ethanol blending mandates with provincial energy authorities, creating demand pull for non-food maize streams. GB standards for mycotoxin limits and moisture content enforced by SAMR determine which quality grades qualify for food versus feed versus industrial channels. Stakeholders must monitor how provincial carbon intensity benchmarks for processing facilities reshape location decisions for new crush and fermentation capacity.
Market Dynamics
China's dual carbon goals from the MEE are compressing margins for ethanol distilleries while livestock herd expansion in Shandong and Hebei pulls feed-grade maize volumes northward, restructuring procurement geography around coastal processing clusters.
Growth Catalysts
- Livestock herd scaling:Pork and poultry operations in Shandong Province are expanding compound feed rations, pulling maize flows from northeast granaries toward coastal crush facilities.
- Ethanol blending mandates:The National Development and Reform Commission coordinates provincial E10 programs, creating dedicated demand streams for non-food maize grades.
- Coastal infrastructure buildout:Deep-water terminals at Dalian and Yantai are shortening import-to-processor transit times for foreign-origin shipments.
Market Restraints
- Input cost volatility:Natural gas and coal prices swing fermentation economics for starch and ethanol plants in Jilin and Liaoning.
- Supply concentration risk:Heilongjiang and Jilin provinces generate over half of domestic output, exposing processors to regional weather shocks.
- Regulatory friction:SAMR-enforced GB standards for mycotoxin limits disqualify substantial import volumes from food-grade channels.
Strategic Opportunities
- Underpenetrated western corridors:Sichuan and Chongqing feed mills remain underserved by efficient northeast grain logistics, creating arbitrage potential for rail-linked distributors.
- High-purity starch demand:Pharmaceutical and textile buyers in Jiangsu are paying premiums for Grade A specifications with tighter protein and ash tolerances.
- Carbon intensity benchmarking:Provincial MEE mandates for processing facility emissions are accelerating capital deployment toward combined heat and power systems.
Industry Challenges
- Capex intensity for decarbonization:Fermentation plants face retrofit costs for biogas capture and wastewater treatment to meet tightening MEE discharge standards.
- Certification timeline compression:GB standard updates for genetically modified traceability are forcing processors to rebuild documentation systems ahead of enforcement windows.
- Integration complexity:Legacy grain reserve management software from provincial state granaries resists real-time linkage with private processor ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Maize Market |
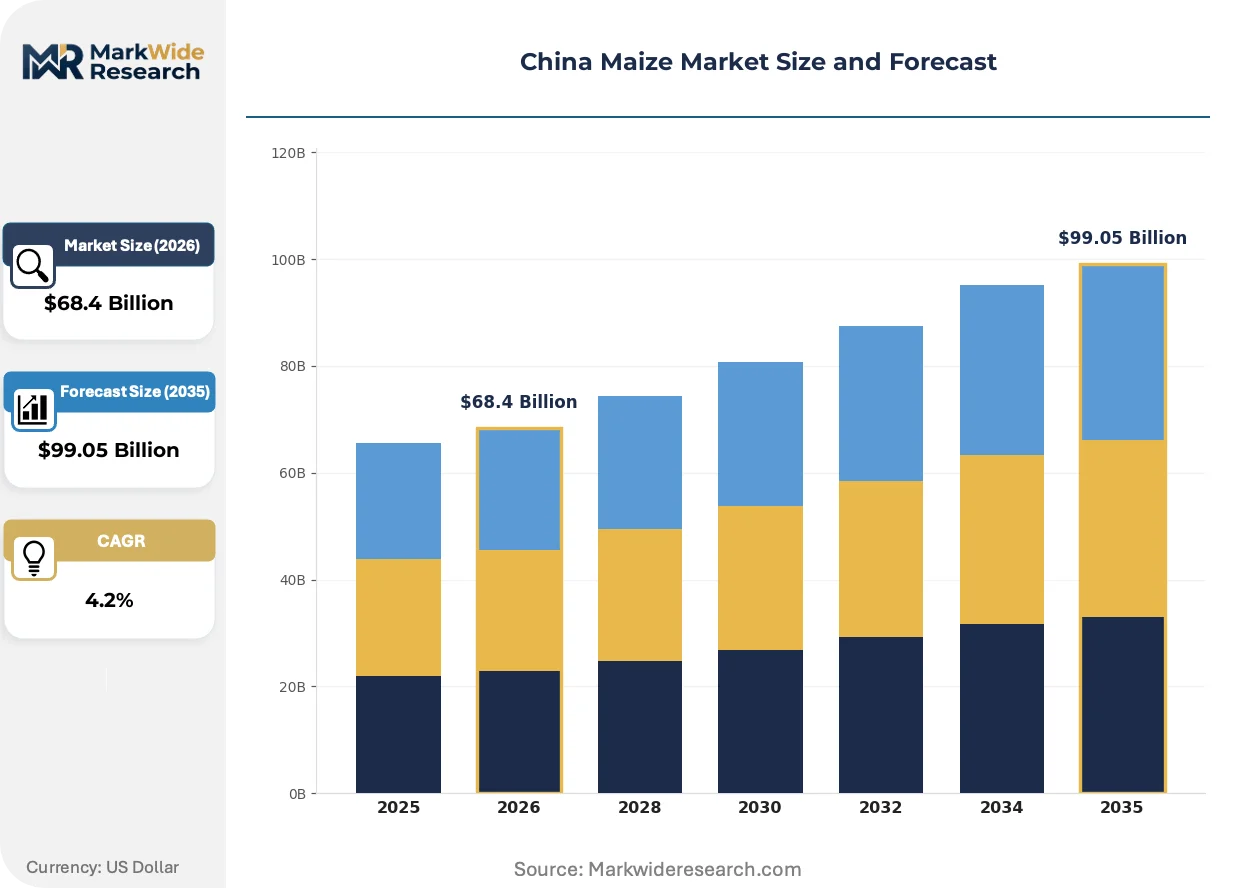
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $99.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Maize, White Maize, Sweet Maize, Flint Maize End Use: Animal Feed, Food Products, Ethanol Production, Starch Manufacturing Distribution Channel: Online Retail, Wholesalers, Supermarkets, Direct Sales Quality Grade: Grade A, Grade B, Grade C, Food Grade |
| Companies Covered | Archer Daniels Midland, Cargill, Bunge, Shandong Zhongbo Food Co., Ltd., Chaohu Meiwei Food Co., Ltd., Fujian Uniland Foods Co., Ltd., Heilongjiang Golden Valley Agricultural Science and Technology Development Co., Ltd., COFCO Corporation, China Agri-Industries Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Maize Market Strategic Shifts
Processing technology and regulatory enforcement are converging to compress legacy operational models while opening margin pools for quality-differentiated supply chains.
Enzymatic wet-milling systems with membrane filtration are displacing conventional acid-steep processes in starch extraction. Shandong-based processors are retrofitting existing lines to capture higher yields from high-moisture harvests. The technology is displacing capital-intensive dryer investments by enabling direct processing of freshly harvested kernels.
MEE carbon intensity benchmarks for industrial fermentation facilities are tightening discharge permits for existing ethanol plants. Distilleries in Heilongjiang are consolidating onto combined heat and power systems to maintain operating licenses. The regulation is compressing marginal capacity in regions without access to biomass boiler feedstocks.
Direct contracting between feed mills and northeast grain cooperatives is shortening traditional state-granary intermediation. Large swine operations in Henan are negotiating volume commitments with Jilin farm clusters for identity-preserved shipments. The pattern concentrates procurement leverage with vertically integrated livestock groups while fragmenting spot market liquidity at Dalian futures delivery points.
China Maize Market Segmentation
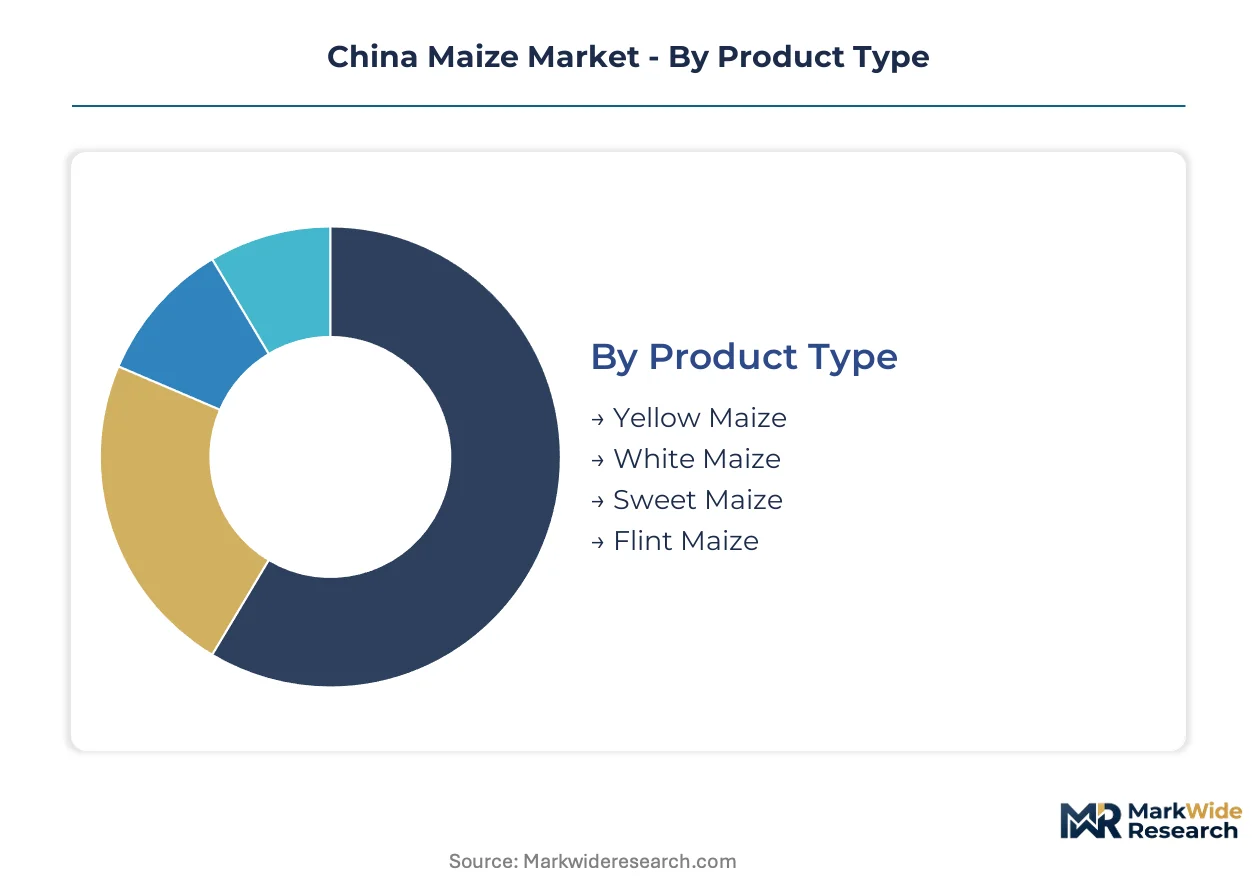
Segmentation in the China maize market exposes how quality grading and end-use specifications fragment procurement economics. GB standards enforced by SAMR create rigid channel boundaries that processors navigate through identity-preserved supply chains.
Product Type:
Yellow maize dominates domestic procurement volumes across Shandong and Hebei feed corridors, while white maize serves specialized food channels with tighter mycotoxin thresholds.
- Yellow Maize:Kernel composition runs approximately 72% starch and 4% oil by dry weight, delivering superior metabolizable energy for swine and poultry rations. Demand concentrates in Shandong Province where coastal crush facilities process northeast grain flows for compound feed manufacturers serving expanding livestock herds.
- Sweet Maize:Higher sugar content and moisture specifications distinguish this variety for fresh consumption and canning operations. Procurement in Jiangsu and Zhejiang targets premium food-grade segments with price premiums tied to harvest timing and cold-chain integrity.
- White Maize:Preferred for specialty food applications including traditional milling and snack production, with tighter aflatoxin limits than yellow varieties.
- Flint Maize:Hard endosperm structure suits alkaline cooking processes for tortilla and masa production, serving regional ethnic food processors.
Yellow maize commands the established base. The steepest expansion runs through sweet maize as premium fresh consumption penetrates tier-one urban markets.
End Use:
Cost tier segmentation separates commodity feed applications from margin-intensive industrial fermentation and pharmaceutical starch channels.
- Animal Feed:Compound feed manufacturers in Henan and Shandong blend maize with soybean meal at ratios calibrated to swine growth stages. The National Development and Reform Commission's ethanol mandates compete for non-food grades, tightening supply for feed processors during harvest shortfalls.
- Starch Manufacturing:Wet-milling operations in Jilin and Liaoning extract high-purity starch for textile sizing and pharmaceutical excipients. Grade A specifications with protein below 0.35% and ash under 0.15% command substantial premiums from Jiangsu textile buyers.
- Ethanol Production:Fermentation distilleries in Heilongjiang face MEE carbon intensity benchmarks that favor facilities with biomass boiler integration.
- Food Products:Direct human consumption spans fresh, canned, and milled applications with SAMR-enforced GB standards for moisture and fungal metabolites.
Animal feed anchors volume throughput. The fastest value expansion sits with starch manufacturing as pharmaceutical purity requirements tighten.
Distribution Channel:
Volume concentration favors direct procurement as large livestock groups bypass traditional state-granary intermediation.
- Direct Sales:Identity-preserved contracting between Jilin farm cooperatives and Henan swine operations eliminates Dalian futures delivery friction. Large integrators negotiate volume commitments with specified moisture and mycotoxin ceilings.
- Wholesalers:Regional distributors in Heilongjiang maintain storage infrastructure for spot market liquidity, bridging harvest timing gaps for smaller feed mills.
- Supermarkets:Packaged sweet maize and specialty varieties reach urban consumers through modern retail with traceability labeling requirements.
- Online Retail:E-commerce platforms serve niche organic and non-GMO segments with premium positioning for health-conscious buyers in tier-one cities.
Direct sales capture the volume core. Online retail posts the steepest expansion trajectory as traceability premiums attract digitally native consumers.
Quality Grade:
Margin sensitivity stratifies sharply across pharmaceutical-grade purity versus commodity feed tolerances.
- Grade A:Maximum 14% moisture, 0.35% protein, and 0.15% ash content qualifies for pharmaceutical and textile starch extraction. Jiangsu buyers pay substantial premiums for certificates of analysis documenting batch-level compliance.
- Food Grade:SAMR-enforced GB 2715 standards for aflatoxin B1 below 20 micrograms per kilogram and fumonisin limits govern direct human consumption channels.
- Grade B:Intermediate specifications serve industrial ethanol fermentation with relaxed protein tolerances.
- Grade C:Minimum thresholds for bulk feed applications where energy density outweighs purity metrics.
Grade A holds the premium tier. Grade B is expanding most quickly as ethanol blend rates rise under provincial E10 programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed processors in Shandong Province exhibit the sharpest price elasticity, while pharmaceutical starch buyers in Jiangsu show inelastic demand for Grade A specifications. This divergence concentrates procurement leverage in coastal corridors and fragments spot liquidity in interior provinces.
Shandong Province
Compound feed manufacturers serving expanding swine and poultry herds drive procurement volumes toward coastal crush facilities. The National Development and Reform Commission coordinates ethanol blending mandates that compete for non-food grades during harvest shortfalls. Yantai and Qingdao processing clusters access both northeast grain flows and deep-water export terminals.
Heilongjiang Province
Northeast grain cooperatives supply identity-preserved shipments to large integrators in Henan under direct contracting arrangements. MEE carbon intensity benchmarks force ethanol distilleries toward combined heat and power retrofits. Harbin and Qiqihar anchor starch extraction capacity facing input cost volatility from natural gas price swings.
Jiangsu Province
Textile and pharmaceutical buyers pay substantial premiums for Grade A starch with protein below 0.35% and ash under 0.15%. SAMR-enforced GB standards for mycotoxin limits shape which batches qualify for food-grade channels. Nanjing and Suzhou industrial zones concentrate wet-milling operations serving high-purity downstream demand.
Sichuan-Chongqing Corridor
Feed mills in this interior region remain underserved by efficient northeast grain logistics, creating arbitrage potential for rail-linked distributors. Provincial energy authorities implement carbon intensity benchmarks that reshape location decisions for new fermentation capacity. Chengdu and Chongqing urban clusters pull sweet maize volumes for premium fresh consumption markets.
Hebei Province
Pork operations in this northern province expand compound feed rations that pull maize flows from adjacent northeast granaries. Dual carbon goals from the MEE tighten emissions standards for processing facilities across the Beijing-Tianjin-Hebei corridor. Tangshan and Shijiazhuang host coastal infrastructure shortening transit times for foreign-origin shipments.
China Maize Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with state-backed grain reserve mandates creating procurement advantages for domestic incumbents. Multinational traders compete through specialized terminal operations and integrated processing complexes. Three archetypes dominate: state-linked integrators with reserve network access, global traders with deep-water terminal assets, and regional specialists in identity-preserved supply chains. Competitive moves center on captive port infrastructure buildout and backward integration into northeast farm cooperatives.
Within the state-linked integrator tier, COFCO Corporation anchors procurement networks across Heilongjiang and Jilin through grain reserve mandates. Among global trading houses, Cargill and Archer Daniels Midland occupy positions differentiated by terminal operations and integrated starch complexes respectively. Shandong Zhongbo Food Co., Ltd. exemplifies the regional specialist archetype focused on coastal processing corridors.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill |
| Bunge |
| Shandong Zhongbo Food Co., Ltd. |
| Chaohu Meiwei Food Co., Ltd. |
| Fujian Uniland Foods Co., Ltd. |
| Heilongjiang Golden Valley Agricultural Science and Technology Development Co., Ltd. |
| COFCO Corporation |
| China Agri-Industries Holdings |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of northeast-to-coastal transit inventory concentrates pricing power with Dalian futures delivery points and state granary intermediaries, compressing margins for processors caught between fixed procurement contracts and spot market volatility. This inventory banding directly shapes how Grade A premiums detach from feed-grade benchmarks across Shandong crush facilities.
Pricing Analysis
Extended service and logistics bundling drives lifetime value for large integrators negotiating identity-preserved shipments with Jilin farm cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade starch from ethanol fermentation feedstock and bulk animal feed rations. Cost compression in standard grades is intensifying because MEE carbon intensity benchmarks force distillery retrofits without corresponding price recovery mechanisms. Compound feed manufacturers in Henan exhibit the sharpest price sensitivity, while Jiangsu textile buyers show inelastic demand for Grade A certificates of analysis.
Supply Chain Analysis
Bohai Strait roll-on/roll-off ferry capacity underwrites year-round grain movement from Dalian to Yantai processing clusters. Heilongjiang and Jilin provinces generate over half of domestic output, with Ukrainian and Brazilian origins filling import quota allocations. The supply chain rests on natural gas price volatility for Jilin starch plants and mycotoxin disqualification risk at SAMR inspection points. Distribution runs through direct contracting between northeast cooperatives and coastal livestock integrators, fragmenting traditional state-granary spot liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where grain reserve mandates create regulatory entrenchment that foreign traders cannot replicate without decades of infrastructure buildout.
For Market Incumbents: Secure captive port terminal access at Dalian and Yantai before multinational traders expand deep-water capacity. Deepen backward integration into Heilongjiang farm cooperatives to lock identity-preserved supply streams ahead of direct contracting proliferation. The threat of enzymatic wet-milling yield advantages demands R&D investment in membrane filtration retrofits.
For New Entrants and Emerging Players: Differentiate on carbon-intensity certification for ethanol distilleries serving provincial E10 programs with biomass boiler integration. White-space targets include Sichuan-Chongqing rail corridors underserved by efficient northeast logistics and premium sweet maize cold-chain distribution to tier-one urban markets. A go-to-market angle of traceability-as-a-service for pharmaceutical starch buyers bypasses incumbent granary relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MEE discharge standards and GB certification timelines compress marginal capacity toward integrated leaders. Target regional specialists with established northeast cooperative networks and coastal processing assets. The signal to watch is provincial carbon intensity benchmark enforcement accelerating distillery license non-renewals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Northeast Farm Cooperatives | Captures identity-preserved supply streams ahead of direct contracting fragmentation. |
| Combined Heat and Power Retrofit Deployment | Preserves ethanol distillery operating licenses under tightening MEE discharge standards. |
| Membrane Filtration Technology Adoption | Enables Grade A starch yield advantages without capital-intensive dryer investments. |
| Deep-Water Terminal Capacity Expansion | Shortens import-to-processor transit times for foreign-origin shipments at Dalian. |
| Carbon Intensity Certification Program | Unlocks provincial E10 program access for ethanol fermentation capacity. |
Study Parameters
Initial hypotheses were tested against primary input from grain reserve procurement officers, ethanol distillery operations managers, compound feed formulation specialists, and starch plant technical directors and refined through secondary validation. Sources included SAMR GB standard filings, NDRC ethanol mandate coordination documents, Dalian Commodity Exchange delivery data, and provincial MEE discharge permit records. Bottom-up volume modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Variance decomposition across product type, end use, quality grade, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from historical trade flow patterns and policy trajectory analysis incorporated livestock herd scaling forecasts and ethanol blend rate assumptions. Industry-specific inputs included northeast granary inventory reporting and coastal processing capacity utilization surveys.
Material uncertainties — harvest shortfall severity, natural gas price spikes, GB standard update timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about provincial E10 implementation pace and MEE enforcement intensity. Practitioners should keep alternative scenarios live as dual carbon goal milestone deadlines and import quota allocation revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Green Banana Flour Market
Grains
00 Flour Market
Grains
Bangladesh Rice Market
Grains
Global Oats Market
Grains
Fortified Rice Market
Grains
Africa Wheat Protein Market
Grains
Wheat Fiber Market
Grains
Grain Augers Market
Grains
Argentina Grains Market
Grains
Cornmeal Market
Grains
GMO Corn Market
Grains
Lentil Market
Grains
Grain Bins Market
Grains
Low Fat Rice Market
Grains
Paraguay Grains Market
Grains
Soybean Market